
 Colombia Appliances and Electronics Market | 2026-2036
Colombia Appliances and Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Appliances and Electronics Market Insights
Colombia's energy efficiency labeling regulations under the Ministry of Mines and Energy is rebalancing procurement criteria across retail and hospitality channels. LG Electronics leverages its inverter compressor technology to sustain premium positioning in refrigeration. Samsung Electronics anchors its growth through integrated smart home ecosystems that connect appliances with mobile platforms. Industrias HACEB competes aggressively on domestic manufacturing scale and localized service networks.
Appliances and electronics encompass electromechanical devices and semiconductor-based equipment designed for household, commercial, and industrial tasks, typically operating on alternating current between 110-120V at 60Hz in Colombian territory, with energy consumption ratings measured under ISO 15502 protocols for refrigeration units. The product type dimension shows refrigerators commanding the largest installed base while air conditioners represent the fastest structural expansion due to Andean temperature variability and urban heat island effects. Technology segmentation reveals smart appliances capturing disproportionate margin pools through software subscription attach rates, though energy efficient variants still dominate absolute unit sales volumes.
Colombia's national standards body ICONTEC enforces electrical safety protocols aligned with IEC 60335 for household appliances, while the Superintendency of Industry and Commerce monitors anticompetitive practices in distribution channels. The Ministry of Environment and Sustainable Development implements extended producer responsibility frameworks that obligate manufacturers to finance end-of-life collection infrastructure. Stakeholders must monitor how forthcoming carbon border adjustments in neighboring trade blocs reshape component sourcing economics and local assembly competitiveness.
Market Dynamics
Colombia's Ministry of Mines and Energy efficiency labeling mandates are forcing manufacturers to redesign product portfolios around inverter compressor architectures and connected monitoring systems, compressing development cycles while raising compliance thresholds for market entry.
Growth Catalysts
- Andean Urban Heat Islands:Temperature variability across Bogotá and Medellín corridors is accelerating replacement cycles for climate-controlled refrigeration and cooling systems in dense metropolitan zones.
- ICONTEC Electrical Safety Alignment:Harmonization with IEC 60335 protocols is reducing technical barriers for regional manufacturers seeking cross-border certification reciprocity.
- Extended Producer Responsibility Mandates:The Ministry of Environment and Sustainable Development's end-of-life collection financing rules is creating aftermarket service revenue pools for domestic assemblers.
Market Restraints
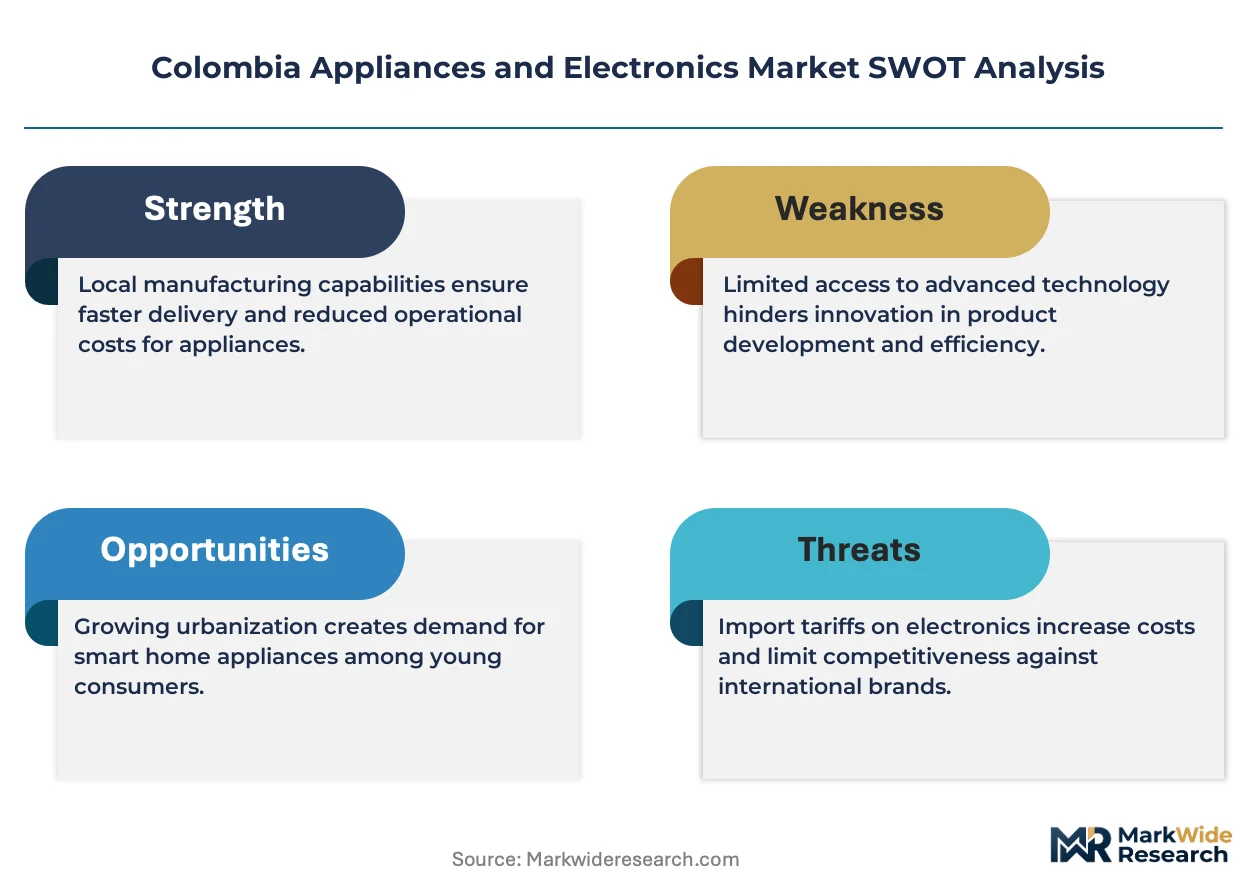
- Semiconductor Input Volatility:Dependence on imported microcontroller units and power management chips exposes manufacturers to Asian foundry capacity constraints and freight cost swings.
- Andean Logistics Bottlenecks:Mountainous terrain and limited Pacific port infrastructure concentrates inbound component flows through Cartagena and Buenaventura, amplifying lead time risk.
- Dual Voltage Legacy Infrastructure:Persistent 110V/220V split across Colombian territories forces redundant SKU proliferation and inventory fragmentation.
Strategic Opportunities
- Caribbean Coastal Electrification:Barranquilla and Santa Marta corridor households remain underpenetrated for smart appliance adoption relative to Andean metros, offering first-mover positioning.
- Software Subscription Attach Models:Predictive maintenance algorithms and energy optimization dashboards bundled with hardware sales is opening recurring revenue streams.
- Carbon Border Adjustment Preparation:Anticipated trade bloc emissions accounting rules is incentivizing local assembly investments to preserve export competitiveness.
Industry Challenges
- ISO 15502 Testing Capacity Scarcity:Limited accredited laboratory infrastructure for refrigeration energy consumption verification is extending product launch timelines.
- Field Service Network Fragmentation:Sparse authorized technician coverage outside Bogotá-Medellín-Cali triangle is degrading warranty fulfillment and brand loyalty.
- Legacy System Integration Complexity:Smart home ecosystem interoperability with existing residential electrical panels requires costly retrofit consultations that stall purchase decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Appliances and Electronics Market |
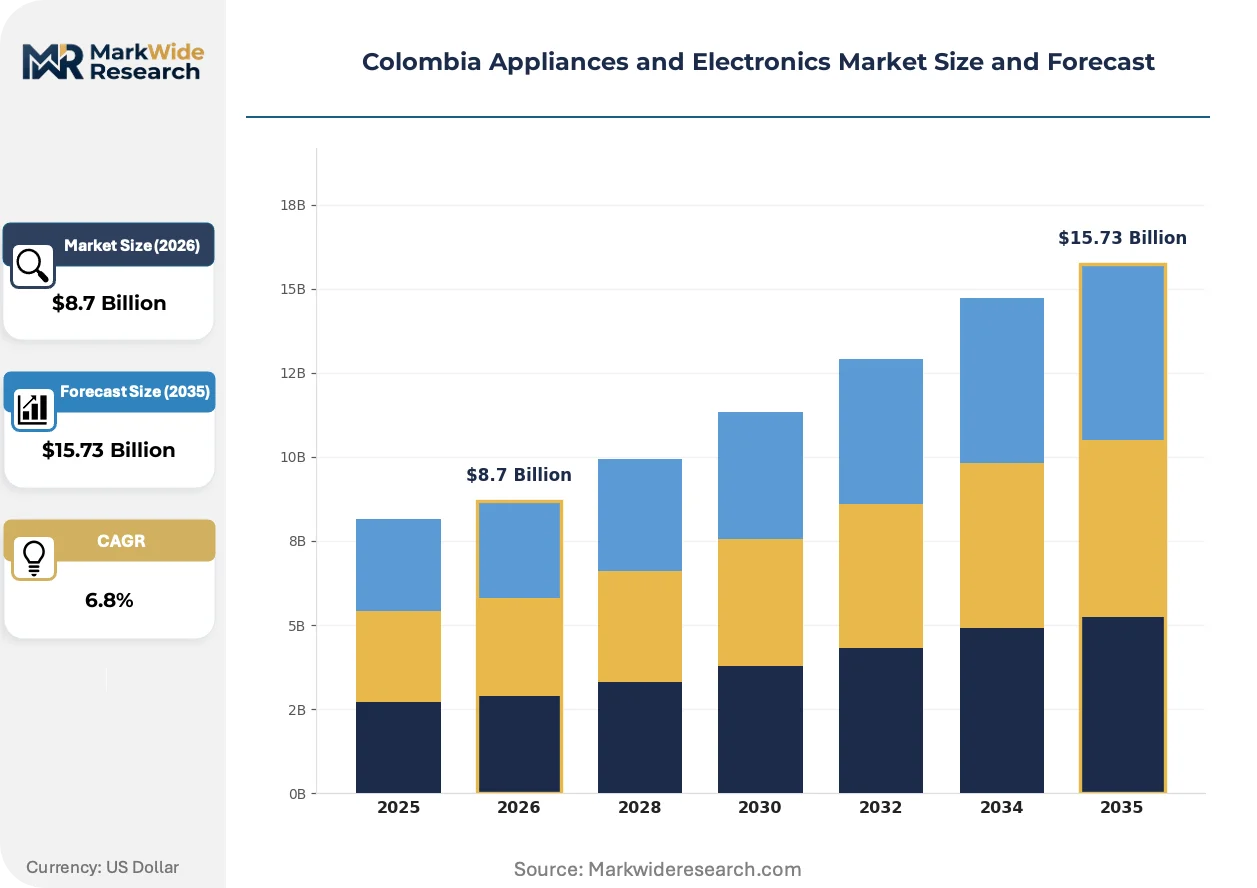
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Air Conditioners Technology: Smart Appliances, Energy Efficient, IoT Enabled, Traditional End User: Residential, Commercial, Retail, Hospitality Distribution Channel: Online Retail, Offline Retail, Wholesalers, Direct Sales |
| Companies Covered | Whirlpool Corporation, Electrolux AB, LG Electronics, Samsung Electronics, Panasonic Corporation, BSH Hausgeräte GmbH, Haier Electronics Group Co. Ltd, Arcelik AS, Industrias HACEB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Appliances and Electronics Market Trends and Innovations
Connected appliance architectures and predictive energy management systems are compressing traditional replacement cycles while redefining manufacturer-customer relationships beyond the point of sale.
Inverter-driven variable-speed compressor technology is electrifying residential cooling and refrigeration efficiency benchmarks. Middle-income households in Medellín and Cali are adopting these systems at replacement rates outpacing national averages by a significant margin. This electrification is compressing market share for fixed-speed legacy platforms and forcing price repositioning across standard-tier product lines.
The Ministry of Mines and Energy's mandatory comparative energy labeling regime is tightening disclosure requirements for standby power and annual consumption metrics. Domestic manufacturers must now submit verified test data to ICONTEC-accredited facilities before commercialization authorization. Refrigeration categories face the steepest compliance cost escalation, with redesign cycles compressing from thirty-six to eighteen months for mid-tier suppliers.
Direct-to-installer procurement channels are displacing traditional retail intermediation for commercial kitchen and hospitality equipment. Restaurant groups and hotel chains in Bogotá's Zona Rosa and Parque Lleras districts now negotiate fleet pricing through manufacturer-employed specification consultants. This channel shift concentrates buyer power among fewer decision-makers while raising service-level expectations for same-day technical response.
Colombia Appliances and Electronics Market Segmentation
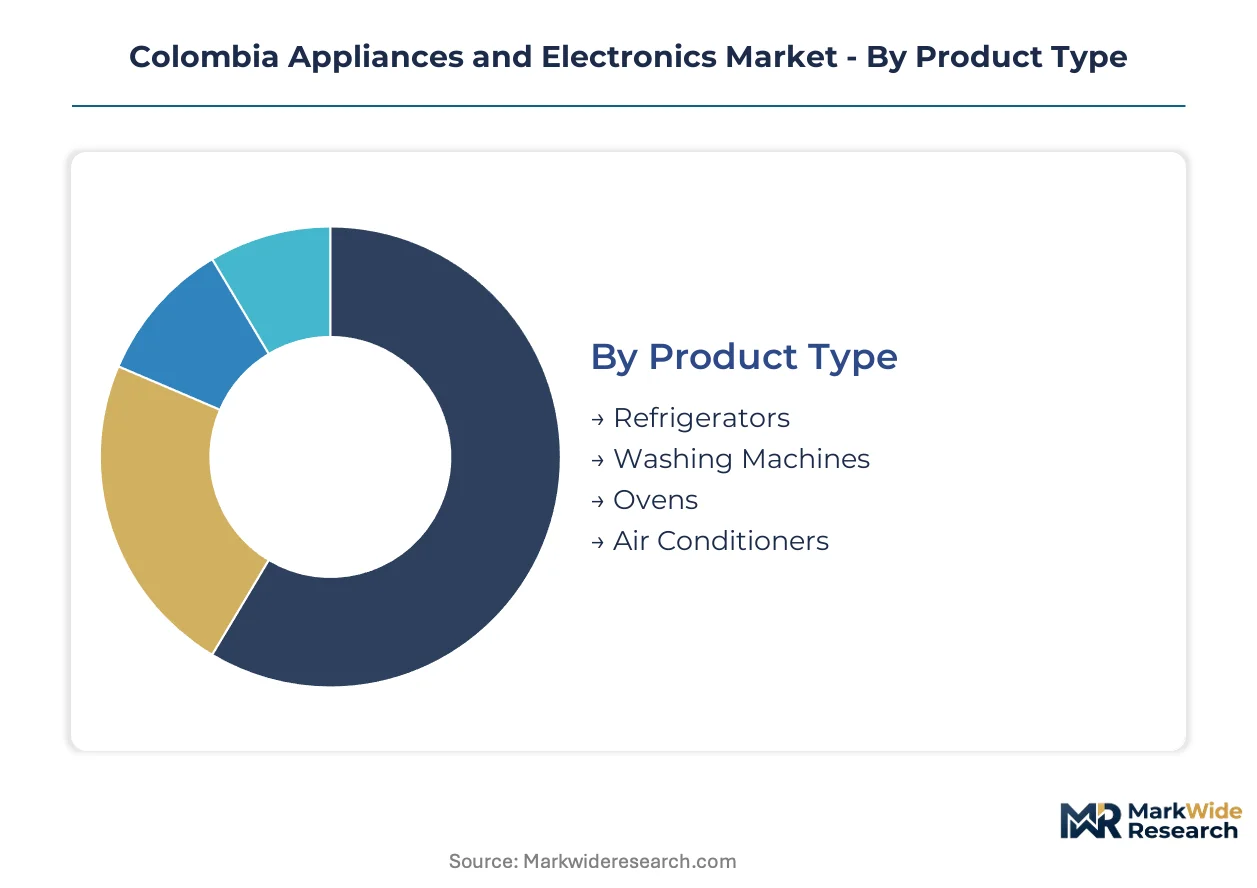
Segmentation in Colombia's appliances and electronics market reveals distinct upgrade cycles across product categories, with energy efficiency mandates and smart home integration reshaping replacement timelines. Understanding these divisions enables targeted positioning against Ministry of Mines and Energy compliance thresholds and regional income disparities.
Product Type:
Replacement cycles vary dramatically across appliance categories, with climate-driven demand in Andean corridors compressing refresh timelines for cooling equipment while durable goods extend lifespans through component upgrades.
- Refrigerators:Inverter compressor architectures now dominate new installations as households replace fixed-speed units to meet energy labeling requirements. Demand concentrates in Bogotá and Medellín metropolitan zones where electricity tariffs incentivize efficiency investments and extended producer responsibility rules mandate end-of-life collection logistics.
- Air Conditioners:Variable-speed heat pump systems address urban heat island effects in dense Andean corridors. Barranquilla and Santa Marta coastal households are accelerating adoption as electrification expands, though 110V infrastructure constraints limit product standardization.
- Washing Machines:Front-loading platforms with moisture-sensing cycles are displacing top-loading units in middle-income Cali households seeking water efficiency certifications.
- Ovens:Convection and induction technologies are penetrating commercial kitchen specifications in Bogotá's Zona Rosa hospitality cluster.
Refrigerators sit at the top of the volume ranking, with air conditioners climbing the fastest.
Technology:
Technology tiers in Colombia stratify around software attach rates and energy certification grades, with margin pools concentrating in connected platforms while regulatory compliance drives baseline specifications.
- Smart Appliances:WiFi-enabled refrigeration and climate systems bundle predictive maintenance algorithms with hardware sales. Direct-to-installer channels in Medellín's Parque Lleras district are negotiating fleet pricing for hospitality deployments that integrate with building management systems.
- Energy Efficient:Inverter-driven compressor platforms and ISO 15502-certified refrigeration units dominate procurement criteria under Ministry of Mines and Energy mandates. ICONTEC testing capacity scarcity is extending verification timelines for mid-tier suppliers redesigning portfolios.
- IoT Enabled:Sensor-integrated appliances with mobile platform connectivity are capturing premium positioning in Cali and Bogotá upper-middle segments.
- Traditional:Fixed-speed mechanical platforms persist in price-sensitive rural corridors outside the Andean triangle where smart home infrastructure remains underdeveloped.
Energy efficient variants command absolute unit leadership, while smart appliances are gaining share fastest through recurring software revenue models.
End User:
End user segmentation tracks channel concentration and service-level expectations, with commercial buyers consolidating procurement power while residential demand fragments across income tiers.
- Residential:Urban households in the Andean region drive replacement demand for inverter refrigeration and connected climate systems. Bogotá's dense apartment stock limits smart home retrofit feasibility, compressing adoption to new construction and major renovation cycles.
- Commercial:Restaurant groups and hotel chains negotiate specification consulting through manufacturer-employed technical advisors. Same-day service response requirements are raising barriers for distributors lacking field technician networks.
- Retail:Appliance showroom operators in Medellín and Cali are consolidating procurement to capture volume pricing on energy-efficient inventory.
- Hospitality:Boutique hotel developments in Cartagena's historic center are specifying integrated smart room systems with centralized energy monitoring.
Residential demand anchors volume scale, with hospitality posting the steepest expansion trajectory as coastal tourism infrastructure electrifies.
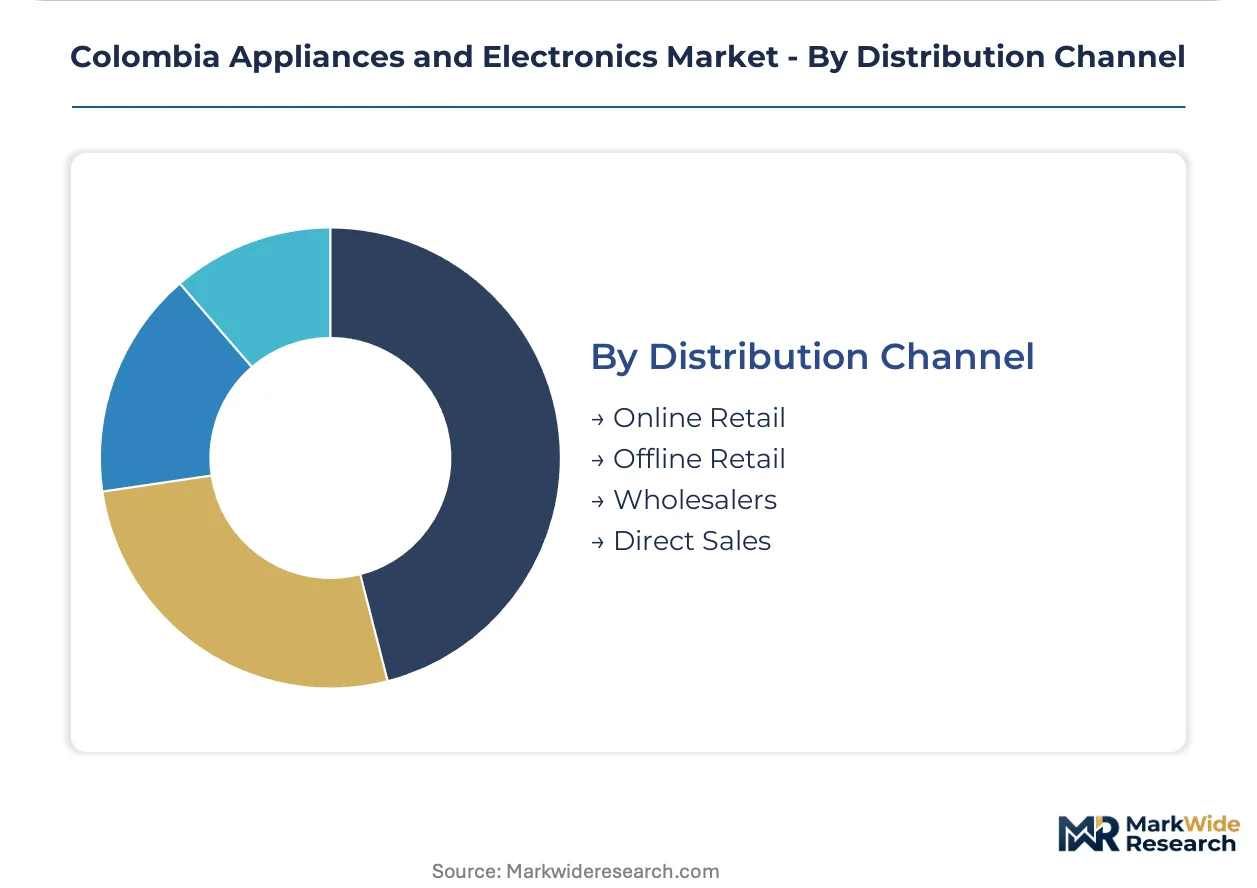
Distribution Channel:
Channel structure in Colombia reflects logistics constraints and technical service requirements, with direct relationships displacing intermediaries where installation complexity demands specialized expertise.
- Online Retail:E-commerce platforms are capturing standard appliance transactions in Bogotá and Medellín where delivery infrastructure supports next-day fulfillment. Extended warranty attachments and installation scheduling integrations are raising average transaction values.
- Offline Retail:Branded showroom networks concentrate in Andean metropolitan corridors with authorized service centers co-located to address warranty fulfillment expectations.
- Wholesalers:Regional distributors in Cali and Barranquilla manage inventory fragmentation from dual-voltage SKU requirements across 110V and 220V territories.
- Direct Sales:Manufacturer-employed specification consultants are displacing traditional intermediaries for commercial kitchen and hospitality equipment procurement in Bogotá's premium districts.
Offline retail maintains volume dominance, with direct sales expanding most quickly as commercial buyers consolidate decision-making authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's appliance assembly workforce concentrates in the Andean corridor, where Bogotá and Medellín host the majority of technical talent and manufacturing infrastructure. This concentration shapes procurement patterns and service network density across the national territory.
Bogotá Capital District
Urban heat island effects and dense apartment stock drive replacement demand for inverter refrigeration and connected climate systems. The Ministry of Mines and Energy's mandatory efficiency labeling applies strictest enforcement in this jurisdiction. Zona Rosa hospitality clusters specify integrated smart room systems through direct manufacturer channels.
Antioquia Department
Medellín's middle-income households adopt variable-speed compressor platforms at rates exceeding national benchmarks. ICONTEC-accredited testing facilities in the metropolitan zone reduce compliance timelines for regional suppliers. Parque Lleras district restaurant groups consolidate procurement through specification consultants.
Valle del Cauca Department
Cali households prioritize water-efficient front-loading washing machines seeking certification under municipal conservation programs. The Pacific port of Buenaventura channels imported components though logistics bottlenecks extend lead times. Local distributors manage dual-voltage SKU fragmentation across 110V and 220V territories.
Caribbean Coastal Region
Barranquilla and Santa Marta corridors remain underpenetrated for smart appliance adoption relative to Andean metros. Expanding electrification infrastructure creates first-mover positioning for connected product portfolios. Extended producer responsibility collection networks are less developed, raising aftermarket service costs.
Colombia Appliances and Electronics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Colombia's appliance landscape. Integrated manufacturers with captive compressor foundries and regional assembly plants command procurement advantages in refrigeration and climate systems. The market structures around three archetypes: multinational electronics conglomerates with smart home ecosystems, European heritage brands with premium positioning, and domestic assemblers leveraging localized service networks. Competitive moves concentrate on portfolio diversification into energy-certified product lines and backward integration into component manufacturing to mitigate semiconductor input volatility.
Among Korea-based electronics conglomerates, LG Electronics and Samsung Electronics exemplify ecosystem-driven positioning through connected appliance architectures and mobile platform integration. European heritage manufacturers including Electrolux AB and BSH Hausgeräte GmbH occupy premium-tier positions emphasizing engineering credentials and durability claims. Domestic specialist Industrias HACEB anchors the local assembly archetype, competing through geographic proximity to Andean service networks and compliance familiarity with Ministry of Mines and Energy mandates.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Electrolux AB |
| LG Electronics |
| Samsung Electronics |
| Panasonic Corporation |
| BSH Hausgeräte GmbH |
| Haier Electronics Group Co. Ltd |
| Arcelik AS |
| Industrias HACEB |
| Others |
Pricing and Supply Chain Analysis
Semiconductor input costs from Asian foundries cascade through Colombian assembly operations into tiered hardware pricing, with inverter compressor modules and WiFi connectivity chipsets concentrating margin pressure at the premium tier while fixed-speed mechanical platforms absorb residual demand in price-sensitive corridors.
Pricing Analysis
Bundled installation and extended warranty services separate premium positioning from transactional hardware sales in Bogotá and Medellín, where three-tier pricing structure across premium, standard, and economy levels aligns with ICONTEC certification grades and after-sales network density. Cost compression in the standard tier intensifies because mid-tier suppliers redesign portfolios around eighteen-month compliance cycles. Hospitality buyers in Zona Rosa and Parque Lleras districts exhibit lowest price sensitivity, prioritizing same-day service response over unit economics.
Supply Chain Analysis
Extended producer responsibility mandates from the Ministry of Environment and Sustainable Development are reshaping sourcing toward domestic assembly partners with captive collection infrastructure, drawing microcontroller units from Taiwan, power management chips from South Korea, and compressor castings from China. Single-source vulnerability concentrates in Pacific port throughput at Buenaventura, where Andean logistics bottlenecks amplify lead time risk. Distribution runs through Cartagena container terminals into regional wholesaler networks managing dual-voltage SKU fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's appliance market functions as a geographic-arbitrage play between Andean manufacturing scale and Caribbean coastal underpenetration, with electrification infrastructure differentials creating first-mover windows against established metro competitors.
For Market Incumbents: Deepen backward integration into inverter compressor manufacturing to offset semiconductor input volatility from Asian foundries, while expanding ICONTEC-accredited testing capacity to compress compliance timelines that currently disadvantage mid-tier redesign cycles. Field service network density outside the Bogotá-Medellín-Cali triangle remains the priority lever for warranty fulfillment differentiation. For New Entrants and Emerging Players: Direct-installer procurement channels in Barranquilla and Santa Marta hospitality corridors offer white-space positioning against established retail intermediaries, with boutique hotel developments specifying integrated smart room systems lacking local specification consultant coverage. Target Caribbean coastal electrification expansion with predictive maintenance subscription bundles that commercial buyers negotiate through fleet pricing. For Investors and Strategic Acquirers: Consolidation pressure builds where field service network fragmentation degrades brand loyalty and warranty fulfillment economics, particularly among domestic assemblers lacking authorized technician density outside metropolitan triangles. Acquisition candidates include vertically integrated mid-cap specialists with captive compressor foundries and Ministry of Mines and Energy compliance familiarity. Monitor carbon border adjustment preparation investments as inflection signal for local assembly competitiveness preservation.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Technology Licensing | LG Electronics leverages patented variable-speed architectures to sustain premium refrigeration positioning under Ministry labeling mandates. |
| Direct-to-Installer Channel Expansion | Manufacturer-employed specification consultants displace retail intermediaries for Bogotá hospitality procurement with same-day technical response. |
| Extended Producer Responsibility Infrastructure | Domestic assemblers finance end-of-life collection networks to capture aftermarket service revenue pools under Ministry of Environment rules. |
| Smart Home Ecosystem Integration | Samsung Electronics anchors growth through mobile platform connectivity that bundles predictive maintenance algorithms with hardware sales. |
| Caribbean Coastal Electrification Positioning | First-mover smart appliance deployment in Barranquilla and Santa Marta corridors exploits underpenetration relative to Andean metros. |
Research Methodology
Multiple input streams — primary interviews with appliance manufacturing executives, ICONTEC certification specialists, and hospitality procurement directors, alongside customs records, Ministry of Mines and Energy regulatory filings, and Superintendency of Industry and Commerce distribution data — were reconciled through bottom-up unit shipment modeling and top-down value aggregation across the analysis window.
Historical replacement cycle patterns from Andean metropolitan corridors were cross-referenced against panel input from regional distributor networks to derive expansion trajectories across product type, technology tier, end user segment, and distribution channel dimensions. CAGRs emerged from segmented growth rate reconciliation with semiconductor input cost indices and electrification infrastructure deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment implementation in neighboring trade blocs and Pacific port capacity expansion at Buenaventura. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Laundry Dryer Market
Appliances
Electric Hand Dryer Market
Appliances
Egypt Dishwashers Market
Appliances
GCC Microwave Oven Market
Appliances
Refrigerator Door Seal Market
Appliances
Residential Space Heater Market
Appliances
Kuwait Microwave Ovens Market
Appliances
Conveyor Dishwasher Market
Appliances
Glass Ceramic Cooktop Market
Appliances
Europe Tumble Dryers Market
Appliances
Digital Showers Market
Appliances
Egypt Microwave Ovens Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Germany Consumer Appliances Market
Appliances
Qatar Dishwashers Market