
 Glass Ceramic Cooktop Market | 2026-2036
Glass Ceramic Cooktop Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Ceramic Cooktop Market Analytics
Residential renovation demand is rotating toward premium induction cooktops as homeowners prioritize energy efficiency and sleek kitchen aesthetics. SCHOTT CERAN dominates branded glass-ceramic substrate supply for major appliance OEMs across Europe and Asia. EuroKera leverages proprietary lithium aluminosilicate formulations to sustain thermal shock performance leadership. Kedi Glass-Ceramic anchors cost-competitive supply from China, competing on volume for mid-range electric cooktop segments.
Glass ceramic cooktops consist of lithium aluminosilicate or borosilicate glass-ceramic panels engineered to withstand thermal cycling from ambient to over 700°C without deformation, manufactured through controlled nucleation and crystallization of glass substrates. Induction product types lead value generation due to higher panel specifications and consumer willingness to pay for precision temperature control. Residential end users occupy the largest volume pool, though hospitality installation types are registering faster growth as hotel chains standardize kitchen specifications. Built-in configurations dominate mature markets, while portable units are gaining traction in urban rental segments across Asia.
The EU Ecodesign Directive and REACH frameworks mandate minimum energy efficiency thresholds and restrict hazardous substance content in glass-ceramic manufacturing inputs. The US Department of Energy appliance standards and California Title 24 building codes shape product specifications for North American market access. China's GB standards for household appliances enforce thermal efficiency testing protocols that influence export-oriented manufacturer design cycles. Stakeholders must monitor evolving efficiency benchmarks and material compliance requirements as regulatory divergence between jurisdictions intensifies certification complexity.
Market Dynamics
Residential kitchen renovation cycles are compressing as homeowners prioritize energy-efficient appliance upgrades, creating sustained pull for premium induction-compatible glass-ceramic surfaces that meet tightening thermal efficiency mandates.
Growth Catalysts
- EU Ecodesign Directive:Minimum energy efficiency thresholds for cooking appliances mandate higher-specification glass-ceramic substrates, accelerating replacement demand across German and French residential markets.
- Induction technology maturation:Precision temperature control capabilities are displacing conventional electric coil cooktops in mid-market kitchen renovations, expanding addressable panel volume.
- Hospitality standardization:Hotel chains in Spain and Italy are specifying uniform glass-ceramic cooktop configurations across property portfolios, creating pooled procurement volumes.
Market Restraints
- Lithium supply concentration:Spodumene and lithium carbonate processing capacity clusters in Australia and Chile, exposing glass-ceramic manufacturers to raw material price volatility and geopolitical supply risk.
- Technical performance ceiling:Current lithium aluminosilicate formulations face thermal shock limitations above 750°C, constraining high-power commercial induction applications.
- REACH compliance friction:ECHA substance restrictions on nickel and chromium compounds in manufacturing inputs force reformulation cycles that extend product development timelines by 12-18 months.
Strategic Opportunities
- Urban rental penetration:Portable induction units with lightweight glass-ceramic panels are gaining traction in Tokyo and Seoul apartment markets where permanent installation is restricted.
- Smart kitchen convergence:Integration of temperature sensors and IoT connectivity into cooktop surfaces creates value-add differentiation beyond thermal performance.
- US Inflation Reduction Act:Residential clean energy tax credits for efficient electric appliances subsidize induction cooktop purchases, opening incremental demand in California and New York retrofit markets.
Industry Challenges
- Crystallization process expertise:Controlled nucleation of glass-ceramic substrates requires specialized furnace operators and materials scientists, creating talent scarcity in manufacturing hubs.
- Multi-jurisdiction certification:Simultaneous compliance with EU CE marking, US DOE appliance standards, and China's GB testing protocols extends product launch timelines and fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Ceramic Cooktop Market |
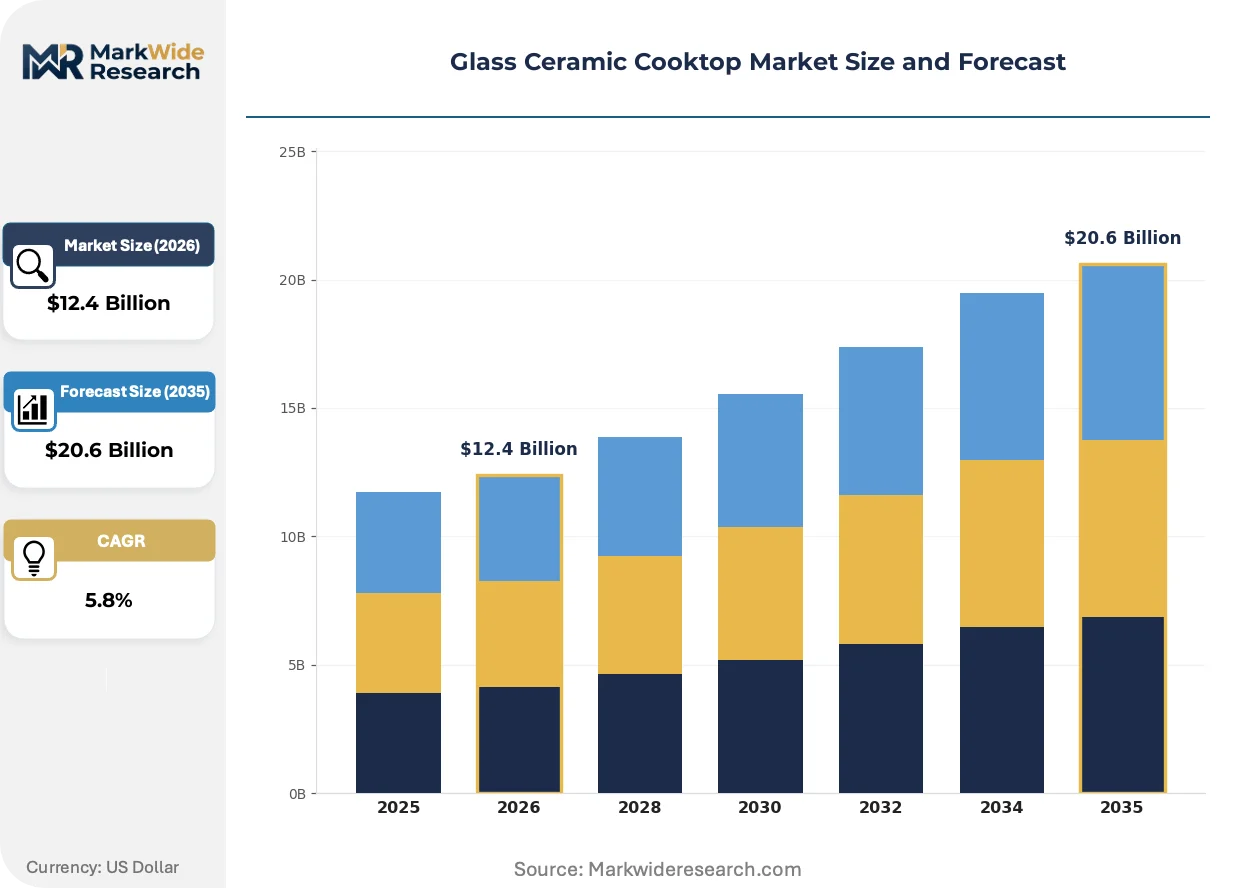
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction, Electric, Gas, Hybrid End User: Residential, Commercial, Hospitality, Institutional Installation Type: Built-in, Freestanding, Portable, Drop-in Material: Ceramic, Glass, Metal, Composite |
| Companies Covered | Kanger Enterprise, Kedi Glass-Ceramic, SCHOTT CERAN, Novatech Glass, Far East Optoelectronics, EuroKera, TA HSIANG, LG Electronics, NEG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Ceramic Cooktop Market Evolving Landscape
Glass-ceramic cooktop manufacturing is experiencing material science advancement alongside regulatory-driven efficiency mandates, reshaping competitive positioning around thermal performance and sustainability credentials.
Transparent conductive oxide coatings are fragmenting the traditional opaque cooktop aesthetic, enabling visual integration with kitchen countertops. High-end residential developers in Milan and Copenhagen are specifying these panels for minimalist design schemes. The technology is fragmenting the premium segment into performance-focused and design-focused sub-categories with diverging price structures.
REACH substance restriction expansions are forcing reformulation of glass-ceramic nucleating agents across European manufacturing. ECHA evaluations of boron compound classifications are compressing allowable input chemistries. German and French substrate producers are accelerating alternative crystallization catalyst development to maintain production continuity.
Builder procurement consolidation is compressing vendor relationships in multi-family residential construction. Large developers in Texas and Florida are mandating single-source glass-ceramic specifications across entire apartment portfolios. This behavior is concentrating volume with substrate suppliers capable of multi-year supply agreements and dedicated inventory buffers.
Glass Ceramic Cooktop Market Segmentation
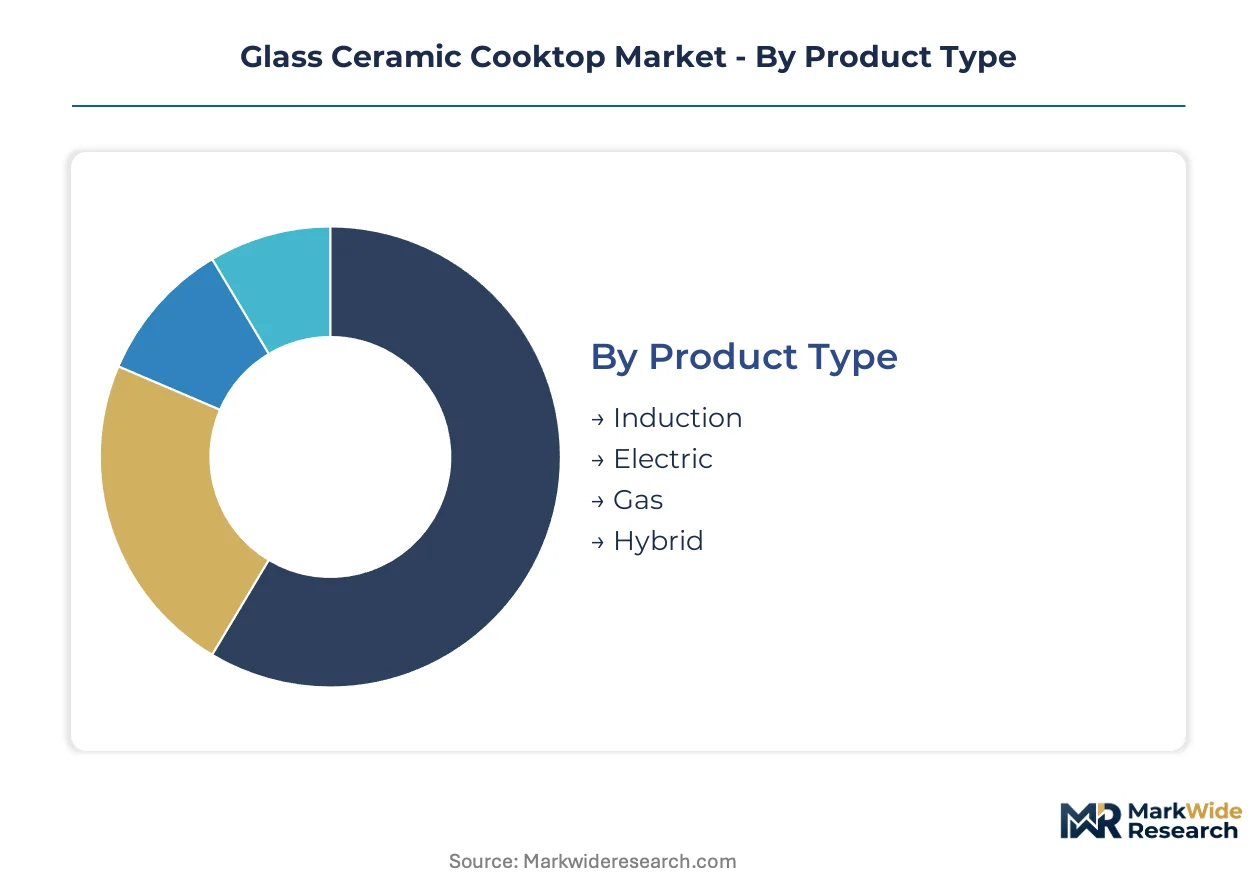
Glass-ceramic cooktop demand fragments across four structural dimensions, each governing distinct procurement channels and margin profiles. Product type and installation configuration determine whether panels flow through builder supply chains, retail distributors, or direct hospitality procurement. Understanding these segment boundaries enables targeted positioning against diverging technical specifications and price elasticity patterns.
Product Type:
Channel mix varies sharply across heating technologies, with induction panels commanding premium distribution through kitchen design studios while electric variants sustain volume through mass retail.
- Induction:Lithium aluminosilicate substrates engineered for rapid thermal response and magnetic field compatibility. German kitchen renovation demand concentrates here as homeowners prioritize energy efficiency credentials under EU Ecodesign thresholds.
- Electric:Conventional resistive heating relies on lower-specification borosilicate or standard glass-ceramic formulations. Volume concentrates in mid-range replacement cycles across US suburban housing stock where retrofit costs deter induction upgrades.
- Gas:Glass-ceramic overlays serve aesthetic functions atop conventional burner systems rather than primary heating surfaces. Demand persists in markets with established natural gas infrastructure.
- Hybrid:Dual-zone configurations combining induction and electric elements in single panels. Niche positioning targets transitional consumers in mixed-fuel households.
By volume, Electric leads. By growth pace, Induction is expanding most quickly.
End User:
Cost tier stratification separates specification-intensive hospitality procurement from price-sensitive residential replacement demand.
- Residential:Single-family and multi-family household installations. Italian and Spanish consumers drive premium built-in specifications while US markets sustain freestanding volume through big-box retail.
- Commercial:Restaurant and foodservice operations requiring thermal durability beyond residential ratings. French and Japanese operators specify reinforced panels for high-duty-cycle environments.
- Hospitality:Hotel chains standardizing cooktop configurations across property portfolios. Procurement consolidation in Madrid and Rome creates pooled volume with dedicated inventory requirements.
- Institutional:Schools, hospitals, and corporate cafeterias governed by public procurement protocols. Compliance documentation demands exceed private-sector thresholds.
Residential dominates absolute panel consumption. Hospitality procurement is climbing the fastest as chain standardization accelerates.
Installation Type:
Application context determines whether glass-ceramic panels integrate permanently into cabinetry or serve temporary deployment scenarios.
- Built-in:Flush-mounted panels requiring precise cutout dimensions and countertop integration. German kitchen manufacturers specify these exclusively for new construction and full renovations.
- Freestanding:Self-contained ranges with integrated oven compartments. US and UK markets sustain this format through replacement-driven purchase patterns.
- Portable:Lightweight single-burner or dual-burner units for restricted-installation environments. Tokyo and Seoul apartment markets are absorbing rising volumes.
- Drop-in:Semi-integrated units bridging built-in and freestanding categories. Limited to specific regional preferences in Australia and Canada.
Built-in configurations command the highest unit margins. Portable segments are gaining share fastest among urban rental demographics.
Material:
Supply concentration and processing complexity differentiate raw material categories, with lithium-bearing substrates commanding specialized manufacturing assets.
- Ceramic:Sintered oxide compositions offering thermal mass advantages. Traditional electric coil cooktops in emerging markets continue specifying these lower-cost alternatives.
- Glass:Tempered soda-lime formulations for decorative overlays and budget electric applications. Thermal shock limitations constrain induction compatibility.
- Metal:Stainless steel and enameled steel surfaces in commercial and outdoor cooking equipment. Glass-ceramic competition is displacing share in indoor residential segments.
- Composite:Multi-layer laminates combining ceramic cores with glass surfaces. Niche positioning targets specific thermal performance requirements.
Glass-ceramic substrates dominate value generation. Ceramic alternatives retain volume leadership in lowest-price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European glass-ceramic distribution, channeling lithium aluminosilicate substrates from French and German manufacturing clusters into Scandinavian and Baltic renovation markets.
Germany
Building energy codes in Baden-Württemberg and Bavaria mandate thermal efficiency thresholds that accelerate induction cooktop replacement cycles. The EU Ecodesign Directive enforces minimum performance standards for residential cooking appliances. Stuttgart's appliance OEM corridor concentrates procurement volume with substrate suppliers capable of multi-year supply agreements.
China
GB standards for household appliances enforce thermal efficiency testing protocols that reshape export-oriented manufacturer design cycles. MIIT regulations govern lithium compound handling in glass-ceramic nucleation processes. The Yangtze River Delta manufacturing belt anchors cost-competitive panel production for mid-range electric cooktop segments.
United States
The Department of Energy appliance standards and California Title 24 building codes shape product specifications for North American market access. The Inflation Reduction Act's residential clean energy tax credits subsidize efficient electric appliance purchases. Texas and Florida builder procurement consolidation mandates single-source specifications across multi-family apartment portfolios.
Japan
METI efficiency labeling programs steer consumer preference toward induction-compatible surfaces in Tokyo and Osaka metro renovation markets. JIS standards govern thermal shock performance testing for residential cooking equipment. The Kansai industrial corridor hosts specialized furnace operators with crystallization process expertise.
France
ECHA REACH substance restrictions on nickel and chromium compounds force reformulation cycles across European glass-ceramic manufacturing. The EU Green Deal's embodied carbon tracking requirements pressure substrate producers to document supply chain emissions. The Limoges materials science cluster sustains proprietary lithium aluminosilicate formulation development.
Glass Ceramic Cooktop Market Competitive Landscape
Concentration sits with specialized glass-ceramic substrate manufacturers possessing controlled nucleation expertise and multi-jurisdiction certification capabilities. The vendor base stratifies across premium formulation specialists, scale-driven Asian fabricators, and diversified appliance OEMs with captive substrate operations. Three archetypes dominate: proprietary technology licensors, cost-optimized volume producers, and vertically integrated appliance brands. Competitive moves center on alternative crystallization catalyst development and dedicated inventory buffers for hospitality procurement consolidation.
Among European technology licensors, EuroKera and SCHOTT CERAN exemplify premium-tier positioning through proprietary lithium aluminosilicate formulations. Kedi Glass-Ceramic anchors the cost-competitive volume tier from Chinese manufacturing bases. These three entities represent divergent strategic vectors—formulation leadership, brand equity capture, and scale-driven market penetration—without implying specific market share claims or operational details beyond their evident geographic and structural positioning.
| Leading Market Players |
|---|
| Kanger Enterprise |
| Kedi Glass-Ceramic |
| SCHOTT CERAN |
| Novatech Glass |
| Far East Optoelectronics |
| EuroKera |
| TA HSIang |
| LG Electronics |
| NEG |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory buffers for lithium aluminosilicate substrates concentrate pricing power with German and French formulation specialists, while Chinese volume producers compress margins through shorter cycle times and reduced working capital requirements. This divergence between premium-tier supply assurance and cost-tier velocity shapes procurement negotiations across residential renovation and hospitality specification channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs glass-ceramic panel transactions, with formulation complexity and REACH compliance certification separating tiers. Hospitality procurement consolidation in Madrid and Rome extracts volume discounts exceeding residential retail channels, while German kitchen OEMs absorb premium pricing for dedicated inventory buffers. Cost compression in mid-range electric segments intensifies as Yangtze River Delta producers expand furnace capacity. Price-sensitive buyers in US suburban replacement cycles prioritize economy-tier borosilicate alternatives, whereas Italian design studios exhibit minimal elasticity for transparent conductive oxide finishes.
Supply Chain Analysis
France and Germany anchor premium lithium aluminosilicate substrate production, while China's Yangtze River Delta manufacturing belt feeds cost-competitive borosilicate volume. Spodumene concentrate from Australia and Chilean lithium carbonate supply nucleating agents for crystallization processes. Single-source vulnerability concentrates in Australian spodumene processing, where geological concentration and limited alternative feedstock create chokepoint exposure. Distribution runs through Hamburg's port infrastructure into Scandinavian renovation markets, with dedicated logistics contracts serving hospitality procurement pools in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation support and extended warranty services expand faster than hardware sales as hospitality chains prioritize uptime guarantees and rapid panel replacement protocols. This service-attach layer offers margin expansion beyond commoditizing substrate transactions.
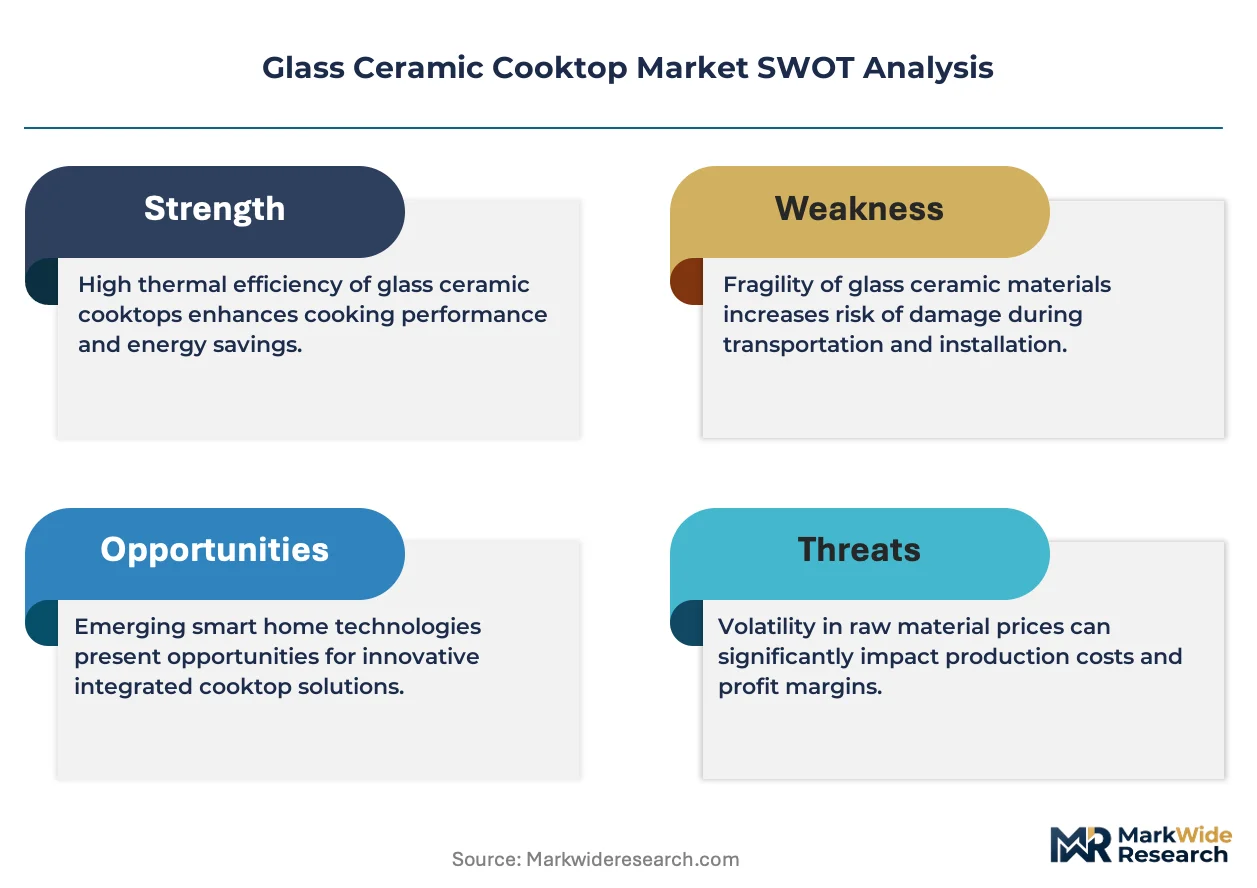
For Market Incumbents: Fortify crystallization process expertise through captive furnace operator training programs in the Kansai industrial corridor, countering talent scarcity that delays product launches. Deepen backward integration into lithium compound sourcing via long-term offtake agreements with Australian spodumene processors, reducing exposure to spot market volatility that compresses formulation margins. For New Entrants and Emerging Players: Aftermarket sensor integration for legacy cooktop surfaces represents an underserved layer where incumbents lack dedicated engineering resources. Target portable induction unit segments in Tokyo and Seoul apartment markets, where installation restrictions prevent built-in competition. Pursue direct-to-property-manager distribution bypassing traditional kitchen retail channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance OEMs with captive but under-optimized substrate operations lacking multi-jurisdiction certification capabilities. Five-to-ten year viability hinges on REACH-compliant alternative nucleating agent development. Monitor ECHA boron compound classification proceedings as an inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Crystallization Catalyst Development | ECHA boron restrictions in France and Germany force formulation pivots to maintain EU production continuity. |
| Hospitality Procurement Consolidation Response | Texas and Florida builder mandates for single-source specifications reward dedicated inventory buffer investments. |
| Smart Surface Sensor Integration | IoT temperature monitoring in Milan and Copenhagen premium installations differentiates beyond thermal performance. |
| Portable Unit Lightweight Panel Engineering | Tokyo and Seoul rental market traction requires redesigned glass-ceramic substrates below conventional thickness thresholds. |
| REACH Compliance Documentation Systems | Embodied carbon tracking under EU Green Deal pressures Limoges cluster producers to audit supply chain emissions. |
Research Methodology
A standing panel of appliance OEM procurement directors, glass-ceramic furnace operators, ECHA regulatory affairs specialists, and hospitality chain facility managers provided ongoing calibration against secondary validation from MIIT GB standard filings, EU Ecodesign Directive implementation reports, and US DOE appliance standard dockets. Bottom-up substrate volume estimates triangulated with top-down renovation spending analysis across German, Italian, and US metropolitan markets.
Consistency checks against external benchmarks validated value outputs across the projection horizon, with segmentation modeling spanning product type, installation configuration, end-user category, and material formulation tier. CAGRs derived from regression analysis of replacement cycle compression and regulatory efficiency mandate adoption curves, incorporating lithium compound price volatility indices and hospitality procurement consolidation timelines as industry-specific inputs.
Material uncertainties — lithium supply disruption, ECHA substance restriction expansion, and hospitality capital expenditure cycles — sit outside the modeled envelope. Forecasts reflect assumptions about continued EU Ecodesign Directive enforcement and US Inflation Reduction Act credit stability. Recalibration cycles align with material shifts in nucleating agent regulatory classifications and builder procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
United States Washing Machine Market
Appliances
Minibar Refrigerators Market
Appliances
APAC White Goods Market
Appliances
Body Dryer Market
Appliances
Electric Ranges Market
Appliances
Bhutan and Nepal White Goods Market
Appliances
Under Counter Dishwasher Market
Appliances
Electric Yogurt Maker Market
Appliances
Dishwasher Market
Appliances
Global Massage Chairs Market
Appliances
Mexico Washing Machine Market
Appliances
Refrigerator Door Seal Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Europe Microwave Oven Market
Appliances
India Washing Machine Market
Appliances
Bahrain Dishwashers Market