
 North America Compact Dishwasher Market | 2026-2036
North America Compact Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
North America Compact Dishwasher Market Insights
Market Context
Buyer fragmentation across urban micro-unit developers and rental property portfolios is repositioning procurement patterns toward compact-format specifications. Whirlpool Corporation leverages its North American manufacturing footprint to sustain cost-competitive positioning in countertop and portable variants. Robert Bosch GmbH anchors premium positioning through quiet-operation engineering and extended warranty programs. Danby specializes in apartment-scale formats, occupying the sub-24-inch niche with distribution concentrated through big-box and direct-to-property-manager channels.
Technical Definition and Segments
A compact dishwasher denotes a dishwashing appliance with width typically below 24 inches, designed for constrained installation footprints in residential kitchens, food-service prep areas, and institutional break rooms, utilizing reduced water volumes per cycle compared with standard-capacity units. The built-in and portable type categories dominate current shipment volumes, while drawer configurations command margin premiums in luxury residential and boutique hospitality retrofit projects. Smart technology integration represents the fastest-expanding technology segment, though high-efficiency units without connectivity features retain stronger penetration in price-sensitive commercial end-user applications.
Regulatory Outlook
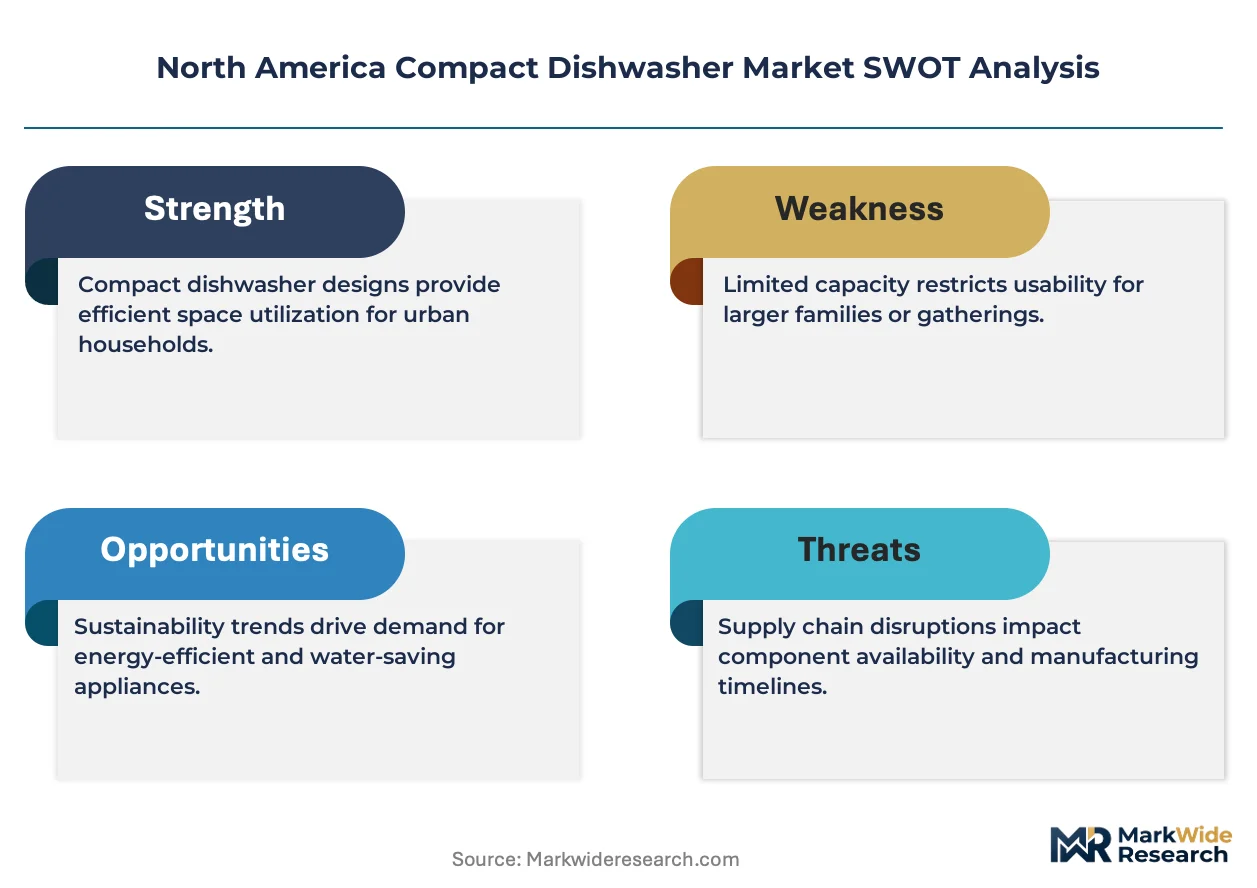
ENERGY STAR certification requirements administered by the EPA and DOE shape minimum efficiency thresholds and water-consumption limits for products sold across the United States, while Canada's Natural Resources Canada enforces parallel EnerGuide labeling that manufacturers must satisfy for cross-border market access. The EPA WaterSense program and California Title 20 appliance standards exert additional pressure on design specifications, particularly in western states facing sustained water-use restrictions. Stakeholders must monitor evolving federal appliance efficiency rulemakings and state-level building code amendments that increasingly mandate compact-format readiness in new multifamily construction.
Market Dynamics
Municipal water-efficiency mandates in drought-prone states are compressing installation timelines and forcing specification upgrades across multifamily construction pipelines, fundamentally altering procurement cadence and manufacturer certification priorities.
Growth Catalysts
- ENERGY STAR tightening:EPA and DOE efficiency thresholds are eliminating lower-tier models from retail shelves, channeling demand toward certified compact formats and accelerating replacement cycles in California, Texas, and Florida corridors.
- Micro-unit construction surge:Urban developers in Dallas, Houston, and Miami are embedding sub-24-inch dishwasher specifications into base building designs, creating captive demand for built-in and drawer configurations.
- WaterSense program expansion:EPA WaterSense labeling is gaining traction among property managers seeking utility rebate eligibility, particularly in western states facing sustained consumption restrictions.
Market Restraints
- Stainless steel and electronic component volatility:Input cost swings for compressor motors and control boards are compressing margins on entry-level countertop units, forcing portfolio repricing.
- Cross-border certification friction:Divergent EPA and Natural Resources Canada testing protocols create duplicated compliance costs for manufacturers serving both markets, slowing product launch velocity.
- Sink-mounted spray arm substitutes:Manual dishwashing attachments and countertop washing pods retain cost advantage in sub-500-dollar appliance budgets, limiting penetration in extreme price-sensitive segments.
Strategic Opportunities
- Mexico manufacturing proximity:Nearshoring assembly capacity to Baja California and Chihuahua reduces freight exposure to Texas and California distribution hubs while hedging Asia-Pacific supply chain risk.
- Smart-home ecosystem convergence:Wi-Fi-enabled cycle programming and leak-detection sensors are expanding into mid-tier price bands, opening premium feature access to rental property portfolios previously locked out of connected appliances.
- Title 20 readiness mandates:California's building code amendments requiring compact-format appliance rough-ins in new multifamily units are creating regulatory tailwinds for specification-grade manufacturers with pre-certified product lines.
Industry Challenges
- Installation technician certification gaps:Shortages of plumbers familiar with 18-inch and drawer-configuration rough-in requirements are extending project timelines and inflating retrofit labor costs in urban renovation markets.
- Dual-certification timeline compression:Simultaneous EPA ENERGY STAR and Canadian EnerGuide validation processes are stretching R&D-to-market intervals, forcing inventory pre-positioning before full regulatory clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Compact Dishwasher Market |
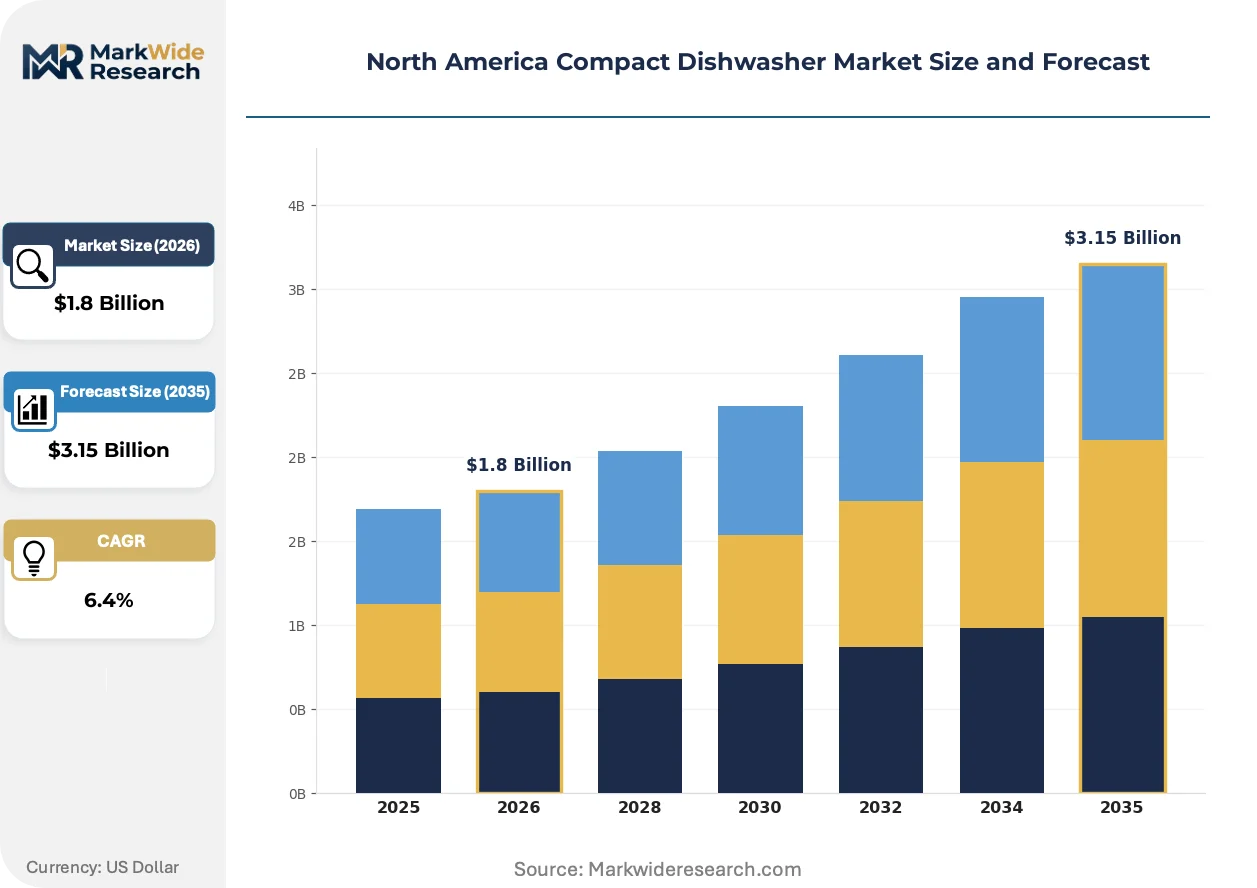
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Built-in, Portable, Countertop, Drawer Technology: Smart, Sensor, High-Efficiency, Traditional End User: Residential, Commercial, Hospitality, Institutions Size: 18-inch, 24-inch, Mini, Compact |
| Companies Covered | Whirlpool Corporation, Electrolux AB, BSH, Robert Bosch GmbH, Haier Group Corporation, LG Electronics Inc., Siemens AG, Danby, Mabe, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Compact Dishwasher Market Trends and Innovations
Connectivity integration and water-recirculation engineering are compressing the feature gap between compact and full-size units, while procurement centralization among institutional buyers is rewiring traditional retail channel dominance.
Condensation-drying technology is expanding into compact dishwasher architectures previously reliant on energy-intensive heated drying elements. Micro-unit developers in Austin and Phoenix are specifying these systems to meet strict energy-budget caps in LEED-targeted buildings. This shift is expanding into price bands below six hundred dollars, eroding the historical premium associated with European-engineered drying systems.
California Title 20 appliance standards are mandating maximum water consumption thresholds per cycle that exceed current federal ENERGY STAR baselines. Manufacturers must redesign spray arm geometry and pump efficiency to maintain cycle performance under reduced volume constraints. The built-in segment is responding fastest, with 2024-2025 product launches prioritizing western state compliance ahead of national rollout.
Property management software integration is reshaping how rental portfolios specify and maintain compact dishwashers. Institutional buyers in Atlanta and Chicago are unbundling appliance procurement from traditional big-box channels, instead routing volume through direct manufacturer agreements tied to maintenance analytics platforms. This behavior is most visible in mid-rise multifamily assets where unit counts justify captive service contracts and remote diagnostics capabilities.
North America Compact Dishwasher Market Segmentation
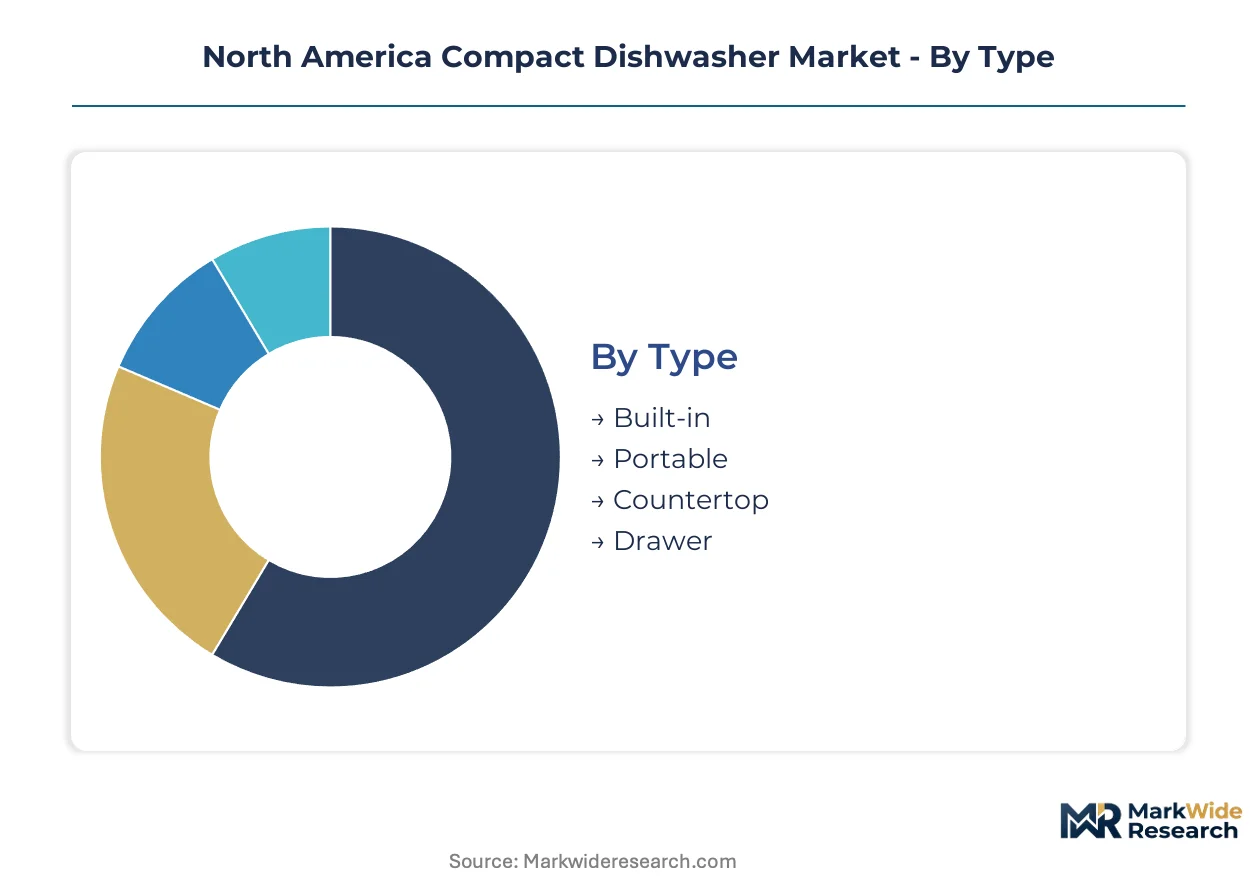
Segmentation in the North America compact dishwasher market reveals divergent capital requirements and margin profiles across installation formats and technology tiers. Procurement patterns vary sharply between property developers seeking bulk built-in specifications and individual consumers prioritizing plug-and-play portability.
Type:
Built-in configurations demand the heaviest upfront investment in cabinet integration, plumbing rough-ins, and contractor coordination, while portable and countertop variants minimize installation capital.
- Built-in:These units require permanent cabinet modification and dedicated water supply lines. Texas and California multifamily developers specify these for new construction to meet Title 20 readiness mandates and secure utility rebate eligibility.
- Portable:Freestanding units with wheeled bases and temporary faucet connections dominate rental property retrofits where permanent installation is prohibited. Demand concentrates in Chicago and Atlanta mid-rise portfolios seeking appliance flexibility between tenant turns.
- Countertop:Compact units sitting on kitchen surfaces with manual water filling suit extreme space constraints.
- Drawer:Pull-out compartment designs command premium positioning in luxury residential and boutique hospitality.
Most installed capacity flows through built-in specifications. Expansion is steepest in drawer configurations.
Technology:
Smart and sensor-enabled systems carry higher bill-of-materials costs and firmware development overhead compared with mechanical-control traditional units.
- Smart:Wi-Fi-connected units with app-based cycle programming and leak detection sensors. Miami and Phoenix property managers specify these for remote diagnostics integration with building management platforms.
- Sensor:Load-sensing systems adjusting water volume and cycle duration based on soil detection. These balance efficiency gains against moderate price premiums in California water-restricted municipalities.
- High-Efficiency:ENERGY STAR-certified mechanical designs without connectivity features retain cost advantage in price-sensitive commercial break room applications.
- Traditional:Basic timer-based controls with fixed cycle options serve budget-constrained replacement demand.
Volume leadership sits with high-efficiency mechanical units. Connected smart systems are gaining share fastest among institutional buyers.
End User:
Commercial and hospitality procurement operates on centralized volume contracts with service-level agreements, while residential purchasing fragments across individual retail transactions.
- Residential:Individual homeowners and apartment dwellers purchasing through retail channels or builder specifications. Florida condo conversions and Texas urban infill projects drive built-in demand in this segment.
- Commercial:Office break rooms and food-service prep areas requiring durability and rapid cycle turnaround. Procurement centralizes through facility management vendors with captive maintenance contracts.
- Hospitality:Boutique hotels and extended-stay properties specifying compact formats for in-suite kitchenettes. LEED-targeted properties in Austin and Denver prioritize condensation-drying and WaterSense certification.
- Institutions:University housing, healthcare facilities, and government buildings with extended replacement cycles and strict procurement compliance requirements.
The residential channel carries the largest installed base. Hospitality applications are expanding most quickly as boutique property development accelerates.
Size:
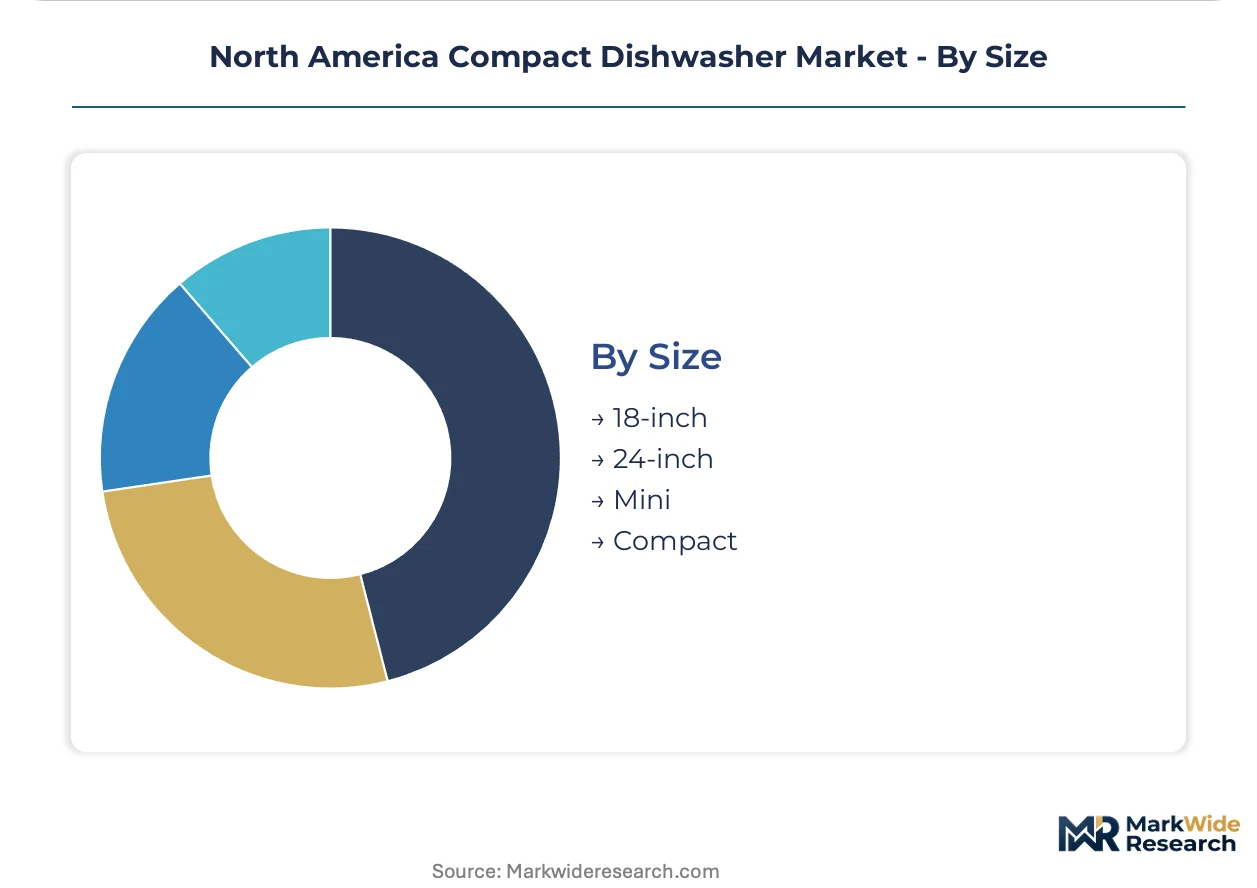
18-inch and true compact formats require specialized component miniaturization and non-standard rack engineering, elevating per-unit manufacturing investment versus full-width 24-inch designs.
- 18-inch:Slim-width built-in units fitting standard cabinet openings with reduced capacity. These dominate California and Texas micro-unit specifications where kitchen footprints fall below seventy square feet.
- 24-inch:Full-width compact designs with shortened depth rather than reduced width. These suit galley kitchen renovations in older urban housing stock where cabinet width is fixed but depth is constrained.
- Mini:Ultra-compact units below eighteen inches wide targeting studio apartments and accessory dwelling units.
- Compact:General classification encompassing all sub-standard-capacity dimensions without specific dimensional designation.
Twenty-four-inch formats retain the broadest installed base. Eighteen-inch specifications are climbing the fastest as micro-unit construction penetrates Sun Belt urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plumbing technician density and appliance installer certification programs anchor geographic production and deployment capacity across the continent. Regional demand patterns diverge sharply between Sun Belt water-restriction corridors and northern retrofit markets.
United States
Texas and California urban corridors drive specification-grade built-in demand through Title 20 readiness mandates and municipal rebate programs. EPA ENERGY STAR and WaterSense certification requirements compress procurement timelines for multifamily developers in Dallas, Houston, and Los Angeles. Austin and Phoenix micro-unit construction clusters specify condensation-drying systems to meet LEED energy-budget caps.
Canada
Ontario and Quebec rental property portfolios generate portable-format demand where permanent installation is prohibited by lease structures. Natural Resources Canada EnerGuide labeling creates cross-border certification friction with divergent EPA testing protocols. Toronto and Vancouver urban infill projects concentrate drawer-configuration specifications in luxury residential segments.
Mexico
Baja California and Chihuahua manufacturing proximity supports nearshored assembly capacity serving Texas and California distribution hubs. The country's national appliance efficiency regulator enforces labeling standards that manufacturers must satisfy for market access. Mexico City metro area construction activity generates demand for compact-format specifications in mid-rise multifamily developments.
North America Compact Dishwasher Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price bands in this market. The vendor base organizes around three strategic archetypes: full-line appliance conglomerates with North American manufacturing footprints, European-engineered premium specialists emphasizing quiet-operation systems, and sub-24-inch niche players concentrated through property-manager channels. Competitive moves center on portfolio diversification into smart-home ecosystems and geographic expansion through Mexico nearshoring to hedge supply chain exposure.
Among diversified conglomerates, Whirlpool Corporation anchors cost-competitive positioning through domestic manufacturing scale. Robert Bosch GmbH exemplifies the European-engineered premium archetype with extended warranty programs. Danby occupies the focused specialist tier, concentrating distribution through big-box and direct-to-property-manager channels for apartment-scale formats.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Electrolux AB |
| BSH |
| Robert Bosch GmbH |
| Haier Group Corporation |
| LG Electronics Inc. |
| Siemens AG |
| Danby |
| Mabe |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap appliance specialists anchored in the Great Lakes manufacturing belt exert outsized pricing discipline through captive distribution relationships with property management portfolios, while their limited balance sheet flexibility constrains supply chain hedging against compressor motor cost volatility.
Pricing Analysis
The bundled-vs-unbundled service split separates specification-grade built-in procurement with installation and warranty wrap from countertop units sold through retail without after-sales support. Three-tier pricing structure across premium, standard, and economy levels stratifies by ENERGY STAR certification tier and quiet-operation decibel ratings, with Texas and California developers least sensitive and individual Amazon-channel buyers most price-responsive. Cost compression in entry-level countertop segments is intensifying because stainless steel input volatility and electronic control board shortages are forcing portfolio repricing without corresponding feature upgrades.
Supply Chain Analysis
Regional distribution centers in Dallas, Houston, and Los Angeles operate hub-and-spoke patterns radiating into Sun Belt metro corridors. Manufacturing concentrates in Mexico's Baja California and Chihuahua states, China's Zhejiang and Guangdong provinces, and domestic Ohio and Tennessee facilities. Raw material dependencies center on cold-rolled steel for cabinetry, copper windings for compressor motors, and semiconductor components for control boards. Single-source vulnerability in Asian electronic subassemblies creates tariff exposure through Section 301 duties. Distribution runs through big-box retail, direct-to-property-manager channels, and e-commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the demand-shift toward WaterSense-certified and condensation-drying specifications in LEED-targeted multifamily construction.
For Market Incumbents: Acquire smart-home connectivity engineering teams to embed Wi-Fi-enabled diagnostics and leak-detection sensors across mid-tier product lines. Consolidate installation technician certification programs in Texas and California to close the plumber shortage gap threatening project timelines. Defend against sink-mounted spray arm substitutes and manual washing pods by bundling extended warranty coverage with specification-grade built-in procurement. For New Entrants and Emerging Players: Enter via the 18-inch built-in segment serving California Title 20 readiness mandates where incumbent certification backlogs create specification windows. Target Atlanta and Chicago mid-rise rental portfolios seeking portable-format flexibility with direct manufacturer agreements bypassing traditional retail markup. Pursue white-label partnerships with property management software platforms to embed maintenance analytics as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among sub-24-inch niche specialists with concentrated property-manager channel exposure and limited smart-home R&D investment. Long-term viability over the five-to-ten year horizon hinges on regulatory tailwinds from municipal water-efficiency mandates deepening replacement cycle frequency. Monitor California Title 20 amendment trajectories and EPA WaterSense program expansion as the inflection signal for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Ecosystem Integration | Wi-Fi-enabled diagnostics open mid-tier rental portfolios previously locked out of connected appliances. |
| Mexico Nearshoring Expansion | Baja California assembly capacity hedges Asia-Pacific supply chain risk for Texas distribution. |
| WaterSense Certification Investment | EPA labeling secures utility rebate eligibility in western states facing consumption restrictions. |
| Direct Property-Manager Channel Development | Bypassing big-box retail captures institutional volume with captive service contract attachment. |
| Condensation-Drying Technology Migration | Energy-budget compliance in LEED-targeted buildings erodes European-engineered drying premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance procurement directors at multifamily developers, plumbing contractor operations managers, big-box category buyers, and property management software platform executives with secondary validation against ENERGY STAR certified product databases, EPA WaterSense program listings, Natural Resources Canada EnerGuide registrations, and municipal building code amendment records. Bottom-up shipment data triangulated against top-down construction permit analysis.
Segment-weighting applied differential growth assumptions across installation formats, technology tiers, and end-user channels throughout the forecast period. The analytical framework modeled type, technology, end user, and size dimensions alongside regional regulatory cluster intensity. CAGRs derived from regression analysis of historical replacement cycles, new construction penetration rates, and efficiency mandate compliance deadlines. Industry-specific inputs included ENERGY STAR certification timeline compression and Title 20 amendment adoption curves.
Inputs from manufacturer product launch schedules and municipal code adoption timelines were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around near-term shipment forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Global Home Ice Maker Market
Appliances
Vacuum Cleaner Market
Appliances
United States Multi-Functional Oven Market
Appliances
Smart Connected Washing Machine Market
Appliances
Europe Microwave Oven Market
Appliances
Mexico Laundry Appliances Market
Appliances
Middle East Water Heater Market
Appliances
Consumer Appliances Market
Appliances
Egypt Microwave Ovens Market
Appliances
Clothing Iron Market
Appliances
Saudi Arabia Microwave Ovens Market
Appliances
Mini Refrigerator Market
Appliances
Digital Showers Market
Appliances
Household Vacuum Cleaners Market
Appliances
Kuwait Dishwasher Market
Appliances
Dishwasher Market