

Carrier-Agnostic Parcel and Freight Visibility Aggregation Market Size, Share, and Industry Trends Forecast 2026-2036
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market Insights
Healthcare logistics is repositioning carrier-agnostic visibility from a retail-centric tool to a compliance-critical infrastructure layer. project44 leverages its API density to anchor pharmaceutical cold-chain tracking across North American lanes. FourKites sustains competitive density through predictive ETAs calibrated for automotive just-in-sequence networks. Descartes Systems Group dominates customs-coupled visibility, extending its brokerage-to-tracking integration into European pharmaceutical corridors.
Carrier-agnostic parcel and freight visibility aggregation denotes a software architecture that normalizes telemetry streams from disparate carriers through standardized APIs, typically processing location, temperature, and exception events at sub-five-minute intervals to render unified shipment state. The primary commercial purpose is eliminating data fragmentation across multimodal supply chains, enabling shippers to orchestrate inventory positioning without proprietary carrier portal dependencies. Real-Time Tracking occupies the mature revenue base, while Predictive Analytics captures expanding margin pools as machine-learning models ingest weather, port congestion, and driver-hours data. Cloud-Based deployment leads absolute adoption, though Hybrid architectures gain traction among defense and pharmaceutical verticals with data-sovereignty requirements.
FDA traceability mandates under the Drug Supply Chain Security Act compel pharmaceutical shippers to maintain immutable chain-of-custody records, directly stimulating demand for exception-management layers that flag temperature excursions across carrier handoffs. The EU AI Act introduces risk-classification requirements for automated routing decisions, pressuring European visibility vendors to document algorithmic transparency in predictive ETA engines. Stakeholders must now evaluate whether their aggregation platforms can ingest emerging telematics standards from autonomous trucking pilots without architecture overhaul.
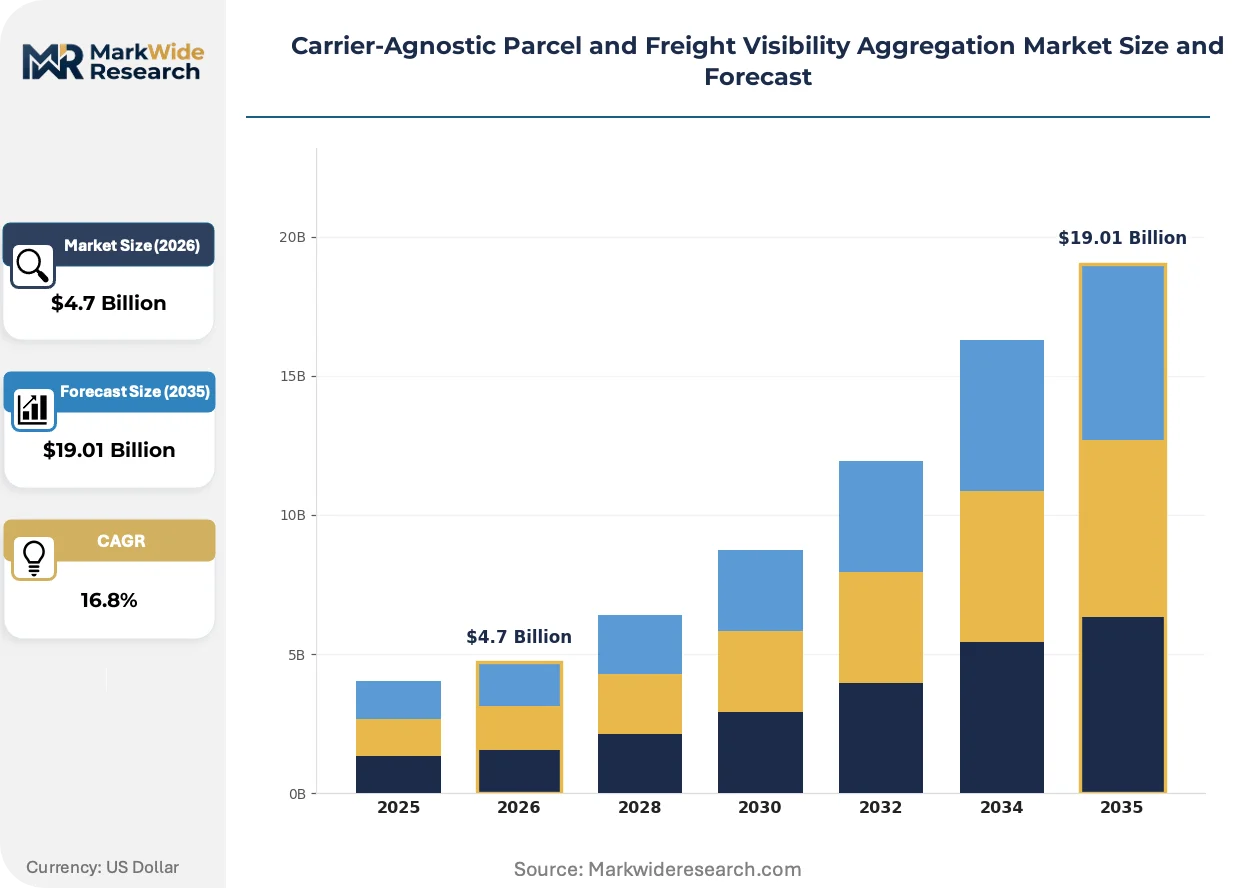
Market Dynamics
API-first integration architectures are compressing carrier onboarding cycles from months to weeks, forcing visibility platforms to prioritize data-normalization engines over proprietary network scale. This technical pivot rewards vendors with pre-built adapter libraries while penalizing those dependent on custom EDI mappings.
Growth Catalysts
- EU AI Act compliance layers:Automated routing decisions in European freight networks now require documented algorithmic transparency, stimulating demand for explainable ETA prediction modules that audit decision trails across carrier handoffs.
- Pharmaceutical cold-chain mandates:FDA traceability requirements under the Drug Supply Chain Security Act compel immutable chain-of-custody records, directly expanding exception-management deployments for temperature-sensitive pharmaceutical lanes.
- Automotive just-in-sequence networks:Tier-1 suppliers in Germany and Mexico are consolidating visibility spend around platforms that correlate inbound component ETAs with assembly-line takt times, compressing safety-stock buffers.
Market Restraints
- Telematics standard fragmentation:Incompatible data protocols across North American, European, and Asian carrier fleets force visibility vendors to maintain redundant parsing engines, elevating engineering overhead.
- Cloud concentration risk:Dominant hyperscaler infrastructure in the United States creates single-point-of-failure exposure for real-time tracking architectures with sub-five-minute latency requirements.
- Legacy TMS substitution:Deeply embedded enterprise transportation management systems in Fortune 500 shippers delay API-first visibility adoption through multi-year refresh cycles.
Strategic Opportunities
- India pharmaceutical export corridors:CDSCO-aligned cold-chain documentation requirements for EU-bound generics create first-mover openings for visibility platforms with integrated customs-brokerage modules.
- Autonomous trucking telematics convergence:Machine-vision and lidar telemetry streams from driverless pilot programs require new ingestion architectures that fuse traditional GPS with predictive hazard detection.
- Carbon-accounting regulatory tailwinds:EU Green Deal emissions-reporting mandates for freight transport stimulate demand for visibility layers that calculate CO2 per shipment across multimodal legs.
Industry Challenges
- API engineering talent scarcity:Shortages of developers experienced in carrier EDI-to-REST translation protocols delay platform roadmap execution and elevate compensation costs in competitive labor markets.
- Data-sovereignty compliance complexity:Pharmaceutical and defense verticals in Germany and Switzerland require hybrid deployment architectures that segment telemetry processing across jurisdictional boundaries.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market Trends and Innovations
Machine-learning inference at the network edge is displacing cloud-centralized ETA calculation, compressing prediction latency while exposing new attack surfaces for data integrity verification. This architectural migration reshapes vendor R&D priorities and customer procurement criteria simultaneously.
Digital twin simulations of multimodal freight networks are automating disruption-response protocols by ingesting real-time port congestion, weather, and driver-hours data to generate alternative routing recommendations without human intervention. Automotive manufacturers in Germany and Mexico are deploying these systems at scale to protect just-in-sequence assembly schedules. The technology is automating exception management previously staffed by control-tower analysts, compressing headcount in shipper logistics functions.
REACH chemical-transport documentation requirements in the European Union now mandate digital substance-tracking across carrier handoffs, compelling visibility platforms to integrate hazardous-material classification databases directly into shipment-state rendering. Chemical manufacturers operating Antwerp-Rotterdam corridor lanes are upgrading to platforms with embedded ECHA compliance modules. This regulatory layer elevates data-retention and audit-trail specifications above pure location-tracking functionality.
Shipper procurement of visibility services is consolidating around annual platform fees with usage-based tiers for predictive-analytics modules, displacing per-shipment transaction pricing that dominated early cloud adoption. Large retail and industrial enterprises in the United States are negotiating enterprise-wide licenses that bundle parcel, freight, and customs visibility. This contract-structure shift favors vendors with cross-modal data architectures over point-solution specialists.
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market Segmentation
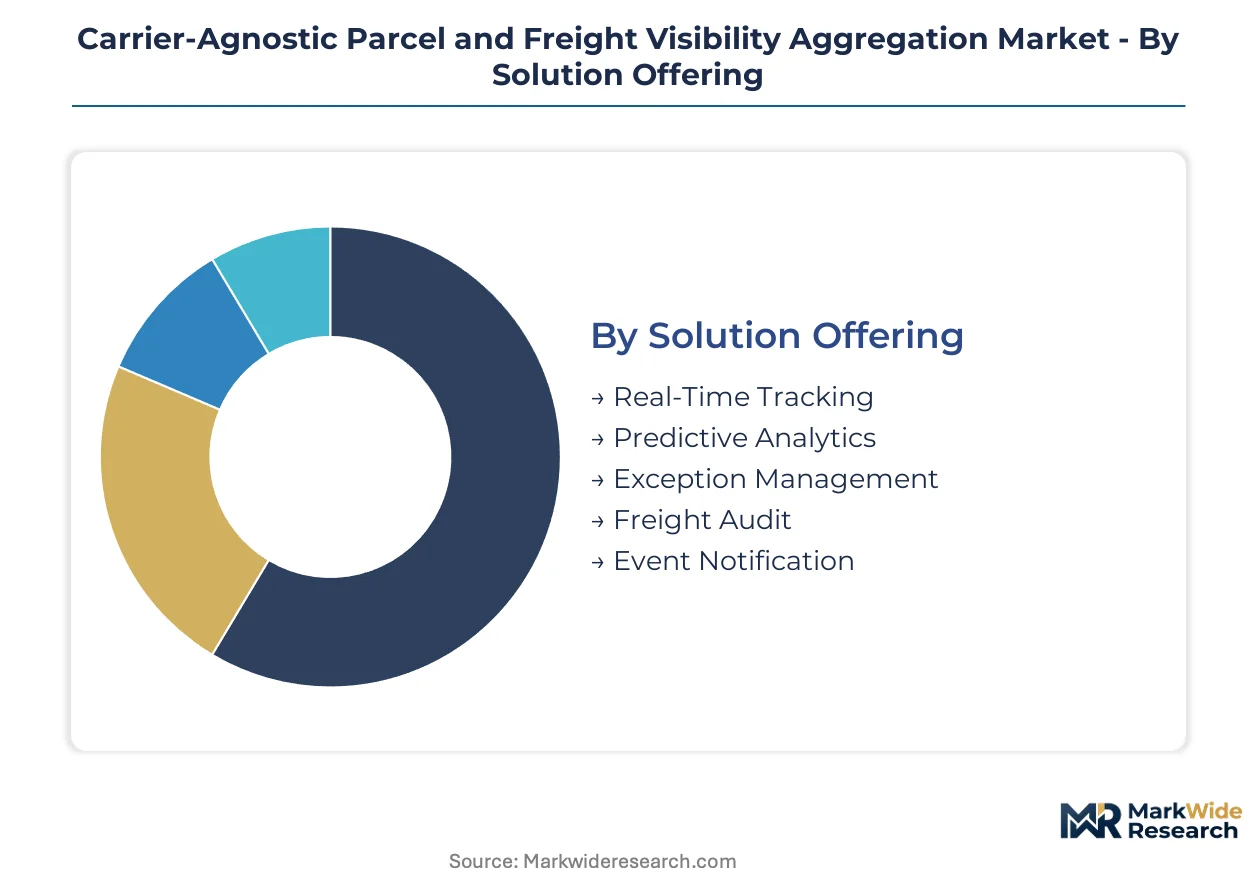
Segmentation in carrier-agnostic visibility aggregation reflects how procurement priorities diverge across technical maturity, compliance exposure, and operational scale. Shippers select solution architectures based on whether their primary pain point lies in latency reduction, predictive intelligence, or exception containment.
Solution Offering:
Supply concentration in this category tilts toward platforms that compress data-to-decision latency through normalized API ingestion rather than proprietary carrier networks.
- Real-Time Tracking:Telemetry normalization engines ingest GPS, temperature, and door-sensor streams at sub-five-minute intervals, rendering unified shipment state across multimodal handoffs. Pharmaceutical distributors in Germany anchor demand here, driven by FDA Drug Supply Chain Security Act chain-of-custody mandates that require immutable location records across carrier transfers.
- Predictive Analytics:Machine-learning models fuse weather patterns, port congestion indices, and driver-hours data to generate ETAs with confidence intervals. Tier-1 automotive suppliers in Mexico deploy these modules to correlate inbound component arrival with assembly-line takt times, compressing safety-stock buffers.
- Exception Management:Automated flagging systems trigger intervention protocols when telemetry breaches predefined thresholds for temperature, dwell time, or route deviation. Cold-chain pharmaceutical lanes drive adoption.
- Freight Audit:Invoice reconciliation engines match carrier billing against actual movement data captured through API telemetry. Retail distribution networks with high parcel volumes prioritize this capability.
- Event Notification:Configurable alert pipelines push shipment-state changes to downstream ERP and WMS systems via webhook or message queue architectures.
Today's leader: Real-Time Tracking. Tomorrow's challenger: Predictive Analytics.
Deployment Type:
Cost tier stratification separates hyperscaler-dependent architectures from sovereignty-compliant deployments that segment processing across jurisdictional boundaries.
- Cloud-Based:Multi-tenant SaaS architectures leverage hyperscaler infrastructure to achieve sub-five-minute latency at continental scale. North American retail and e-commerce shippers dominate consumption, though concentration risk around single-provider infrastructure creates resilience concerns for mission-critical pharmaceutical lanes.
- Hybrid:Edge-processing nodes handle telemetry normalization while audit trails and analytics reside in jurisdictional cloud instances. Swiss and German pharmaceutical manufacturers mandate this architecture to satisfy data-sovereignty requirements under national privacy frameworks and EU AI Act algorithmic-transparency rules.
- On-Premise:Dedicated hardware deployments within shipper or 3PL data centers retain full telemetry custody. Defense and classified-material logistics specify this model.
- SaaS:Subscription-based access to standardized visibility platforms with pre-built carrier adapter libraries. Mid-market shippers prioritize rapid onboarding over customization depth.
- Edge Computing:Inference engines deployed at sorting hubs or fleet gateways enable localized ETA calculation without round-trip cloud latency. Autonomous trucking pilot programs are testing this architecture for machine-vision telemetry fusion.
Cloud-Based deployments capture current volume leadership. Hybrid architectures are climbing the fastest as pharmaceutical and defense verticals harden sovereignty compliance.
Use Case:
Application-level segmentation maps directly to shipper organizational structure—procurement, operations, and customer experience teams each fund distinct visibility capabilities.
- Supply Chain Optimization:Inventory positioning algorithms ingest inbound shipment ETAs to trigger safety-stock releases and cross-dock routing. Automotive manufacturers in Germany deploy these systems to protect just-in-sequence assembly schedules.
- Last Mile Delivery:Parcel-specific tracking with customer-facing ETA windows and alternative delivery scheduling. E-commerce fulfillment networks anchor demand, particularly in urban corridors with high same-day delivery penetration.
- Inventory Management:Warehouse management system integration that converts shipment-state changes into receiving dock appointments and put-away priority signals.
- Reverse Logistics:Return merchandise authorization tracking with condition verification at carrier handoff points. Electronics and apparel retailers prioritize this capability.
- Carrier Performance Monitoring:Scorecarding engines that benchmark carrier ETAs against actuals, dwell times, and exception rates to inform procurement negotiations.
Supply Chain Optimization holds the revenue base. Last Mile Delivery represents the steepest expansion trajectory as e-commerce service-level agreements tighten.
End User Industry:
Customer-type segmentation reveals how visibility procurement authority concentrates with asset-light intermediaries versus asset-heavy principals.
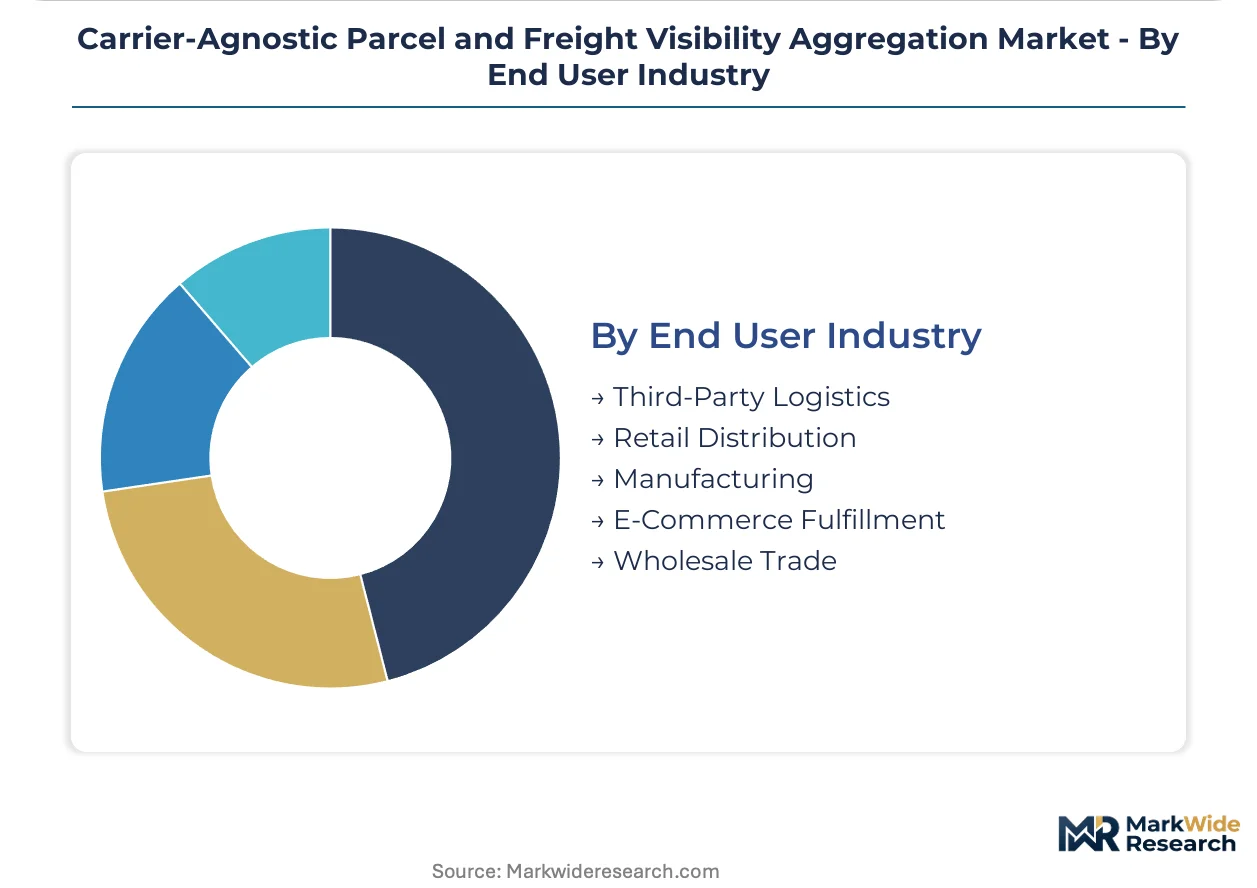
- Third-Party Logistics:3PLs aggregate visibility spend across multiple shipper clients, achieving carrier-adapter economies of scale that individual shippers cannot replicate. DHL Supply Chain and Kuehne+Nagel deploy white-labeled visibility layers across pharmaceutical and industrial verticals.
- E-Commerce Fulfillment:Direct-to-consumer retailers require parcel-level tracking with branded customer communication portals. Amazon's logistics arm and Shopify merchants drive API-first platform selection.
- Retail Distribution:Big-box and grocery chains coordinate inbound vendor-managed inventory with store-level replenishment timing.
- Manufacturing:Industrial producers track inbound raw materials and outbound finished goods through multimodal networks with customs-coupled visibility requirements.
- Wholesale Trade:Distributors serving fragmented customer bases prioritize freight audit and exception management over predictive capabilities.
Third-Party Logistics commands procurement volume today. E-Commerce Fulfillment is gaining share fastest as direct-to-consumer channel expansion accelerates visibility platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and pharmaceutical logistics clusters anchor carrier-agnostic visibility demand, with tier-1 suppliers and cold-chain distributors consolidating procurement around API-first platforms. The report traces adoption patterns across five strategic markets where regulatory pressure and industrial density converge.
United States
E-commerce fulfillment networks and pharmaceutical distributors drive platform consolidation. FDA Drug Supply Chain Security Act mandates compel immutable chain-of-custody documentation, directly stimulating exception-management deployments. Chicago and Memphis logistics corridors host dense carrier-agnostic visibility implementations protecting just-in-time retail replenishment.
Germany
Automotive just-in-sequence networks and REACH chemical-transport documentation requirements create dual demand vectors. EU AI Act algorithmic-transparency rules pressure vendors to document predictive ETA decision trails. The Stuttgart-Munich industrial belt concentrates platform adoption among tier-1 suppliers synchronizing inbound component flows with assembly takt times.
India
Pharmaceutical export corridors to the European Union generate first-mover openings for visibility platforms with integrated customs-brokerage modules. CDSCO-aligned cold-chain documentation requirements for EU-bound generics create compliance-critical infrastructure gaps. Mumbai-Pune and Hyderabad clusters witness accelerating procurement of carrier-agnostic layers as generic manufacturers harden export compliance.
Switzerland
Data-sovereignty requirements under national privacy frameworks and pharmaceutical confidentiality protocols mandate hybrid deployment architectures. Swissmedic regulatory expectations for temperature-sensitive biologics elevate audit-trail specifications. Basel and Zurich pharmaceutical manufacturers segment telemetry processing across jurisdictional boundaries to satisfy confidentiality mandates.
United Kingdom
Post-Brexit customs complexity and pharmaceutical re-export corridors stimulate demand for customs-coupled visibility. UK MHRA alignment with FDA traceability standards creates parallel compliance obligations. London and Midlands distribution networks deploy aggregation platforms to manage multimodal handoffs across Channel crossings and domestic last-mile legs.
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market Competitive Landscape
API-first integration partnerships dominate the current landscape as vendors compress carrier onboarding cycles from months to weeks. The market structure concentrates around three to five platforms with pre-built adapter libraries, while point-solution specialists face margin compression. Two strategic archetypes emerge: cloud-native visibility aggregators with normalized data engines, and legacy transportation management vendors extending through acquisition. M&A activity and geographic expansion through carrier adapter partnerships constitute the dominant competitive vectors.
Within the cloud-native tier, project44 and FourKites exemplify platforms that have anchored competitive position through API density rather than proprietary network scale. Descartes Systems Group occupies a distinct position coupling visibility with customs brokerage integration. These three entities represent how vendor selection increasingly favors data-normalization depth over carrier network exclusivity.
| Leading Market Players |
|---|
| project44 |
| FourKites |
| Descartes Systems Group |
| e2open |
| Shippeo |
| SAP |
| Transporeon |
| FarEye |
| Parcel Perform |
| Others |
Pricing and Supply Chain Analysis
API-first integration architectures are compressing carrier onboarding cycles while simultaneously fragmenting pricing power across vendor tiers. Cloud hyperscaler infrastructure costs and data-normalization engineering talent scarcity in Germany and the United States are reshaping both cost structures and supply concentration in multimodal visibility platforms.
Pricing Analysis
Input-cost pass-through from hyperscaler compute and API engineering talent scarcity is intensifying margin pressure at the mid-market tier. SaaS subscription models with usage-based tiers for predictive-analytics modules dominate, displacing per-shipment transaction pricing. Price differentiation hinges on API adapter library depth and EU AI Act compliance certification tier. Cost compression in the mid-market tier is intensifying because engineering overhead from telematics standard fragmentation cannot be fully passed through. Small and mid-market shippers exhibit highest price sensitivity; pharmaceutical distributors with FDA Drug Supply Chain Security Act mandates show lowest.
Supply Chain Analysis
Domestic-content mandates under the EU AI Act and German data-sovereignty frameworks are forcing telemetry processing localization within European jurisdictional boundaries. Engineering talent pools concentrate in Germany, the United States, and India. Raw material dependencies rest on hyperscaler cloud infrastructure, carrier EDI-to-REST translation protocols, and machine-learning inference hardware. Single-source vulnerability around dominant hyperscaler infrastructure in the United States creates resilience exposure for sub-five-minute latency architectures. Distribution runs through direct enterprise sales with annual platform fees, supplemented by 3PL white-label partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA Drug Supply Chain Security Act mandates and EU AI Act algorithmic-transparency rules generate irreversible infrastructure demand across pharmaceutical and automotive verticals.
For Market Incumbents: Extend API adapter library coverage into autonomous trucking telematics protocols before pilot programs scale. Deepen vertical integration into edge-computing hardware partnerships to reduce hyperscaler concentration risk. Fortify against emerging cloud-native entrants by embedding customs-brokerage modules directly into visibility platforms.
For New Entrants and Emerging Players: 3PL channel partners offer the lowest-friction path to carrier-adapter economies of scale without proprietary network buildout. White-space opportunity concentrates in India pharmaceutical export corridors where CDSCO-aligned cold-chain documentation requirements for EU-bound generics outpace platform supply. Target mid-market generic manufacturers in Mumbai-Pune and Hyderabad clusters with integrated customs-brokerage positioning.
For Investors and Strategic Acquirers: Roll-up economics work for API-first visibility aggregators because carrier-adapter library depth compounds defensibility faster than proprietary network scale. Five-to-ten-year viability hinges on predictive-analytics module attach rates expanding beyond real-time tracking commoditization. Acquisition target archetype: regional platforms with pre-built EDI-to-REST translation engines in underserved pharmaceutical corridors. Signal to watch: autonomous trucking pilot program telemetry standard convergence triggering architecture overhaul demand.
| Strategic Initiative | Industry Significance |
|---|---|
| API Adapter Library Expansion | Pre-built carrier integrations compress onboarding cycles from months to weeks for pharmaceutical distributors. |
| Edge Computing Architecture Deployment | Localized ETA calculation satisfies EU AI Act latency requirements for German automotive just-in-sequence networks. |
| Customs-Brokerage Module Integration | Descartes Systems Group's brokerage-to-tracking coupling creates regulatory compliance moats in European corridors. |
| Predictive Analytics Module Development | Machine-learning ETA engines with confidence intervals protect tier-1 automotive supplier inventory positioning. |
| Hybrid Deployment Architecture Rollout | Swiss and German pharmaceutical manufacturers segment telemetry processing to satisfy data-sovereignty mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics technology procurement officers, supply chain directors at pharmaceutical distributors, API engineering leads at visibility platforms, customs brokerage operations managers, and automotive tier-1 supplier logistics heads with secondary validation against SEC filings, EU regulatory databases, carrier EDI specification repositories, and hyperscaler infrastructure capex disclosures. Bottom-up carrier-adapter deployment tallies triangulated against top-down platform revenue segmentation.
Segment-weighting approaches distributed value across solution offering, deployment type, use case, and end-user industry dimensions, with additional granularity for regulatory compliance tier and API integration complexity. CAGRs derived from logistic curve fitting to adoption saturation patterns across the projection horizon, incorporating autonomous trucking pilot program telemetry standard evolution and EU AI Act implementation timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to telematics standard fragmentation resolution and hyperscaler infrastructure concentration events. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.