
 IoT Spend by Logistics Industry Market | 2026-2036
IoT Spend by Logistics Industry Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Spend by Logistics Industry Market Foresight
Cold chain logistics is hardening as the dominant end-use vertical, displacing generic freight tracking in capital allocation. Amazon Web Services leverages its cloud infrastructure to anchor data-intensive warehouse automation deployments for temperature-sensitive cargo. Intel Corporation sustains silicon leadership in edge-computing chipsets purpose-built for low-latency fleet telemetry. Cisco Systems dominates industrial networking hardware that connects distributed sensor arrays across multimodal transport nodes.
IoT spend by logistics industry encompasses connected hardware, communication protocols, data platforms, and analytics software that capture location, condition, and operational status across supply chain assets, typically operating on LPWAN, cellular, or satellite connectivity with sub-second latency thresholds for critical alerts. Its primary purpose is to replace reactive dispatch with predictive orchestration, reducing spoilage, detention, and empty-mile costs. Cloud computing now captures the largest share of technology budgets as logistics operators abandon on-premises data centers for elastic consumption models. Warehouse automation within the application layer is expanding fastest, driven by labor scarcity and throughput guarantees in e-commerce fulfillment. Third-party logistics providers remain the most concentrated end-user pool, though margin compression is pushing larger 3PLs toward hybrid deployment architectures that blend edge processing with centralized analytics.
The FCC governs spectrum allocation for fleet telematics in the United States, while the EU AI Act imposes risk-classification requirements on automated routing algorithms used in cross-border logistics. Germany's KBA enforces digital tachograph and remote-monitoring standards for commercial vehicles, directly mandating cellular-connected logging devices. Stakeholders must weigh regulatory fragmentation against platform consolidation as they select IoT architectures that can adapt to diverging compliance timelines without hardware replacement cycles.
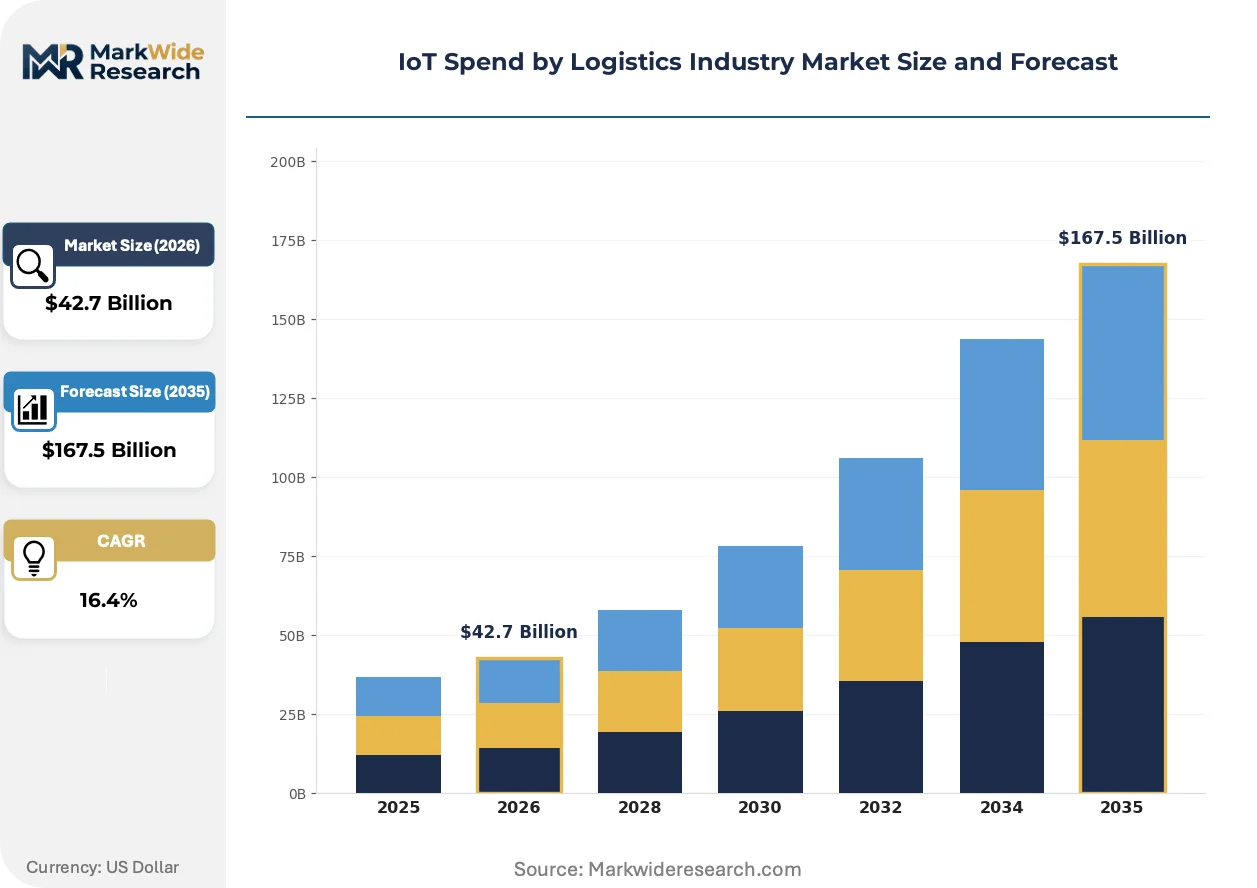
Market Dynamics
EU F-Gas Regulation mandates are compressing retrofit timelines for refrigerated fleets, forcing logistics operators to accelerate sensor deployment for real-time refrigerant leak detection and compliance documentation across cross-border routes.
Growth Catalysts
- California battery-electric truck mandates:Fleet operators must install telematics for state-monitored emissions tracking, expanding cellular-connected device penetration in heavy-duty transport.
- Cold chain pharmaceutical protocols:Temperature excursion alerts now require sub-30-second latency, driving edge-computing hardware procurement for vaccine and biologics distribution.
- LPWAN spectrum harmonization:Germany's KBA-aligned digital tachograph standards are creating procurement templates adopted by neighboring logistics clusters.
Market Restraints
- Silicon supply concentration:Edge-computing chipset fabrication relies on Taiwan-based foundry capacity, exposing fleet telematics hardware to geopolitical disruption risk.
- Cellular module cost volatility:NB-IoT and LTE-M radio components face lithium and rare earth price swings that compress hardware margins.
- Regulatory fragmentation:Divergent FCC spectrum allocation and EU AI Act risk classifications force multi-architecture engineering, inflating R&D overhead.
Strategic Opportunities
- India pharmaceutical cold chain:CDSCO temperature-monitoring mandates for export APIs remain underpenetrated by integrated IoT platforms, creating first-mover whitespace.
- Brazil last-mile electrification:ANVISA-aligned perishable delivery rules intersect with urban emission zones, opening combined sensor-charging infrastructure deployment.
- Warehouse robotics convergence:Integration of UWB positioning with automated guided vehicles enables real-time inventory-to-vehicle handoff tracking.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for low-power fleet telemetry competes with consumer electronics for constrained talent pools.
- Multi-protocol integration complexity:Legacy SCADA warehouse systems resist seamless handoff to cloud-native analytics platforms without middleware customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Spend by Logistics Industry Market |
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $167.5 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wireless Sensors, RFID, GPS Tracking, Cloud Computing Application: Supply Chain Management, Fleet Management, Warehouse Automation, Predictive Maintenance End User: Third-Party Logistics, E-Commerce, Freight Forwarders, Retail Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Intel Corporation, Amazon Web Services, Cisco Systems, IBM, Microsoft, Robert Bosch, Sierra Wireless, KORE Wireless, Twilio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Spend by Logistics Industry Market Shifts & Advancements
Digital twin architectures are collapsing the latency between physical asset condition and dispatch decision-making, compressing the traditional sense-analyze-act pipeline into continuous feedback loops.
Digital twin platforms are unifying sensor streams from refrigerated trailers, warehouse climate systems, and last-mile electric vehicles into single operational views. Pharmaceutical 3PLs in Germany and the Netherlands are deploying these systems for lane-risk scoring before cargo acceptance. This unification is collapsing the traditional separation between fleet management and warehouse energy optimization, forcing software vendors to merge historically distinct product lines.
EU AI Act risk-classification rules are mandating human-in-the-loop overrides for automated routing algorithms that handle temperature-sensitive cargo. Logistics operators must now document decision audit trails, inflating data storage requirements and reshaping cloud procurement specifications. Cross-border pharmaceutical lanes between Germany and Switzerland face the steepest compliance engineering costs.
Buyer procurement patterns are compressing vendor evaluation cycles from 18-month RFP processes to 90-day pilot-to-scale commitments. Large 3PLs now demand API-first platforms that slot into existing transportation management systems without custom integration. This acceleration is most visible in e-commerce fulfillment clusters around Rotterdam and Hamburg, where throughput guarantees override traditional security review depth.
IoT Spend by Logistics Industry Market Segmentation
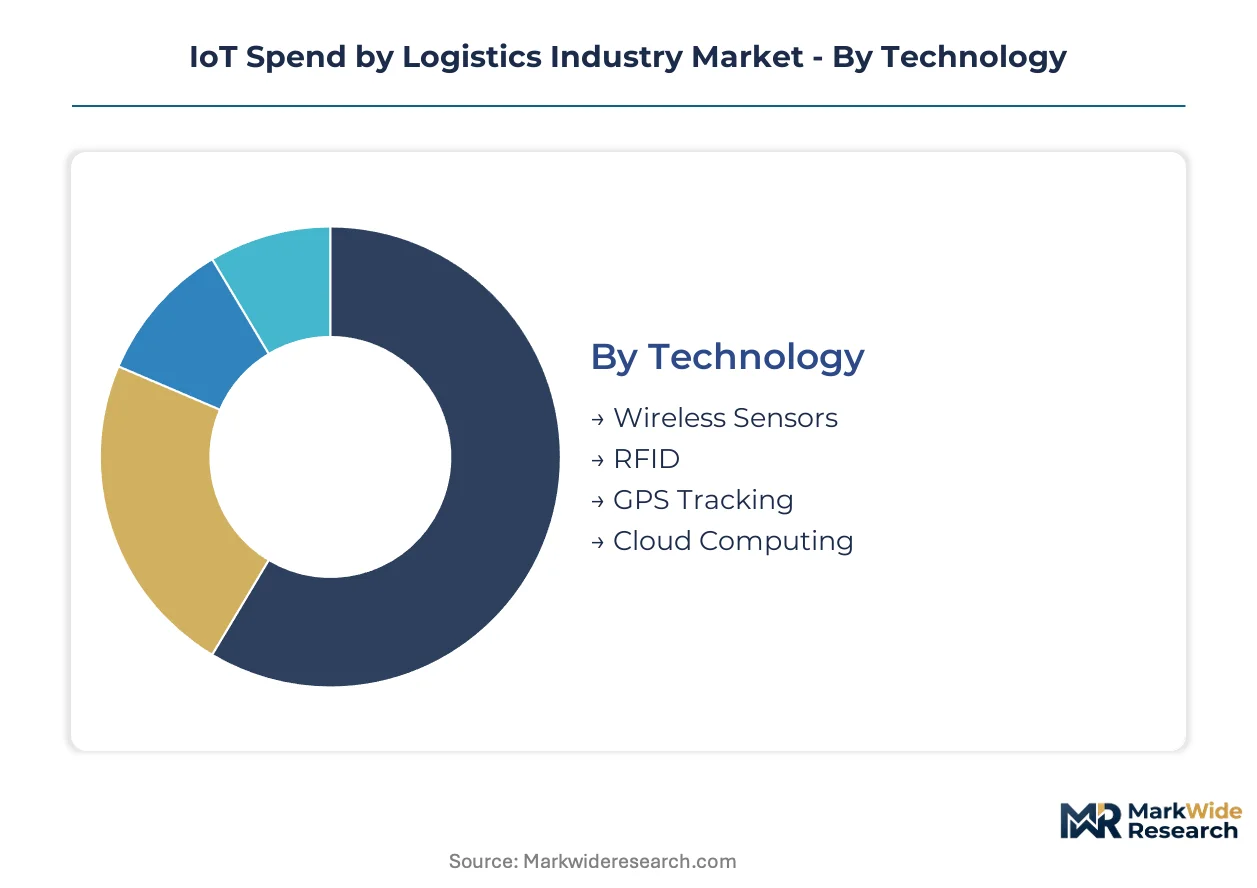
IoT spend by logistics industry fragments across four operational dimensions that determine compliance burden and integration complexity. Technology choices dictate sensor density requirements under EU F-Gas and California emissions mandates. Application priorities separate capital-intensive warehouse automation from fleet telematics with shorter replacement cycles.
Technology:
Certification requirements concentrate in wireless sensor and GPS tracking segments, where FCC Part 15 and CE marking govern radio frequency emissions across cross-border deployments.
- Wireless Sensors:Temperature, humidity, and shock-detection nodes operating on LPWAN protocols with sub-100mW power envelopes. Pharmaceutical 3PLs in Germany and the Netherlands are standardizing on LoRaWAN for refrigerated trailer compliance under EU Good Distribution Practice.
- RFID:Passive UHF and active battery-assisted tags for pallet-level identification in automated warehouse gates. E-commerce fulfillment centers in Hamburg and Rotterdam are retrofitting fixed-reader infrastructure to meet same-day delivery SLAs.
- GPS Tracking:Multi-constellation receivers combining GNSS with cellular triangulation for meter-level positioning in urban canyons. Fleet operators face KBA-mandated digital tachograph integration for cross-border EU routes.
- Cloud Computing:Elastic compute and storage services replacing on-premises data centers for analytics workloads. Third-party logistics providers favor consumption-based pricing to align costs with shipment volatility.
Cloud computing sits at the top of the volume ranking, with wireless sensors climbing the fastest.
Application:
Cost tier separation distinguishes high-touch warehouse automation from commoditized fleet tracking with compressed margins.
- Supply Chain Management:End-to-end visibility platforms integrating supplier portals, carrier APIs, and customer-facing track-and-trace. Retailers in Germany demand real-time inventory positioning across multi-modal handoffs.
- Fleet Management:Telematics for fuel consumption, driver behavior, and regulatory compliance documentation. California CARB mandates are forcing cellular-connected device upgrades for battery-electric truck monitoring.
- Warehouse Automation:Automated guided vehicles, robotic picking systems, and climate-controlled storage orchestration. Labor scarcity in e-commerce fulfillment is accelerating capital allocation to goods-to-person systems.
- Predictive Maintenance:Vibration and thermal monitoring for conveyor systems and refrigeration compressors. Cold chain operators use edge analytics to prevent cargo spoilage from equipment failure.
Warehouse automation commands the steepest expansion trajectory, while fleet management retains the largest installed base.
End User:
Customer type determines procurement sophistication, with third-party logistics providers demanding API-first platforms and retailers prioritizing turnkey integration.
- Third-Party Logistics:Asset-light operators managing contracted fleets and warehouse networks for multiple shippers. Margin compression is pushing larger 3PLs toward hybrid edge-cloud architectures to reduce data egress costs.
- E-Commerce:Direct-to-consumer retailers with same-day delivery promises requiring sub-hour inventory visibility. Urban last-mile electrification in Germany and California is converging charging infrastructure with telematics deployment.
- Freight Forwarders:Intermediaries coordinating ocean, air, and land legs without direct asset ownership. Digital container tracking adoption lags behind integrated logistics providers due to fragmented carrier data standards.
- Retail:Brick-and-mortar and omnichannel operators using IoT for loss prevention and replenishment automation. Grocery chains are prioritizing cold chain monitoring for prepared food categories under tightened FSSAI and FDA safety protocols.
Third-party logistics sits at the top of the volume ranking, with e-commerce climbing the fastest.
Deployment:
Maturity curves separate legacy on-premises installations from cloud-native architectures with faster feature iteration.
- On-Premises:Dedicated server infrastructure in logistics facilities with full data sovereignty control. Defense and pharmaceutical shippers in Germany retain on-site deployments for EU AI Act audit trail requirements.
- Cloud-Based:Fully managed SaaS platforms with automatic scaling and vendor-managed security patching. Mid-market 3PLs are abandoning owned data centers to redirect capital toward fleet expansion.
- Hybrid:Sensitive telemetry processed at the edge with aggregated analytics in centralized cloud repositories. This architecture satisfies both sub-30-second pharmaceutical alert latency and long-term trend analysis needs.
- Edge Computing:Micro-data centers and ruggedized gateways deployed in vehicles and remote warehouses. Battery-electric truck mandates in California and Germany require onboard processing for state-monitored emissions telemetry.
Cloud-based deployment sits at the top of the volume ranking, with edge computing climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing IoT deployment capital toward jurisdictions with harmonized compliance frameworks and subsidized edge infrastructure. Logistics operators migrate sensor procurement to countries where single certifications satisfy multi-market access, compressing total cost of ownership for cross-border fleet operators.
United States
California CARB mandates for battery-electric trucks are forcing cellular telematics upgrades across heavy-duty fleets, with the FCC governing spectrum allocation for cross-state operations. The Los Angeles-Long Beach port complex anchors the nation's densest concentration of refrigerated container tracking deployments, where 3PLs integrate emissions monitoring with warehouse automation procurement.
Germany
KBA-enforced digital tachograph standards are creating procurement templates adopted by neighboring logistics clusters, while EU F-Gas Regulation accelerates refrigerant leak-detection sensor density. Hamburg's port-adjacent warehousing districts drive edge-computing deployments for real-time pharmaceutical cargo handoffs to Rotterdam-connected corridors.
Netherlands
Rotterdam's automated container terminals demand sub-second latency for crane-to-truck coordination, pushing 3PLs toward hybrid cloud-edge architectures. The country's national pharmaceutical regulator aligns with EU Good Distribution Practice for temperature-monitoring mandates, concentrating IoT vendor activity in the Randstad logistics belt.
India
CDSCO temperature-monitoring mandates for export APIs remain underpenetrated by integrated platforms, creating whitespace for first-mover IoT providers. Maharashtra's Mumbai-Pune pharmaceutical corridor and Gujarat's Mundra port zone are emerging as pilot deployment zones for cold chain digitization.
Brazil
ANVISA-aligned perishable delivery rules intersect with São Paulo's urban emission zones, opening combined sensor-charging infrastructure for last-mile electrification. The country's national pharmaceutical regulator is tightening cold chain documentation requirements for vaccine distribution, driving telematics procurement in the Southeast region.
IoT Spend by Logistics Industry Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud infrastructure providers capturing the largest technology budgets while hardware vendors face margin compression from silicon cost volatility. The vendor base concentrates around three strategic archetypes: hyperscale cloud platforms anchoring data-intensive warehouse deployments, silicon specialists supplying edge-computing chipsets, and industrial networking firms connecting distributed sensor arrays. Competitive moves center on API-first platform consolidation and hybrid architecture partnerships that reduce data egress costs for margin-pressed 3PLs.
Within the cloud-platform tier, Amazon Web Services and Microsoft exemplify hyperscale providers anchoring elastic consumption models for logistics operators abandoning owned data centers. Intel Corporation occupies a position among silicon specialists supplying low-latency chipsets for fleet telemetry, while Cisco Systems represents industrial networking hardware vendors connecting multimodal transport nodes. These three companies illustrate how technology stack layering—cloud, silicon, connectivity—determines competitive positioning without vertical integration into adjacent tiers.
| Leading Market Players |
|---|
| Intel Corporation |
| Amazon Web Services |
| Cisco Systems |
| IBM |
| Microsoft |
| Robert Bosch |
| Sierra Wireless |
| KORE Wireless |
| Twilio |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up IoT hardware vendors exercise pricing discipline through portfolio-wide procurement leverage, compressing cellular module costs while passing silicon volatility risk to third-party logistics buyers through indexed SaaS contracts.
Pricing Analysis
Distributor margins in cellular-connected fleet hardware sit at 15-25 points above direct OEM channels, incentivizing large 3PLs to pursue volume-tiered SaaS commitments. Three-tier pricing structure across premium certification-grade, standard CE-marked, and economy unbundled sensor levels separates pharmaceutical cold chain operators from generic freight trackers. Cost compression in edge-computing gateways is intensifying because Taiwan foundry allocation constraints squeeze hardware margins. E-commerce fulfillment clusters in Germany and California exhibit lowest price sensitivity due to throughput guarantee penalties.
Supply Chain Analysis
Dual-sourcing requirements for NB-IoT and LTE-M cellular modules mandate qualification of at least two radio suppliers, forcing logistics operators to maintain redundant vendor relationships despite integration overhead. Taiwan, China, and South Korea anchor semiconductor fabrication for fleet telemetry chipsets. Raw material dependencies span lithium for battery-assisted RFID tags, rare earth elements for antenna substrates, and copper for gateway enclosures. Single-source vulnerability concentrates in Taiwan-based foundry capacity for low-latency edge processors. Distribution runs through industrial electronics distributors serving Hamburg and Rotterdam port-adjacent clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas and California CARB mandates generate recurring sensor replacement cycles independent of technology obsolescence.
For Market Incumbents: Extend platform consolidation into adjacent warehouse automation software, acquiring UWB positioning specialists before robotics vendors internalize tracking capabilities. Vertical integration into captive edge-computing chipset supply buffers Taiwan foundry disruption risk. Certification investment for EU AI Act audit-trail documentation captures pharmaceutical 3PL procurement budgets ahead of compliance deadlines. For New Entrants and Emerging Players: Enter via underpenetrated India pharmaceutical cold chain corridors where CDSCO temperature-monitoring mandates lack integrated platform coverage. Brazil last-mile electrification intersecting ANVISA perishable rules offers combined sensor-charging infrastructure deployment. API-first pilot programs with mid-market 3PLs bypass 18-month incumbent procurement cycles. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking edge-computing talent to reduce data egress costs for margin-pressed logistics customers. Acquisition targets with hybrid architecture deployment expertise and pharmaceutical regulatory compliance track records command premium positioning. Watch for KBA-aligned digital tachograph standard adoption spreading beyond Germany as inflection indicator for fleet telematics consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Edge-Cloud Architecture Deployment | Reduces data egress costs for 3PLs operating under Rotterdam-Hamburg corridor compliance requirements. |
| EU AI Act Audit-Trail Platform Certification | Captures pharmaceutical cold chain procurement budgets ahead of cross-border lane documentation mandates. |
| Cellular Module Dual-Source Qualification | Mitigates Taiwan foundry concentration risk for fleet telematics hardware under California CARB timelines. |
| API-First Transportation Management Integration | Compresses vendor evaluation cycles from 18-month RFP processes to 90-day pilot commitments for e-commerce 3PLs. |
| Digital Twin Platform Convergence | Unifies refrigerated trailer, warehouse climate, and last-mile EV sensor streams for pharmaceutical lane-risk scoring. |
Research Methodology
Coverage spans Germany, Netherlands, United States, India, and Brazil, with primary inputs from each logistics cluster combined with secondary validation. Interviews with fleet telematics procurement directors, warehouse automation engineers, pharmaceutical 3PL compliance officers, and cellular module sourcing managers informed demand-side assumptions. Secondary sources include KBA digital tachograph enforcement records, FCC Part 15 certification databases, EU F-Gas Regulation implementation guidance, and CDSCO export API monitoring mandates. Bottom-up sensor shipment data triangulates against top-down cloud infrastructure spending disclosed by hyperscale providers.
Granularity-level modeling distinguishes technology tier, application priority, end-user procurement sophistication, and deployment architecture maturity across the projection horizon. Segmentation dimensions include wireless sensor protocol type, warehouse automation system integration complexity, and pharmaceutical versus generic freight compliance burden. CAGRs derive from installed base replacement cycles under regulatory mandate compression and elasticity-adjusted adoption curves for edge-computing hardware. Forecast inputs incorporate silicon foundry capacity allocation schedules and LPWAN spectrum harmonization timelines.
Inputs from KBA enforcement records and FCC certification databases were available through the study window; gaps in India CDSCO implementation granularity introduce uncertainty bands for pharmaceutical cold chain penetration assumptions. Forecasts reflect documented assumptions regarding regulatory mandate acceleration and foundry capacity expansion. Deviation in Taiwan semiconductor export restrictions or EU AI Act enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
North America Automotive Logistics Market