
 India RTP Market | 2026-2036
India RTP Market Size, Share, and Industry Trends Forecast 2026-2036
India RTP Market Foresight
Project finance for payment infrastructure build-outs is fragmenting competitive dynamics in India's real-time payments landscape. National Payments Infrastructure Limited anchors UPI backbone operations across the country. Visa leverages its tokenization expertise to compete in secure credential provisioning. Mastercard sustains merchant acquiring relationships through its network of banking partnerships.
Real-time payments (RTP) in India constitute electronic fund transfers settled within seconds through the Unified Payments Interface protocol, operating on a 24x7 basis with transaction limits scaling from micro-payments to high-value corporate settlements. The system enables immediate fund availability between bank accounts, wallets, and merchant terminals without batch processing delays. Mobile wallet and QR code technologies dominate transaction volumes, with QR-based merchant acceptance expanding fastest across unorganized retail. Immediate payment types capture the bulk of retail flow, while standing instruction functionality for recurring bills and subscriptions represents an emerging margin pool in the corporate segment.
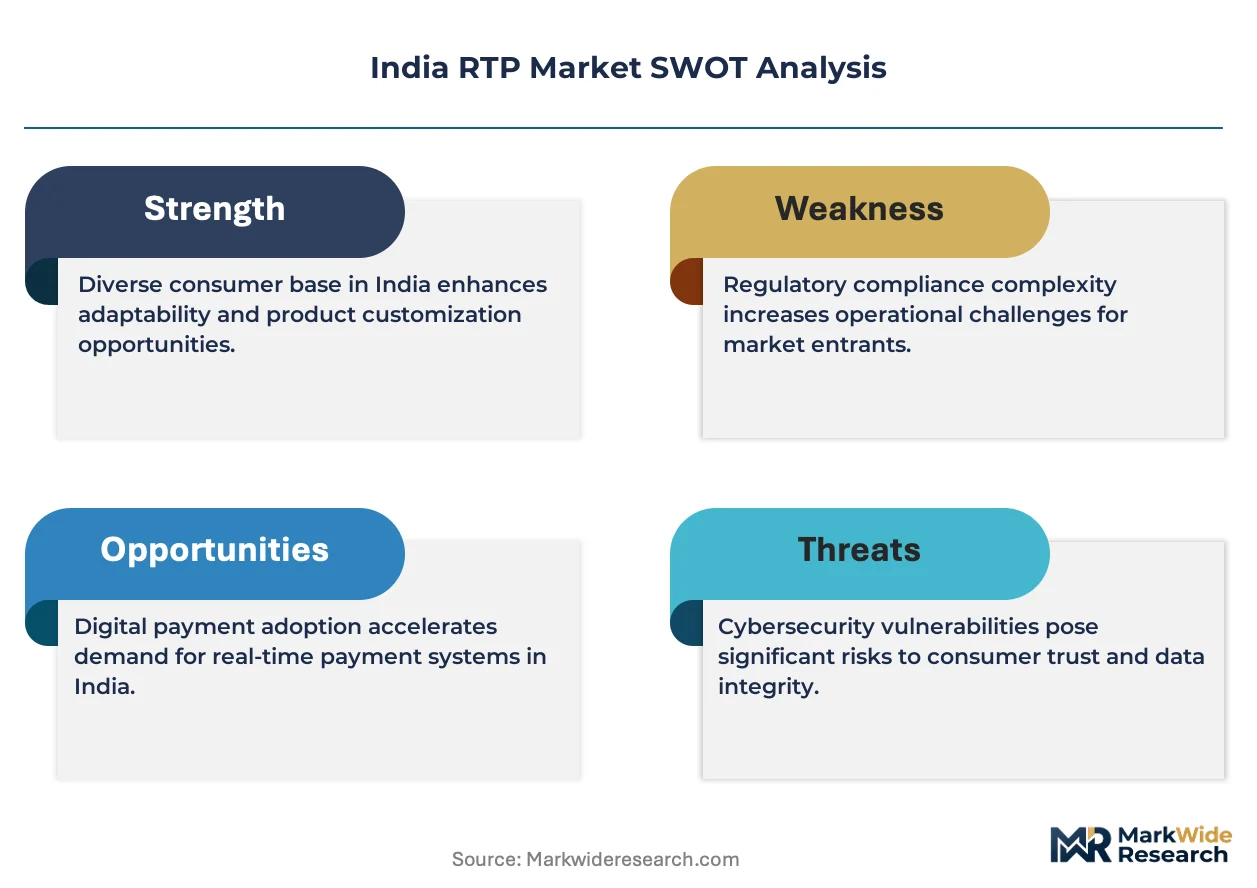
RBI's UPI regulatory framework, BIS payment system standards, and NPCI operating guidelines collectively shape product design, interoperability mandates, and participant eligibility in India's RTP ecosystem. RBI's tiered KYC requirements directly determine transaction limits and wallet functionality available to different user categories. Stakeholders must monitor how the central bank's evolving data localization directives and foreign payment provider caps reshape platform economics and partnership structures.
Market Dynamics
RBI's interoperability mandates are compressing platform differentiation and forcing payment providers to compete on execution speed rather than network exclusivity. This regulatory pressure is redistributing margin pools toward infrastructure operators and specialized credential security vendors.
Growth Catalysts
- UPI infrastructure mandates:RBI's real-time payment interoperability requirements compel banks and wallets to connect through standardized protocols, expanding addressable transaction volume across all licensed participants.
- QR code merchant acceptance:Unorganized retail in Maharashtra, Karnataka, and Tamil Nadu is adopting low-cost acceptance infrastructure, converting cash-dominant transactions into trackable digital flows.
- Small business digitization:Tier-2 and tier-3 city enterprises are migrating receivables and supplier payments onto RTP rails to accelerate working capital velocity.
Market Restraints
- Foreign provider participation caps:RBI's restrictions on international payment network ownership limit Mastercard and Visa to minority stakes in domestic operating entities, constraining capital deployment.
- Tiered KYC compliance costs:Progressive identity verification requirements impose operational overhead that scales disproportionately for wallet providers serving underbanked populations.
- Data localization infrastructure:Mandated domestic server deployment raises fixed costs for cloud-dependent payment architectures, compressing unit economics at lower transaction volumes.
Strategic Opportunities
- Standing instruction functionality:Corporate billing and subscription management represents underdeveloped RTP use cases with recurring revenue potential beyond immediate retail transfers.
- Tier-2 city merchant acquiring:Payment service providers can build density in Uttar Pradesh, Rajasthan, and Madhya Pradesh where QR penetration lags southern states.
- Tokenization services:NPCI's expanding credential security requirements create white space for specialized vendors to provision secure device binding and transaction authentication.
Industry Challenges
- 24x7 operational reliability:RBI's continuous settlement mandate requires infrastructure teams to maintain sub-second latency during maintenance windows and peak load spikes.
- Interoperable dispute resolution:Multi-party transaction reversals across competing wallet and bank platforms create reconciliation complexity that slows merchant fund availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India RTP Market |
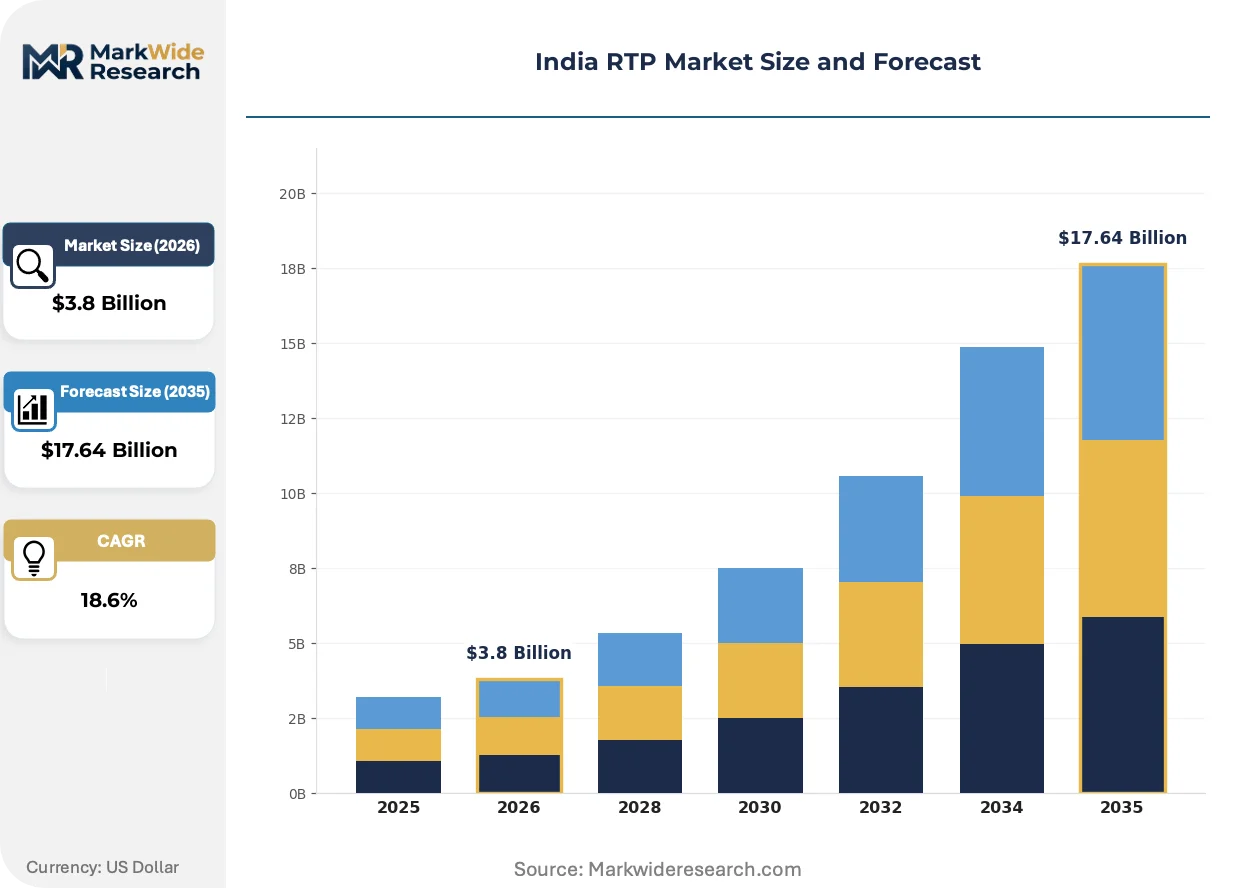
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Immediate Payment, Deferred Payment, Standing Instruction, Bulk Payment Technology: Mobile Wallet, USSD, QR Code, Contactless Payment End User: Retail Customers, Corporates, Small Businesses, NGOs Transaction Size: Micro Transactions, Low Value, Medium Value, High Value |
| Companies Covered | Visa, Mastercard, PayPal, National Payments Infrastructure Limited, Alipay, WeChat Pay, Square, Stripe, Adyen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India RTP Market Shifts & Advancements
Payment authentication architecture is fragmenting across multiple credential types, with behavioral biometrics and device binding displacing static PINs as primary trust anchors. This shift is compressing fraud windows while raising infrastructure requirements for real-time risk scoring.
Static OTP verification is migrating from dominant authentication method to fallback layer as device-bound cryptographic credentials gain regulatory preference. National Payments Corporation of India is mandating tokenized card-on-file and device fingerprinting for high-value transactions above prescribed thresholds. This migration from knowledge-based to possession-based authentication is narrowing the attack surface for credential phishing while concentrating implementation burden on issuer IT systems.
RBI's data localization directives are compelling payment providers to rearchitect cloud dependencies around domestic server infrastructure. Foreign platform operators must establish captive data centers or lease capacity from India-based hyperscale facilities, altering cost structures and vendor selection criteria. Fintechs with lean cloud-native stacks face the steepest reconfiguration timeline as they retrofit for sovereign data residency requirements.
Merchant acquisition is consolidating around integrated software vendors that embed payment acceptance into inventory and accounting workflows. Kirana stores in Gujarat and Telangana are selecting acquirers based on reconciliation dashboard quality rather than transaction pricing alone. This preference shift favors platforms with vertical software partnerships over pure-play payment networks lacking adjacent business tool integration.
India RTP Market Segmentation
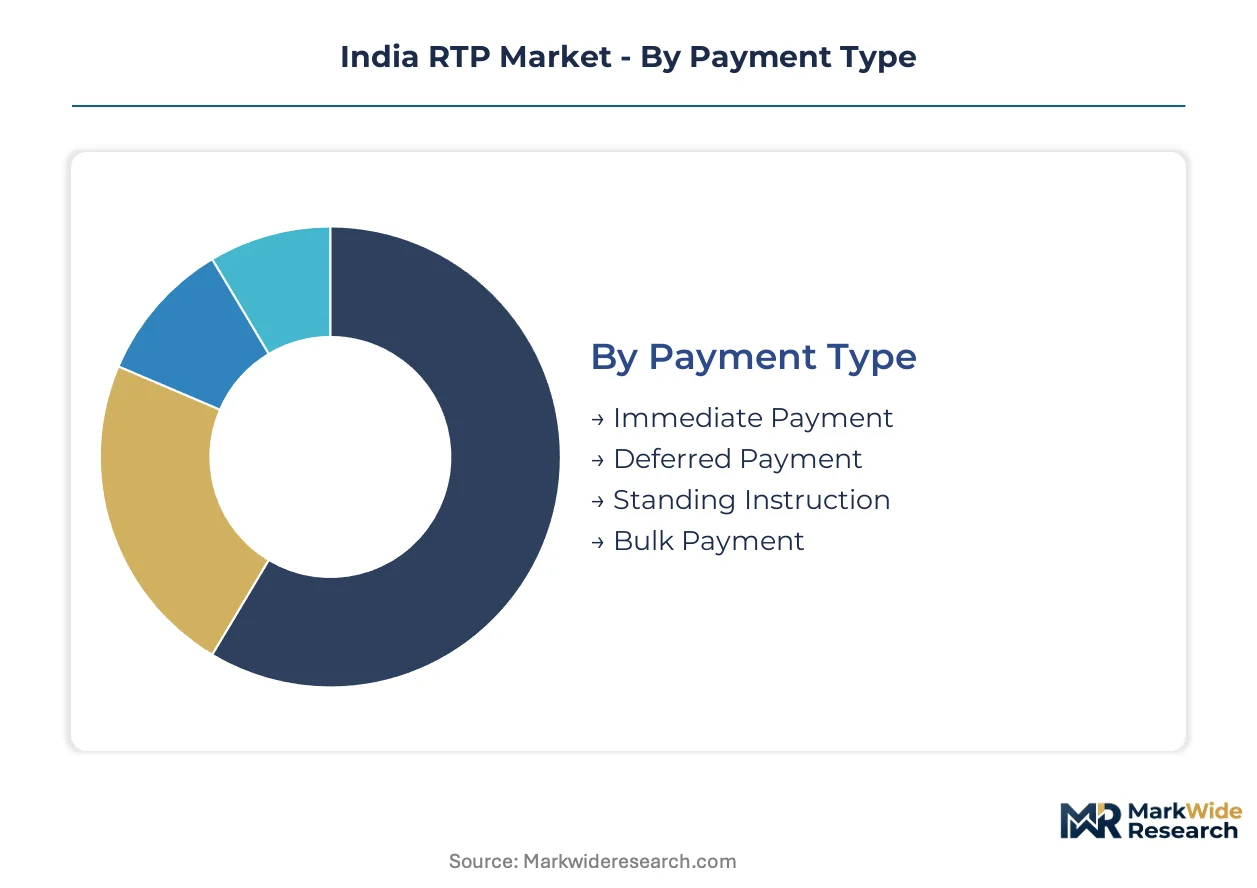
Segmentation in India's real-time payments market reveals how transaction purpose, interface technology, and user scale interact to determine platform economics. Payment providers must align infrastructure investments with the specific latency, security, and reconciliation requirements of each segment cluster.
Payment Type:
Application intent separates immediate settlement from scheduled or aggregated flows, with each variant imposing distinct technical architecture demands on NPCI's UPI backbone.
- Immediate Payment:Single-transaction settlement completes within seconds through UPI's core protocol, with sub-200ms latency requirements. Demand concentrates in Maharashtra and Karnataka retail corridors where merchant QR acceptance has converted cash-dominant street commerce into trackable digital rails.
- Standing Instruction:Recurring authorization frameworks enable automated bill settlements and subscription management without per-transaction user confirmation. Corporate billing departments in Tamil Nadu manufacturing clusters are adopting this functionality to reduce accounts payable processing overhead.
- Deferred Payment:Authorized holds with delayed settlement support escrow-like arrangements for e-commerce delivery confirmation.
- Bulk Payment:File-based multi-beneficiary disbursement handles salary credits and government benefit distribution through standardized NPCI file formats.
Immediate Payment holds installed capacity. Standing Instruction is rotating up the share rankings.
Technology:
Interface modality determines hardware requirements, authentication pathways, and merchant onboarding friction across India's heterogeneous device penetration landscape.
- QR Code:Static and dynamic quick-response codes enable smartphone-camera-based initiation without dedicated terminal hardware. Unorganized retail in tier-2 Gujarat and Telangana markets is adopting low-cost printed codes, converting kirana store cash flows into reconcilable digital entries.
- Mobile Wallet:Stored-value applications with tokenized credential management support both UPI-linked and closed-loop transaction architectures. Wallet providers face RBI's tiered KYC compliance burden that scales disproportionately for underbanked user acquisition.
- Contactless Payment:NFC-enabled tap-to-pay leverages device-bound secure elements for sub-50ms authentication.
- USSD:Unstructured supplementary service data enables feature-phone transaction initiation through telecom signaling channels.
QR Code dominates transaction volume velocity. Mobile Wallet is climbing the fastest among interface modalities.
End User:
Customer category shapes transaction frequency distribution, average ticket size, and the relative importance of reconciliation tooling versus consumer-facing interfaces.
- Small Businesses:Tier-2 and tier-3 city enterprises use RTP rails for supplier payments and receivables acceleration, with working capital velocity as the primary adoption driver. Uttar Pradesh and Rajasthan trading communities are migrating from cash-based hundi systems to traceable UPI settlements.
- Corporates:Treasury departments leverage bulk file formats and API integrations for payroll and vendor disbursement at scale. Manufacturing firms in Tamil Nadu automotive clusters demand standing instruction functionality for recurring utility and lease obligations.
- Retail Customers:Individual users drive volume through peer-to-peer transfers and merchant payments.
- NGOs:Non-profit disbursement requirements prioritize beneficiary identification and audit trail completeness.
Small Businesses anchor transaction growth momentum. Corporates are gaining share in value-weighted flow metrics.
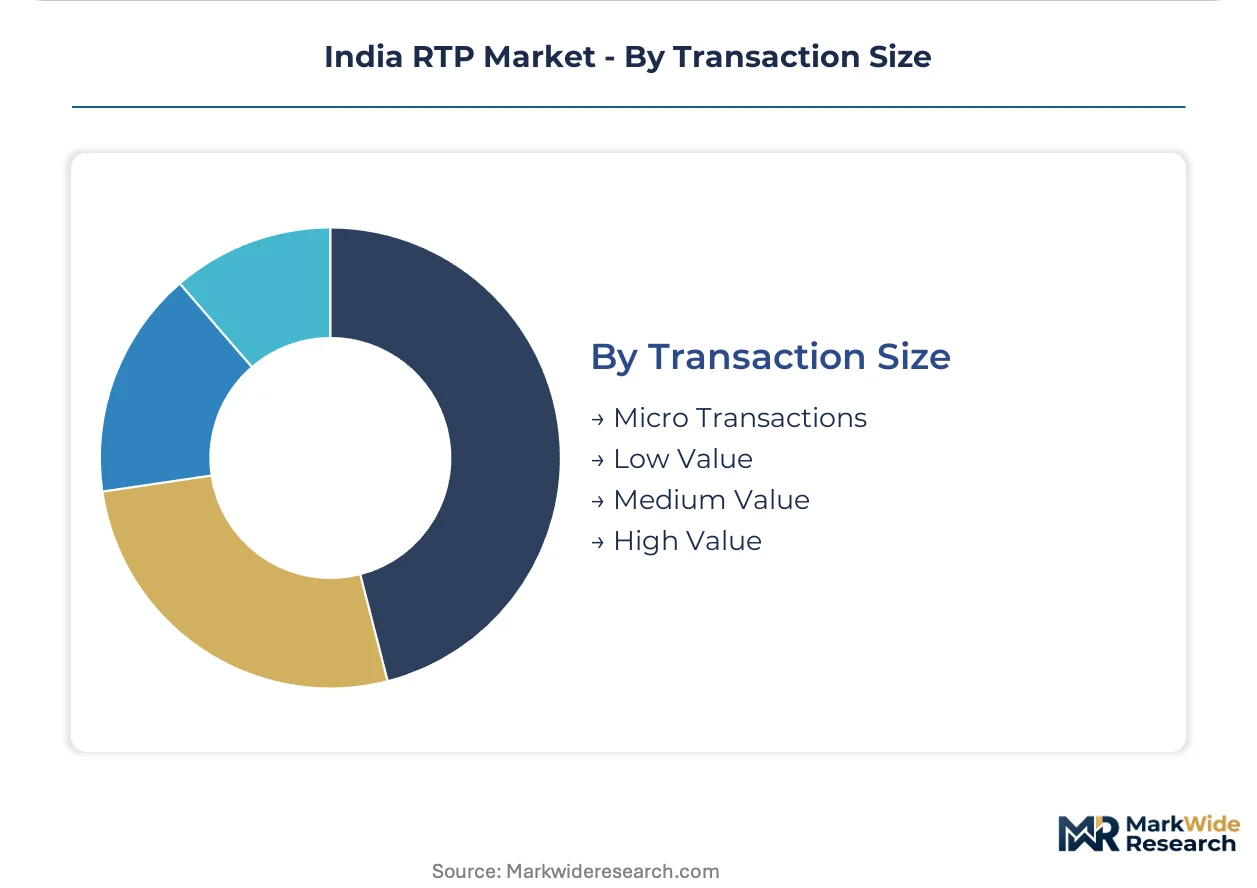
Transaction Size:
Value tiering determines authentication rigor, regulatory reporting thresholds, and the applicable NPCI risk management protocols for each settlement band.
- Micro Transactions:Sub-rupee payments support transit fares and vending applications through simplified PIN or biometric confirmation. Urban transit authorities in Bengaluru and Mumbai are deploying closed-loop micro-payment corridors for metro and bus fare collection.
- High Value:Corporate settlements above prescribed thresholds mandate device binding, tokenized credentials, and real-time fraud scoring per RBI's evolving authentication directives.
- Low Value:Everyday retail purchases fall within standard UPI limits with streamlined confirmation.
- Medium Value:Mid-tier B2B and premium retail transactions trigger graduated security protocols.
Micro Transactions command volume density. High Value is expanding most quickly in average ticket trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's real-time payments infrastructure generates substantial domestic transaction value while foreign provider participation remains constrained by regulatory caps. The market exhibits pronounced regional concentration in western and southern states where digital payment penetration has achieved critical mass.
Maharashtra
Mumbai's financial district and Pune's manufacturing belt drive corporate RTP adoption for treasury operations and vendor settlements. RBI's UPI infrastructure mandates require all licensed banks to maintain interoperable connectivity through NPCI protocols. The Mumbai-Pune corridor hosts dense QR code merchant acceptance networks converting street commerce into digital rails.
Karnataka
Bengaluru's technology ecosystem generates high-velocity peer-to-peer and merchant payment volumes across startup and gig economy workforces. The state's progressive digital infrastructure policies align with RBI's tiered KYC framework enabling graduated wallet functionality. Whitefield and Electronic City clusters demonstrate concentrated fintech platform deployment for salary disbursements and supplier payments.
Tamil Nadu
Coimbatore's automotive component manufacturers and Chennai's port-linked trading communities utilize standing instruction functionality for recurring utility and lease obligations. BIS payment system standards govern technical architecture for industrial zone payment terminals. Sriperumbudur's electronics manufacturing cluster shows accelerating corporate bulk payment adoption for payroll and contractor settlements.
Gujarat
Surat's diamond trading networks and Ahmedabad's textile markets are migrating from cash-based hundi systems to traceable UPI settlements for working capital efficiency. RBI's data localization directives compel payment providers to maintain domestic server infrastructure for transaction processing. The Gujarat International Finance Tec-City anchors institutional payment infrastructure development for cross-border trade facilitation.
Telangana
Hyderabad's pharmaceutical and IT services sectors demand integrated payment acceptance embedded into enterprise resource planning workflows. NPCI operating guidelines shape product design for API-integrated corporate disbursement platforms. The HITEC City corridor exhibits dense merchant acquiring concentration where kirana stores select providers based on reconciliation dashboard capabilities.
India RTP Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in credential security and tokenization layers. The competitive structure consolidates around infrastructure operators with regulatory mandates, while foreign networks compete through minority-stake domestic entities and technology licensing arrangements. Three archetypes dominate: UPI backbone operators anchoring interoperability, international card networks leveraging tokenization expertise, and wallet providers scaling tier-2 merchant acquisition. Competitive intensity concentrates on execution speed and API integration depth rather than network exclusivity.
Among international payment networks, Visa and Mastercard occupy positions shaped by RBI's foreign ownership restrictions, competing through secure credential provisioning and banking partnership architectures. National Payments Infrastructure Limited anchors the domestic infrastructure tier as the mandated UPI backbone operator. Within the wallet and merchant acquiring segment, PayPal represents the cross-border specialist archetype navigating data localization requirements.
| Leading Market Players |
|---|
| Visa |
| Mastercard |
| PayPal |
| National Payments Infrastructure Limited |
| Alipay |
| WeChat Pay |
| Square |
| Stripe |
| Adyen |
| Others |
Supply & Pricing Matrix
RBI's data localization mandates function as a regulatory chokepoint that simultaneously widens pricing tier spreads between domestic-hosted and cloud-dependent providers while forcing supply chain reconfiguration toward India-based server infrastructure. This structural constraint compresses margins for fintechs with lean cloud-native stacks while concentrating pricing power among hyperscale facilities with captive data center capacity.
Pricing Analysis
Industrial OEM buyers anchor transaction-based pricing structures across India's RTP landscape, with merchant acquirers charging basis-point spreads on settlement value rather than fixed subscription fees. Price differentiation hinges on API integration depth and reconciliation dashboard sophistication, with integrated software vendors commanding premium positioning over pure-play payment networks. Cost compression in the wallet-provider tier is intensifying because RBI's tiered KYC requirements impose disproportionate operational overhead for underbanked user acquisition. Small businesses in tier-2 cities exhibit highest price sensitivity, selecting providers primarily on transaction pricing, while corporate treasury departments prioritize reconciliation tooling over marginal rate differences.
Supply Chain Analysis
Extended payment terms from NPCI to participating banks create supply-chain finance dependencies that ripple through downstream wallet and merchant-acquiring relationships. Infrastructure hardware draws from Taiwan, South Korea, and domestic India-based assembly facilities for server and networking equipment. Critical component dependencies include cryptographic security modules, domestic cloud compute capacity, and telecom signaling infrastructure. Single-source vulnerability concentrates in NPCI's monopoly over UPI protocol governance and settlement finality. Distribution runs through banking partnerships that embed payment acceptance into enterprise software workflows rather than direct merchant relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across India's RTP ecosystem creates viable entry niches as RBI's interoperability mandates compress platform differentiation and redistribute margin pools toward specialized infrastructure operators.
For Market Incumbents: Insulate core banking partnerships through deeper API integration and exclusive reconciliation tooling development before foreign networks escalate technology licensing arrangements. Secure captive data center capacity in Mumbai and Bengaluru hyperscale facilities to preempt supply constraints from RBI's evolving data localization directives. Vertical integration into tokenization services addresses NPCI's expanding credential security requirements. For New Entrants and Emerging Players: Tier-2 merchant acquiring in Uttar Pradesh, Rajasthan, and Madhya Pradesh represents the most penetrable entry point, with QR penetration lagging southern states by substantial margins. Standing instruction functionality for corporate billing and subscription management offers underdeveloped use cases with recurring revenue potential beyond immediate retail transfers. A go-to-market angle anchored to vertical software partnerships—embedding payment acceptance into inventory and accounting workflows—circumvents direct price competition with established acquirers. For Investors and Strategic Acquirers: Specialized credential security vendors with device-binding and tokenization capabilities present the highest-probability acquisition targets as NPCI mandates displace static OTP verification. Long-term viability over the next decade hinges on regulatory alignment with RBI's evolving authentication directives and data residency requirements. The signal to watch is foreign provider participation cap adjustments, which would reshape capital deployment trajectories for international payment networks currently restricted to minority domestic stakes.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Buildout | Captive server infrastructure satisfies RBI localization mandates while compressing unit economics for cloud-dependent competitors. |
| API Integration Partnership | Deep ERP embedding converts merchant-acquiring relationships into sticky software dependencies with switching costs. |
| Tokenization Service Launch | Device-bound cryptographic credentials address NPCI's regulatory preference while narrowing phishing attack surfaces. |
| Tier-2 City Merchant Acquisition | QR density buildout in lagging states captures working capital digitization demand from trading communities. |
| Standing Instruction Platform Development | Recurring authorization frameworks unlock corporate billing margins beyond immediate retail settlement flows. |
Research Methodology
A standing panel of payment platform CTOs, NPCI operations directors, merchant-acquiring sales heads, and corporate treasury managers at manufacturing firms provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation through RBI circulars, NPCI operating guidelines, BIS payment system standards, and SEC filings from listed international payment networks. Bottom-up transaction volume modeling triangulated against top-down addressable market sizing across payment type, technology interface, and end-user segments.
Scenario-bracketing around regulatory implementation timelines and foreign participation cap adjustments framed the analytical approach across the projection horizon. Segmentation dimensions modeled include payment type, interface technology, end-user category, transaction size tier, and regional adoption cluster. CAGRs derived from logistic diffusion curves fitted to historical UPI volume trajectories, with inputs from mobile device penetration forecasts and merchant digitization rates in tier-2 and tier-3 cities.
Practitioners should monitor RBI circulars on authentication thresholds and data localization scope for early signals of forecast revision triggers. The analysis reflects assumptions about regulatory continuity and infrastructure reliability that macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Digital Transfer Services Market
Payments
LAMEA Payment Gateway Market
Payments
Saudi Arabia POS Terminal Market
Payments
Global Real-Time Payments Market
Payments
Poland Payments Market
Payments
United Kingdom Payment Market
Payments
Payment Security Market
Payments
Kenya Mobile Money Market
Payments
India POS Terminals Market
Payments
Proximity Payment Market
Payments
Russia Payments Market
Payments
Taiwan Mobile Payments Market
Payments
Mobile Money Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Payment Processing Solutions Market
Payments
Israel Credit Cards Market