
 France Big Data Analytics in Energy Market | 2026-2036
France Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
France Big Data Analytics in Energy Market Insights
The gap between premium predictive analytics suites and commodity visualization dashboards is hardening in the French energy sector. Siemens Aktiengesellschaft leverages its digital twin expertise to dominate high-margin utility transformation projects. Schneider Electric SE anchors its position through deep integration with France's distribution network infrastructure. Microsoft Corporation competes by extending cloud-native AI tools that reduce deployment friction for mid-sized renewable operators.
France Big Data Analytics in Energy encompasses the computational processing of massive, heterogeneous datasets generated across generation, transmission, and consumption nodes to extract actionable intelligence for operational optimization and strategic planning. Core technical specifications include real-time stream processing architectures handling terabyte-scale SCADA feeds, machine learning pipelines for anomaly detection in grid frequency data, and geospatial analytics layers mapping renewable intermittency patterns against demand clusters. Predictive Analytics leads current revenue contribution as French utilities prioritize asset failure prevention over reactive maintenance scheduling. Cloud-Based deployment is expanding fastest among independent power producers seeking elastic compute capacity without capital-intensive infrastructure commitments. Visualization Tools remain a mature margin pool where standardized dashboards face commoditization pressure from open-source alternatives.
France's energy data ecosystem operates under CNIL oversight for consumer privacy protection, EU Green Deal disclosure mandates for carbon accounting transparency, and CRE grid code requirements for real-time operational data standards. These frameworks compel vendors to embed audit trails and interoperability protocols directly into platform architectures. Stakeholders must monitor how upcoming EU AI Act risk classifications affect automated decision systems in load dispatching and demand response orchestration.
Market Dynamics
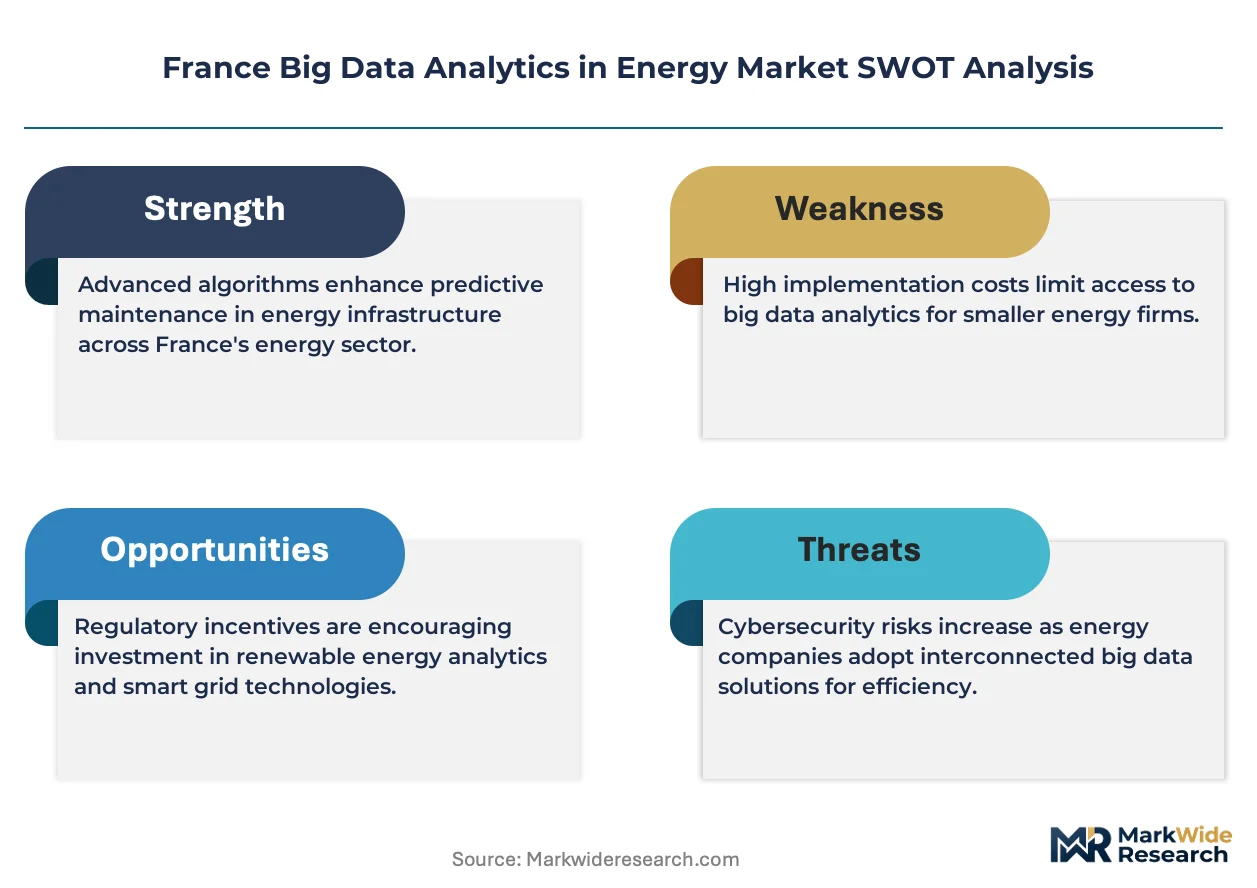
French grid operators face mounting pressure to reconcile real-time operational transparency with CNIL-mandated consumer data protection, forcing vendors to engineer privacy-preserving analytics architectures from the ground up.
Growth Catalysts
- EU Green Deal disclosure mandates:Carbon accounting transparency requirements compel electricity distributors to deploy granular emissions tracking systems across generation and transmission nodes.
- Paris-Saclay cluster concentration:Energy startups co-locating with EDF and Enedis research facilities accelerate proof-of-concept cycles for predictive maintenance algorithms.
- Predictive Analytics adoption:French utilities prioritize asset failure prevention platforms over reactive scheduling, driving demand for machine learning pipelines processing SCADA telemetry.
Market Restraints
- Cloud infrastructure cost volatility:Independent power producers face unpredictable compute pricing for elastic AI training workloads, constraining mid-tier operator participation.
- CNIL compliance friction:Strict audit trail requirements for consumer energy data extend platform development timelines and inflate architectural complexity.
- Open-source visualization commoditization:Standardized dashboard tools face displacement from free alternatives, compressing margins in mature software tiers.
Strategic Opportunities
- Occitanie renewable corridor:Solar and wind expansion in southern France creates demand for geospatial intermittency mapping against industrial demand clusters.
- EU AI Act risk classification:Upcoming automated decision system rules for load dispatching create first-mover advantage for vendors embedding explainable AI protocols.
- Digital twin convergence:Integration of physics-based simulation with operational data streams enables high-margin utility transformation projects.
Industry Challenges
- SCADA-ML pipeline engineering:Shortage of specialists capable of bridging industrial control protocols with modern stream processing architectures delays deployment timelines.
- Legacy system interoperability:Decades-old grid management software requires costly middleware development to interface with cloud-native analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Big Data Analytics in Energy Market |
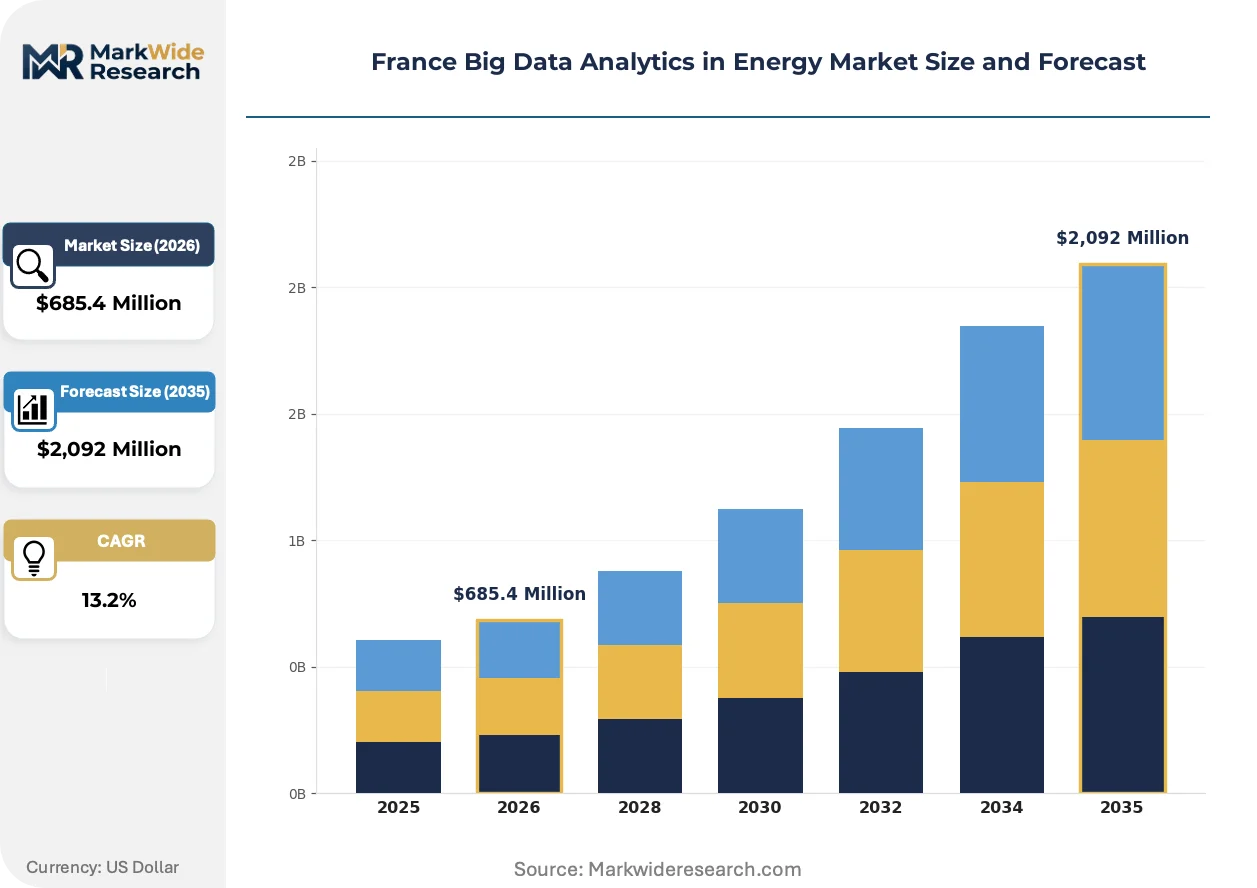
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,092 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics, Data Mining, Visualization Tools, Data Integration Application: Energy Management, Predictive Maintenance, Load Forecasting, Demand Response End User: Utility Companies, Industrial Sector, Renewable Energy Providers, Petroleum Industry Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Siemens Aktiengesellschaft, Schneider Electric SE, Microsoft Corporation, SAP SE, International Business Machines Corporation, General Electric Company, ABB Group, Accenture plc, Orange Business Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Big Data Analytics in Energy Market Trends and Innovations
Edge-to-cloud federated learning architectures are reshaping how French energy operators balance computational intensity with data sovereignty requirements, compressing the traditional centralized analytics model.
Federated analytics platforms are unifying localized model training at substation level with centralized aggregation, preserving raw data locality. Regional distribution cooperatives in Brittany and Normandy are piloting these deployments ahead of national rollouts. This architecture is unifying previously siloed operational technology and information technology budgets under single capital programs.
France's transposition of EU AI Act risk tiers into CRE grid code amendments will mandate human-in-the-loop protocols for automated dispatch decisions. Vendors must redesign inference pipelines to embed audit trails and override mechanisms. High-frequency trading desks at power exchanges face the steepest compliance retrofit requirements.
Buyer consolidation among independent power producers is compressing vendor sales cycles and elevating procurement sophistication. Mid-sized renewable operators now demand API-first platforms with usage-based pricing rather than perpetual licenses. This pattern concentrates in the Grand Est region where biogas cooperatives have formed collective purchasing consortia.
France Big Data Analytics in Energy Market Segmentation
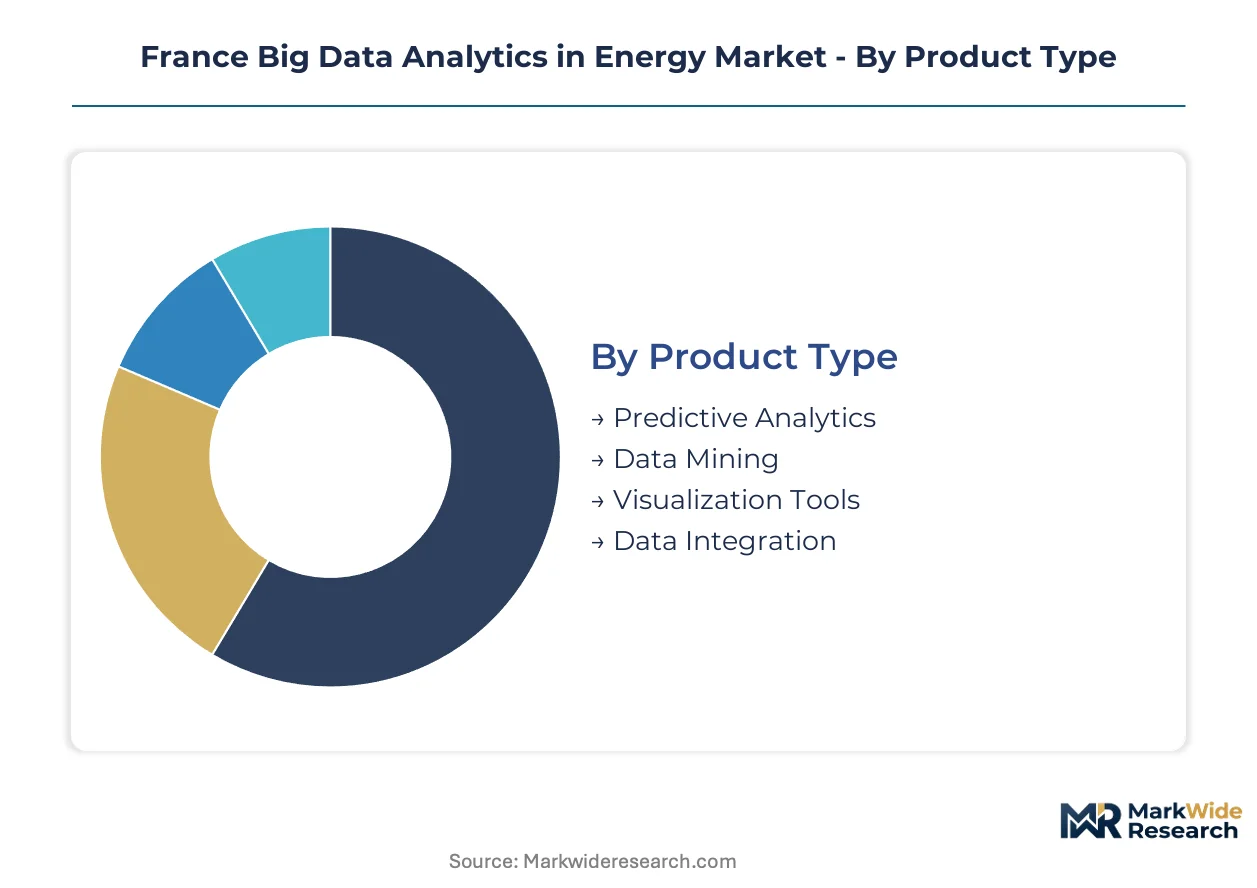
Segmentation in the French energy analytics market reveals how capital allocation, regulatory exposure, and infrastructure maturity shape purchasing behavior across distinct buyer archetypes. Understanding these fault lines helps vendors calibrate pricing architecture and deployment support.
Product Type:
Capital-intensity varies sharply across product tiers, with platforms requiring dedicated ML engineering teams commanding the highest upfront investment.
- Predictive Analytics:Machine learning pipelines processing SCADA telemetry for asset failure prevention. EDF and Enedis prioritize these platforms for nuclear and distribution infrastructure, driven by EU Green Deal maintenance transparency mandates.
- Data Mining:Pattern extraction algorithms identifying consumption anomalies and fraud detection signatures. Demand concentrates among regional distribution cooperatives in Brittany seeking to optimize grid balancing costs.
- Visualization Tools:Standardized dashboard layers for operational KPI monitoring. Open-source alternatives from Grafana and Apache Superset compress margins in this mature tier.
- Data Integration:Middleware architectures bridging legacy SCADA with cloud-native analytics stacks. Petroleum operators in the Paris Basin require these for refinery digitalization projects.
Most installed capacity flows through Predictive Analytics. Expansion is steepest in Data Integration.
Application:
Application selection tracks the operational maturity of French energy operators, with sophisticated buyers clustering around forward-looking use cases.
- Energy Management:Real-time optimization of generation dispatch and consumption scheduling. Industrial clusters in Dunkirk and Fos-sur-Mer deploy these systems to manage exposure to CRE tariff structures.
- Predictive Maintenance:Algorithmic forecasting of equipment degradation trajectories. Nuclear operators under ASN oversight invest here to demonstrate proactive safety management.
- Load Forecasting:Statistical models projecting demand patterns against weather and economic indicators. Grid operators in the Occitanie renewable corridor need these for solar intermittency absorption.
- Demand Response:Automated orchestration of flexible consumption during peak pricing events. Biogas cooperatives in Grand Est use these platforms for collective purchasing leverage.
Energy Management captures the largest deployment base. Demand Response is climbing the fastest as aggregator business models mature.
End User:
End user type determines procurement sophistication, with regulated incumbents favoring perpetual licenses and emerging players seeking usage-based structures.
- Utility Companies:EDF, Enedis, and RTE drive standard-setting for interoperability protocols. These buyers embed CNIL audit requirements directly into RFP specifications.
- Industrial Sector:Energy-intensive manufacturers in chemicals and metallurgy. Sites in the Hauts-de-France region prioritize demand response to manage exposure to capacity market charges.
- Renewable Energy Providers:Independent solar and wind operators. Paris-Saclay cluster startups favor cloud-native platforms with elastic compute pricing.
- Petroleum Industry:Refinery operators and downstream logistics players. These buyers lag in adoption due to legacy DCS infrastructure and capital allocation priorities.
Utility Companies anchor current revenue. Renewable Energy Providers are gaining share fastest amid biogas and offshore wind buildouts.
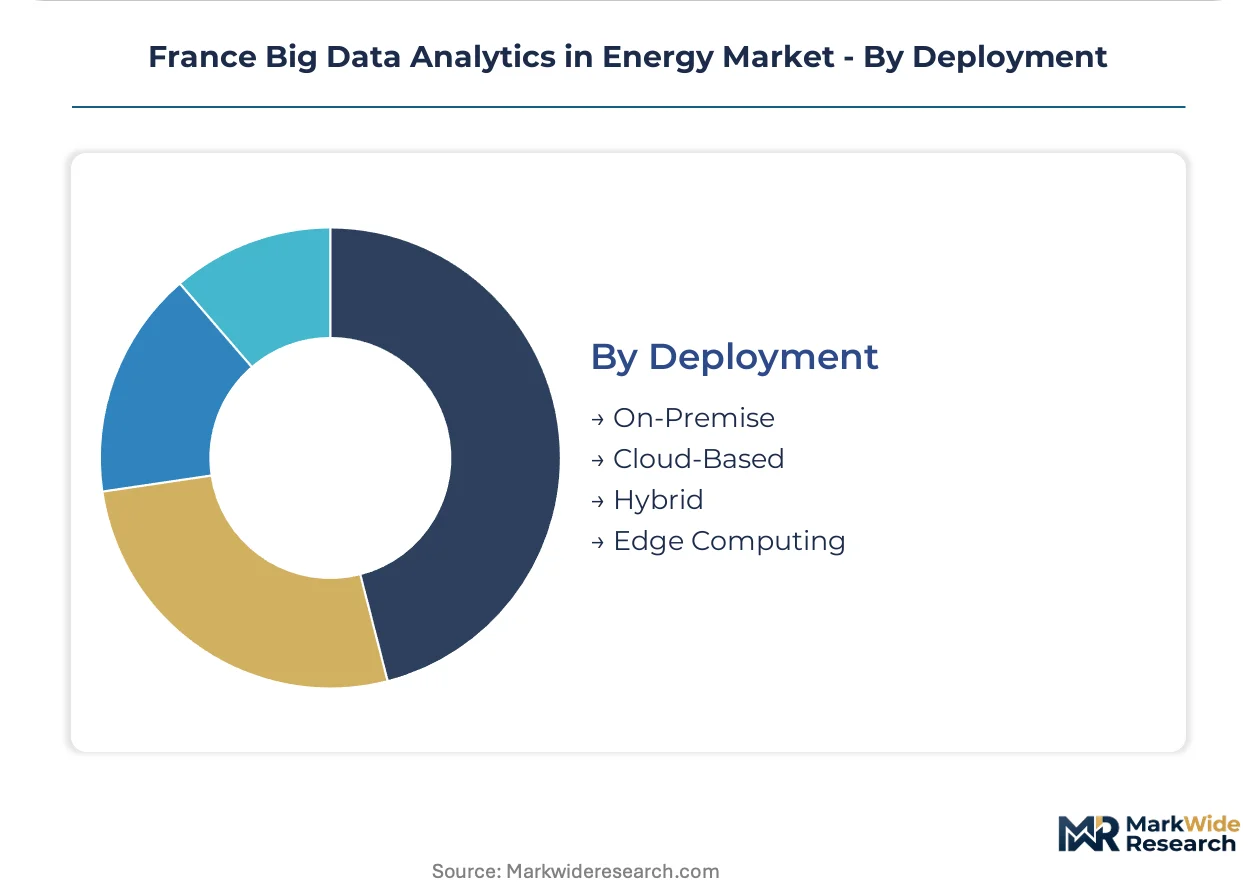
Deployment:
Deployment architecture selection reflects data sovereignty requirements and latency sensitivity across French operational contexts.
- On-Premise:Dedicated hardware installations within operator facilities. Nuclear and critical grid infrastructure mandates these configurations under CRE cybersecurity directives.
- Cloud-Based:Hyperscaler-hosted compute with elastic scaling. Independent power producers in Occitanie prefer this model to avoid capital-intensive infrastructure commitments.
- Hybrid:Split architectures with sensitive workloads on-premise and analytics in cloud. Regional distribution cooperatives piloting federated learning use this pattern.
- Edge Computing:Localized processing at substation or generation asset level. Brittany and Normandy cooperatives deploy these for real-time grid balancing with minimal backhaul latency.
On-Premise retains the largest installed base. Edge Computing shows the steepest expansion trajectory as federated analytics architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris-Saclay's concentration of data scientists and energy systems engineers anchors France's analytics talent base, with EDF's R&D campus and university research labs co-locating to accelerate algorithm development cycles.
Île-de-France
EDF and Enedis headquarters drive procurement standardization for predictive maintenance platforms. CNIL audit requirements for consumer energy data shape vendor selection criteria. The Paris-Saclay cluster hosts startup incubators testing federated learning architectures with major distributors.
Auvergne-Rhône-Alpes
Industrial manufacturers in chemicals and metallurgy deploy demand response systems to manage CRE capacity market charges. The EU Green Deal's carbon accounting mandates accelerate emissions tracking adoption. Lyon-based engineering consultancies specialize in SCADA-ML pipeline integration for nuclear operators.
Occitanie
Solar and wind expansion creates demand for geospatial intermittency mapping against industrial demand clusters. Regional distribution cooperatives pilot edge computing deployments for real-time grid balancing. The Montpellier tech corridor attracts cloud-native platform vendors targeting independent power producers.
Hauts-de-France
Energy-intensive manufacturing sites prioritize demand response orchestration to optimize exposure to wholesale price volatility. ASN oversight of nuclear installations drives investment in algorithmic safety monitoring. The Dunkirk industrial cluster tests predictive analytics for port electrification logistics.
Brittany and Normandy
Regional distribution cooperatives lead federated learning pilots, unifying localized model training with centralized aggregation. Edge computing deployments at substation level minimize backhaul latency for grid balancing. Rennes-based research institutes collaborate with Enedis on privacy-preserving analytics architectures.
France Big Data Analytics in Energy Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light cloud-native providers across deployment architectures, creating a tiered competitive structure. Siemens Aktiengesellschaft and Schneider Electric SE anchor the integrated hardware-software segment through deep utility relationships. Microsoft Corporation and SAP SE occupy the platform-agnostic cloud tier. Strategic moves concentrate on federated analytics partnerships and edge-to-cloud middleware development rather than direct product rivalry.
Within the integrated systems tier, Siemens Aktiengesellschaft exemplifies the physics-based digital twin approach, while Schneider Electric SE represents distribution network-native platform deployment. Microsoft Corporation anchors the hyperscaler vector with elastic compute offerings. These three occupy positions reflecting divergent bets on where analytics value accumulates—at the asset edge, in network infrastructure, or through cloud-scale processing.
| Leading Market Players |
|---|
| Siemens Aktiengesellschaft |
| Schneider Electric SE |
| Microsoft Corporation |
| SAP SE |
| International Business Machines Corporation |
| General Electric Company |
| ABB Group |
| Accenture plc |
| Orange Business Services |
| Others |
Pricing and Supply Chain Analysis
Premium predictive analytics suites and commodity visualization dashboards diverge sharply in both pricing architecture and supply chain configuration across the French energy sector. This bifurcation channels vendor investment toward specialized ML engineering talent for high-margin utility transformation projects while compressing margins in standardized dashboard tiers exposed to open-source displacement.
Pricing Analysis
Bundled platform deployments combining hardware, software, and implementation services command substantial premiums over unbundled SaaS subscriptions targeting mid-tier renewable operators. Three-tier pricing structure across enterprise, professional, and developer levels reflects divergence in SCADA integration depth and CNIL compliance certification. Cost compression in visualization tiers is intensifying because Grafana and Apache Superset alternatives eliminate licensing revenue pools. Independent power producers in Occitanie exhibit the highest price sensitivity due to unpredictable cloud compute costs, while EDF and Enedis demonstrate lowest sensitivity given regulatory mandates for predictive maintenance transparency.
Supply Chain Analysis
Workforce availability constraints in France, Germany, and Ireland shape delivery timelines for specialized SCADA-ML pipeline engineering and federated learning architecture deployment. Talent pipelines draw from Paris-Saclay research institutes, Munich technical universities, and Dublin hyperscaler engineering centers. Supply chain risk centers on single-source vulnerability for edge computing hardware components subject to CRE cybersecurity certification delays. Distribution runs through direct enterprise sales teams for utility incumbents and API-first platform marketplaces for cloud-native independent power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Big Data Analytics in Energy Market functions as a stable compounder anchored by regulatory mandates under the EU Green Deal and EU AI Act that institutionalize demand for transparency and explainable automation across grid operations.
For Market Incumbents: Acquire specialized SCADA-ML engineering boutiques to close capability gaps in legacy system interoperability. Siemens Aktiengesellschaft and Schneider Electric SE should deepen control over edge computing hardware supply chains to defend margin pools against hyperscaler encroachment. Federated learning patent portfolios represent critical defensive assets as Brittany and Normandy cooperatives scale pilot deployments. For New Entrants and Emerging Players: Regional distribution cooperatives in Grand Est biogas clusters present the most penetrable buyer archetype underserved by incumbent sales coverage. Cloud-native platforms with usage-based API pricing address procurement sophistication gaps among consolidated independent power producers. A direct channel strategy bypassing traditional utility sales cycles accelerates proof-of-concept traction in Occitanie solar corridors. For Investors and Strategic Acquirers: Asymmetric upside sits with edge-to-cloud middleware specialists bridging operational technology and information technology budget consolidation. Long-term viability hinges on CRE grid code amendment compliance capabilities as EU AI Act risk tiers transpose into operational mandates. The signal to watch is federated learning procurement volume from Enedis regional pilots as an inflection indicator for national rollout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Enables CNIL-compliant model training across substation-level data silos without raw data centralization. |
| Edge Computing Certification | CRE cybersecurity directives mandate hardened hardware for critical grid infrastructure deployments. |
| SCADA-ML Pipeline Acquisition | Shortage of specialists bridging industrial control protocols with stream processing architectures constrains scaling. |
| API-First Platform Launch | Mid-sized renewable operators in Occitanie demand elastic compute pricing without perpetual license commitments. |
| Digital Twin Integration | Physics-based simulation convergence with operational data streams commands premium pricing from EDF transformation budgets. |
Research Methodology
Direct dialogue with utility planning officers, independent power producer project developers, grid operators at Enedis and RTE, and SCADA-ML engineering specialists anchored qualitative foundations. Secondary validation drew from CRE regulatory filings, EU Green Deal implementation trackers, CNIL audit guidance documents, and hyperscaler energy vertical capex disclosures. Bottom-up and top-down triangulation cross-checked deployment volume estimates against procurement pipeline visibility.
Bottom-up modeling segmented revenue across predictive analytics, data mining, visualization tools, and data integration product types, further disaggregated by on-premise, cloud-based, hybrid, and edge computing deployment architectures. Top-down validation assessed aggregate utility IT spending patterns and renewable operator technology budgets across the analysis window. CAGRs were derived from fitted growth curves incorporating EU AI Act implementation timelines and federated learning adoption S-cycles.
Inputs from CRE grid code consultations and Paris-Saclay cluster startup pipelines were available through the study window; gaps in proprietary SCADA telemetry volume data introduce uncertainty bands around predictive analytics penetration assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and cloud infrastructure cost trajectories. Material deviation in EU AI Act risk classification timelines or CNIL audit stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market