
 Russia Cross Laminated Timber Market | 2026-2036
Russia Cross Laminated Timber Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Cross Laminated Timber Market Intelligence
Northwestern Russia is fragmenting as new CLT capacity comes online near timber-rich zones. Segezha Group leverages its integrated sawmill network to control raw material flows from Karelia to production sites. Stora Enso sustains technology leadership through precision-engineered panel systems. Binderholz anchors its position with specialized adhesive formulations suited to cold-climate performance requirements.
Cross laminated timber consists of odd-numbered layers of lumber boards stacked perpendicular to adjacent layers, bonded with structural adhesives under hydraulic pressure, typically achieving panel thicknesses from 60mm to 500mm. Its primary purpose is to replace steel and concrete in load-bearing wall, floor, and roof assemblies while sequestering atmospheric carbon within the building envelope. Structural Panels dominate current output volumes as builders prioritize standardized load-bearing elements for mid-rise residential frames. Residential Construction represents the fastest-expanding end-user channel as Moscow developers adopt CLT for five-to-eight story apartment blocks. Load-Bearing Structures capture the deepest margin pools due to engineering certification requirements and project-specific design complexity.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) oversees GOST standards for glued timber products, while the Ministry of Construction maintains fire safety classifications that determine permissible building heights for CLT assemblies. The Eurasian Economic Union's harmonized technical regulations create cross-border compliance obligations for producers serving Kazakhstan and Belarus markets. Stakeholders must monitor how amendments to Russia's urban planning codes affect CLT eligibility in state-funded residential programs.
Market Dynamics
CLT adoption in Russia accelerates as Rosstandart's updated GOST standards enable engineered wood in multi-story residential frames, compressing approval timelines for developers seeking lower-carbon construction methods.
Growth Catalysts
- Eurasian Economic Union harmonization:Technical regulation alignment permits Russian CLT producers to serve Kazakhstan and Belarus without duplicate certification, expanding addressable demand across three integrated markets.
- Moscow residential density mandates:Urban planning codes now permit five-to-eight story wooden structures in the Central Federal District, creating immediate pull from apartment developers seeking faster construction cycles.
- Karelian timber basin proximity:Northwestern production clusters leverage captive softwood supply from Segezha and Arkhangelsk regions, reducing raw material transport costs versus concrete supply chains.
Market Restraints
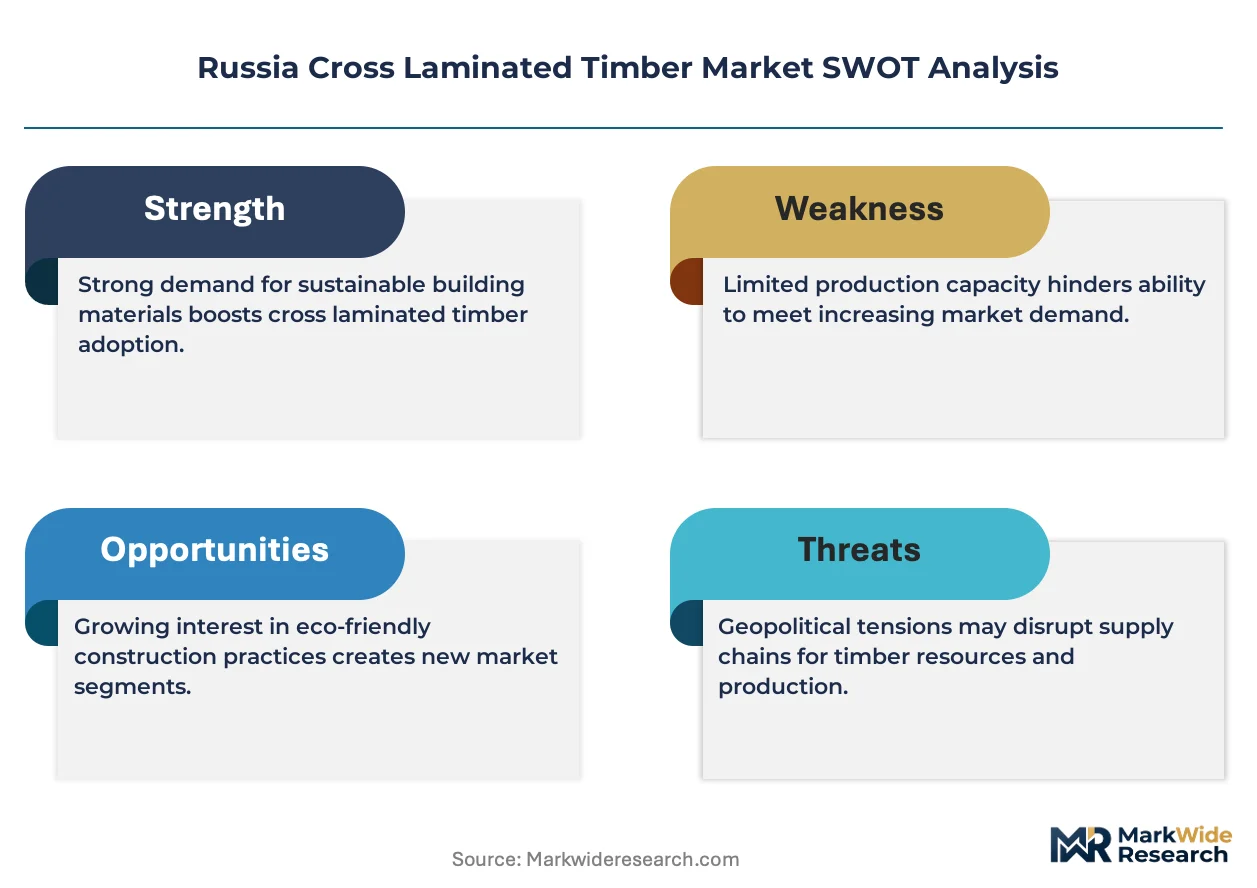
- Adhesive input volatility:Structural polyurethane and melamine resin prices fluctuate with petrochemical feedstock costs, compressing panel margins when oil benchmarks spike.
- Fire safety classification ceilings:Ministry of Construction height restrictions limit CLT to mid-rise applications, excluding the high-rise residential segment where concrete and steel retain structural dominance.
- Engineered wood substitution threat:Glued laminated timber and laminated veneer lumber compete for identical load-bearing applications with lower unit costs and established supply chains.
Strategic Opportunities
- Siberian underpenetration:Novosibirsk and Irkutsk construction markets lack local CLT capacity, creating first-mover advantage for producers establishing eastern distribution nodes.
- Industrial building retrofit wave:Warehouse and logistics facility developers seek carbon-sequestering envelope materials to meet corporate sustainability targets and ESG disclosure requirements.
- Rosstandart fast-track certification:Streamlined type-approval processes for prefabricated panel systems reduce time-to-market for innovative connection hardware and fire-retardant treatments.
Industry Challenges
- Structural engineer scarcity:Russian universities produce limited graduates trained in timber-specific load calculations, constraining project design capacity and extending pre-construction timelines.
- Panel-to-foundation integration complexity:Legacy Soviet-era concrete slab infrastructure requires specialized anchoring systems, adding cost and coordination friction for mixed-material projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Cross Laminated Timber Market |
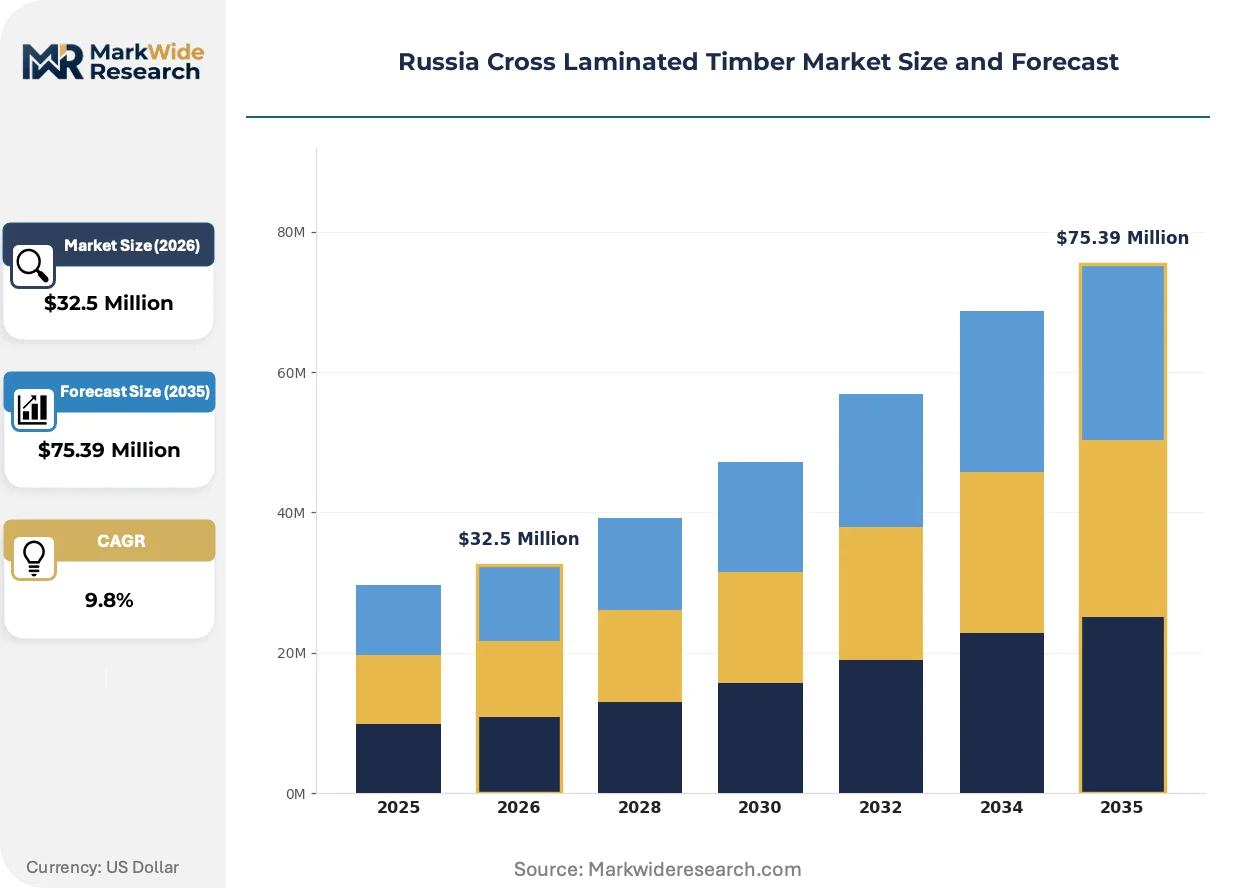
| Market Size in 2026 | $32.5 Million |
| Market Size in 2035 | $75.39 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Panels, Facade Elements, Roof Elements, Ceiling Panels End User: Residential Construction, Commercial Buildings, Industrial Facilities, Infrastructure Projects Application: Load-Bearing Structures, Non-Load Bearing Walls, Acoustic Applications, Thermal Insulation Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Distributors |
| Companies Covered | Segezha Group, Stora Enso, Binderholz, KLH Massivholz, Mayr-Melnhof Holz, Hasslacher Norica Timber, Lignotrend, Nordic Structures, Schilliger Holz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Cross Laminated Timber Market Strategic Shifts & Innovations
Digital fabrication and regulatory modernization are compressing design-to-assembly timelines while reshaping competitive advantage around precision-engineered panel systems rather than commodity lumber supply.
Building information modeling software is virtualizing the entire CLT project workflow from structural optimization to CNC cutting paths. Moscow-based developers now require BIM-compatible panel specifications for mid-rise residential tenders. This capability compression is virtualizing traditional engineering consultancies and erection contractors into integrated design-build entities.
Rosstandart's 2024 amendments to GOST 2708-75 and related glued timber standards explicitly recognize CLT for load-bearing wall and floor assemblies. The industrial consequence is accelerated type-approval for imported European connection systems and fire-retardant treatments. Northwestern producers are responding fastest, submitting certification packages for multi-story apartment prototypes in St. Petersburg.
Developer procurement patterns now favor turnkey panel supply contracts over discrete material purchases. General contractors in the Central Federal District are consolidating vendor relationships with producers offering structural engineering, logistics coordination, and on-site assembly supervision. This bundling trend is most visible in Moscow's five-to-eight story residential segment, where speed-to-occupancy determines project financing costs.
Russia Cross Laminated Timber Market Segmentation
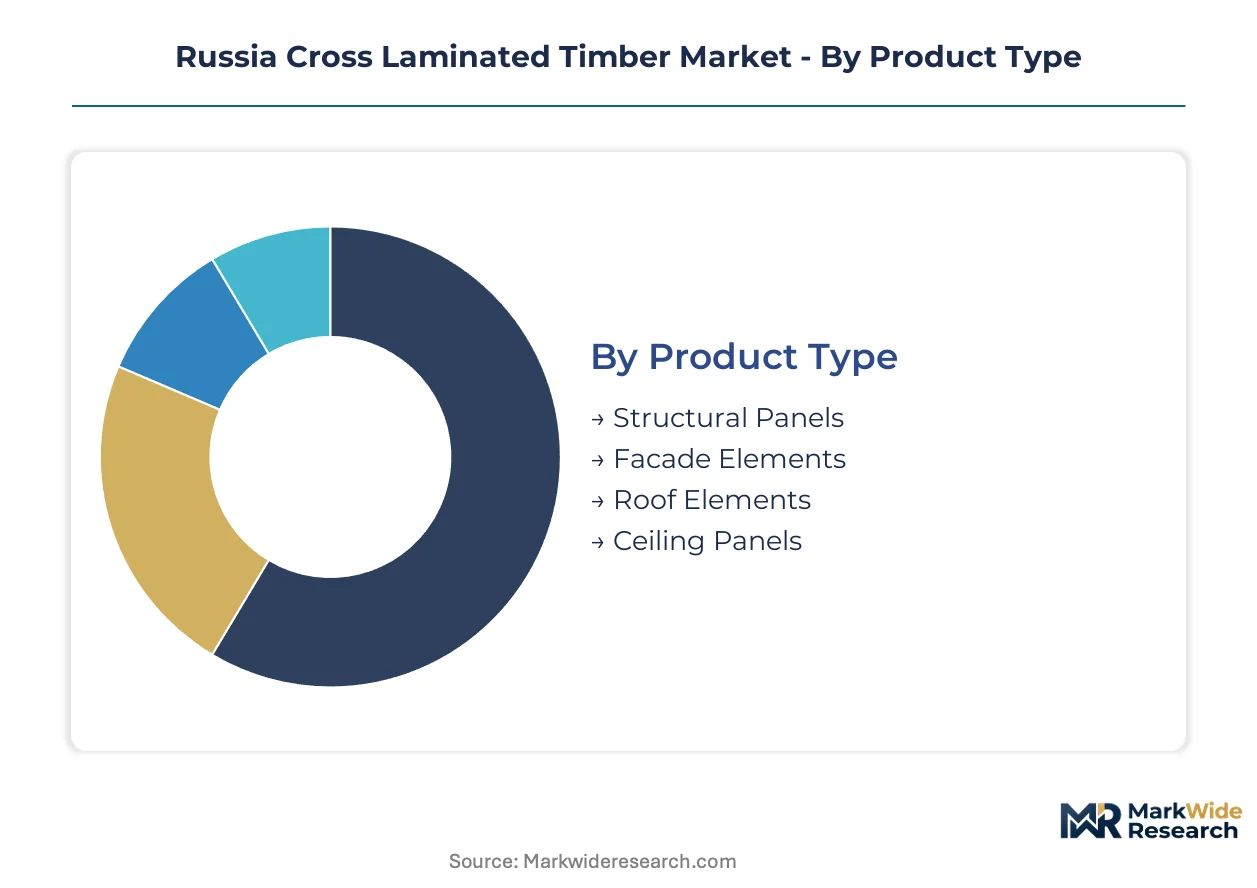
CLT market segmentation in Russia reflects divergent procurement cycles across construction verticals. Product specifications and application requirements create distinct margin profiles that reshape competitive positioning for panel manufacturers.
Product Type:
Structural Panels turn over fastest due to standardized specifications and repeat residential orders, while Facade Elements cycle slowly through custom architectural review.
- Structural Panels:Multi-layered perpendicular lumber boards bonded under hydraulic pressure, achieving 60mm to 500mm thicknesses for load-bearing assemblies. Moscow developers specify these for five-to-eight story apartment frames where GOST certification compresses approval timelines.
- Facade Elements:Externally finished panel systems integrating weatherproof membranes and architectural cladding. St. Petersburg commercial projects drive specification complexity as planners enforce historic district aesthetic requirements.
- Roof Elements:Prefabricated cassettes with integrated insulation and vapor barriers for pitched assemblies.
- Ceiling Panels:Acoustically treated systems for multi-unit residential common areas and office fit-outs.
Structural Panels anchors the volume base while Facade Elements gains share at the steepest rate.
End User:
Residential Construction commands the highest procurement frequency through state-funded housing programs, whereas Infrastructure Projects stretch delivery cycles across multi-year public tenders.
- Residential Construction:Multi-story wooden frame buildings permitted under updated urban planning codes in the Central Federal District. Moscow apartment developers prioritize speed-to-occupancy to minimize carrying costs on construction financing.
- Commercial Buildings:Office and retail envelope systems where corporate ESG targets drive carbon-sequestering material selection. St. Petersburg logistics developers specify CLT for warehouse superstructures to meet sustainability disclosure requirements.
- Industrial Facilities:Manufacturing plant enclosures requiring fire-rated panel assemblies for process safety compliance.
- Infrastructure Projects:Bridge decks, railway stations, and transit facilities where Rosstandart type-approval processes extend procurement lead times.
Residential Construction dominates current output volumes while Commercial Buildings shows the most rapid demand acceleration.
Application:
Load-Bearing Structures generate the longest engineering cycles due to structural certification requirements, while Thermal Insulation panels move fastest through standardized procurement channels.
- Load-Bearing Structures:Wall and floor assemblies engineered for gravity and lateral loads with project-specific connection detailing. Northwestern producers capture premium margins through integrated design-build contracts that bundle structural engineering with panel supply.
- Non-Load Bearing Walls:Partition systems and infill panels separating interior spaces without structural function. Moscow fit-out contractors specify these for office renovation projects where speed of installation determines contract profitability.
- Acoustic Applications:Densely laminated panels with enhanced mass for sound transmission control in multi-family housing.
- Thermal Insulation:Thick-section panels prioritizing envelope thermal performance over structural capacity for low-rise construction.
Load-Bearing Structures commands the deepest margin pools while Thermal Insulation expands most quickly through standardized residential programs.
Distribution Channel:
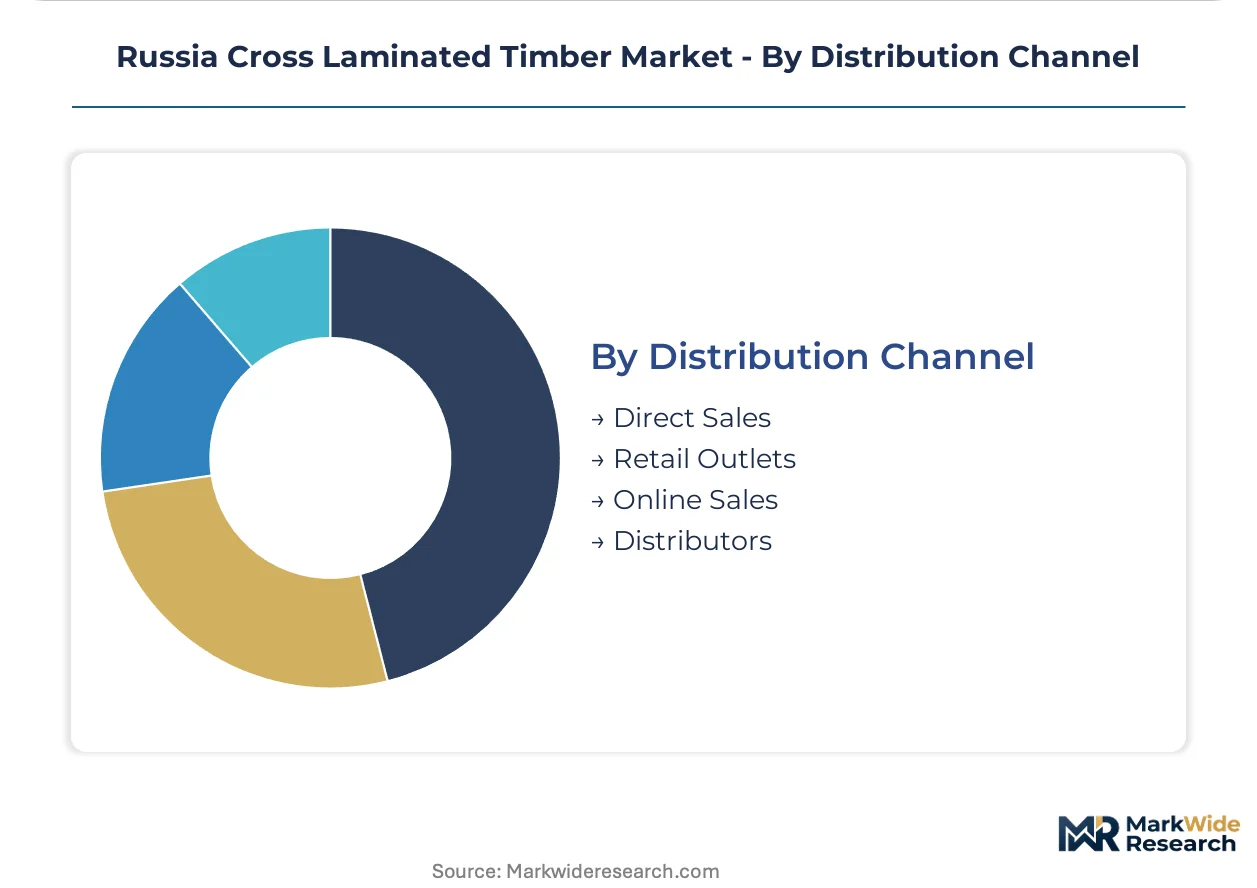
Direct Sales concentrate transaction velocity with large developers, whereas Retail Outlets serve fragmented renovation demand through slower-turn inventory.
- Direct Sales:Producer-to-developer contracts bundling structural engineering, logistics coordination, and on-site assembly supervision. Central Federal District general contractors now mandate turnkey panel supply for mid-rise tenders.
- Distributors:Regional stocking intermediaries serving smaller contractors beyond producer direct coverage areas. Siberian construction markets rely on these channels given the absence of local manufacturing capacity.
- Retail Outlets:Lumber yard and building material center sales of standardized panel dimensions for single-family and renovation applications.
- Online Sales:Digital procurement platforms for specification sheets, cut-to-order services, and small-volume project quotes.
Direct Sales captures the dominant revenue share while Distributors posts the steepest expansion trajectory as producers penetrate underdeveloped eastern regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rosstandart anchors the Central Federal District's regulatory framework, enabling multi-story CLT construction through updated GOST standards while regional demand fragments across timber-rich zones and emerging eastern markets.
Central Federal District
Moscow apartment developers drive procurement volume for five-to-eight story wooden frames under relaxed urban planning codes. Rosstandart's fast-track certification for prefabricated panel systems compresses approval timelines for state-funded housing programs. The Moscow-St. Petersburg corridor concentrates turnkey panel supply contracts bundling structural engineering with on-site assembly supervision.
Northwestern Federal District
Karelian softwood basins feed captive raw material flows to production clusters near Segezha and Arkhangelsk regions. The Ministry of Construction maintains fire safety classifications that determine permissible building heights for CLT assemblies in St. Petersburg's historic districts. Northwestern producers submit certification packages for multi-story apartment prototypes faster than competitors in other regions.
Siberian Federal District
Novosibirsk and Irkutsk construction markets lack local CLT capacity, creating first-mover advantage for producers establishing eastern distribution nodes. Regional stocking intermediaries serve smaller contractors given the absence of local manufacturing infrastructure. Timber harvesting in Krasnoyarsk Krai remains underutilized for engineered wood production despite abundant softwood supply.
Volga Federal District
Kazan and Nizhny Novgorod developers experiment with CLT for commercial warehouse envelopes to meet corporate ESG disclosure requirements. The Eurasian Economic Union's harmonized technical regulations create cross-border compliance obligations for producers serving Kazakhstan markets from Volga logistics hubs. Regional distributors expand coverage as direct sales networks from northwestern producers remain thin.
Southern Federal District
Rostov-on-Don and Krasnodar construction markets show nascent CLT adoption for low-rise residential and thermal insulation applications. Legacy Soviet-era concrete slab infrastructure requires specialized anchoring systems, adding coordination friction for mixed-material projects. Southern distributors rely on rail freight from northwestern production clusters, extending delivery lead times versus concrete supply chains.
Russia Cross Laminated Timber Market Key Industry Players
Capability concentration sits with integrated timber-to-panel specialists; scale advantage sits with diversified Nordic producers with cross-border certification experience. The vendor base organizes around three archetypes: captive sawmill operators controlling upstream softwood flows, European multinationals leveraging precision-engineering platforms, and regional fabricators serving localized project pipelines. Dominant competitive moves include backward integration into Karelian timber basins and strategic partnerships with Moscow-based developers for turnkey supply contracts.
Among integrated Russian producers, Segezha Group exemplifies the captive-resource archetype through its control of northwestern sawmill networks. Stora Enso and Binderholz represent the precision-engineering tier, with the former anchoring technology leadership through panel system specifications and the latter occupying a position defined by adhesive formulation specialization for cold-climate performance. These three names illustrate how competitive advantage in Russian CLT markets derives from raw material security, engineering certification depth, and climate-specific product adaptation rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Segezha Group |
| Stora Enso |
| Binderholz |
| KLH Massivholz |
| Mayr-Melnhof Holz |
| Hasslacher Norica Timber |
| Lignotrend |
| Nordic Structures |
| Schilliger Holz |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility in adhesive resin markets determines both tiered pricing spreads across certification grades and supply chain configuration toward captive softwood basins. Rosstandart's GOST certification requirements create pricing premiums for structurally certified panels while Karelian timber proximity compresses logistics costs for northwestern producers.
Pricing Analysis
Geographic price spreads widen between Central Federal District developers and Siberian contractors due to rail freight differentials from Karelian production clusters. Three-tier pricing structure across premium, standard, and economy levels separates GOST-certified structural panels from non-certified commodity grades and custom-engineered facade systems. Cost compression in standard-grade segments is intensifying because polyurethane adhesive prices fluctuate with oil benchmarks. State-funded housing developers exhibit highest price sensitivity through volume tender mechanisms, while St. Petersburg commercial projects demonstrate lowest sensitivity due to ESG-mandated material specifications.
Supply Chain Analysis
Karelian softwood basins feed captive raw material flows to production clusters near Segezha and Arkhangelsk regions, with secondary sourcing from Siberian timber harvesting in Krasnoyarsk Krai. Structural polyurethane adhesives, melamine resins, and precision-engineered connection hardware constitute critical input dependencies. Single-source vulnerability concentrates in European-sourced connection systems subject to import certification delays under Eurasian Economic Union harmonization rules. Distribution runs through producer-direct turnkey contracts for Moscow developers, regional stocking intermediaries for Siberian markets, and rail-linked distributor networks for southern federal districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from regulatory approval bottlenecks as Rosstandart's GOST amendments compress type-approval timelines and unlock state-funded residential procurement cycles.
For Market Incumbents: Pre-empt glued laminated timber substitution by securing GOST certification for multi-story connection systems before competitors complete approval packages. Deepen backward integration into Arkhangelsk timber basins to insulate margin pools from adhesive input volatility. Anchor position through turnkey design-build contracts that bundle structural engineering with panel supply, raising switching costs for Moscow developers. For New Entrants and Emerging Players: Establish a beachhead in Novosibirsk and Irkutsk construction markets where local CLT capacity absence creates first-mover advantage for eastern distribution nodes. Target industrial warehouse envelope retrofits where corporate ESG disclosure requirements drive carbon-sequestering material selection. Pursue fast-track Rosstandart certification for prefabricated panel systems to compress time-to-market versus established northwestern producers. For Investors and Strategic Acquirers: The market sits at a regulatory normalization phase that favors integrated timber-to-panel specialists with captive softwood security and certification depth. Long-term viability hinges on producers controlling upstream Karelian sawmill networks rather than manufacturing scale alone. Watch Rosstandart amendment velocity for connection hardware and fire-retardant treatments as the inflection signal for competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Karelian Timber Basins | Captive softwood supply insulates margin pools from transport cost volatility and raw material competition. |
| GOST Certification for Multi-Story Connection Systems | Rosstandart type-approval creates regulatory moats against lower-cost glued laminated timber substitutes. |
| Eastern Distribution Node Establishment | Novosibirsk and Irkutsk market entry captures underpenetrated demand before northwestern producers extend coverage. |
| Turnkey Design-Build Contract Bundling | Integrated structural engineering and assembly supervision raises switching costs for Moscow residential developers. |
| Industrial Warehouse Envelope Specialization | ESG-mandated carbon sequestration targets in logistics facilities open non-residential procurement channels. |
Research Approach
A spread of perspectives from CLT production managers, structural engineering consultants, Moscow developer procurement leads, and Rosstandart certification officers converged on the working assumptions underlying demand projections. Primary fieldwork combined facility visits to northwestern production clusters with secondary validation through Eurasian Economic Union technical regulation filings, Ministry of Construction fire safety classifications, and customs data on adhesive resin imports. Bottom-up project pipeline analysis triangulated against top-down construction sector forecasts.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by structural versus non-structural grades, end-user channels spanning residential and commercial verticals, and application-specific engineering certification requirements. CAGRs derived from regression analysis of historical construction permit data against CLT penetration rates in permitted wooden structures. Forecast inputs included urban planning code amendment schedules and state-funded housing program allocation patterns.
Sensitivities concentrate around Rosstandart certification velocity, adhesive resin price volatility, and Eurasian Economic Union harmonization implementation timing. Forecasts reflect documented assumptions regarding GOST standard adoption rates and multi-story height restriction relaxations. Cross-checking against Ministry of Construction building permit issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Insulating Glass Window Market