
 Machinery Rental and Leasing Market | 2026-2036
Machinery Rental and Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Machinery Rental and Leasing Market Insights
Modular equipment bundling is expanding as rental providers package excavators, loaders, and site offices into single contract offerings. United Rentals Inc. leverages its national branch network to deliver integrated fleet solutions across metropolitan construction zones. Ashtead Group plc (Sunbelt Rentals) anchors its growth strategy in Sunbelt state population migration where residential and commercial buildouts sustain equipment utilization rates. Herc Holdings Inc. (Herc Rentals) differentiates through specialty offerings including climate control and power generation for industrial turnaround projects.
Machinery rental and leasing denotes the short-to-medium-term provision of capital equipment against periodic payments, typically structured as operating leases with maintenance inclusion and flexible term extensions. The arrangement transfers operational risk to the lessor while preserving the lessee's balance sheet capacity for core business investment. Construction equipment dominates service type revenue given the cyclical nature of building activity and the prohibitive cost of owning idle crawler cranes and earthmoving fleets. Material handling shows the fastest structural expansion as e-commerce fulfillment centers and warehouse automation drive forklift and telehandler demand across manufacturing and logistics end users. Long-term deployment contracts command premium pricing stability compared to on-demand spot rentals, which absorb higher logistics and repositioning costs.
OSHA workplace safety mandates and EPA Tier 4 Final emissions standards shape fleet replacement cycles by accelerating retirement of older diesel units. The Federal Reserve's interest rate posture directly influences lease versus buy decisions across contractor and manufacturing end user segments. Stakeholders must monitor equipment telematics adoption rates and residual value forecasting models as digital fleet management becomes the primary determinant of rental yield optimization.
Market Dynamics
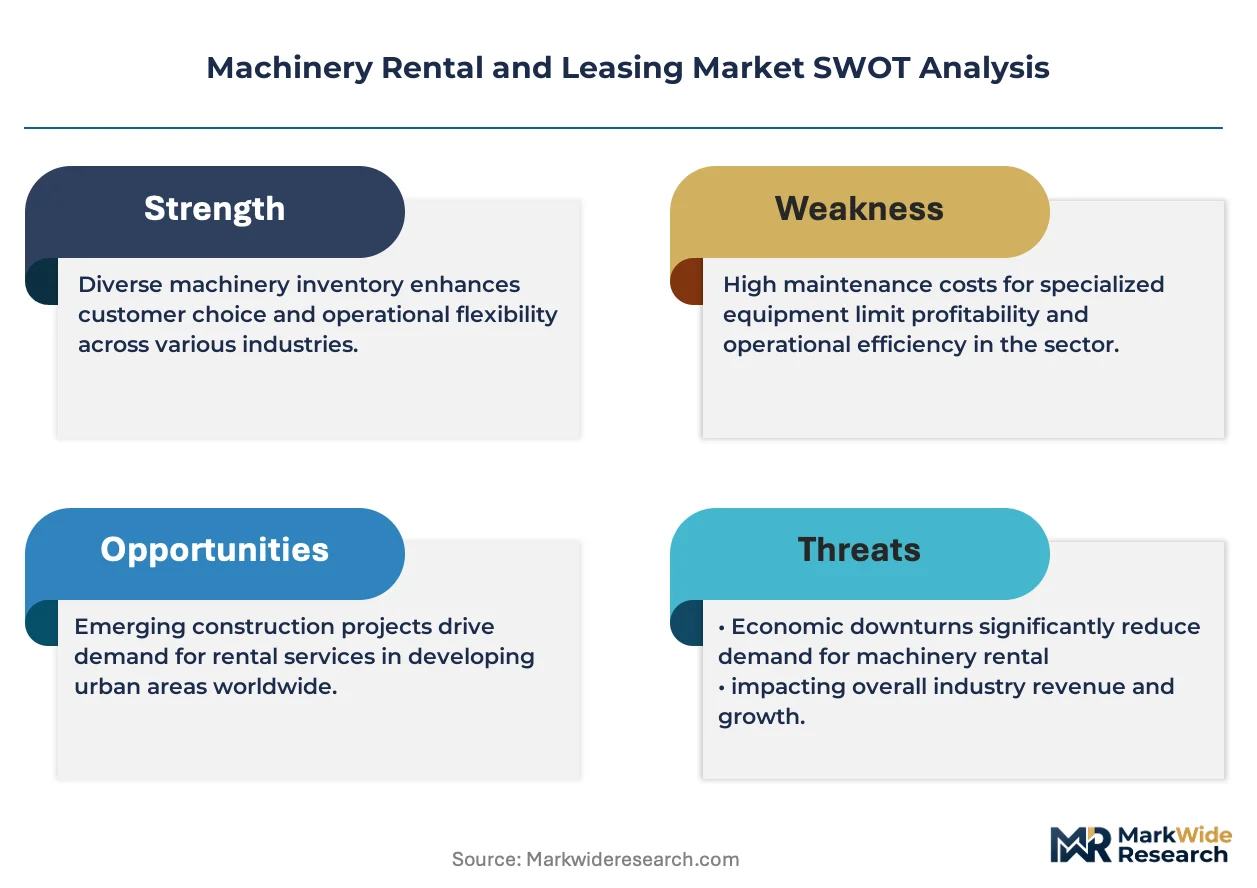
EPA Tier 4 Final emissions mandates are compressing fleet replacement cycles across the construction equipment rental sector, forcing capital redeployment toward compliant diesel engines and alternative powertrains.
Growth Catalysts
- Infrastructure Investment and Jobs Act:Federal highway and bridge allocations across the United States are accelerating earthmoving equipment deployment through rental channels.
- E-commerce fulfillment center construction:Warehouse automation buildouts in Texas, Florida, and California are driving telehandler and forklift utilization rates.
- Telematics integration:IoT-enabled fleet management systems are reducing idle time and optimizing asset deployment for multi-site contractors.
Market Restraints
- Steel and hydraulic component volatility:Input cost fluctuations for crane booms and excavator arms compress rental margin buffers during contract periods.
- Equipment manufacturer concentration:Production bottlenecks at Caterpillar, Komatsu, and Deere facilities extend lead times for Tier 4 Final compliant units.
- Diesel particulate filter maintenance burden:Aftertreatment system complexity raises total cost of ownership for rental fleets operating older transitional equipment.
Strategic Opportunities
- Electric compact equipment:Battery-powered mini-excavators and skid steers penetrate urban job sites with noise and emissions restrictions in California municipalities.
- OSHA silica dust enforcement:Respirable crystalline silica standards drive rental demand for enclosed cabs and dust suppression attachments on demolition sites.
- Subscription-based maintenance bundling:Predictive service contracts tied to telematics data streams create recurring revenue anchors beyond base rental rates.
Industry Challenges
- Certified equipment operator scarcity:Crane and aerial lift licensing backlogs in high-growth construction markets delay fleet deployment and contract execution.
- Legacy ERP integration with telematics platforms:Rental management software migration creates data silos and billing reconciliation friction for multi-branch operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machinery Rental and Leasing Market |
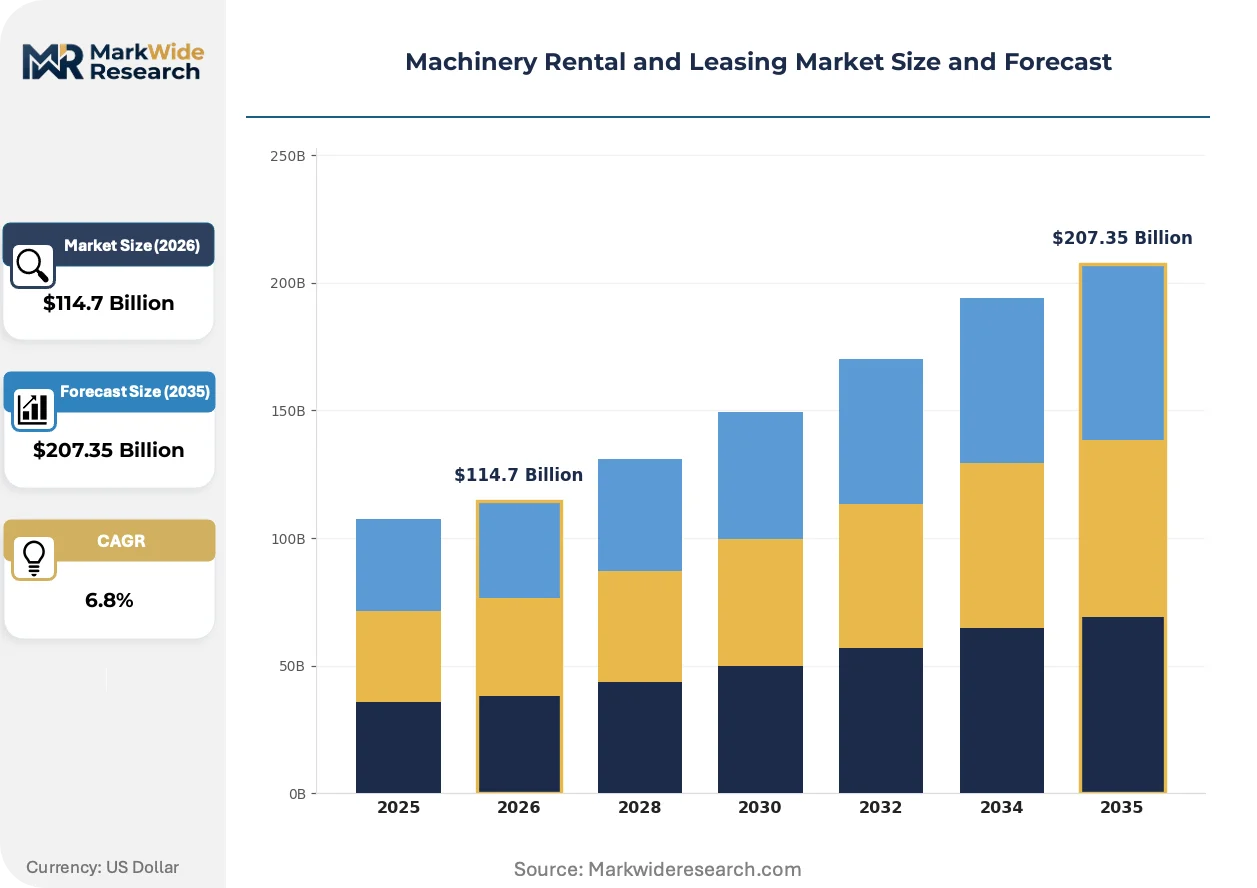
| Market Size in 2026 | $114.7 Billion |
| Market Size in 2035 | $207.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Construction Equipment, Agricultural Machinery, Industrial Tools, Material Handling Deployment: On-premises, Off-site, On-demand, Long-term End User: Contractors, Farmers, Manufacturers, Event Organizers Equipment Type: Heavy Machinery, Light Equipment, Power Tools, Forklifts |
| Companies Covered | United Rentals Inc., Ashtead Group plc (Sunbelt Rentals), Herc Holdings Inc. (Herc Rentals), WillScot Mobile Mini Holdings Corp., H&E Equipment Services Inc., Loxam Group, Aggreko plc, Sunstate Equipment Co., EquipmentShare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machinery Rental and Leasing Market Trends and Innovations
Telematics-enabled predictive maintenance is restructuring how rental fleets manage asset lifecycle value, shifting competitive advantage from scale toward data-driven utilization optimization.
Electric powertrains for compact earthmoving equipment are overtaking diesel alternatives in municipal and indoor construction segments. Urban contractors in California and New York are specifying zero-emission excavators for noise-restricted job sites. Battery swapping infrastructure and fast-charging protocols are compressing the operational range penalty that previously limited electric unit deployment.
EPA Tier 4 Final compliance deadlines are accelerating retirement of pre-2015 diesel engines from active rental fleets. Off-road emissions enforcement in California through the Air Resources Board extends equipment replacement obligations beyond federal minimums. Rental providers are front-loading capital expenditure toward dual-fuel and electric platforms to maintain eligibility for public infrastructure contracts.
Fixed-fee fleet management contracts are displacing transactional spot rentals for multi-year construction projects. General contractors in Texas and Florida are consolidating equipment procurement under single-source agreements with utilization guarantees and maintenance inclusion. This procurement consolidation transfers residual value risk to rental providers while locking in volume commitments through project completion milestones.
Machinery Rental and Leasing Market Segmentation
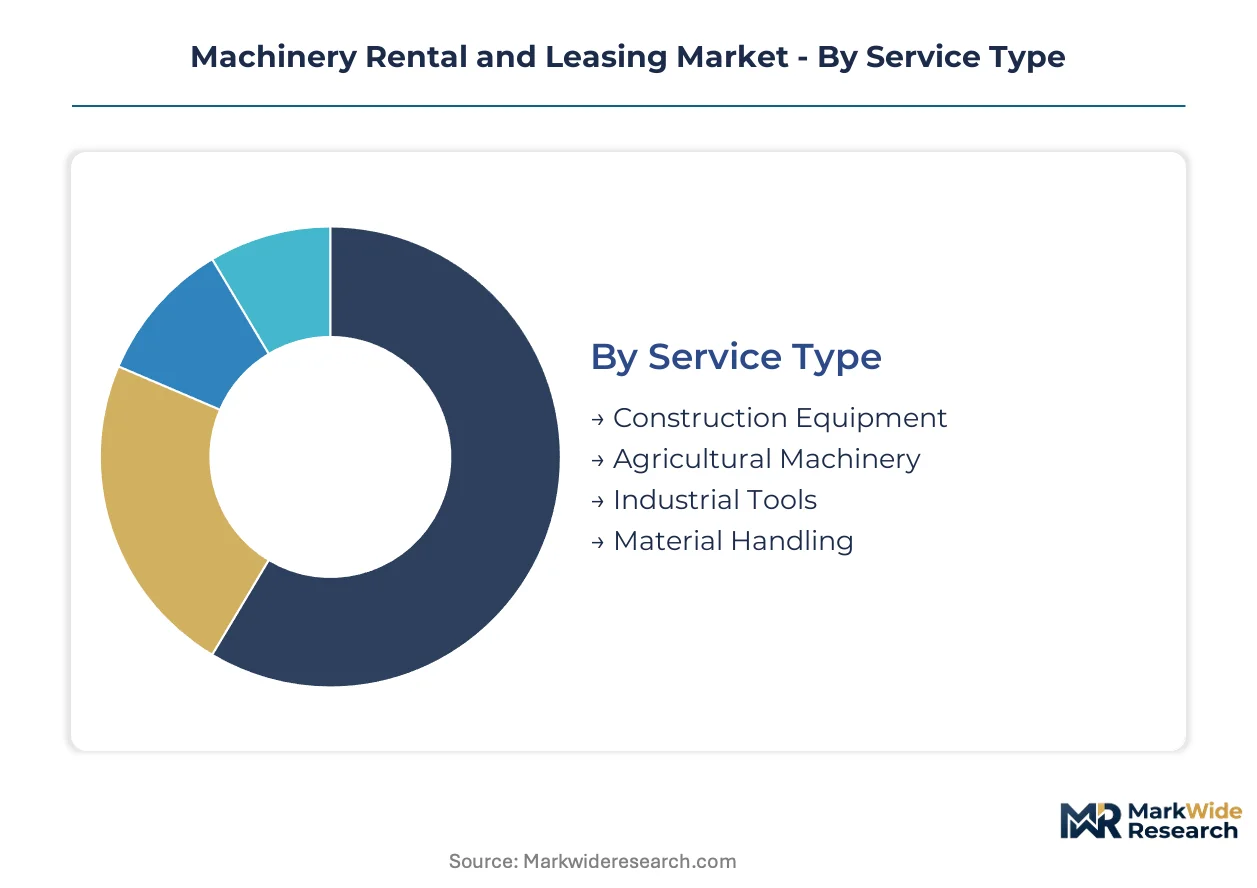
Machinery rental segmentation reveals how capital deployment strategies diverge across equipment categories and contract structures. Rental providers calibrate fleet composition and pricing models to match the utilization patterns and risk profiles inherent to each segment boundary.
Service Type:
Construction equipment commands the largest revenue base through high-value earthmoving fleets, while material handling accelerates fastest on e-commerce fulfillment demand.
- Construction Equipment:Crawler cranes, excavators, and earthmoving fleets generate the highest per-unit rental yields. Infrastructure contractors in Texas and Florida drive utilization through multi-year highway and bridge projects.
- Material Handling:Telehandlers and warehouse forklifts are expanding most quickly as automated fulfillment centers proliferate. California logistics hubs absorb premium rates for electric units compliant with municipal emissions restrictions.
- Agricultural Machinery:Seasonal harvest equipment serves row-crop operations in Midwest grain belts with revenue concentrated in narrow planting and harvesting windows.
- Industrial Tools:Compressed air systems and precision machining equipment support manufacturing turnarounds with rental terms tied to maintenance outage schedules.
Today's leader: Construction Equipment. Tomorrow's challenger: Material Handling.
Deployment:
Contract duration determines pricing stability and logistics cost allocation between rental provider and lessee.
- Long-term:Multi-year fleet management agreements transfer residual value risk to lessors while locking volume commitments through project milestones. General contractors in high-growth Sunbelt markets favor this structure for capital predictability.
- On-demand:Spot rentals absorb repositioning costs and equipment availability uncertainty. Short-term deployment suits emergency response and seasonal demand spikes where owning idle capacity is prohibitive.
- On-premises:Dedicated yard placement eliminates transport friction for contractors with concentrated job site footprints.
- Off-site:Centralized depot models optimize fleet pooling across dispersed customer bases but introduce delivery scheduling complexity.
Long-term contracts anchor provider revenue stability. On-demand formats capture premium pricing during supply-constrained periods.
End User:
Customer type dictates equipment specification requirements and service bundling expectations.
- Contractors:General and specialty construction firms drive the majority of earthmoving and aerial lift demand. OSHA compliance mandates shape their attachment and cab specification preferences.
- Manufacturers:Industrial facilities rent power generation and climate control equipment for planned turnarounds. Predictive maintenance contracts align rental terms with production schedules.
- Farmers:Row-crop and specialty producers utilize seasonal machinery without capital lockup. Harvest window timing creates concentrated demand spikes.
- Event Organizers:Temporary power, climate control, and material handling support festivals and sporting venues with ultra-short rental horizons.
Contractors generate the deepest revenue pools. Manufacturers offer the steadiest contract renewal rates.
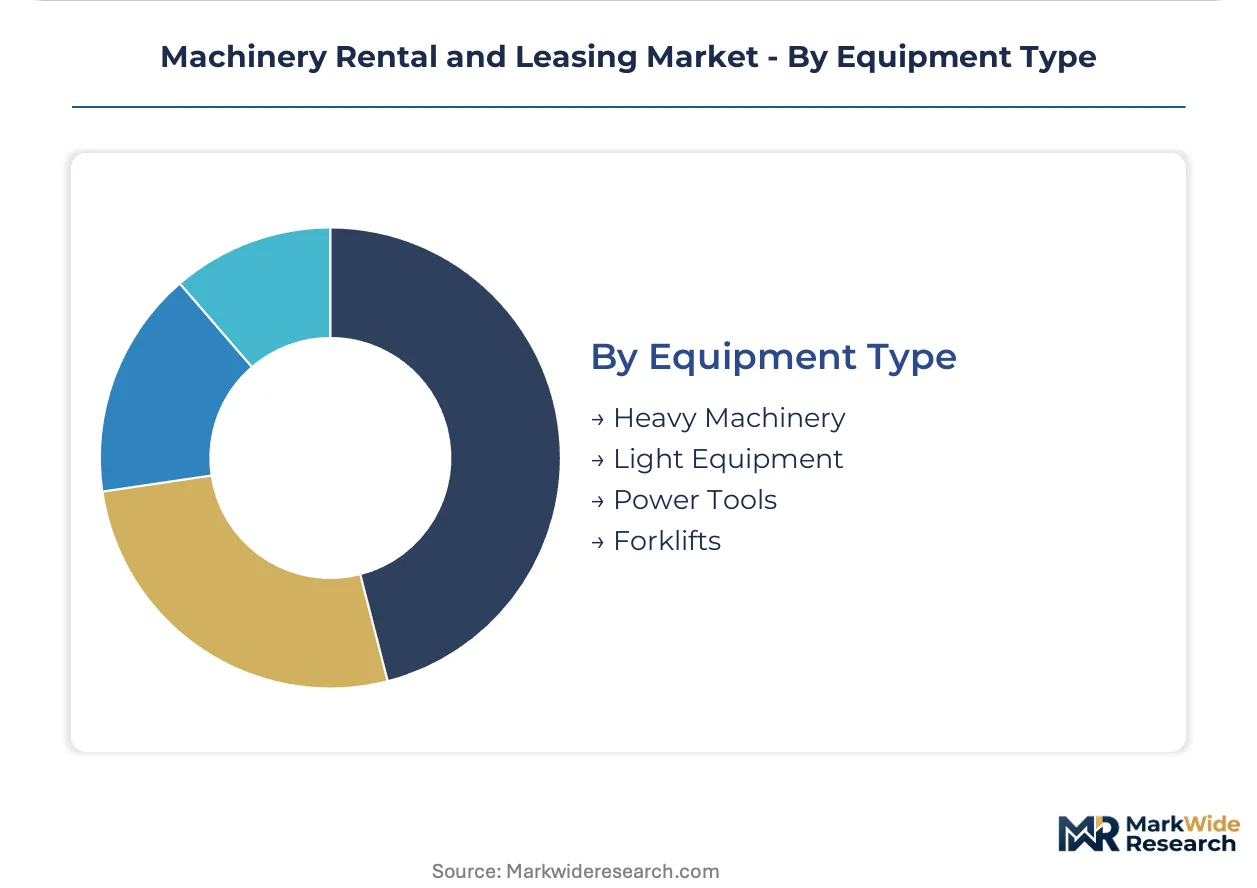
Equipment Type:
Asset weight class separates high-capital heavy machinery from portable tool categories with faster inventory turns.
- Heavy Machinery:Crawler cranes and large excavators require specialized transport and certified operators. EPA Tier 4 Final compliance costs concentrate in this segment through aftertreatment system maintenance.
- Light Equipment:Compaction rollers and small excavators serve municipal and residential contractors with lower operator certification barriers.
- Forklifts:Warehouse and industrial material handling equipment faces accelerating electrification mandates in California and New York municipalities.
- Power Tools:Handheld and stationary equipment rotates rapidly through job sites with minimal logistics overhead.
Heavy Machinery dominates capital deployment. Forklifts are climbing the fastest on warehouse automation buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The machinery rental and leasing industry traces its modern scale to post-war United States construction expansion, where capital-intensive earthmoving fleets first shifted from ownership to operational lease structures. Equipment rental density remains highest in North American and European markets where contractor balance sheet optimization and emissions compliance create sustained outsourcing demand.
United States
Federal Infrastructure Investment and Jobs Act allocations are accelerating crawler crane and excavator deployment across Texas and Florida highway corridors. EPA Tier 4 Final enforcement through the Office of Air and Radiation mandates fleet replacement cycles that favor rental over ownership for compliance cost absorption. Houston and Dallas-Fort Worth construction clusters concentrate multi-year fleet management contracts with utilization guarantees.
Germany
Industrial manufacturing turnarounds and renewable energy construction drive precision machinery rental demand across the Rhine-Ruhr and Bavarian industrial zones. EU Green Deal alignment through the Federal Ministry for Economic Affairs and Climate Action incentivizes electric compact equipment procurement for urban job sites. Munich and Stuttgart metropolitan contractors specify zero-emission mini-excavators for noise-restricted municipal infrastructure.
China
High-speed rail and urban metro expansion sustain earthmoving equipment utilization across Yangtze River Delta and Pearl River Delta construction corridors. Ministry of Ecology and Environment dual carbon goals accelerate electric forklift and telehandler adoption in Shenzhen and Shanghai logistics hubs. State-backed infrastructure stimulus concentrates rental demand in provincial capital construction clusters.
United Kingdom
Commercial build-to-rent residential development and data center construction drive aerial lift and material handling rental across Greater London and the Southeast. Health and Safety Executive workplace safety mandates shape enclosed cab specifications for demolition and silica-exposed applications. Manchester and Birmingham regeneration zones absorb premium rates for telematics-enabled fleet solutions.
India
National highway expansion and smart city infrastructure sustain excavator and compactor rental demand across Maharashtra and Gujarat state construction corridors. Central Pollution Control Board construction equipment emissions norms in Delhi-NCR and Mumbai metropolitan regions accelerate retirement of older diesel units. Bangalore and Hyderabad technology campus buildouts concentrate warehouse forklift and telehandler deployment.
Machinery Rental and Leasing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fleet telematics integration and maintenance bundling sophistication. The market exhibits consolidated leadership at the national scale with fragmented regional specialists competing on equipment availability and logistics responsiveness. Three archetypes dominate: integrated national networks with branch density advantages, specialty providers focusing on climate control and power generation, and technology-enabled platforms leveraging IoT fleet management. Competitive dynamics center on strategic acquisitions to extend geographic coverage and capital deployment toward electric and dual-fuel equipment platforms.
Among North American rental operators, United Rentals Inc. and Herc Holdings Inc. occupy positions within the integrated national network tier, while Ashtead Group plc represents the transatlantic scale-driven archetype bridging United States Sunbelt operations with European market presence. These entities exemplify how branch network density and fleet diversification create competitive separation from regional specialists.
| Leading Market Players |
|---|
| United Rentals Inc. |
| Ashtead Group plc (Sunbelt Rentals) |
| Herc Holdings Inc. (Herc Rentals) |
| WillScot Mobile Mini Holdings Corp. |
| H&E Equipment Services Inc. |
| Loxam Group |
| Aggreko plc |
| Sunstate Equipment Co. |
| EquipmentShare |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up rental specialists concentrate fleet ownership across North American metropolitan markets, translating scale economies into disciplined rate-setting power while compressing supplier payment terms to offset steel and hydraulic component volatility.
Pricing Analysis
Long-term fleet management contracts with utilization guarantees anchor revenue stability for multi-year highway and bridge projects. Three-tier pricing structure across premium telematics-enabled fleets, standard compliant diesel units, and economy-tier older equipment separates contractors by project sophistication and emissions requirements. Cost compression in the economy tier intensifies because EPA Tier 4 Final compliance deadlines accelerate retirement of pre-2015 engines. Event organizers and seasonal agricultural users exhibit the highest price sensitivity, while infrastructure contractors with federal funding lock-in demonstrate the lowest.
Supply Chain Analysis
Freight costs for crawler crane and large excavator transport absorb disproportionate margin impact given specialized flatbed requirements and pilot car escort regulations across state lines. Equipment manufacturing concentrates in the United States, Japan, and Germany, with final assembly and engine integration drawing from Tier 1 supplier networks in Illinois, Aichi prefecture, and Baden-Württemberg. Steel plate and hydraulic cylinder sourcing rests on commodity price volatility and single-source vulnerability for precision-machined components. Distribution runs through national branch networks with regional depot pooling, supplemented by on-premises yard placement for contractor concentration zones in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machinery rental margin expansion hinges on telematics-enabled utilization optimization transferring operational risk to lessors while commanding premium rates for data-driven fleet guarantees.
For Market Incumbents: Hedge residual value exposure by front-loading capital deployment toward electric compact equipment and dual-fuel platforms eligible for California municipal contracts. Deepen backward integration into predictive maintenance service capabilities to capture recurring revenue beyond base rental rates. Consolidate regional specialists in Sunbelt growth corridors to extend branch density advantages against telematics-enabled challengers. For New Entrants and Emerging Players: IoT-native fleet management platforms offer a technology-first wedge into contractor segments frustrated by legacy ERP integration failures at established providers. Target specialty industrial turnaround equipment—climate control and power generation—where Herc Holdings has validated premium pricing but branch coverage remains thin. Pursue direct sales to e-commerce fulfillment developers in Dallas-Fort Worth and Phoenix logistics hubs bypassing national account teams. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with fleet age profiles requiring near-term Tier 4 Final replacement capex but embedded customer relationships in high-growth construction corridors. Five-to-ten-year viability favors providers with demonstrated telematics adoption rates and maintenance bundling attach rates above industry medians. Monitor equipment telematics penetration rates as the inflection signal separating premium-margin data-driven operators from commodity rental providers.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | IoT-enabled utilization tracking reduces idle time and optimizes asset deployment across multi-site contractor networks. |
| Electric Fleet Transition | Battery-powered compact equipment penetrates California municipal contracts with noise and emissions restrictions. |
| Predictive Maintenance Bundling | Service contracts tied to telematics data streams create recurring revenue anchors beyond base rental rates. |
| Regional Specialist Acquisition | Branch density extension in Texas and Florida locks in volume commitments through project completion milestones. |
| Specialty Equipment Expansion | Climate control and power generation offerings differentiate positioning for industrial turnaround project demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, construction contractor procurement leads, OEM regional sales managers, and equipment finance underwriters with secondary validation through SEC 10-K filings, Association of Equipment Manufacturers shipment data, and EPA compliance certification databases. Bottom-up equipment unit deployment estimates triangulated against top-down infrastructure spending allocations.
Segment-weighting across service type, contract duration, end user category, and equipment weight class drove analytical framework construction across the projection horizon. CAGRs derived from historical utilization rate trajectories, fleet replacement cycle compression under Tier 4 Final mandates, and e-commerce fulfillment center construction pipelines. Forecast inputs incorporated Federal Reserve interest rate posture impacts on lease-versus-buy decisions and diesel-electric powertrain substitution elasticities.
The model holds under sustained infrastructure spending and emissions enforcement continuity; deviation in steel price volatility or certified operator supply constraints would shift fleet deployment timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Embedded Lending Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Truck Financial Leasing Market