
 France Metal Fabrication Equipment Market | 2026-2036
France Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
France Metal Fabrication Equipment Market Foresight
The EU Green Deal's industrial decarbonization mandates is rebalancing procurement criteria toward energy-efficient electric and CNC-controlled systems. Trumpf France leverages its laser technology leadership to dominate high-precision aerospace contracts. Amada France anchors its position through extensive service networks across French metal workshops. LVD Group specializes in customized press brake configurations for tier-1 automotive suppliers.
France metal fabrication equipment encompasses machinery for cutting, forming, joining, and finishing metallic workpieces, typically operating at tolerances of ±0.1 mm for CNC laser systems and generating cutting speeds exceeding 100 m/min on thin-gauge steel. Its primary purpose centers on transforming raw metal stock into precision components for industrial assembly chains. Laser cutting machines command the largest installed base among product types, reflecting aerospace and shipbuilding demand for complex geometries. Electric technology variants capture the fastest expansion trajectory as French factories retrofit hydraulic lines to meet factory energy efficiency codes. CNC-controlled systems concentrate margin pools in software-integrated maintenance contracts and remote diagnostics services.
France's regulatory environment binds equipment suppliers through CE marking conformity, REACH material compliance for lubricants and coatings, and the EU AI Act's emerging protocols for autonomous CNC programming modules. ANSM and CNIL oversight extends into industrial data governance as connected fabrication lines transmit production telemetry across supplier networks. Stakeholders must monitor how the EU F-Gas Regulation's phase-down schedules affect hydraulic system refrigerant alternatives and electric actuator substitution timelines.
Market Dynamics
The EU Green Deal's industrial decarbonization mandates are forcing French metal fabricators to retire hydraulic press brakes ahead of normal replacement cycles, compressing equipment refresh timelines and redirecting capital toward electric servo-electric systems.
Growth Catalysts
- EU F-Gas Regulation phase-down:The mandated reduction in hydrofluorocarbon refrigerants accelerates factory conversions from hydraulic to all-electric press brake architectures. French automotive suppliers in Grand Est are prioritizing electric retrofits to maintain production continuity.
- Aerospace precision demands:Safran and Airbus supply chain specifications require ±0.05 mm forming tolerances. This specification pull drives CNC laser system upgrades across tier-2 fabricators in Occitanie and Nouvelle-Aquitaine.
- Factory energy efficiency codes:The French government's tertiary sector decree mandates 40% energy reduction targets by 2030. Metal workshops in Île-de-France are replacing legacy hydraulic lines with regenerative electric drives to comply.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electric servo motors depend on neodymium and copper windings. Price swings in these inputs compress margin visibility for equipment OEMs quoting multi-year maintenance contracts.
- German component supply concentration:Critical CNC control systems and linear motion components originate from Baden-Württemberg suppliers. Geopolitical friction or logistics disruption propagates directly into French delivery schedules.
- Hydraulic system sunk costs:Existing press brake installed base represents decades of amortized capital. The functional adequacy of legacy equipment for standard gauge work delays replacement decisions despite efficiency gaps.
Strategic Opportunities
- Brittany shipbuilding revival:Naval Group's submarine and surface vessel programs require thick-plate cutting and forming capacity. Local fabricators in Brest and Lorient corridors present untapped demand for high-tonnage press brakes.
- AI Act autonomous programming modules:The EU AI Act's risk classification framework creates first-mover advantage for vendors embedding certified generative CNC programming. French aerospace OEMs are piloting self-optimizing laser nesting algorithms.
- Remanufacturing-as-a-service:Circular economy mandates under the EU Green Deal favor equipment life extension. Independent service networks in Auvergne-Rhône-Alpes are building certified remanufacturing capabilities for electric drive retrofits.
Industry Challenges
- CNC programming specialist scarcity:The convergence of laser physics, servo dynamics, and CAM software exceeds traditional mechanical technician training. French technical institutes are struggling to graduate operators proficient in multi-axis coordination.
- CE marking conformity timeline compression:The Machinery Directive's updated essential safety requirements demand revised documentation for software-integrated systems. Certification delays of six to nine months strand finished equipment in factory acceptance limbo.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Metal Fabrication Equipment Market |
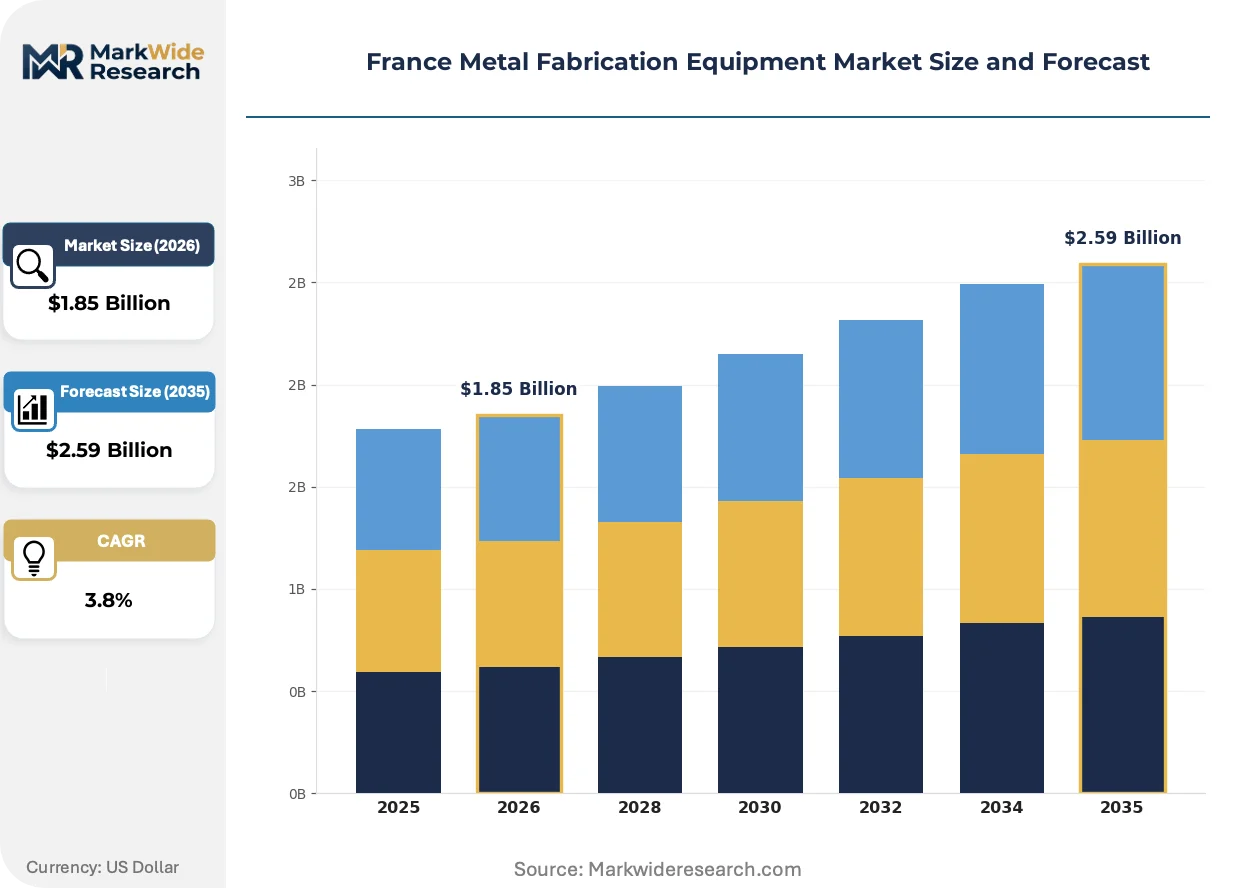
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Cutting Machines, CNC Press Brakes, Welding Equipment, Punching Machines, Bending Machines Technology: Hydraulic, Mechanical, Electric, Pneumatic, CNC Controlled Application: Shipbuilding, Aerospace, Construction, Heavy Machinery, Consumer Goods Manufacturing End User: Tier-1 Suppliers, Metal Workshops, Industrial Manufacturers, Maintenance Service Providers |
| Companies Covered | Trumpf France, Amada France, LVD Group, Bystronic France, Fives Group, Schuco International, JIER Group, Hurco, AIA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Metal Fabrication Equipment Market Shifts & Advancements
Electrification of forming equipment is compressing the technology lifecycle in French metal workshops, while regulatory pressure on industrial emissions accelerates software-integrated system architectures.
Fiber laser cutting systems are consolidating their position as the dominant sheet metal processing technology. Aerospace subcontractors in Toulouse and Nantes corridors are standardizing on 6 kW and 12 kW fiber platforms for aluminum and titanium alloys. This consolidation is compressing CO2 laser aftermarket service revenue and redirecting vendor R&D toward beam delivery optics and automated nozzle changers.
The EU AI Act's risk-based classification for autonomous manufacturing systems imposes conformity assessment obligations on CNC equipment with self-optimizing capabilities. French metal fabricators deploying generative nesting algorithms must now document training data provenance and decision audit trails. High-precision aerospace suppliers are absorbing these compliance costs fastest, while general job shops defer AI-enabled upgrades pending regulatory clarity from ANSM and notified body guidance.
Service contract unbundling is fragmenting the traditional equipment-vendor relationship. French automotive tier-1 suppliers are separating hardware procurement from software maintenance and predictive analytics subscriptions. This disintermediation is most visible in the Grand Est supplier corridor, where buyers negotiate laser source maintenance independently of motion system service agreements, compressing OEM aftermarket capture rates.
France Metal Fabrication Equipment Market Segmentation
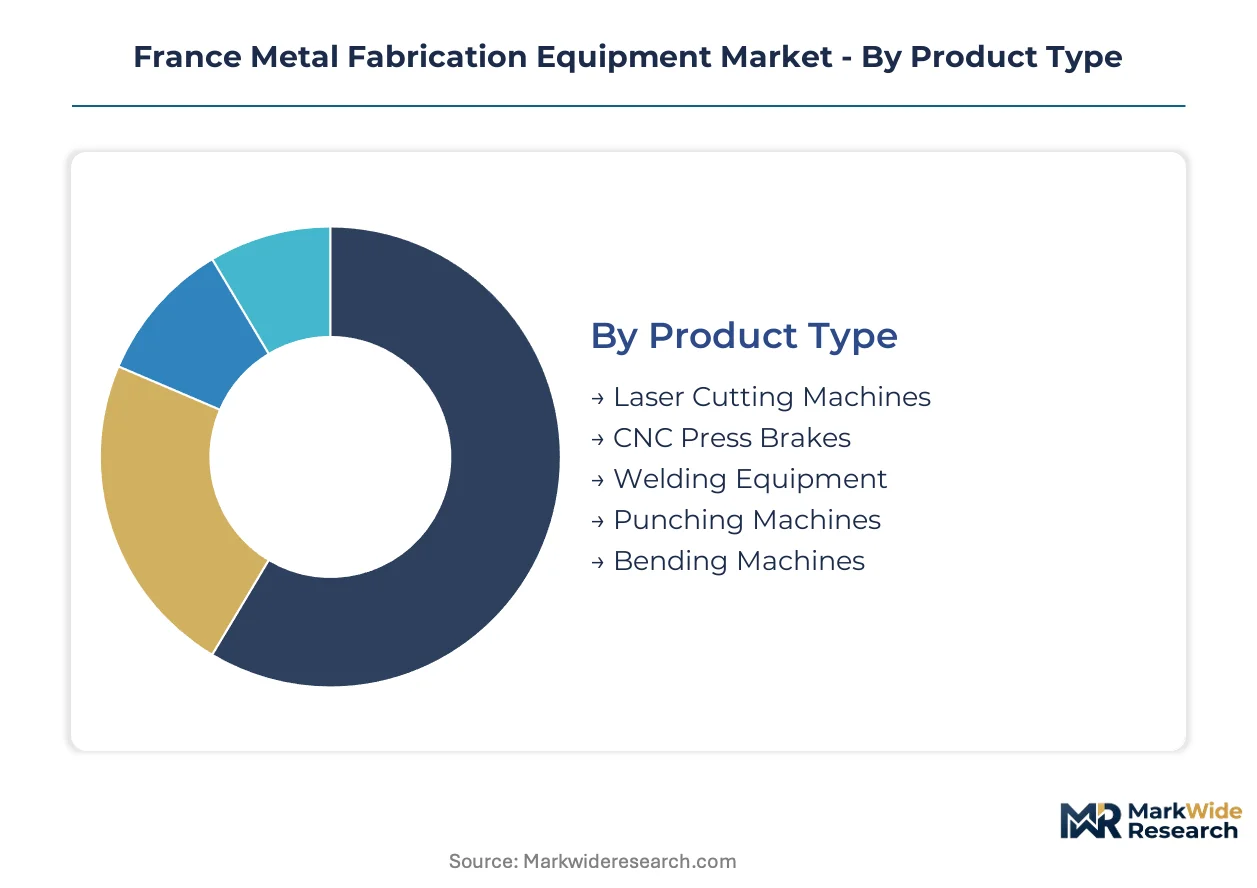
Equipment segmentation in France reveals distinct procurement patterns across aerospace precision mandates, automotive supplier consolidation, and shipbuilding thick-plate requirements. Buyers prioritize technology trajectories that align with EU Green Deal compliance timelines and CE marking conformity obligations.
Product Type:
Capital allocation decisions hinge on installed base replacement cycles and energy efficiency retrofit deadlines imposed by French factory codes.
- Laser Cutting Machines:Fiber laser platforms dominate thin-gauge processing with cutting speeds exceeding 100 m/min on aluminum and titanium alloys. Aerospace subcontractors in Toulouse and Nantes corridors standardize on 6 kW and 12 kW systems to meet Airbus supply chain specifications for complex geometries.
- CNC Press Brakes:Electric servo-electric architectures are displacing hydraulic lines as Grand Est automotive suppliers retrofit ahead of EU F-Gas Regulation phase-down schedules. Regenerative drives capture braking energy to meet tertiary sector energy reduction targets.
- Welding Equipment:Automated MIG and TIG systems serve Naval Group shipbuilding programs in Brest and Lorient.
- Punching Machines:Turret configurations persist in general job shops processing standard gauge steel.
- Bending Machines:Tube and profile benders concentrate in construction equipment fabrication clusters.
Laser Cutting Machines lead on scale; CNC Press Brakes lead on momentum.
Technology:
Factory energy audits are rebalancing technology portfolios toward architectures with measurable carbon intensity reductions.
- Electric:Servo motor actuation eliminates hydraulic fluid maintenance and enables precision positioning to ±0.05 mm. French workshops in Île-de-France prioritize electric retrofits to comply with 40% energy reduction mandates by 2030.
- CNC Controlled:Software-integrated systems embed predictive maintenance and remote diagnostics capabilities. Aerospace tier-2 fabricators absorb premium pricing for ANSM-compliant data governance and EU AI Act risk classification protocols.
- Hydraulic:Legacy installed base represents decades of amortized capital in general fabrication.
- Mechanical:Clutch-brake architectures persist in low-volume, high-tonnage forming applications.
- Pneumatic:Compressed air systems retain niche positioning in clean-room consumer goods manufacturing.
CNC Controlled systems anchor margin pools; Electric variants are climbing the fastest.
Application:
End-use demand fragmentation requires vendors to configure service networks around distinct tolerance and throughput requirements.
- Aerospace:Precision forming to ±0.05 mm tolerances drives fiber laser and electric press brake adoption. Safran supply chain specifications cascade through Occitanie and Nouvelle-Aquitaine fabricator networks.
- Shipbuilding:Thick-plate cutting and high-tonnage forming capacity supports Naval Group submarine and surface vessel programs. Brittany fabricators in Brest and Lorient corridors present untapped demand for specialized equipment configurations.
- Construction:Structural steel processing concentrates in standardized beam and column fabrication.
- Heavy Machinery:Mining and agricultural equipment demands robust thick-gauge forming systems.
- Consumer Goods Manufacturing:High-volume, lower-tolerance production favors cost-optimized mechanical solutions.
Aerospace commands premium pricing; Shipbuilding shows the steepest expansion trajectory.
End User:
Procurement authority concentration varies across integrated OEMs, distributed job shops, and independent service networks.
- Tier-1 Suppliers:Grand Est automotive corridors negotiate unbundled contracts separating hardware procurement from software maintenance and predictive analytics subscriptions. Buyers source laser source maintenance independently of motion system service agreements.
- Metal Workshops:Distributed fabricators across Auvergne-Rhône-Alpes prioritize equipment life extension and certified remanufacturing capabilities under circular economy mandates.
- Industrial Manufacturers:Integrated producers maintain captive maintenance capabilities for high-utilization assets.
- Maintenance Service Providers:Independent networks build certified electric drive retrofit competencies to capture aftermarket revenue from efficiency mandates.
Tier-1 Suppliers concentrate purchasing volume; Maintenance Service Providers are gaining share fastest through retrofit specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French CNC programming specialists and servo motor engineers concentrate in Grand Est and Île-de-France industrial corridors. Their technical density anchors equipment procurement decisions across tier-1 automotive and aerospace supply chains.
Île-de-France
Precision fabrication workshops in Paris-Saclay cluster absorb electric press brake retrofits to meet tertiary sector energy reduction mandates. The French government's 40% efficiency targets by 2030 compress replacement timelines for legacy hydraulic systems. Metal workshops in Seine-Saint-Denis and Val-d'Oise prioritize regenerative electric drives with ANSM-compliant data telemetry.
Grand Est
Automotive tier-1 suppliers in Metz-Nancy corridor negotiate unbundled procurement contracts separating hardware from predictive analytics subscriptions. EU F-Gas Regulation phase-down schedules accelerate conversions from hydraulic to all-electric press brake architectures. Stellantis supply chain specifications cascade through Moselle and Meurthe-et-Moselle fabricator networks.
Occitanie
Aerospace subcontractors around Toulouse-Blagnac upgrade fiber laser systems to meet Safran ±0.05 mm forming tolerance requirements. The EU AI Act's risk classification protocols impose conformity assessment obligations on self-optimizing CNC programming modules. Tier-2 fabricators in Haute-Garonne absorb premium pricing for certified autonomous nesting algorithms.
Brittany
Naval Group submarine and surface vessel programs in Brest-Lorient corridor generate thick-plate cutting and high-tonnage forming demand. Shipyards require specialized press brake configurations for hull section fabrication. Local fabricators in Finistère and Morbihan present untapped demand for equipment vendors with marine certification capabilities.
Auvergne-Rhône-Alpes
Independent service networks in Lyon-Saint-Étienne corridor build certified remanufacturing capabilities for electric drive retrofits. Circular economy mandates under the EU Green Deal favor equipment life extension over replacement. Maintenance providers in Rhône and Loire capture aftermarket revenue from efficiency-driven refurbishment demand.
France Metal Fabrication Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across French metal fabrication equipment procurement. Integrated European OEMs with captive manufacturing anchor premium-tier positioning through direct sales networks and software-integrated service contracts. The vendor base fragments across German-origin technology licensors, French distribution specialists, and Asian scale manufacturers. Strategic archetypes include laser technology originators, regional service integrators, and cost-optimized volume suppliers. Competitive moves concentrate on geographic service density expansion and predictive maintenance platform differentiation.
Within the technology-originator tier, Trumpf France and Amada France occupy positions defined by installed base scale and aftermarket capture depth. LVD Group exemplifies the regional specialization archetype, anchoring its competitive position through customized press brake configurations. These three entities represent distinct strategic postures: laser platform dominance, extensive service network coverage, and automotive supplier application focus respectively.
| Leading Market Players |
|---|
| Trumpf France |
| Amada France |
| LVD Group |
| Bystronic France |
| Fives Group |
| Schuco International |
| JIER Group |
| Hurco |
| AIA |
| Others |
Supply & Pricing Matrix
Grand Est automotive suppliers' unbundled procurement contracts—splitting hardware from predictive analytics subscriptions—are compressing OEM aftermarket capture rates and forcing vendors to restructure service pricing architectures.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across French metal fabrication equipment. Tier-1 suppliers negotiate laser source maintenance independently from motion system service agreements, fragmenting traditional vendor relationships. Price differentiation rests on certification grade for EU AI Act compliance and geographic service density for emergency response. Cost compression in electric servo retrofits is intensifying because copper and rare-earth magnet volatility squeezes multi-year contract margins. General job shops exhibit highest price sensitivity; aerospace tier-2 fabricators absorb premium pricing for ANSM-compliant data governance.
Supply Chain Analysis
CNC programming specialist scarcity in Baden-Württemberg, Stuttgart, and Munich manufacturing corridors propagates directly into French delivery schedules for control systems and linear motion components. Equipment OEMs draw from German-origin technology licensors for critical servo motors, French distribution specialists for localized service networks, and Asian scale manufacturers for commodity mechanical subassemblies. Supply chain risk centers on single-source vulnerability for neodymium magnet supply from concentrated rare-earth processors. Distribution runs through direct sales networks for premium-tier systems and independent service providers for retrofit and remanufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in French metal fabrication equipment hinges on electric press brake retrofits displacing hydraulic installed base, capturing efficiency-premium pricing while input cost volatility compresses competitor margins.
For Market Incumbents: Hedge against German component supply concentration by cultivating secondary sourcing relationships for CNC control systems in Switzerland and Italy. Deepen vertical integration into regenerative drive manufacturing to capture margin pools from Île-de-France energy efficiency mandates. Prioritize ANSM certification investment for autonomous CNC programming modules ahead of EU AI Act enforcement timelines. For New Entrants and Emerging Players: Direct-to-fabricator digital platforms offer lowest-friction entry into Auvergne-Rhône-Alpes maintenance service networks, where independent providers are gaining share fastest through retrofit specialization. Target Brittany shipbuilding revival corridors for thick-plate cutting and high-tonnage forming capacity. Lead with certified remanufacturing-as-a-service to exploit circular economy mandates under the EU Green Deal. For Investors and Strategic Acquirers: Asymmetric upside sits with regional service integrators building AI Act-compliant predictive maintenance platforms. Five-to-ten year viability favors vendors with captive software-integrated maintenance contract portfolios rather than pure hardware manufacturers. Watch Naval Group procurement acceleration in Brest-Lorient corridors as inflection indicator for marine-certified equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Manufacturing | Captures margin pools from copper and rare-earth price volatility while securing supply for Grand Est automotive retrofits. |
| EU AI Act Certification Program | Creates first-mover advantage for autonomous CNC programming modules in Safran and Airbus supply chains. |
| Remanufacturing-as-a-Service Platform | Aligns with circular economy mandates and captures aftermarket revenue from efficiency-driven refurbishment demand. |
| Geographic Expansion into Brittany Shipbuilding Corridor | Addresses untapped thick-plate cutting and high-tonnage forming demand from Naval Group submarine programs. |
| Strategic Partnership with German Control System Suppliers | Mitigates single-source vulnerability for critical CNC components while maintaining technology access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with maintenance directors at Grand Est automotive suppliers, plant engineers in Île-de-France metal workshops, OEM procurement teams at aerospace tier-1s, and aftermarket service heads across Auvergne-Rhône-Alpes. Secondary validation drew from SEC filings of listed equipment manufacturers, French customs trade data for machinery imports, EU ETS industrial emissions disclosures, and ANSM regulatory guidance documents. Bottom-up equipment shipment tallies and top-down industrial energy audit projections were cross-referenced for triangulation.
Historical reference periods anchored the forecast window to installed base replacement cycles and regulatory compliance deadlines without year-specific anchoring. Segmentation modeling spanned product type, technology architecture, end-use application, and regional industrial corridor concentration. CAGRs were derived from equipment refresh timeline compression and retrofit adoption curves. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and tertiary sector energy reduction mandate enforcement patterns.
The model assumes a particular technology adoption path; alternative pathways for hydraulic-to-electric conversion timing would alter the outlook. Forecasts reflect assumptions about copper and rare-earth magnet price stabilization, ANSM regulatory clarity on AI Act implementation, and Naval Group procurement continuity. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Tower Crane Market
Construction Equipment
Bulldozer Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
US Rental Equipment Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Tunneling Equipment Market