
 Rotational Moulding Machines Market | 2026-2036
Rotational Moulding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Rotational Moulding Machines Market Outlook
The split between premium automated cells and commodity batch equipment is recalibrating competitive economics across the sector. Persico Group leverages its Italian engineering base to dominate high-throughput shuttle systems for automotive OEMs. Ferry Industries Inc. anchors North American demand with extensive service networks and aftermarket parts availability. Reinhardt Roto Machines specializes in custom-built installations for complex industrial geometries, occupying a defensible niche above standard product lines.
Rotational moulding machines heat and rotate hollow molds to form seamless thermoplastic parts, typically processing polyethylene at temperatures between 260°C and 370°C while maintaining bi-axial rotation ratios that control wall thickness distribution. These systems produce chemical-resistant tanks, playground equipment, and vehicle components where structural uniformity and stress-free construction matter. Shuttle type configurations lead factory-installed base demand due to their parallel cooling and loading efficiency, while electric technology represents the fastest-expanding segment as energy costs and emissions compliance reshape processor preferences. Hybrid systems capture margin pools in retrofit environments where gas infrastructure cannot be abandoned immediately.
EPA emissions standards in the United States and EU F-Gas Regulation in Europe constrain gas-fired equipment specifications and accelerate electric conversion timelines. India's BIS certification for polyethylene water storage tanks creates mandatory testing protocols that only precision-controlled machines can reliably satisfy. ISO 9001 quality management and CE marking requirements filter market access for smaller Asian suppliers. Stakeholders must monitor carbon border adjustment mechanisms and evolving polymer recycling mandates to time capital deployment across heating technology platforms.
Market Dynamics
EU ETS carbon pricing is compressing payback periods for electric heating retrofits while India's BIS certification mandates force processor upgrades across Gujarat's captive mold clusters. Equipment procurement decisions now hinge on emissions compliance timelines rather than throughput metrics alone.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases accelerate electric heating adoption in European rotational moulding plants, expanding addressable market for hybrid system suppliers.
- Water tank standardization:India's BIS certification for polyethylene storage creates mandatory precision requirements that only automated shuttle systems reliably satisfy, concentrating demand among certified equipment vendors.
- Automotive lightweighting:Fuel economy mandates from NHTSA and EPA drive hollow-part substitution for metal fuel tanks and HVAC housings, pulling high-throughput shuttle configurations into Tier 1 supplier facilities.
Market Restraints
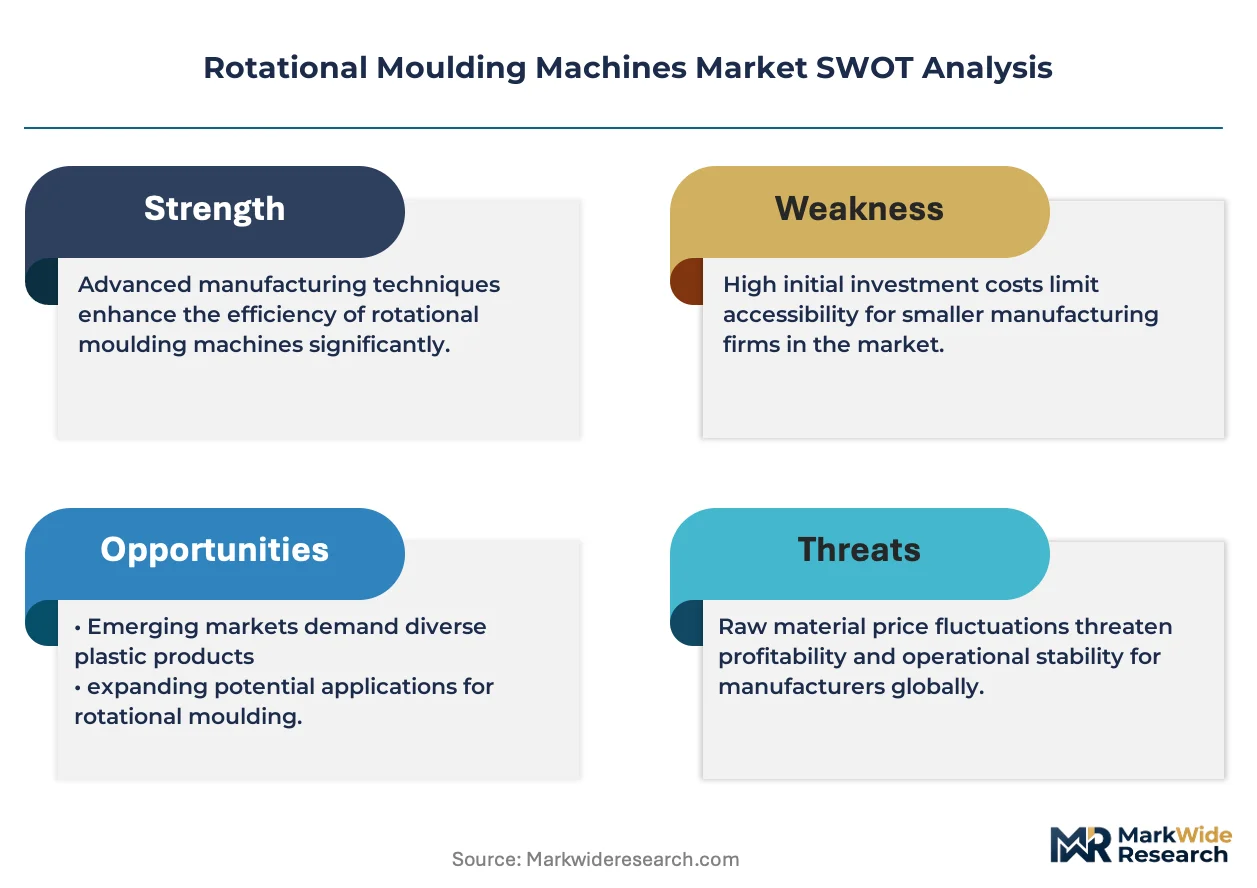
- Steel and aluminum price volatility:Mold fabrication costs fluctuate with commodity metals markets, squeezing margins for custom-built machine specialists serving complex industrial geometries.
- Specialized technician scarcity:Bi-axial rotation ratio calibration and thermal profiling require skills concentrated in Northern Italy and Gujarat, limiting expansion into underpenetrated processing regions.
- Blow molding substitution:High-volume tank producers below 500-liter capacity increasingly adopt extrusion blow molding for cycle-time advantages, constraining rotational moulding's addressable volume at the commodity end.
Strategic Opportunities
- Indonesian infrastructure buildout:National water security programs drive polyethylene tank demand across Java and Sumatra, creating first-mover advantage for equipment suppliers establishing local service presence.
- Recycled polymer integration:EU Green Deal recycling mandates and polymer traceability requirements favor rotational moulding's inherent compatibility with regrind materials versus injection processes.
- Digital twin convergence:Integration of thermal simulation software with machine controls enables predictive wall-thickness optimization, opening premium pricing tiers for data-enabled equipment packages.
Industry Challenges
- CE marking timeline compression:Evolving machinery safety directives extend certification cycles for European-bound equipment, delaying revenue recognition for export-focused manufacturers.
- Legacy gas infrastructure stranding:Hybrid system adoption requires parallel maintenance of combustion and electric heating competencies, stretching technical service organizations across incompatible skill domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotational Moulding Machines Market |
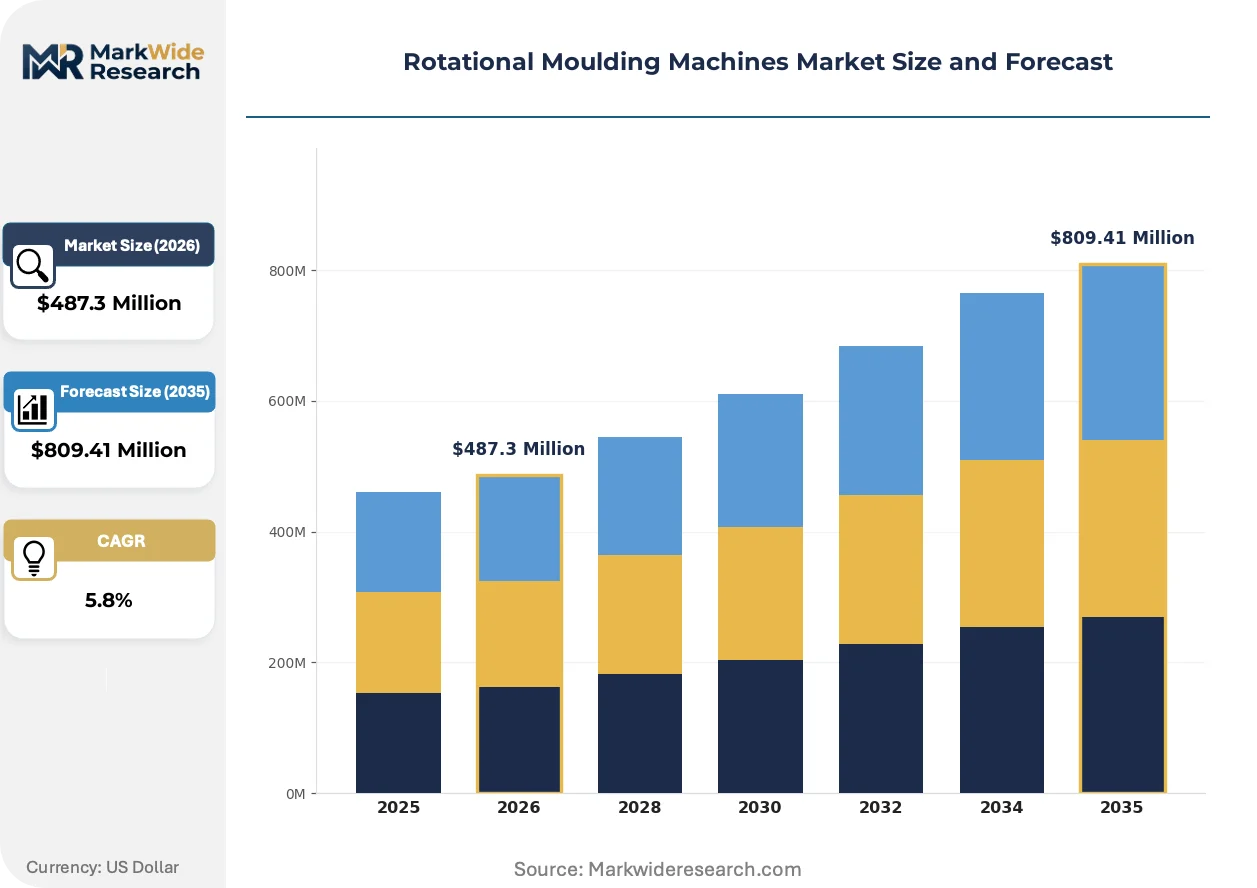
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Arm, Dual Arm, Shuttle Type, Vertical Type End User: Automotive OEMs, Consumer Goods, Industrial Applications, Construction Technology: Gas Fired, Electric, Hybrid, Infrared Installation: Factory Installed, On-site, Modular, Custom-built |
| Companies Covered | Rotomachinery Group, Orex Rotomoulding, Persico Group, Fixopan Rotomoulding Machines, Polivinil Rotomachinery, Rotoline Machinery, Reinhardt Roto Machines, Caccia Engineering, Ferry Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotational Moulding Machines Market Strategic Shifts
Active thermal management and predictive control architectures are displacing fixed-cycle programming across installed bases. Equipment differentiation now centers on energy recovery systems and polymer traceability integration rather than mechanical reliability alone.
Inductive heating technology is automating mold temperature profiling through embedded sensor arrays and real-time power adjustment algorithms. Automotive OEMs in Germany and Tier 1 suppliers in Michigan are piloting these configurations for fuel tank production, compressing cycle-to-cycle variation below 3 percent. The technology is automating quality assurance overhead while enabling thinner wall specifications that reduce polymer consumption per part.
REACH authorization procedures for polymer additives are restricting flame-retardant compound availability for playground equipment and marine applications. European processors face reformulation costs and extended testing protocols, pushing specification authority upstream to material suppliers. The regulation most affects small-batch custom molders serving municipal procurement contracts with mandatory EN 1176 certification requirements.
Specification authority is consolidating among polymer compounders and brand-owner sustainability officers, displacing traditional equipment vendor relationships. Water tank distributors in India now source turnkey production cells including mold fabrication and BIS compliance documentation rather than procuring machinery separately. This consolidation is most visible in Gujarat's industrial corridor, where captive mold clusters bundle equipment, tooling, and certification support into single-vendor contracts.
Rotational Moulding Machines Market Segmentation
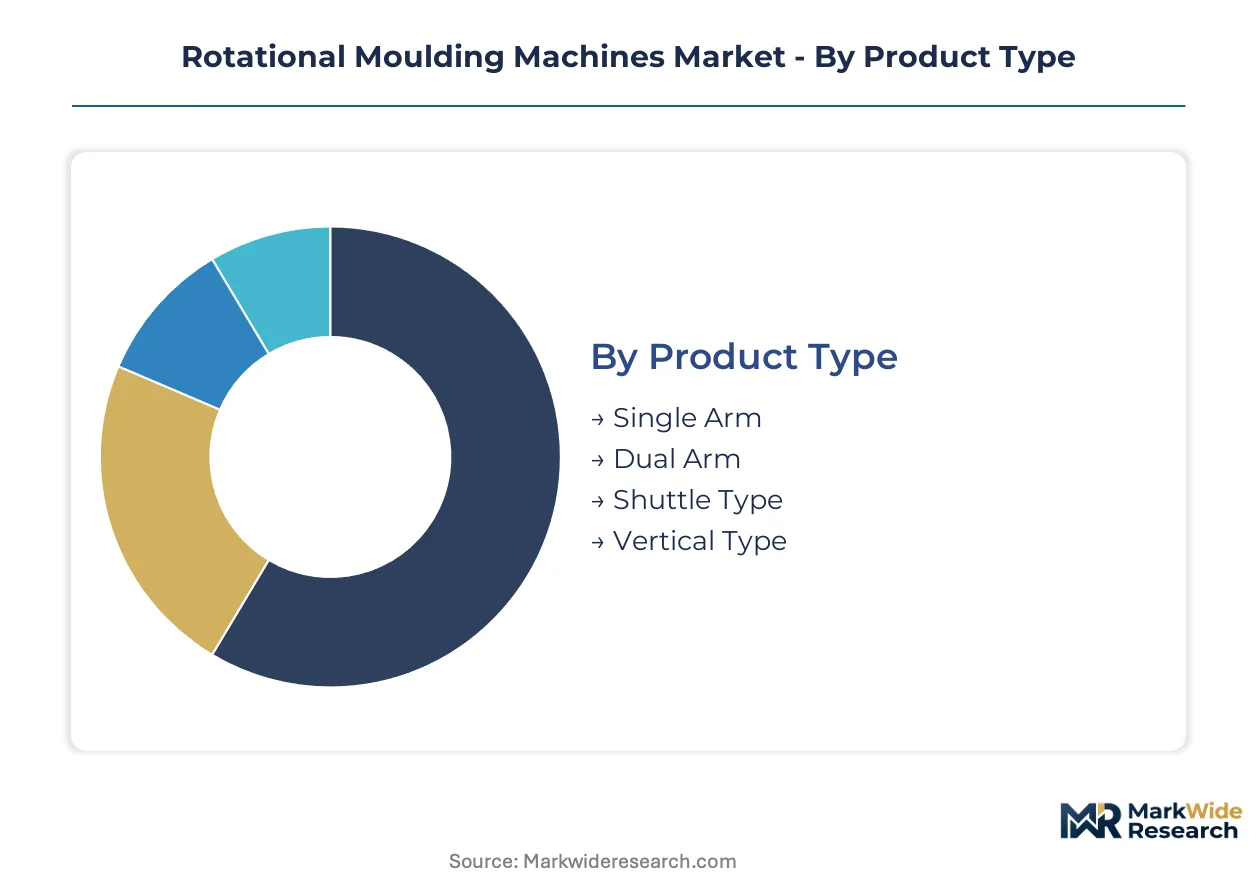
Segmentation in rotational moulding equipment reflects divergent capital deployment strategies across processor tiers. High-volume producers prioritize throughput automation while specialty molders optimize for geometric flexibility and energy compliance.
Product Type:
Volume leadership concentrates in parallel-processing configurations, while premium positioning attaches to custom-engineered geometries demanding precise wall-thickness control.
- Shuttle Type:Parallel cooling and loading stations eliminate idle time between cycles, delivering throughput advantages for automotive OEMs and water tank manufacturers in Gujarat's industrial corridor. Indian processors facing BIS certification mandates favor these systems for consistent precision.
- Single Arm:Entry-level processors and specialty molders deploy these systems for complex industrial geometries where batch flexibility outweighs cycle speed. Lower capital requirements support smaller operations in Southeast Asian emerging markets.
- Dual Arm:Mid-tier processors balance throughput against footprint constraints.
- Vertical Type:Niche applications for oversized tanks and playground equipment dominate this category.
Mature deployment sits with Single Arm systems. Newer deployment is concentrated in Shuttle Type configurations.
End User:
Application-driven segmentation separates commodity volume plays from defensible margin pools anchored in regulatory compliance and specification authority.
- Automotive OEMs:Fuel economy mandates from NHTSA and EPA drive hollow-part substitution for metal fuel tanks and HVAC housings. Tier 1 suppliers in Michigan and Germany pilot inductive heating configurations for sub-3% cycle-to-cycle variation.
- Industrial Applications:Chemical-resistant tank production for process industries demands complex geometries and corrosion specifications. Custom-built installations from specialized European vendors capture premium pricing here.
- Consumer Goods:Playground equipment and marine applications face REACH authorization constraints on flame-retardant compounds.
- Construction:Polyethylene water storage tanks for residential and commercial infrastructure dominate demand in India and Indonesia.
Specification authority concentrates with Automotive OEMs. Margin expansion is accelerating fastest among Industrial Applications.
Technology:
Heating platform selection now hinges on emissions compliance timelines rather than energy cost alone, compressing payback period calculations for electric retrofits.
- Electric:Embedded sensor arrays and real-time power adjustment automate mold temperature profiling. EU F-Gas Regulation phase-down schedules accelerate adoption across European plants under carbon pricing pressure.
- Hybrid:Parallel gas and electric systems capture retrofit environments where combustion infrastructure cannot be abandoned immediately. European processors stranded between legacy equipment and ETS compliance drive demand.
- Gas Fired:Dominates installed base in regions without carbon pricing mechanisms.
- Infrared:Emerging configuration for targeted heating applications in thin-wall part production.
Installed base dominance remains with Gas Fired systems. Technology transition is concentrating procurement decisions in Hybrid configurations.
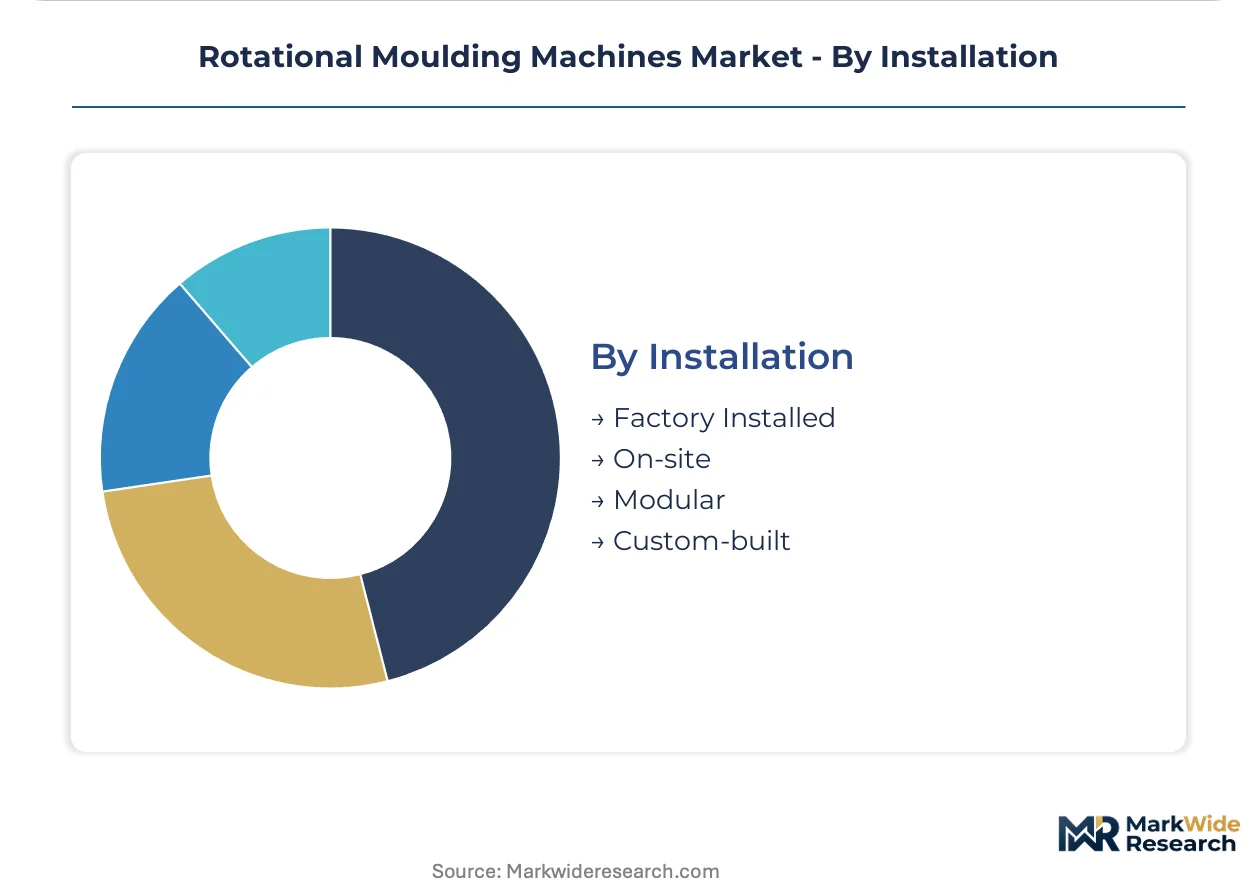
Installation:
Procurement modality reflects supply chain consolidation trends, with bundled turnkey solutions displacing component-level purchasing in key markets.
- Factory Installed:Complete production cells including mold fabrication and compliance documentation now dominate Indian water tank markets. Gujarat's captive mold clusters bundle equipment, tooling, and BIS certification support into single-vendor contracts.
- Custom-built:Complex industrial geometries and non-standard tank specifications require engineered-to-order installations. Reinhardt Roto Machines and comparable specialists occupy this defensible niche above standard product lines.
- On-site:Regional assembly reduces logistics costs for oversized equipment.
- Modular:Scalable configurations support capacity expansion without full replacement.
Procurement concentration is shifting toward Factory Installed solutions. Custom-built maintains pricing power in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's industrial corridor anchors rotational moulding machine procurement, where captive mold fabrication clusters compress lead times for domestic water tank manufacturers facing tightening national standards.
India
Water tank manufacturers across Maharashtra and Gujarat expand capacity as BIS certification mandates for polyethylene storage create mandatory precision requirements. The Bureau of Indian Standards enforces testing protocols that only automated shuttle systems reliably satisfy. Gujarat's captive mold clusters bundle equipment, tooling, and compliance documentation into single-vendor contracts, consolidating procurement decisions among certified vendors.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg pilot inductive heating configurations for fuel tank production, compressing cycle-to-cycle variation below three percent. EU F-Gas Regulation phase-down schedules accelerate electric heating adoption under carbon pricing pressure from EU ETS. Stuttgart-based Tier 1 suppliers integrate thermal simulation software with machine controls, enabling predictive wall-thickness optimization for hollow-part lightweighting programs.
United States
Tier 1 automotive suppliers in Michigan deploy high-throughput shuttle systems to satisfy NHTSA fuel economy mandates driving metal-to-plastic substitution. EPA emissions standards constrain gas-fired equipment specifications, accelerating electric conversion timelines across installed bases. Chicago-area processors leverage extensive aftermarket parts networks to maintain legacy equipment during technology transitions.
Indonesia
National water security programs across Java and Sumatra drive polyethylene tank demand for residential and commercial infrastructure buildout. The Ministry of Public Works and Housing coordinates rural distribution network expansion, creating first-mover advantage for equipment suppliers establishing local service presence. Surabaya-based processors represent emerging demand centers for entry-level single-arm configurations.
Italy
Specialized fabricators in Lombardy and Emilia-Romagna dominate custom-built installations for complex industrial geometries, occupying defensible niches above standard product lines. REACH authorization procedures for polymer additives restrict flame-retardant compound availability, pushing specification authority upstream to material suppliers. Persico Group leverages its Italian engineering base to engineer high-throughput shuttle systems for automotive OEMs.
Rotational Moulding Machines Market Competitive Environment
Premium-margin players sit above commodity-margin players across heating technology sophistication, with electric and hybrid configurations commanding pricing power over legacy gas-fired alternatives. The vendor base stratifies between high-throughput shuttle specialists serving automotive OEMs and custom-built installation experts capturing complex industrial geometries. Three archetypes dominate: Italian-engineered precision specialists, North American service-network anchors, and Asian volume fabricators. Competitive moves concentrate on geographic service expansion and bundled turnkey solutions displacing component-level purchasing.
Within the precision-engineering tier, Persico Group and Reinhardt Roto Machines exemplify divergent strategic positioning. Persico represents the high-throughput shuttle archetype anchored in Italian manufacturing heritage. Reinhardt occupies the custom-built installation niche for non-standard geometries. Ferry Industries Inc. anchors North American market presence through service infrastructure density. These three names illustrate how competitive differentiation maps to customer procurement modality—turnkey bundling versus component sourcing versus aftermarket dependency.
| Leading Market Players |
|---|
| Rotomachinery Group |
| Orex Rotomoulding |
| Persico Group |
| Fixopan Rotomoulding Machines |
| Polivinil Rotomachinery |
| Rotoline Machinery |
| Reinhardt Roto Machines |
| Caccia Engineering |
| Ferry Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive mold fabrication clusters in Gujarat anchor supply positioning and pricing power for Indian water tank manufacturers facing BIS certification mandates. This backward integration into tooling production compresses procurement lead times while insulating certified vendors from commodity equipment pricing cycles.
Pricing Analysis
Throughput-linked pricing anchors equipment contracts, with shuttle system vendors capturing premium positioning based on cycle consistency guarantees and BIS compliance documentation. Price differentiation separates certified automated configurations from entry-level single-arm alternatives, with carbon pricing in Europe compressing margins on gas-fired legacy systems. Cost compression in hybrid retrofit tiers intensifies as EU ETS compliance deadlines approach, while water tank distributors in Gujarat exhibit lowest price sensitivity due to bundled turnkey procurement.
Supply Chain Analysis
India's domestic-content requirements for government infrastructure contracts reshape sourcing toward captive mold clusters in Gujarat and Maharashtra. Steel and aluminum for mold fabrication draw from Indian metal processors and European specialty suppliers, creating tariff exposure on precision-grade alloys. Distribution runs through equipment vendors bundling machinery, tooling, and certification support into single-vendor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-down schedules and India's BIS mandates are forcing consolidation, eliminating uncertified fabricators unable to fund compliance investments.
For Market Incumbents: Deepen backward integration into inductive heating technology development to defend against blow molding substitution in sub-500-liter tank segments. Reinforce service infrastructure density in Michigan and Stuttgart to capture aftermarket revenue during European electric conversion cycles. For New Entrants and Emerging Players: Municipal water security programs in Surabaya and Medan represent penetrable entry points for entry-level single-arm configurations bundled with local assembly partnerships. Target Indonesian processors with factory-installed solutions including mold fabrication and compliance documentation rather than component-level sales. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Italian precision-engineering groups seeking North American service network expansion. Five-to-ten-year viability favors vendors with hybrid system portfolios bridging gas-to-electric transitions. Monitor EU carbon border adjustment mechanism expansion as inflection signal for heating technology platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mold Fabrication | Gujarat's captive clusters compress lead times for BIS-certified water tank producers. |
| Inductive Heating Technology Licensing | German automotive OEMs pilot sub-3% cycle variation configurations for fuel tank lightweighting. |
| Long-term Service Agreement Expansion | Chicago-area processors leverage aftermarket parts networks during electric conversion transitions. |
| Joint Venture for Indonesian Local Assembly | Surabaya-based partnerships address national water security program equipment requirements. |
| CE Marking and Certification Investment | EU machinery safety directive compliance filters market access for export-focused manufacturers. |
Study Parameters
Independent corroboration across plant engineers at Tier 1 automotive suppliers, procurement leads at Indian water tank distributors, and aftermarket service heads at North American equipment vendors underwrites the qualitative findings. Primary interviews with maintenance directors and OEM procurement teams combined with secondary validation from SEC filings, customs trade data, and BIS certification registries. Bottom-up equipment shipment analysis and top-down polymer processing capacity estimates provide triangulation.
Rate-of-change decomposition separates volume growth from technology mix shift and pricing evolution across the analysis window. Segmentation dimensions modeled include product type, heating technology platform, end-use application, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, capacity expansion announcements, and emissions compliance timeline acceleration. Forecast inputs incorporate EU ETS carbon price trajectories and India's BIS certification penetration rates.
Revisions become necessary when EU carbon border adjustment mechanisms expand beyond pilot sectors or when India's BIS mandates extend to additional polymer product categories. Forecasts reflect assumptions about regulatory enforcement consistency and technology substitution elasticities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
CNC Router Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Global Construction Industry Core Drill Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Robotic Total Stations (RTS) Market