
 Industrial Ovens Market | 2026-2036
Industrial Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Ovens Market Analysis
Buyer concentration among tier-one automotive and aerospace suppliers is restructuring procurement patterns across the Industrial Ovens Market. Wisconsin Oven leverages its vertical integration into control system fabrication to secure long-term service contracts with defense contractors. Harper International anchors its position through specialized graphite-heating technology for advanced materials processing. ASC Process Systems competes on geographic dominance, sustaining an installed base concentrated on the US West Coast.
An industrial oven is a thermally insulated chamber designed to generate controlled temperatures ranging from ambient to over 1,000°C for drying, curing, baking, heat-treating, or sterilizing materials and components. Convection ovens dominate volume shipments across food processing and general manufacturing due to their operational flexibility and lower capital cost. Continuous ovens represent the fastest-growing product configuration, driven by automotive and pharmaceutical demand for throughput-optimized production lines. Electric technology leads new installations where emissions compliance restricts gas-fired alternatives, though hybrid systems capture margin pools in facilities pursuing operational redundancy.
NFPA 86 governs combustion safety standards for gas and hybrid industrial ovens in the United States, while EPA emissions regulations constrain burner technology specifications and operating permits. OSHA workplace exposure limits and ISO 13577 furnace safety standards shape equipment design requirements and market access conditions across manufacturing jurisdictions. Stakeholders must monitor regulatory divergence between US and European thermal efficiency mandates when configuring product portfolios for multinational customers.
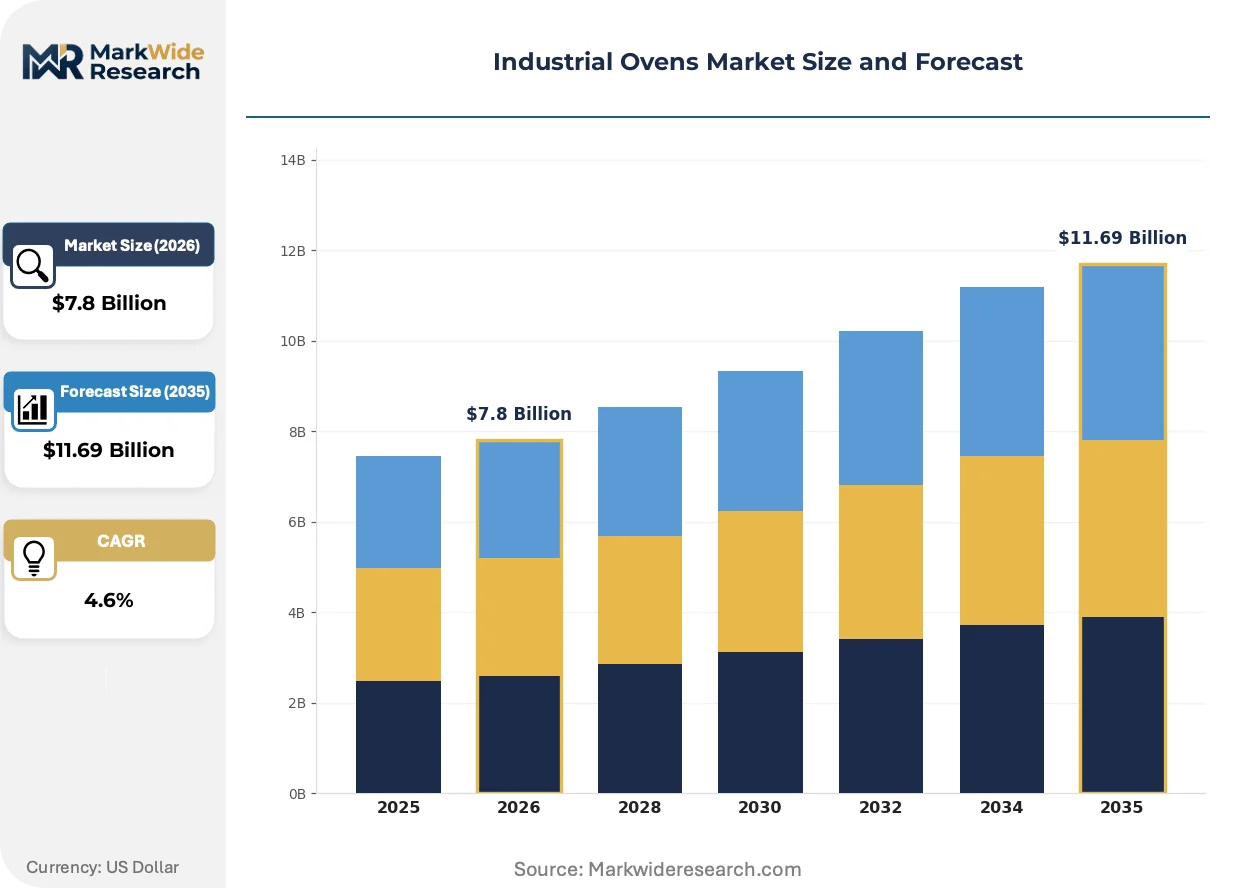
Market Dynamics
Buyer concentration among tier-one automotive and aerospace suppliers is restructuring procurement patterns across the Industrial Ovens Market, forcing equipment manufacturers to absorb extended warranty obligations and embedded service pricing into capital contracts.
Growth Catalysts
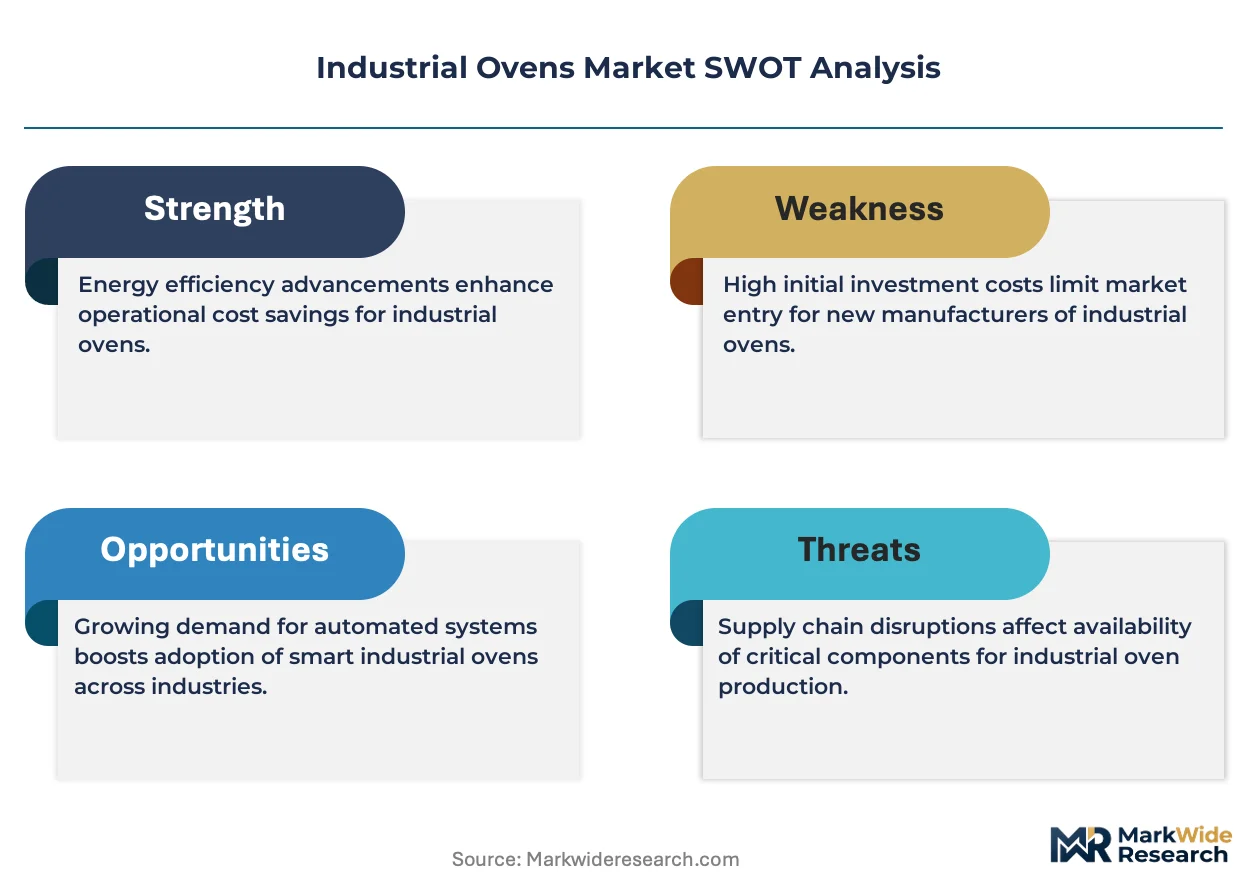
- NFPA 86 Compliance Mandates:US facilities must upgrade legacy combustion systems to meet tightened safety codes, triggering replacement cycles in heat-treatment operations.
- Automotive Supplier Clusters:Dense concentrations of tier-one suppliers in Germany are expanding capital equipment budgets for composite curing and battery thermal processing applications.
- Electric Heating Technology:Zero-emission oven configurations are capturing new installations where EPA emissions standards restrict gas-fired alternatives in food processing and pharmaceutical sterilization.
Market Restraints
- Graphite Heating Element Supply:Specialized graphite suppliers concentrate in limited geographies, exposing advanced materials processors to input cost volatility and single-source risk.
- NFPA 86 Certification Timelines:Extended third-party validation periods for custom combustion systems delay project commissioning and compress manufacturer cash conversion cycles.
- Induction Heating Substitution:Metal heat-treating applications face displacement risk from induction systems offering superior energy efficiency and reduced floor-space requirements.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO regulatory alignment with EU GMP standards is driving sterilization equipment upgrades among domestic API producers and contract manufacturers.
- Continuous Oven Configuration:Throughput-optimized production lines present white space in automotive paint curing and battery electrode drying where batch processing dominates.
- EU Green Deal Thermal Efficiency:Carbon border adjustment mechanisms and industrial decarbonization subsidies favor electric and hybrid oven retrofits across German and French manufacturing bases.
Industry Challenges
- Combustion Safety Engineering Talent:NFPA 86 system design expertise concentrates among aging specialists, constraining manufacturer capacity to scale custom project execution.
- Legacy Control System Integration:Facilities with proprietary SCADA architectures face friction embedding modern oven diagnostics into centralized plant management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Ovens Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Ovens, Infrared Ovens, Batch Ovens, Continuous Ovens End User: Aerospace, Food Processing, Automotive, Pharmaceutical Technology: Electric, Gas, Hybrid, Induction Size: Small, Medium, Large, Custom |
| Companies Covered | Wisconsin Oven, ASC Process Systems, Harper International, Despatch, LEWCO Inc., Grieve Corporation, Davron Technologies, Eastman Manufacturing, JPW Ovens & Furnaces, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Ovens Market Emerging Trajectories
Equipment architecture is fragmenting into configurable subsystems as buyers demand application-specific thermal profiles without engineering-to-order lead times. This shift compresses the traditional value chain separating component suppliers from system integrators.
Modular heating zone technology is modularizing continuous oven configurations for battery electrode manufacturing. Korean and Chinese EV battery producers are specifying standardized thermal modules that slot into production lines with minimal site engineering. This architecture is modularizing supplier relationships, enabling tier-two heating element manufacturers to bypass traditional system integrators and contract directly with plant engineering teams.
EPA emissions regulations are constraining burner technology specifications for gas-fired industrial ovens across US manufacturing jurisdictions. Combustion system vendors must now certify ultra-low NOx configurations that add fifteen to twenty percent capital cost premiums. Food processing and general manufacturing segments are absorbing these premiums or accelerating electric technology migration to avoid operating permit complexity.
After-sales service unbundling is disrupting traditional bundled maintenance contracts in the aerospace supplier base. Tier-one defense contractors are separating predictive diagnostics subscriptions from corrective maintenance call-outs, pressuring oven manufacturers to price monitoring hardware independently from labor services. This behavior is most visible in California and Washington state facilities where capital equipment procurement teams have adopted outcome-based vendor scorecards.
Industrial Ovens Market Segmentation
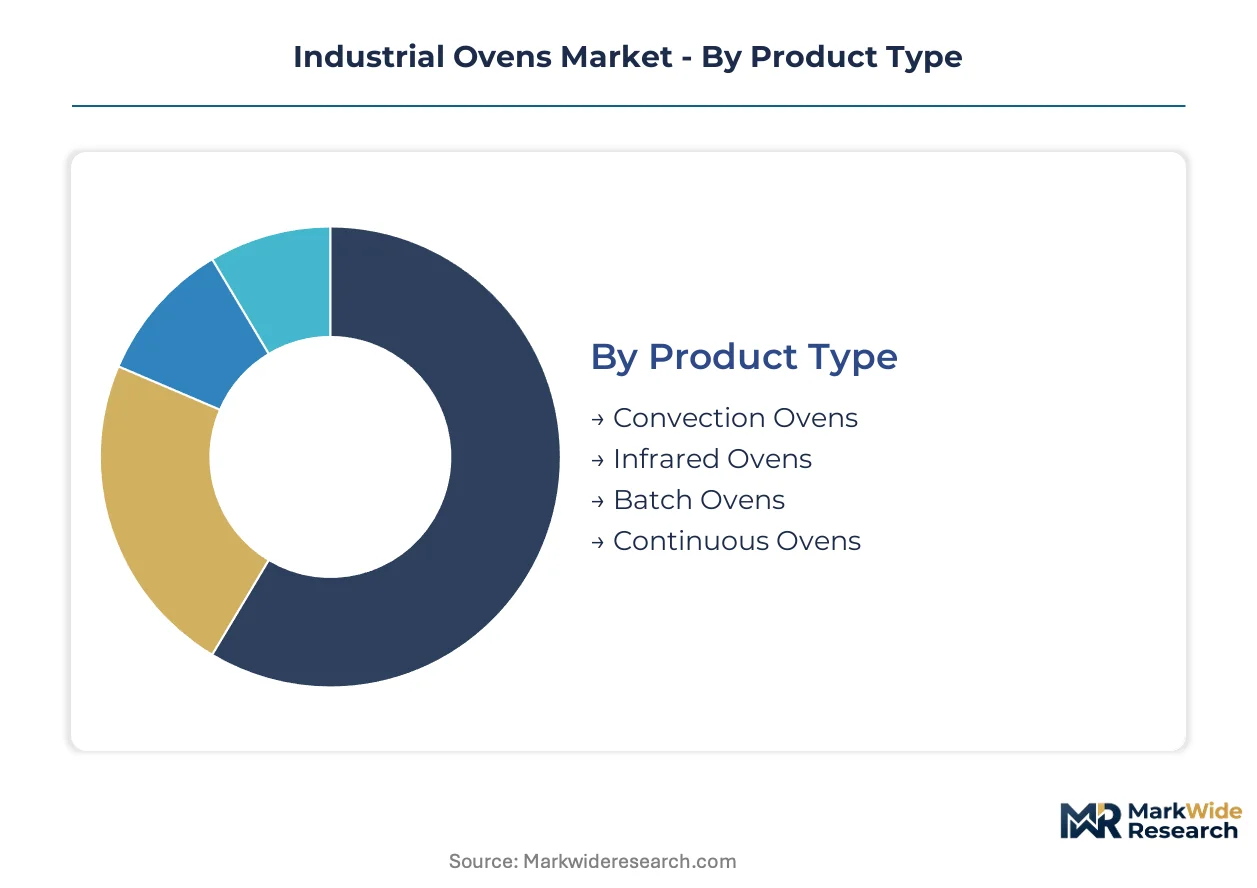
Industrial oven buyers prioritize fundamentally different performance attributes depending on their thermal processing requirements. Aerospace contractors demand precision temperature uniformity for composite curing, while food processors optimize for throughput and sanitation compliance. These divergent needs fragment the competitive landscape into specialized technology and configuration tiers.
Product Type:
Buyers in this category separate by production volume requirements and thermal uniformity specifications rather than capital budget alone.
- Convection Ovens:These systems circulate heated air through forced convection to achieve uniform temperature distribution across the chamber. Food processing facilities in Germany and general manufacturing plants across the US Midwest specify these units for their operational flexibility and lower capital thresholds. Demand concentrates in batch-oriented operations where product changeover frequency makes continuous lines uneconomical.
- Continuous Ovens:Conveyor-fed configurations maintain consistent thermal profiles for uninterrupted material flow. Automotive paint curing operations in Stuttgart supplier clusters and Korean EV battery electrode drying lines are expanding capital budgets for these throughput-optimized systems. EPA emissions compliance complexity is accelerating electric-heated continuous oven specifications where gas-fired alternatives face permit restrictions.
- Infrared Ovens:Radiant heat transfer systems target rapid surface heating for coating curing and pre-heating applications. Powder coating operations in Michigan and Ohio specify short-wave infrared modules for energy efficiency.
- Batch Ovens:Chamber-style units process discrete loads with flexible temperature programming. Heat-treatment shops in France and Italy favor these configurations for job-shop versatility across varying component sizes.
Convection ovens lead volumes today; continuous ovens are gaining share fastest.
End User:
Regulatory exposure and capital intensity create distinct procurement behaviors across vertical applications.
- Automotive:Tier-one suppliers operate dense equipment clusters requiring NFPA 86-compliant combustion safety systems and precise temperature control for composite curing. German automotive supplier zones in Bavaria and Baden-Württemberg represent concentrated demand for continuous oven configurations.
- Aerospace:Defense contractors and commercial airframe manufacturers specify AS9100-certified thermal processing equipment with extensive documentation trails. California and Washington state facilities are unbundling predictive diagnostics subscriptions from corrective maintenance contracts.
- Food Processing:USDA and FDA sanitation standards drive stainless steel construction and cleanable interior designs. Midwest US meat and bakery operations prioritize electric heating to avoid combustion byproduct contamination risks.
- Pharmaceutical:CDSCO-aligned Indian API producers and EU GMP-certified European manufacturers specify validation-ready sterilization ovens with documented thermal mapping. Cleanroom-compatible configurations command specification premiums.
Automotive leads volumes today; pharmaceutical is gaining share fastest.
Technology:
Emissions compliance geography determines technology selection more than energy cost differentials.
- Electric:Resistance heating elements generate zero direct emissions, satisfying EPA restrictions in US food processing and pharmaceutical sterilization applications. California facilities facing regional air quality management district rules are accelerating electric retrofits.
- Gas:Natural gas combustion systems maintain cost advantages in heat-treatment operations where emissions permits remain obtainable. German industrial clusters leverage existing gas infrastructure for large-chamber batch operations.
- Hybrid:Dual-fuel configurations provide operational redundancy for facilities managing energy price volatility or regulatory transition periods. French manufacturing bases pursuing EU Green Deal decarbonization subsidies favor hybrid retrofits as interim solutions.
- Induction:Electromagnetic heating targets conductive materials with superior energy efficiency compared to radiant alternatives. Metal heat-treating applications in Japan and South Korea specify induction for ferrous component processing.
Gas leads volumes today; electric is gaining share fastest.
Size:
Facility footprint constraints and batch economics drive dimensional selection more than component scale alone.
- Large:Chamber volumes exceeding 500 cubic feet accommodate aerospace composite structures and automotive body panels. US defense contractors and German automotive suppliers specify custom large-format ovens with multi-zone temperature control.
- Medium:Standardized dimensions serve general manufacturing and food processing with balanced throughput and floor-space efficiency. Midwest US job shops and Italian metal finishers represent concentrated demand.
- Small:Benchtop and cabinet units target laboratory, R&D, and pilot-line applications. Pharmaceutical development facilities in Massachusetts and North Carolina specify validation-ready small ovens for process scale-up studies.
- Custom:Application-specific dimensions address non-standard component geometries or integration into existing production lines. Battery electrode manufacturing lines in China and Korea specify modular custom configurations.
Medium leads volumes today; custom is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive supplier clusters command denser heat-treatment equipment concentrations than US defense contractor facilities, though California aerospace campuses are accelerating predictive diagnostics adoption faster than Bavarian counterparts.
United States
EPA emissions standards and NFPA 86 safety codes are forcing combustion system upgrades across Midwest heat-treatment operations. California facilities face additional regional air quality management district rules that accelerate electric oven retrofits. Wisconsin Oven leverages vertical integration into control system fabrication to secure long-term service contracts with defense contractors in Washington state.
Germany
EU Green Deal thermal efficiency mandates and carbon border adjustment mechanisms favor electric and hybrid oven retrofits across manufacturing bases. Dense concentrations of tier-one automotive suppliers in Bavaria and Baden-Württemberg are expanding capital equipment budgets for composite curing applications. Stuttgart supplier clusters represent concentrated demand for continuous oven configurations in automotive paint curing operations.
China
EV battery electrode manufacturing lines are specifying standardized thermal modules that slot into production with minimal site engineering. MIIT industrial decarbonization targets and dual carbon goals constrain gas-fired alternatives in coastal manufacturing zones. Korean and Chinese battery producers in the Yangtze River Delta are driving modular heating zone technology adoption.
India
CDSCO regulatory alignment with EU GMP standards drives sterilization equipment upgrades among domestic API producers and contract manufacturers. The country's national pharmaceutical regulator enforces validation-ready equipment specifications with documented thermal mapping. Pharmaceutical development facilities in Maharashtra and Gujarat specify cleanroom-compatible oven configurations.
South Korea
MFDS pharmaceutical manufacturing standards and METI-aligned industrial efficiency programs shape equipment procurement criteria. EV battery producers specify modular custom configurations for electrode drying lines. Busan-Ulsan industrial corridors host concentrated demand for throughput-optimized continuous oven systems.
Industrial Ovens Market Vendor Landscape
US producers anchor one tier of the market; German and Japanese specialists hold differentiated positions in precision thermal processing. The vendor base separates into three strategic tiers: vertically integrated system integrators with captive control fabrication, specialized heating technology developers, and regional fabrication shops serving job-shop demand. Consolidation pressure concentrates among mid-scale players lacking proprietary thermal module designs. Dominant competitive moves include backward integration into heating element supply and geographic expansion through distributor networks rather than direct sales.
Within the vertically integrated tier, Wisconsin Oven represents control system fabrication capabilities, while Harper International exemplifies specialized graphite-heating technology positions. ASC Process Systems occupies a geographic concentration anchor on the US West Coast. These three fabricators illustrate how competitive positioning fragments across technology specialization, captive supply advantages, and regional installed base density rather than scale alone.
| Leading Market Players |
|---|
| Wisconsin Oven |
| ASC Process Systems |
| Harper International |
| Despatch |
| LEWCO Inc. |
| Grieve Corporation |
| Davron Technologies |
| Eastman Manufacturing |
| JPW Ovens & Furnaces |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap fabricators concentrated in the US Midwest and German industrial corridors anchor production capacity, linking conservative pricing discipline to captive control system fabrication and long-term service contract structures. This ownership pattern limits aggressive price competition while reinforcing investment in NFPA 86 certification capabilities as a differentiation barrier.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for standardized thermal modules in battery electrode manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace configurations from general manufacturing batch units. Cost compression in economy-tier convection ovens is intensifying because Korean EV producers specify commoditized heating zones. Tier-one automotive suppliers exhibit lowest price sensitivity due to embedded warranty requirements, while Midwest job shops prioritize capital cost minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Korean and Chinese battery producers, while distributor networks serve fragmented European automotive suppliers. Graphite heating element supply concentrates in Japan and China, with specialized refractory metals sourcing from Germany and the US. Combustion system componentry draws from Italian burner specialists and US controls fabricators. Single-source vulnerability in high-purity graphite exposes advanced materials processors to input disruption. Distribution runs through authorized system integrators in mature markets and direct plant engineering relationships in Asia-Pacific greenfield projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial oven manufacturing offers margin expansion through electric technology premiumization and aftermarket service unbundling, as EPA emissions restrictions and aerospace predictive diagnostics adoption shift buyer willingness-to-pay toward validated thermal performance.
For Market Incumbents: To counter induction heating substitution in metal heat-treating applications, Wisconsin Oven and Harper International should deepen backward integration into heating element supply and expand NFPA 86 engineering capacity through specialist acquisition. Captive control system fabrication remains the priority defensive lever against margin compression in standard configurations. For New Entrants and Emerging Players: Regional fabrication shops in India and Southeast Asia represent the most penetrable channel partner type for breaking into pharmaceutical sterilization equipment. Target CDSCO-aligned API producers in Maharashtra and Gujarat with validation-ready small-batch configurations. A go-to-market angle emphasizing documented thermal mapping and cleanroom compatibility can bypass entrenched European competitors. For Investors and Strategic Acquirers: Defense contractors and Tier-one automotive suppliers are the most active acquirer categories in this space, seeking captive thermal processing capabilities for composite curing and battery electrode manufacturing. Acquisition targets should display proprietary modular heating zone designs and established NFPA 86 or AS9100 certification pathways. The signal to watch is EPA regional air quality rulemaking tightening, which accelerates electric technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive graphite supply secures margin pools in advanced materials processing against Japanese and Chinese input volatility. |
| NFPA 86 Certification Capacity Expansion | Combustion safety engineering scarcity constrains project throughput; specialist hiring or acquisition unlocks revenue recognition speed. |
| Modular Thermal Zone Standardization | Korean and Chinese battery producers specify slot-in configurations, enabling tier-two component suppliers to bypass system integrators. |
| Predictive Diagnostics Unbundling | California and Washington aerospace facilities separate monitoring hardware from labor services, creating standalone recurring revenue streams. |
| Electric Technology Product Line Extension | EPA regional air quality rules and EU Green Deal subsidies favor zero-emission configurations in food processing and pharmaceutical sterilization. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across automotive, aerospace, and pharmaceutical facilities were validated against secondary sources including EPA enforcement databases, NFPA 86 certification registries, SEC equipment supplier filings, and EU industrial emissions monitoring data. This triangulation approach ensures demand-side consumption patterns align with manufacturer shipment disclosures and installed base estimates.
Input-output matrices map thermal processing capacity requirements by end-use sector, technology type, and geographic regulatory cluster across the projection horizon. Segmentation dimensions include product configuration, heating technology, end-user vertical, and chamber size tier. CAGRs were derived from regression analysis of historical capital equipment spending correlated with regulatory compliance cycle timing and automotive production forecasts. Industry-specific inputs incorporate EV battery electrode manufacturing capacity buildouts and CDSCO pharmaceutical facility upgrade schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA regional rulemaking stringency, EU carbon border adjustment implementation pace, and graphite supply chain restructuring. Forecasts reflect assumptions regarding NFPA 86 compliance deadlines and MIIT industrial decarbonization targets without incorporating unforeseen technology substitution or trade policy disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
US Welding Consumables Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Jib Crane Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Trenchers Market
Construction Equipment
Suction Excavator Market
Construction Equipment
Concrete Testers Market