
 Automated Truck Market | 2026-2036
Automated Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Truck Market Analysis
A chronic shortage of qualified long-haul drivers is unwinding traditional fleet economics and forcing freight operators toward autonomous alternatives. Tesla leverages its integrated AI compute stack to control full-stack development costs across vehicle and perception layers. Volvo anchors European deployment credibility through decades of commercial vehicle safety engineering and established service networks. Aurora Innovation specializes in the highway autonomy sub-problem, concentrating R&D resources on structured interstate corridors rather than urban complexity.
An automated truck integrates sensor fusion architectures—typically combining LiDAR point clouds, radar velocity signatures, and computer vision inference—to execute longitudinal and lateral vehicle control without continuous human supervision. These systems operate at SAE Level 4 capability on geofenced highway segments, with teleoperation fallback protocols governing edge-case intervention. Heavy-duty trucks dominate current capital deployment given the outsized unit economics of automating long-haul routes where labor represents the largest variable cost. Last-mile delivery automation within the deployment segment is attracting disproportionate venture investment despite technical complexity, as e-commerce fulfillment density justifies repeated fixed-route optimization.
The US DOT and NHTSA shape market access through evolving FMVSS exemption pathways and pending rulemaking on automated driving system equipment standards. EPA fuel efficiency mandates indirectly accelerate automation adoption by rewarding the precise speed and route optimization that autonomous systems enable. Stakeholders must monitor how state-level insurance liability frameworks evolve, as patchwork coverage rules threaten to fragment interstate operational permissions before federal preemption clarifies.
Market Dynamics
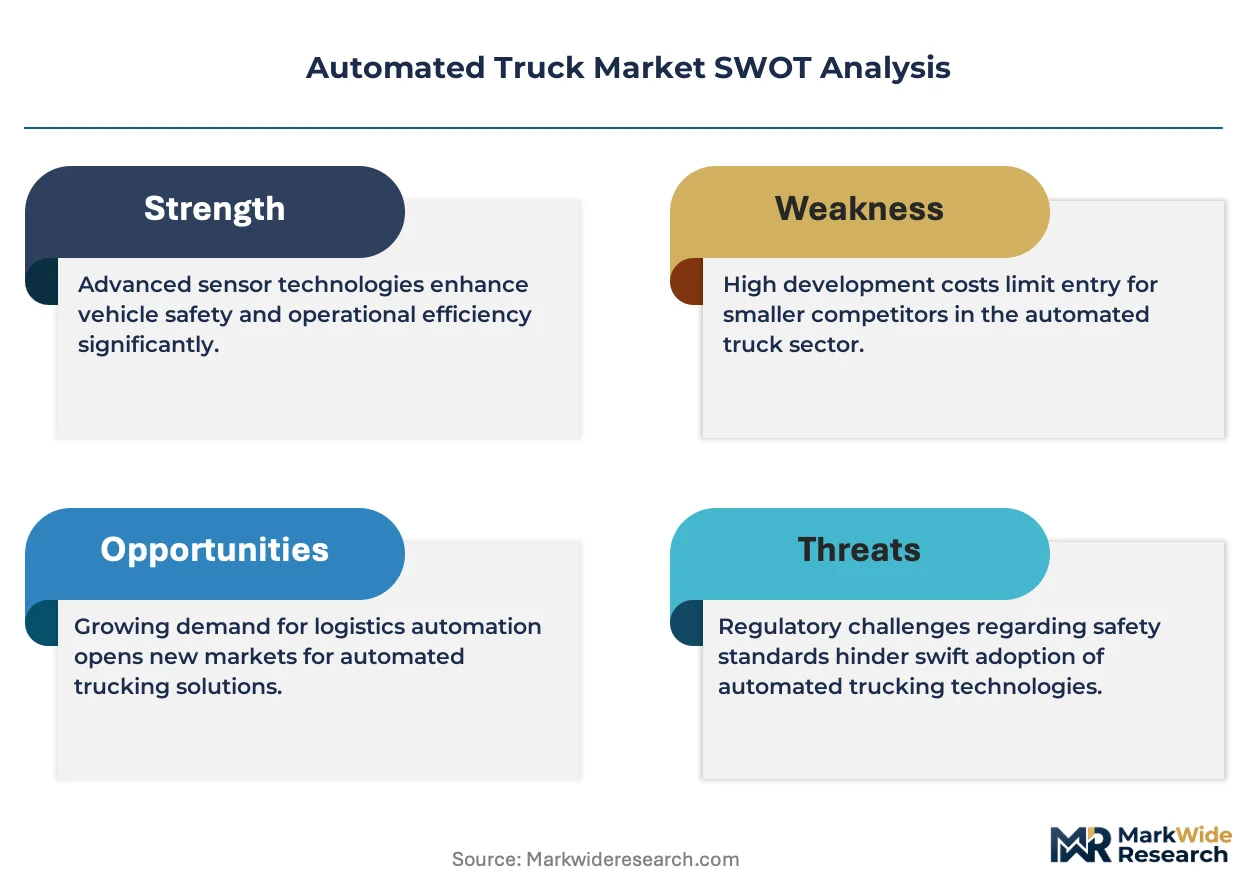
The Automated Truck Market pivots on regulatory permission structures that determine where supervised autonomy can transition from pilot corridors to revenue service. The US DOT's automated vehicle guidance framework creates the foundational conditions for fleet operators to deploy capital at scale.
Growth Catalysts
- Driver shortage economics:Chronic long-haul labor scarcity compresses fleet utilization rates and accelerates operator willingness to absorb automation capital costs.
- Interstate infrastructure readiness:Texas, Arizona, and California maintain geofenced highway segments with favorable lane markings and weather patterns that reduce perception complexity.
- Fuel efficiency mandates:EPA regulations reward precise speed optimization and platooning aerodynamics that autonomous control systems execute more consistently than human drivers.
Market Restraints
- LiDAR sensor cost concentration:High-performance solid-state units remain supply-constrained from limited qualified contract manufacturers.
- State liability fragmentation:Patchwork insurance frameworks across US jurisdictions create operational permission uncertainty for interstate carriers.
- Teleoperation fallback dependency:Edge-case intervention protocols require continuous low-latency cellular coverage that rural interstate segments lack.
Strategic Opportunities
- Canadian cross-border corridors:Transport Canada and US DOT harmonization discussions could unlock Vancouver-Seattle-Portland automation lanes.
- Mexican manufacturing feed routes:Maquiladora clusters near Nuevo Laredo and Tijuana present fixed-route density for supervised autonomy deployment.
- Platooning-as-a-service:Fleet operators can monetize aerodynamic drafting coordination between mixed automated and conventional trucks.
Industry Challenges
- Perception engineering talent scarcity:Sensor fusion algorithm development requires specialized computer vision expertise that competes with autonomous passenger vehicle programs.
- FMVSS exemption timeline uncertainty:NHTSA rulemaking delays on automated driving system equipment standards extend certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Truck Market |
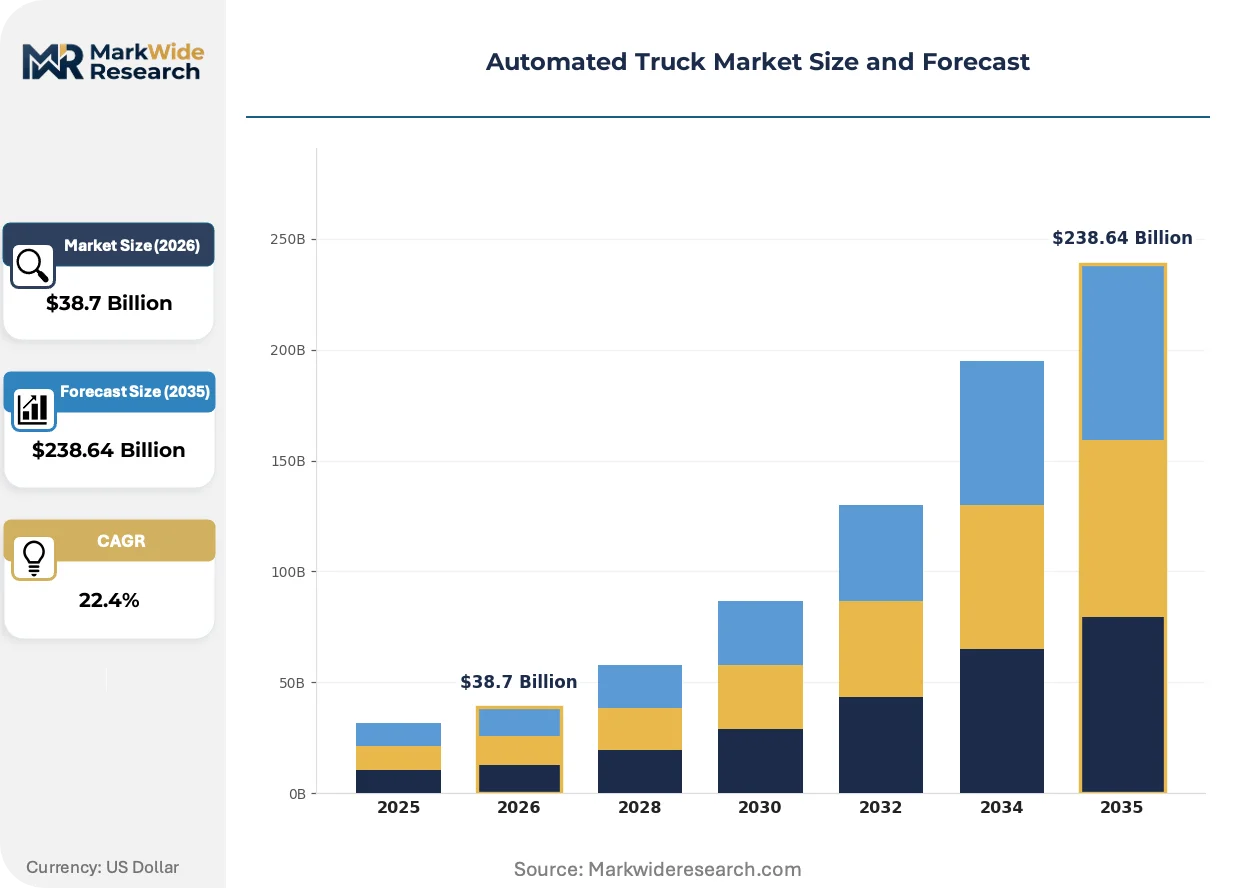
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $238.64 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Trucks, Medium-Duty Trucks, Light-Duty Trucks, Specialty Trucks Technology: LiDAR, Radar, Computer Vision, GPS End User: Logistics Companies, Freight Carriers, E-commerce Firms, Third-Party Logistics Deployment: On-Road, Last-Mile Delivery, Long-Haul, Fleet Management |
| Companies Covered | Waabi, Plus Automation, Gatik, Isuzu, Tesla, Aurora Innovation, Einride, Volvo, Kodiak Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Truck Market Emerging Trajectories
Sensor fusion architectures and edge computing deployments are compressing the technical gap between supervised pilot programs and unsupervised commercial service. Three developments dominate current competitive positioning.
LiDAR-radar-camera fusion stacks are displacing camera-only perception strategies in heavy-duty applications. Long-haul fleet operators in Arizona and Texas corridors now specify multi-modal redundancy as a procurement requirement. This technical specification is displacing Tesla's camera-centric approach from large-fleet RFPs where liability exposure concentrates.
NHTSA's pending automated driving system equipment standards rulemaking is forcing retrofit compatibility investments. Equipment suppliers must engineer backward-compatible hardware interfaces for existing truck chassis. Heavy-duty OEMs with modular electrical architectures capture disproportionate early-mover advantage.
Freight procurement is fragmenting toward lane-specific automation contracts. Large shippers now tender dedicated highway segments rather than full network coverage, matching carrier capability to route complexity. This pattern concentrates in California's Central Valley agricultural corridors where pickup and delivery points are highly predictable.
Automated Truck Market Segmentation
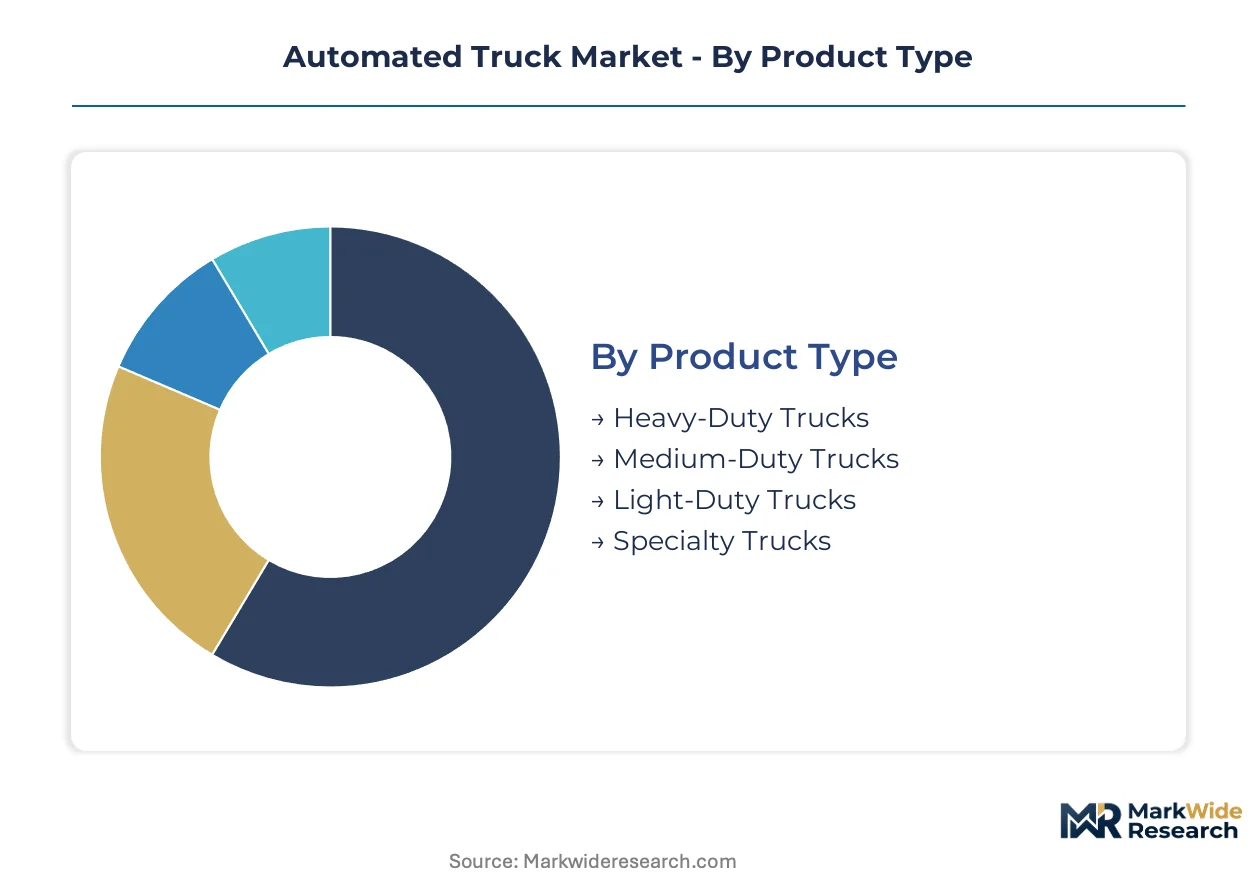
Segmentation in the Automated Truck Market reveals how capital allocation and regulatory permissions concentrate across vehicle classes and operational domains. Fleet operators, technology suppliers, and infrastructure planners each prioritize different segment combinations when deploying resources.
Product Type:
Heavy-duty platforms dominate cross-border corridors between Texas and California, while medium-duty variants concentrate on regional distribution loops around Phoenix and Dallas-Fort Worth.
- Heavy-Duty Trucks:These vehicles integrate redundant sensor arrays and high-compute platforms to automate interstate freight corridors where labor costs exceed equipment amortization. Demand concentrates in the I-10 and I-35 corridors linking California, Arizona, and Texas, driven by agricultural and manufacturing freight density. NHTSA's FMVSS exemption pathways favor these platforms given their predictable highway operating envelopes.
- Medium-Duty Trucks:Configured for regional distribution with reduced sensor payload and teleoperation fallback protocols. Fleet operators in California's Central Valley agricultural networks specify these for 200-400 mile radius routes where pickup predictability justifies partial automation. EPA fuel efficiency mandates accelerate procurement here given stop-start route profiles.
- Light-Duty Trucks:Urban-focused platforms with constrained geofences and frequent human intervention points.
- Specialty Trucks:Refrigerated and flatbed variants with cargo-specific stability controls for sensitive freight categories.
Heavy-Duty Trucks holds the largest share; momentum sits with Medium-Duty Trucks.
Technology:
Sensor modality selection determines liability exposure and route authorization breadth, with multi-modal stacks commanding premium positioning against camera-centric alternatives.
- LiDAR:Solid-state units generate dense point clouds for object classification at highway speeds. Arizona and Texas transportation authorities specify LiDAR inclusion for unsupervised corridor permits, creating procurement mandates for fleet operators serving Los Angeles-Phoenix-Dallas lanes. Supply constraints from qualified contract manufacturers limit deployment velocity.
- Radar:Velocity-signature detection operates reliably through precipitation and dust conditions that degrade optical systems. California's Central Valley agricultural haulers prioritize radar redundancy for seasonal dust exposure during harvest periods. Cost advantages over LiDAR support adoption in medium-duty regional applications.
- Computer Vision:Camera-based inference stacks leverage neural network training on highway-specific object libraries.
- GPS:High-precision positioning enables geofence enforcement and lane-level localization on mapped corridors.
LiDAR captures the premium tier; radar is climbing the fastest.
End User:
Procurement authority fragments between asset-owning carriers and logistics intermediaries, with divergent risk tolerance for technology transition.
- Logistics Companies:Integrated operators like Schneider and Werner Enterprises control fleet automation roadmaps directly. These firms pilot supervised autonomy on dedicated California-Arizona-Texas lanes where freight density supports dedicated equipment allocation. Balance sheet capacity absorbs upfront capital requirements that strain smaller competitors.
- Freight Carriers:Independent operators and mid-sized fleets access automation through leasing structures and technology-as-a-service contracts. Third-party maintenance networks in Dallas and Phoenix reduce operational risk for these capital-constrained adopters.
- E-commerce Firms:Amazon and Walmart direct captive fleet specifications toward last-mile and regional hub connectivity.
- Third-Party Logistics:Asset-light intermediaries influence technology adoption through shipper-facing service level agreements.
Logistics Companies holds the largest share; momentum sits with Freight Carriers.
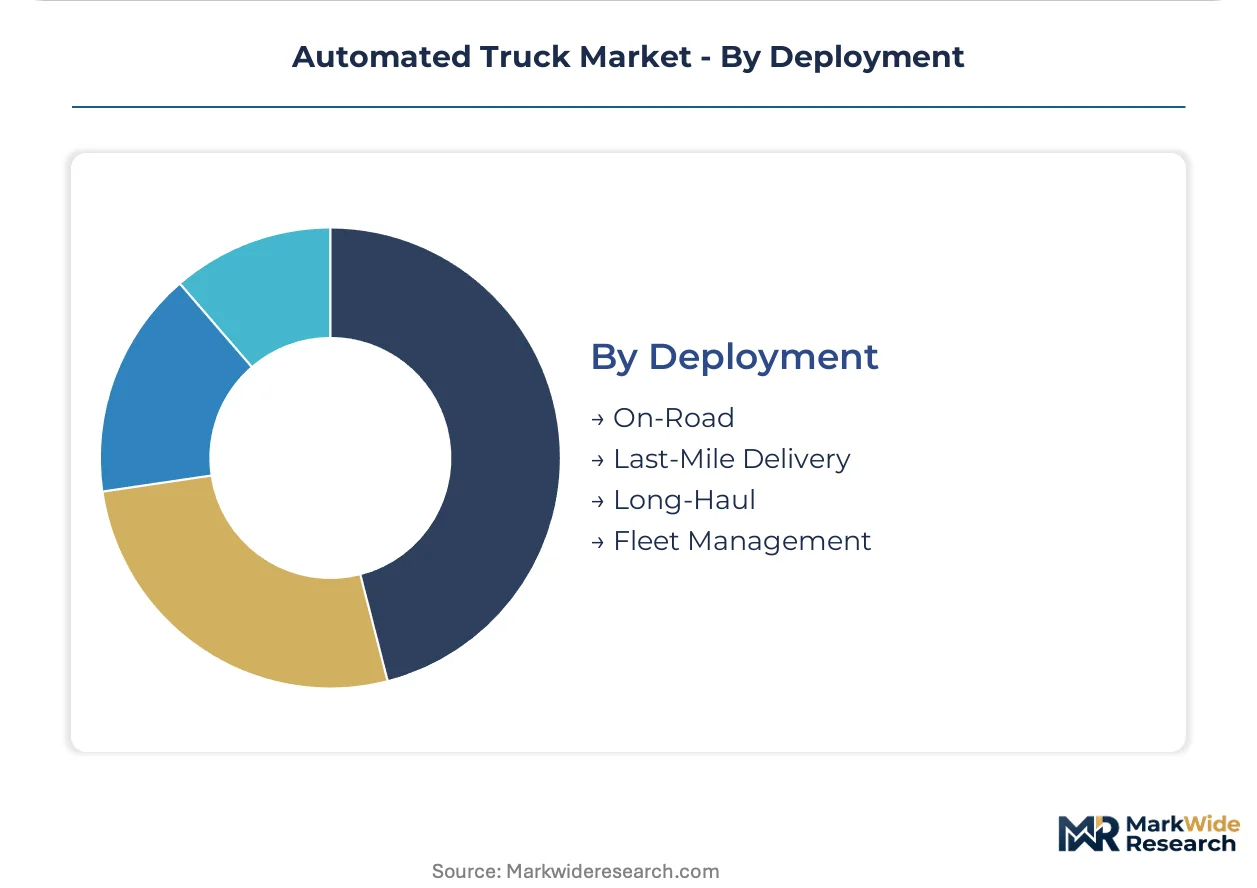
Deployment:
Operational domain selection governs regulatory complexity and revenue model design, with highway corridors offering clearer permission pathways than urban environments.
- On-Road:Supervised highway automation on geofenced interstate segments represents the primary revenue deployment mode. Texas Department of Transportation and Arizona Department of Transportation maintain designated corridors with favorable lane markings and cellular coverage for teleoperation fallback. Fleet operators achieve unit economics parity with conventional trucking on these routes.
- Long-Haul:Extended corridor automation spanning multiple states concentrates on I-10 and I-35 where infrastructure consistency supports multi-jurisdiction permits. US DOT harmonization efforts with Transport Canada could extend these lanes to Vancouver-Seattle-Portland networks.
- Last-Mile Delivery:Urban complexity with pedestrian interaction and unstructured loading environments.
- Fleet Management:Coordination platforms for mixed automated and conventional asset optimization.
On-Road holds the largest share; momentum sits with Long-Haul.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where regulatory sandboxes accelerate deployment velocity, while European operators absorb certification delays that compress margin structures. Canada and Mexico present corridor-specific opportunities tied to US harmonization efforts. Australia and China represent divergent models of infrastructure-led versus manufacturing-scale automation pathways.
United States
Driver shortage economics and favorable liability frameworks concentrate deployment capital in Texas, Arizona, and California. NHTSA's FMVSS exemption pathways for automated driving systems enable supervised commercial service on designated interstate corridors. The I-10 and I-35 freight lanes linking Los Angeles, Phoenix, and Dallas-Fort Worth host the densest pilot-to-scale transitions.
Canada
Cross-border freight density and Transport Canada-US DOT regulatory harmonization discussions position Vancouver-Seattle-Portland corridors for integrated automation. The country's national transportation regulator advances conditional permissions for supervised platooning on the Trans-Canada Highway. Ontario's manufacturing supply chain and British Columbia's port logistics generate concentrated demand for corridor-specific automation contracts.
Mexico
Maquiladora manufacturing clusters near Nuevo Laredo and Tijuana create fixed-route density ideal for supervised autonomy deployment. The Secretariat of Communications and Transportation coordinates with US DOT on cross-border permit reciprocity for automated freight. Northern border states concentrate pilot programs serving automotive and electronics supply chains.
Australia
Mining logistics and remote corridor freight economics justify heavy-duty automation investments despite low population density. The National Transport Commission develops performance-based standards for automated heavy vehicles operating on the Stuart and Tanami highways. Western Australia's Pilbara region hosts iron ore haulage automation that transfers technology to on-road freight applications.
China
Manufacturing scale and MIIT smart vehicle standards accelerate domestic sensor fusion platform deployment. The Ministry of Transport designates intelligent connected vehicle highways in the Yangtze River Delta and Pearl River Delta regions. Shenzhen and Shanghai municipal governments issue operational permits for automated trucks on port-to-industrial park corridors.
Automated Truck Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where full-stack developers compete against component specialists and fleet-integrated operators. The market fragments across three strategic clusters: automotive OEMs with service network advantages, pure-play autonomy software developers, and vertically integrated technology-hardware hybrids. Consolidation pressure concentrates on sensor fusion stack providers as fleet operators standardize procurement specifications. Dominant competitive moves include strategic partnerships between software developers and heavy-duty chassis manufacturers, plus geographic corridor exclusivity agreements with state transportation authorities.
Among the pure-play autonomy developers, Aurora Innovation, Waabi, and Kodiak Robotics exemplify the highway-corridor specialization archetype. These companies occupy positions defined by concentrated R&D investment on structured interstate environments rather than urban complexity. Tesla represents the integrated technology-hardware model with captive AI compute and vehicle manufacturing control. Volvo anchors the established OEM tier through commercial vehicle safety engineering credibility and dense service network coverage. Gatik and Plus Automation sit within the middle-mile regional deployment segment, targeting fixed-route distribution loops with reduced sensor payload requirements.
| Leading Market Players |
|---|
| Waabi |
| Plus Automation |
| Gatik |
| Isuzu |
| Tesla |
| Aurora Innovation |
| Einride |
| Volvo |
| Kodiak Robotics |
| Others |
Supply Flow & Price Mechanics
Solid-state LiDAR substitution for mechanical spinning units is redrawing component sourcing maps from Germany and Japan toward Taiwan and South Korea while compressing sensor procurement economics for fleet operators. This displacement simultaneously concentrates Tier 2 supplier power in East Asian contract manufacturers and forces Western autonomy developers to absorb premium pricing for qualified units or accept extended lead times.
Pricing Analysis
The customization-premium spread separates heavy-duty highway platforms with redundant multi-modal sensor stacks from medium-duty regional configurations with reduced perception payloads. Fleet operators purchasing configured-to-order heavy-duty units face substantial premiums tied to LiDAR inclusion and teleoperation-ready compute architectures, while standardized medium-duty regional trucks compete on narrower margins with radar-centric alternatives. Price differentiation hinges on SAE Level 4 certification tier and after-sales service bundling through OEM maintenance networks. Cost compression in the medium-duty tier is intensifying because radar suppliers are expanding qualified manufacturing capacity. Asset-light freight carriers exhibit highest price sensitivity; integrated logistics companies with balance sheet capacity absorb upfront premiums for liability-redundant configurations.
Supply Chain Analysis
Inbound logistics costs for solid-state LiDAR units remain elevated due to container availability constraints on the Shanghai-Long Beach trade lane and port congestion at Los Angeles. Component supply concentrates in Taiwan, South Korea, and China for LiDAR emitters and receivers, with Germany and the United States contributing specialized optical assemblies and AI compute silicon. Raw material dependencies include indium phosphide wafers, specialized laser diodes, and high-grade aluminum for thermal management housings. Single-source vulnerability for qualified solid-state LiDAR contract manufacturers represents the dominant structural risk. Distribution runs through heavy-duty OEM certified dealer networks in Dallas, Phoenix, and Los Angeles, with third-party teleoperation service providers layering operational support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated truck sector rewards organizations that control sensor fusion engineering talent and hold corridor-specific regulatory permissions. Shortages in perception algorithm developers and geofenced highway access rights create asymmetric returns for first-movers.
For Market Incumbents: Fortify defensive moats by securing exclusive teleoperation service agreements with cellular infrastructure providers along I-10 and I-35 corridors, and deepen backward integration into LiDAR calibration facilities to reduce supplier switching costs. Emerging pure-play autonomy developers with highway-specialized stacks threaten fleet operator relationships that incumbent OEMs have cultivated through decades of commercial vehicle service coverage. For New Entrants and Emerging Players: Anchor in medium-duty regional distribution loops around California's Central Valley agricultural networks, where 200-400 mile radius routes with predictable pickup patterns justify partial automation with reduced sensor payloads. This segment offers lower regulatory complexity than interstate long-haul and faster path to revenue service. A technology-as-a-service contract structure with third-party maintenance partnerships in Dallas and Phoenix reduces capital barriers for mid-sized fleet adoption. For Investors and Strategic Acquirers: The market sits at a pilot-to-scale transition phase that favors vertically integrated technology-hardware hybrids with captive AI compute and vehicle manufacturing control. Long-term viability over the next decade rests on securing multi-jurisdiction regulatory permissions before federal preemption clarifies liability frameworks. Acquisition targets should demonstrate established corridor relationships with Texas, Arizona, or California transportation authorities. The signal to monitor is NHTSA automated driving system equipment standards rulemaking, which will determine certification timeline certainty and equipment retrofit compatibility requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Corridor Exclusivity Agreement | Locked access to Texas DOT-designated automation lanes secures revenue deployment geography before competitors. |
| LiDAR Supply Partnership | Qualified solid-state unit allocation from Taiwan contract manufacturers de-risks sensor procurement bottlenecks. |
| Teleoperation Infrastructure Buildout | Cellular coverage densification along rural I-10 segments enables fallback protocols for unsupervised service. |
| Fleet Operator Technology-as-a-Service | Leasing structures reduce capital barriers for mid-sized carriers in California Central Valley agricultural networks. |
| Cross-Border Regulatory Harmonization | Transport Canada-US DOT alignment unlocks Vancouver-Seattle-Portland automation lane extensions. |
Methodological Framework
Cross-validation between fleet operator procurement interviews and NHTSA regulatory filing analysis anchors the qualitative findings on deployment permission timelines. Primary engagement with autonomy software developers, heavy-duty OEM platform engineers, and logistics company fleet directors combined with secondary validation through FMVSS exemption petitions, state transportation authority corridor designations, and EPA fuel efficiency compliance disclosures. Bottom-up triangulation across sensor supplier capacity announcements and top-down reconciliation against freight demand elasticity models produced volume estimates.
Sensitivity analysis on LiDAR cost decline curves and driver wage inflation assumptions shapes the forecast envelope across the projection horizon. Segmentation dimensions modeled include vehicle duty class, sensor modality configuration, operational domain, and fleet operator balance sheet capacity. CAGRs were derived from installed base growth rates and replacement cycle assumptions. Industry-specific inputs incorporate FMVSS exemption approval velocity and teleoperation cellular coverage expansion maps.
Material uncertainties — NHTSA rulemaking delays, state liability framework fragmentation, and LiDAR supplier qualification bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory permission expansion and sensor cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Robotic Haul Trucks Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Peru Commercial Vehicle Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
France Light Commercial Vehicles Market