
 France HRI Market | 2026-2036
France HRI Market Size, Share, and Industry Trends Forecast 2026-2036
France HRI Market Foresight
Modular kitchen configurations is hardening as the dominant procurement pattern among French foodservice operators, replacing standalone equipment purchases with integrated cooking lines. McDonald's Corporation leverages its European supply chain to standardize modular range-griddle-salamander bundles across franchise locations. Groupe Le Duff anchors its bakery-café expansion on compact, all-in-one cooking modules that fit constrained urban footprints. O'Tacos differentiates through customizable griddle-to-order stations designed for high-throughput assembly.
France HRI (Hotels, Restaurants, and Institutions) equipment encompasses heavy-duty commercial cooking appliances engineered for continuous operation in professional foodservice environments, typically constructed from stainless steel with gas or electric power ratings exceeding 10 kW per unit and designed to withstand daily cycles exceeding twelve hours. The primary purpose is to deliver consistent thermal output for batch and à-la-carte production across high-volume dining operations. Range and griddle segments dominate current installed capacity in full-service restaurants, while salamander and rotisserie categories capture expanding demand from fast-casual concepts seeking finishing versatility and visual merchandising appeal. Equipment dealers and wholesale distributors control the bulk of transaction volume, though direct sales channels deepen penetration among multi-unit chains pursuing fleet-standardization contracts.
France's commercial kitchen sector operates under ANSM food-contact material standards, CE marking for electrical and gas safety compliance, and the EU Ecodesign Directive mandating progressive efficiency improvements in professional cooking equipment. These frameworks elevate capital costs for non-compliant imports while creating procurement preference for certified European manufacturers. Stakeholders must monitor evolving EU F-Gas Regulation amendments and national decarbonization incentives, as electrification mandates could reshape equipment replacement timelines and vendor qualification criteria across French hospitality operations.
Market Dynamics
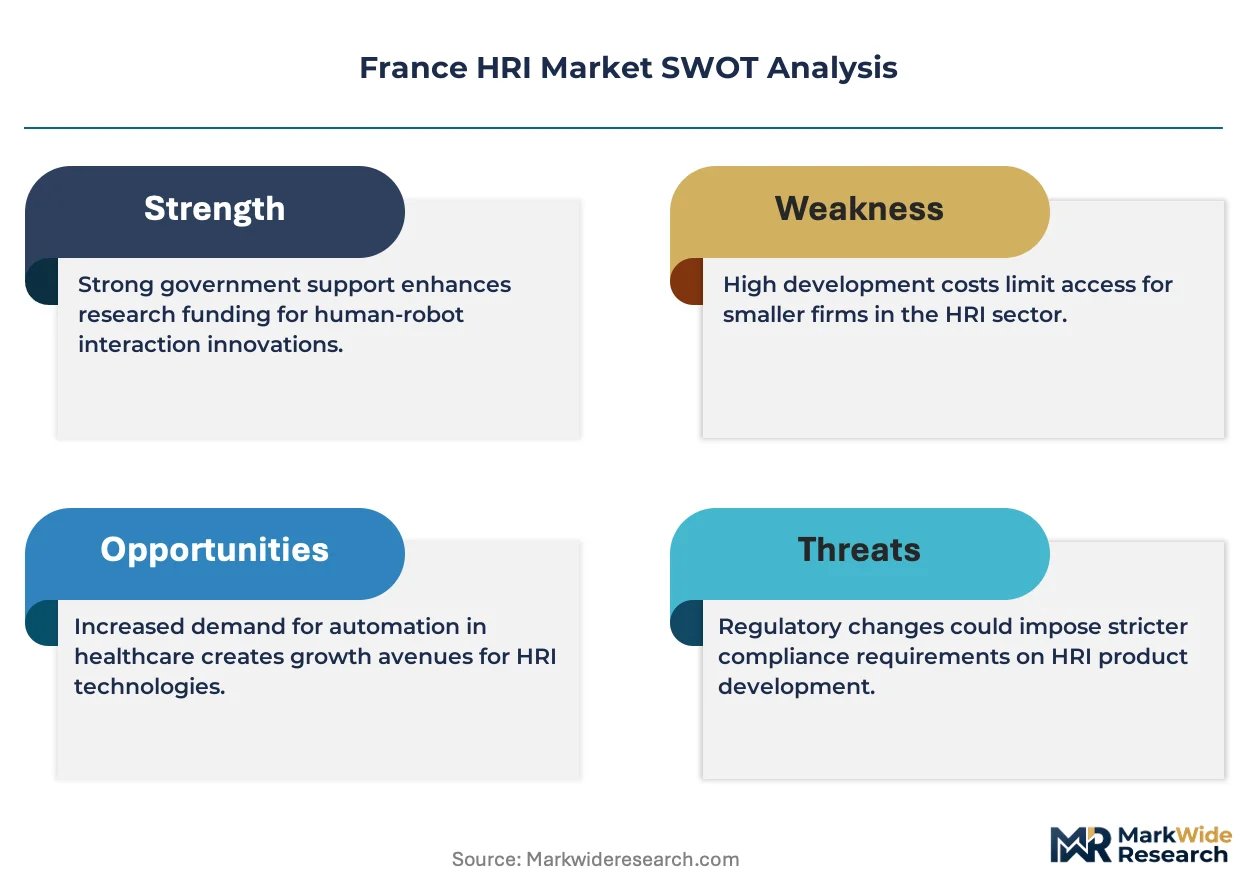
France's national energy transition framework imposes strict efficiency thresholds on commercial cooking appliances, forcing accelerated replacement cycles across quick-service restaurant chains and institutional kitchens. This regulatory pressure is compressing equipment lifespans while elevating procurement standards for thermal output consistency and decarbonization compliance.
Growth Catalysts
- EU Ecodesign Directive:Progressive efficiency mandates for professional cooking equipment create procurement preference for certified European manufacturers, elevating demand for compliant heavy-duty ranges and griddles across French hospitality operations.
- Paris-Ile-de-France corridor density:High-volume foodservice concentration in this urban cluster drives fleet-standardization contracts and volume procurement of modular cooking lines for multi-unit operators.
- Electrification infrastructure:National decarbonization incentives and grid modernization programs enable gas-to-electric equipment transitions in commercial kitchens, expanding addressable market for high-kW electric ranges and induction griddles.
Market Restraints
- Stainless steel input volatility:Raw material price swings for 304-grade and 316-grade stainless steel compress manufacturer margins and destabilize equipment pricing for heavy-duty range and griddle production.
- ANSM certification friction:Food-contact material standards and CE marking requirements for gas and electrical safety elevate capital costs for non-compliant imports, limiting vendor pool diversification.
- Induction technology substitution:Accelerating adoption of induction cooking systems in premium foodservice segments threatens traditional gas-powered range market share in urban French kitchens.
Strategic Opportunities
- F-Gas Regulation amendments:Evolving EU refrigerant phase-down rules create retrofit demand for climate-friendly cooking equipment and associated ventilation systems in institutional kitchens.
- Fast-casual salamander penetration:Underdeveloped finishing equipment deployment in quick-service formats presents white space for compact, high-output salamander modules designed for assembly-line production.
- Direct channel expansion:Multi-unit chains pursuing fleet-standardization contracts increasingly bypass wholesale distributors, creating margin capture opportunity for manufacturers with captive sales organizations.
Industry Challenges
- Gas-safe technician scarcity:Shrinking pipeline of certified commercial gas equipment installers extends commissioning timelines and elevates service costs for high-BTU range installations.
- Legacy kitchen integration:Modular cooking line adoption confronts spatial constraints and ventilation incompatibility in older Parisian restaurant infrastructure, complicating retrofit specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France HRI Market |
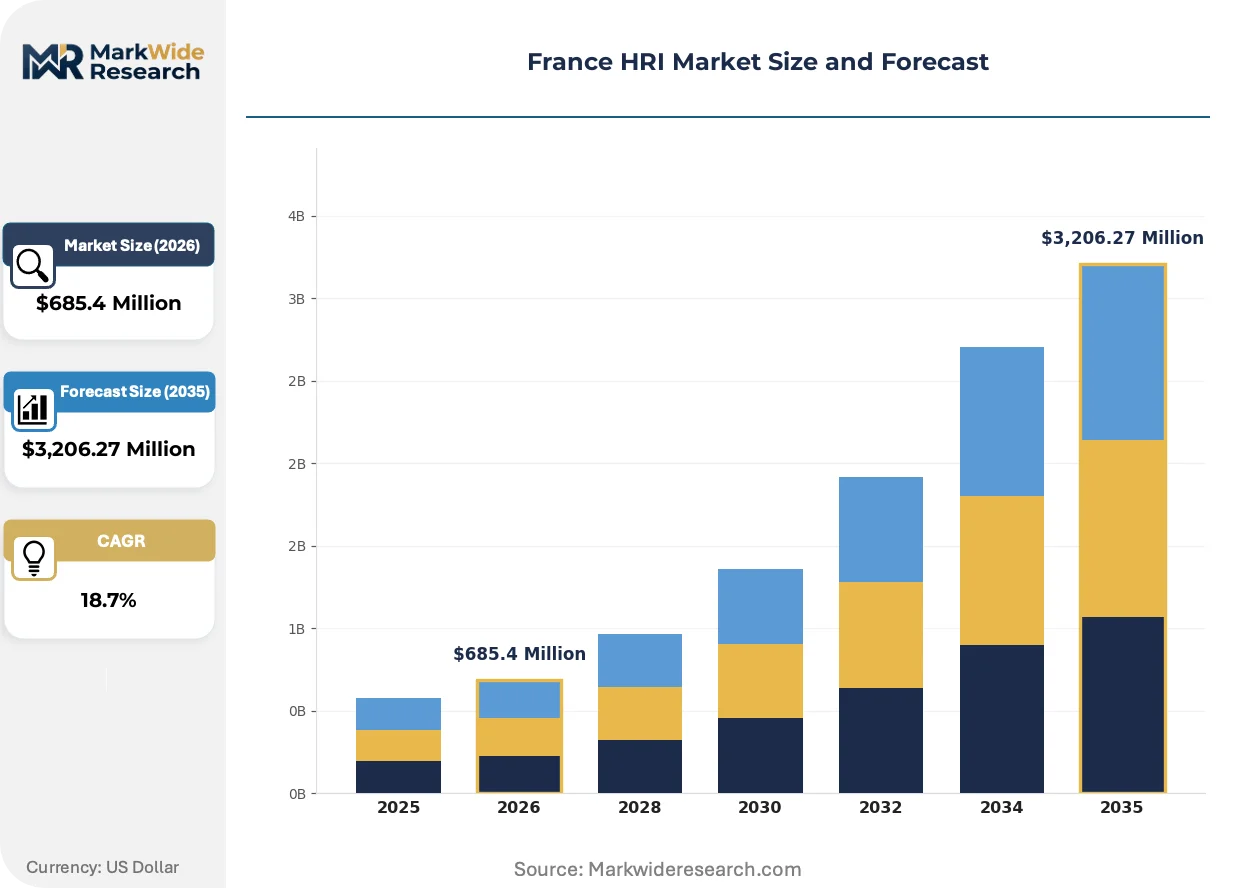
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Range, Oven, Griddle, Salamander, Charbroiler, Rotisserie Application: Hotels, Restaurants, Cafes, Catering Services, Event Venues, Leisure Clubs End User: Commercial Kitchens, Food Trucks, Institutional Canteens, Cruise Ships Distribution Channel: Direct Sales, Wholesale Distributors, Online Retailers, Equipment Dealers, Leasing Companies |
| Companies Covered | McDonald's Corporation, Yum! Brands, Inc., Starbucks Corporation, Groupe Le Duff, Agapes Restauration, Groupe Bertrand, Buffalo Grill SA, O'Tacos, Domino's Pizza, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France HRI Market Shifts & Advancements
Equipment intelligence and thermal precision technologies are reshaping competitive positioning in French commercial kitchen procurement. Operators now demand connected cooking systems that deliver consistent output while satisfying tightening energy efficiency mandates.
Induction heating technology is converging with IoT-enabled temperature control systems in heavy-duty griddle platforms. Full-service restaurant chains in Lyon and Marseille are piloting these units for precise thermal zone management. The technology is converging with predictive maintenance software to compress downtime costs and extend equipment operational lifespans beyond traditional gas alternatives.
France's transposition of the EU F-Gas Regulation into national law imposes progressive restrictions on hydrofluorocarbon use in commercial refrigeration and associated kitchen ventilation heat pumps. Equipment manufacturers must redesign climate control integration in cooking line specifications. Fast-casual operators in the Paris-Ile-de-France corridor face accelerated replacement timelines for non-compliant ventilation-dependent equipment.
Buyer consolidation through procurement consortiums is displacing fragmented dealer relationships among mid-scale restaurant groups. Multi-unit operators in Bordeaux and Nantes now negotiate centralized equipment bundles covering range, griddle, and salamander categories. This concentration is most visible in bakery-café expansion formats seeking standardized compact cooking modules across constrained urban footprints.
France HRI Market Segmentation
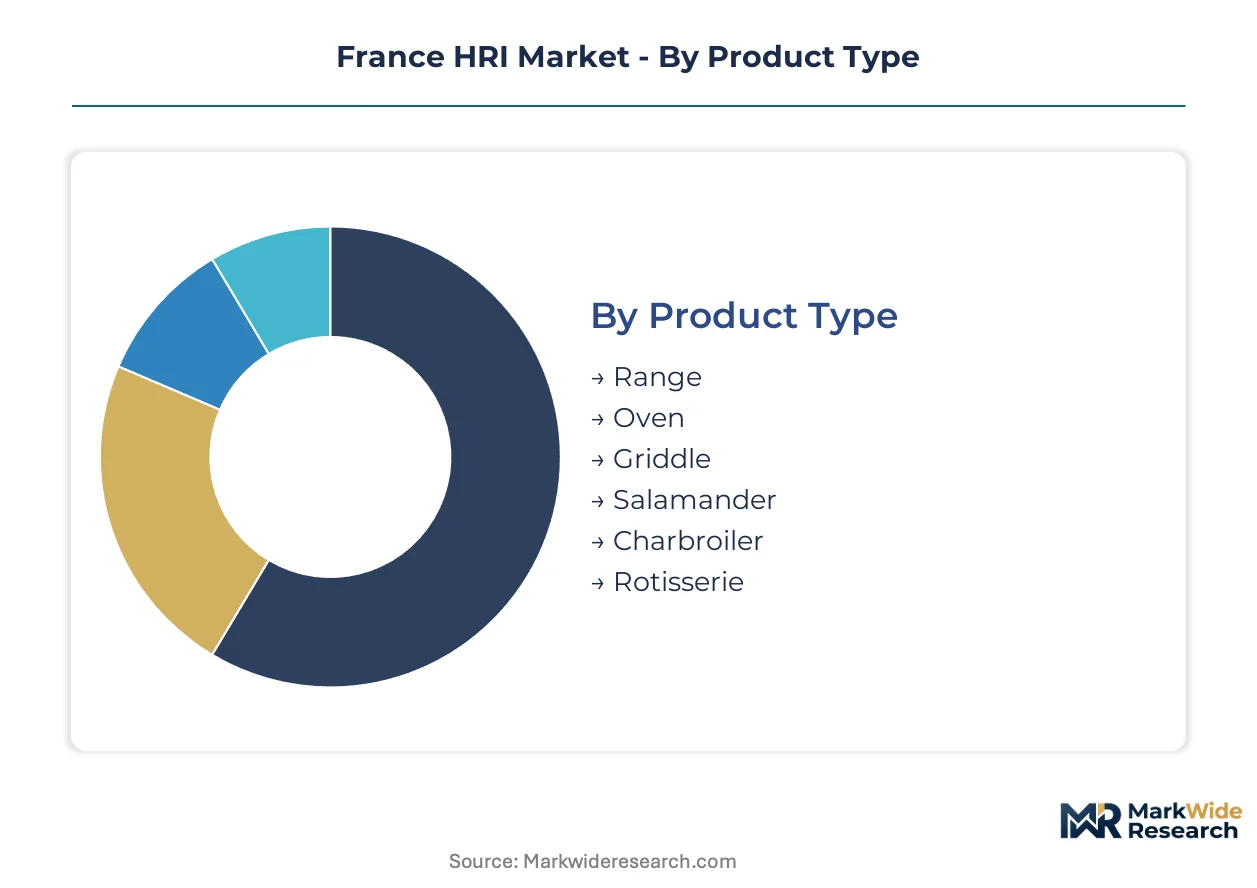
Segmentation in the France HRI market reveals how procurement patterns diverge across operator types, with regulatory compliance and kitchen footprint constraints driving category-specific demand. Equipment specification varies sharply between high-volume institutional buyers and constrained urban foodservice formats.
Product Type:
French operators prioritize thermal output consistency and energy efficiency certification when selecting cooking platforms, with power ratings and decarbonization compliance dominating capital expenditure decisions.
- Range:Heavy-duty gas and electric ranges with power ratings exceeding 10 kW form the backbone of full-service restaurant kitchens. Demand concentrates in Paris-Ile-de-France corridor establishments requiring continuous batch production capability under ANSM food-contact material standards.
- Griddle:Flat-top thermal platforms engineered for high-throughput protein and griddle-to-order preparation. Quick-service chains in Lyon and Marseille are accelerating procurement of induction-equipped models to satisfy EU Ecodesign Directive efficiency thresholds.
- Oven:Convection and combi-steam units for baking and roasting operations across hotel and institutional segments.
- Salamander:Overhead finishing equipment gaining traction in fast-casual assembly-line formats for final melt and brown operations.
- Charbroiler:Open-flame grilling platforms favored by steakhouse and burger-focused concepts seeking visual merchandising and flavor differentiation.
- Rotisserie:Vertical spit cooking systems deployed in retail-foodservice hybrid formats and high-traffic casual dining.
Volume sits with Range and Griddle categories; growth tilts toward Salamander and induction-equipped Griddle segments.
Application:
End-use environment dictates equipment durability specifications, with daily operating hours and menu complexity determining procurement budgets across French hospitality formats.
- Restaurants:Full-service and casual dining operations requiring 12+ hour daily equipment cycles. Parisian bistros and brasseries drive demand for modular range-griddle configurations that withstand intensive à-la-carte production.
- Hotels:Multi-outlet properties with banquet, breakfast, and room service operations. Properties in Bordeaux and Nantes are consolidating procurement through centralized equipment bundles covering all thermal categories.
- Cafes:Constrained-footprint bakery-café formats seeking compact all-in-one cooking modules.
- Catering Services:Mobile and off-premise food production requiring transport-durable equipment specifications.
- Event Venues:Stadiums, convention centers, and exhibition halls with episodic high-volume service demands.
- Leisure Clubs:Sports and recreation facilities with member dining and hospitality amenities.
Restaurants and Hotels anchor installed base; Catering Services and Cafes are climbing the fastest as formats expand.
End User:
Operator scale and mobility requirements fragment procurement channels, with fleet-standardization contracts displacing fragmented dealer relationships among multi-unit buyers.
- Commercial Kitchens:Fixed-location foodservice operations across independent and chain restaurant formats. These buyers negotiate directly with manufacturers for volume pricing on modular cooking lines.
- Institutional Canteens:Corporate, healthcare, and education feeding operations subject to public procurement rules. EU F-Gas Regulation amendments are accelerating ventilation system retrofits in these facilities.
- Food Trucks:Mobile operators requiring compact, high-output equipment with rapid heat-up characteristics and road-durable construction.
- Cruise Ships:Maritime galley operations with space-optimized equipment specifications and marine-grade corrosion resistance requirements.
Commercial Kitchens dominate transaction volume; Food Trucks represent the steepest expansion trajectory among emerging formats.
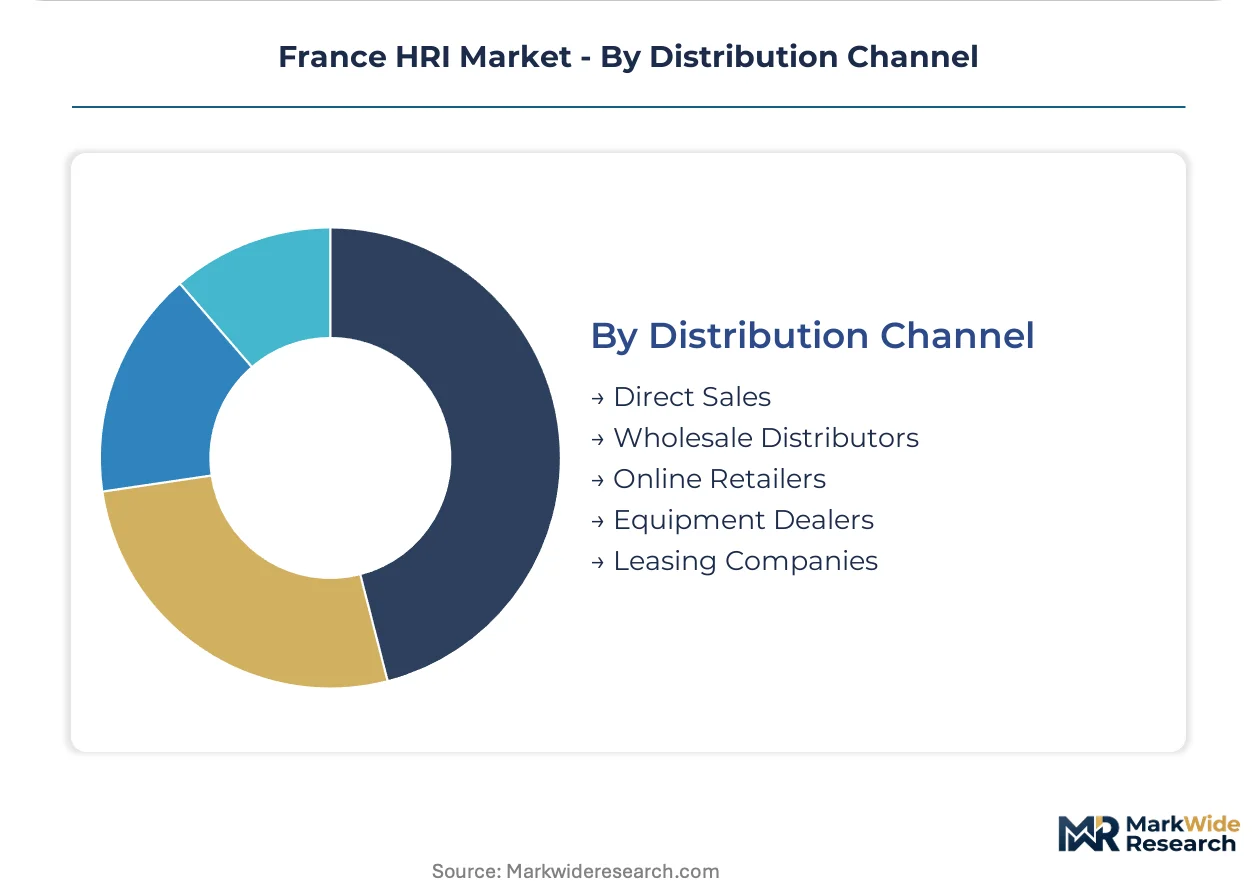
Distribution Channel:
Channel selection reflects buyer scale and standardization requirements, with direct relationships capturing margin from large operators while dealers serve fragmented independent demand.
- Direct Sales:Manufacturer-to-operator relationships for fleet-standardization contracts. McDonald's Corporation and Groupe Le Duff leverage European supply chain integration to secure bundled range-griddle-salamander configurations.
- Equipment Dealers:Local and regional distributors providing installation, commissioning, and after-sales service. These intermediaries control bulk transaction volume among independent restaurants.
- Wholesale Distributors:National and regional logistics platforms serving mid-scale multi-unit operators.
- Online Retailers:Digital procurement channels gaining share for replacement parts and compact equipment categories.
- Leasing Companies:Equipment finance providers enabling capital-constrained operators to access certified-compliant cooking platforms.
Equipment Dealers and Direct Sales split volume leadership; Leasing Companies are gaining share fastest as operators seek to manage decarbonization-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's HRI equipment production concentrates in industrial zones around Lyon and Saint-Étienne, while consumption clusters in the Paris-Ile-de-France corridor where high-density foodservice operations drive procurement volume.
Île-de-France
Parisian bistros and quick-service chains accelerate kitchen equipment replacement cycles under ANSM food-contact material standards. The EU Ecodesign Directive imposes progressive efficiency mandates on professional cooking appliances across this urban cluster. High-volume operators in central Paris negotiate fleet-standardization contracts for modular range-griddle configurations.
Auvergne-Rhône-Alpes
Lyon-based full-service restaurants pilot induction-equipped heavy-duty griddles for precise thermal zone management. CE marking requirements for gas and electrical safety elevate certification costs for equipment manufacturers headquartered in this industrial basin. Saint-Étienne anchors stainless steel fabrication supply chains serving national distribution networks.
Provence-Alpes-Côte d'Azur
Marseille fast-casual operators deploy salamander finishing equipment for assembly-line production formats. National decarbonization incentives enable gas-to-electric transitions in commercial kitchens across this tourism-dependent corridor. Coastal hotel properties in Nice consolidate procurement through centralized equipment bundles covering all thermal categories.
Hauts-de-France
Lille institutional canteens face accelerated ventilation system retrofits under EU F-Gas Regulation amendments. Public procurement rules govern equipment acquisition across corporate and education feeding operations in this northern industrial zone. Multi-unit chains bypass wholesale distributors to secure direct manufacturer relationships for standardized cooking lines.
Nouvelle-Aquitaine
Bordeaux bakery-café formats seek compact all-in-one cooking modules for constrained urban footprints. Regional equipment dealers control transaction volume among independent restaurants while losing share to direct sales channels. Leasing companies gain traction as operators manage decarbonization-driven replacement cycles across this southwestern cluster.
France HRI Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the France HRI equipment market. The vendor base splits between multinational kitchen technology platforms and regional stainless steel fabricators serving localized dealer networks. Three strategic archetypes dominate: integrated cooking line manufacturers, component specialists for ventilation and control systems, and leasing-finance hybrids capturing replacement-cycle demand. Competitive intensity centers on portfolio diversification toward electrification-ready platforms and backward integration into stainless steel supply.
Among North American-headquartered quick-service operators, McDonald's Corporation and Yum! Brands, Inc. occupy positions as fleet-standardization contract anchors, leveraging European supply chain integration to secure bundled equipment configurations. Groupe Le Duff exemplifies the bakery-café expansion archetype, anchoring procurement concentration for compact modular cooking lines. These named entities represent demand-side consolidation pressures that reshape manufacturer competitive dynamics.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Yum! Brands, Inc. |
| Starbucks Corporation |
| Groupe Le Duff |
| Agapes Restauration |
| Groupe Bertrand |
| Buffalo Grill SA |
| O'Tacos |
| Domino's Pizza, Inc. |
| Others |
Supply & Pricing Matrix
Stainless steel input costs for 304-grade and 316-grade alloys cascade through three-tier pricing structures across premium, standard, and economy equipment tiers, with Paris-Ile-de-France corridor buyers absorbing premium markups for ANSM-certified modular configurations while provincial independents negotiate volume discounts through consolidated dealer networks.
Pricing Analysis
Margin tightening in mid-tier equipment reflects raw material volatility and CE marking compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates fleet-standardization contracts from fragmented independent procurement. Cost-down pressure accelerates as electrification mandates compress replacement cycles. Quick-service chains demonstrate lowest price sensitivity; independent bistros exhibit highest.
Supply Chain Analysis
CE marking and ANSM food-contact certification requirements gate vendor qualification, compressing the supplier pool. Manufacturing concentrates in France, Italy, and Germany. Stainless steel sheet and gas burner assemblies constitute critical inputs. Single-source vulnerability looms for induction component sourcing. Distribution runs through regional equipment dealers serving fragmented demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in France HRI equipment hinges on backward integration into stainless steel fabrication and captive control over certified component supply chains.
For Market Incumbents: To counter induction technology substitution, deepen upstream control over electric heating element production and secure exclusive distribution partnerships with multi-unit chains pursuing fleet-standardization contracts.
For New Entrants and Emerging Players: Begin with compact salamander modules for fast-casual assembly-line formats, exploiting white space in finishing equipment deployment across Lyon and Marseille expansion corridors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap stainless steel fabricators in Auvergne-Rhône-Alpes with dormant CE marking capabilities. Long-term viability centers on electrification-ready platform portfolios. Monitor EU F-Gas Regulation amendment timing as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive supply of 304-grade and 316-grade inputs insulates margin from commodity volatility. |
| Electrification-Ready Platform Development | High-kW electric ranges and induction griddles align with France's national decarbonization incentives. |
| Direct Sales Channel Expansion | Manufacturer-to-operator relationships capture margin from McDonald's Corporation and Groupe Le Duff fleet contracts. |
| ANSM Certification Investment | Food-contact material compliance elevates barriers against non-compliant import competition. |
| Predictive Maintenance Software Integration | IoT-enabled thermal control systems extend operational lifespans and differentiate griddle offerings. |
Research Methodology
Document review covered EU Ecodesign Directive implementation records, ANSM certification databases, and stainless steel trade flow data, complemented by interviews with equipment procurement directors at multi-unit chains, commercial kitchen design consultants, regional dealer network managers, and maintenance service technicians. Secondary sources included CE marking compliance registries, F-Gas Regulation amendment tracking, and hospitality industry capital expenditure surveys. Bottom-up equipment shipment estimates were cross-referenced against top-down foodservice operator expansion plans.
Historical volume trajectories were cross-referenced against panel input from manufacturer sales executives and distributor inventory managers. Segmentation modeling covered product type, application environment, end-user scale, and distribution channel across the analysis window. CAGRs were derived from regression analysis of replacement cycle compression and regulatory mandate acceleration. Forecast inputs incorporated electrification infrastructure deployment timelines and EU F-Gas phase-down schedules.
Underlying measurement precision varies by segment; range and griddle categories carry tighter precision than salamander and rotisserie due to established shipment reporting. Forecasts reflect assumptions around regulatory compliance timelines and raw material cost stabilization. A model refresh is warranted upon material change in EU Ecodesign Directive enforcement intensity or national decarbonization subsidy allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Global Offshore Catering Services Market