
 North America Restaurant Furniture Market | 2026-2036
North America Restaurant Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Restaurant Furniture Market Insights
Buyer consolidation among fast-casual and quick-service chains is recalibrating procurement volumes and contract terms across the supply base. Grand Rapids Chair Co leverages its Michigan manufacturing footprint to anchor supply relationships with regional restaurant groups. Herman Miller, Inc competes on design-forward seating systems that differentiate within the fine-dining segment. Steelcase Inc. sustains channel control through direct sales teams serving national franchise operators.
North America restaurant furniture encompasses fixed and movable seating, surface, and storage systems engineered for commercial foodservice environments, typically rated for fire resistance, load-bearing capacity, and cleanability under ANSI/BIFMA standards. The primary purpose centers on optimizing diner throughput, brand expression, and staff workflow efficiency in high-traffic eating establishments. Chairs and tables occupy the largest volume share across the product type dimension, though upholstered booths command premium margin pools in the fine-dining and luxury price tiers. Metal and wood materials dominate structural applications, while plastic variants are displacing traditional options in fast-food and economy segments where replacement cycles compress.
The U.S. Access Board enforces ADA compliance on seat heights, knee clearances, and reach ranges, directly constraining design freedom and tooling investments for domestic manufacturers. Health Canada and the U.S. Consumer Product Safety Commission coordinate on flammability standards for upholstered components, creating dual-jurisdiction certification burdens for cross-border suppliers. Stakeholders must monitor evolving state-level building codes and sustainability procurement mandates as municipalities from Vancouver to New York City tighten embodied-carbon requirements for commercial interiors.
Market Dynamics
Fast-casual chains are compressing interior refresh cycles from seven years to three, forcing manufacturers to engineer modular seating systems that accommodate rapid reconfiguration without full replacement.
Growth Catalysts
- ADA Accessibility Mandates:The U.S. Access Board's updated knee-clearance specifications are compelling restaurants to replace non-compliant booths, creating replacement demand across Texas, California, and Florida dining establishments.
- Texas Restaurant Density:Dallas-Fort Worth, Houston, and Austin are outpacing national opening averages, concentrating procurement volumes with regional manufacturers capable of rapid-turn upholstery and metal fabrication.
- Cross-Laminated Timber:Engineered wood products are penetrating mid-market dining chains seeking fire-rated structural seating with lower embodied carbon than conventional hardwood alternatives.
Market Restraints
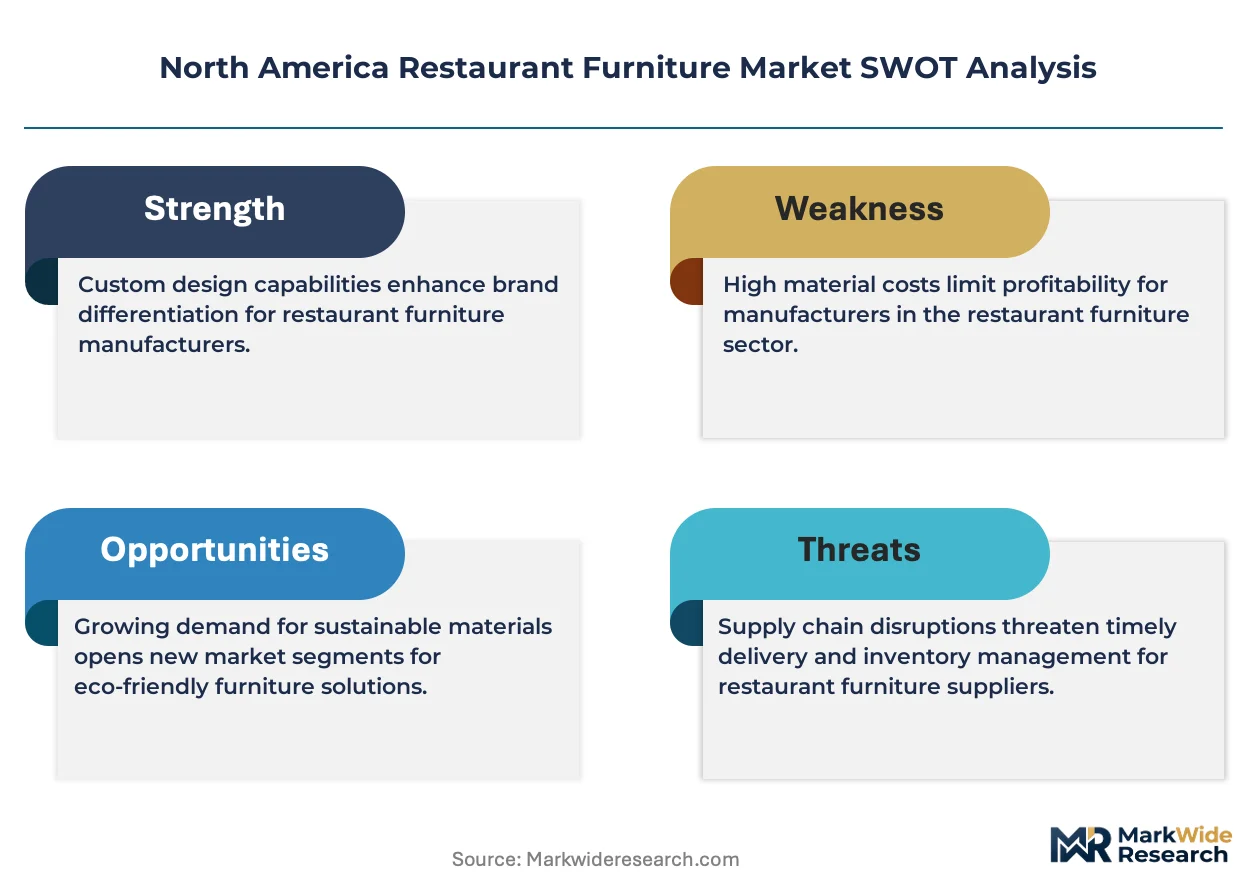
- Steel Tariff Volatility:Section 232 duties on imported aluminum and steel have destabilized input costs for metal-frame chair producers serving price-sensitive quick-service operators.
- Canadian Upholstery Concentration:Three Ontario textile mills supply the majority of North American commercial-grade vinyl, creating single-source vulnerability for flame-retardant seating components.
- Flammability Testing Bottlenecks:Health Canada's coordination delays with U.S. CPSC on dual-jurisdiction certification are extending product launch timelines by four to six months for cross-border suppliers.
Strategic Opportunities
- Mexico Manufacturing Expansion:Guanajuato and Querétaro are attracting U.S. furniture brands seeking duty-advantaged production capacity within USMCA trade corridors.
- California Title 24 Compliance Services:Energy-efficient seating design consulting represents a service-layer revenue stream as municipalities from San Diego to Sacramento tighten commercial interior standards.
- Direct-to-Franchise Digital Platforms:Configurator tools enabling unit-level managers to specify and order replacement seating without distributor intermediaries are capturing margin previously allocated to dealer networks.
Industry Challenges
- Commercial Upholstery Craft Shortage:Michigan and North Carolina training programs are failing to replace retiring specialists capable of hand-tufted booth construction for fine-dining specifications.
- Legacy ERP Integration:Mid-sized manufacturers with decades-old inventory systems face data-migration costs when onboarding national chain clients requiring real-time order visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Restaurant Furniture Market |
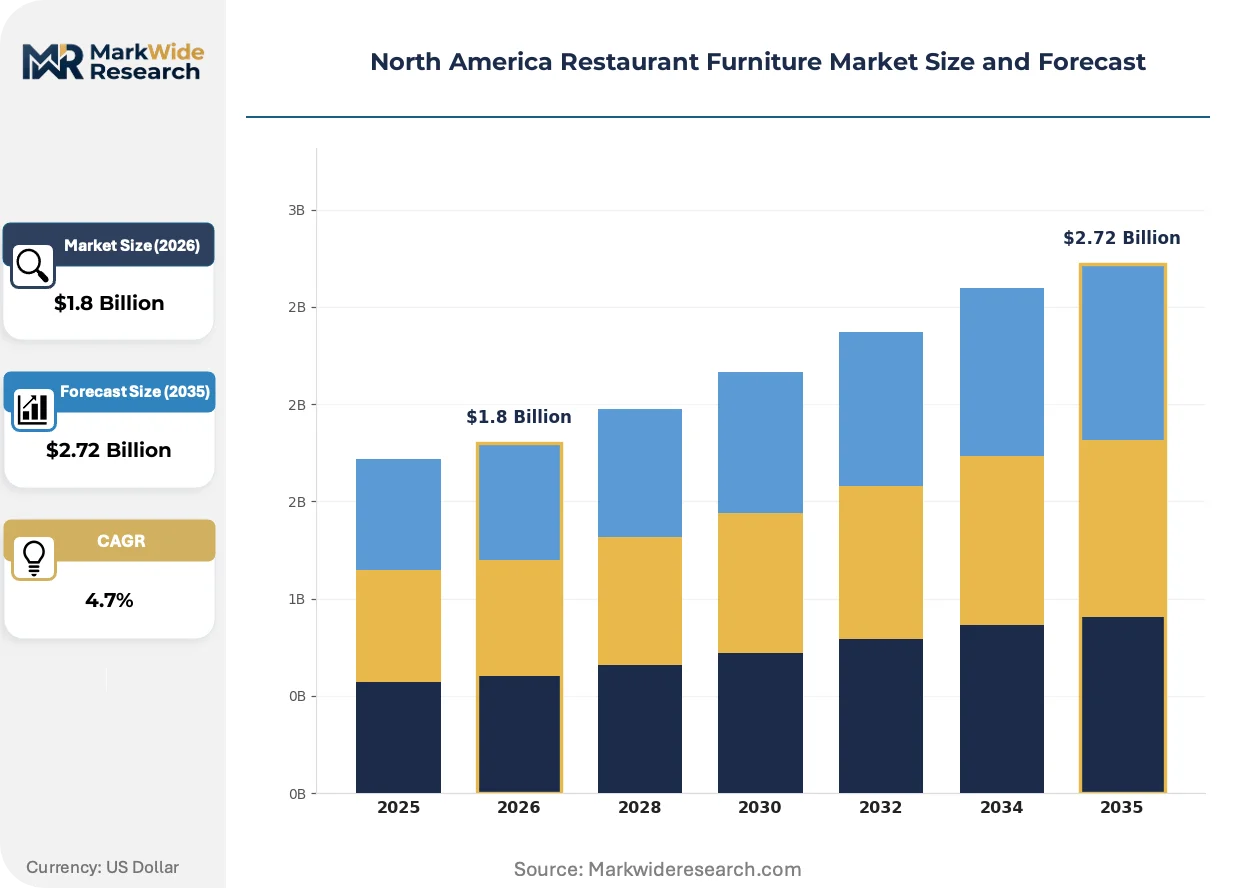
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Booths, Bar Stools Material: Wood, Metal, Plastic, Upholstered End User: Casual Dining, Fast Food, Fine Dining, Cafés Price Tier: Economy, Mid-Range, Luxury, Custom |
| Companies Covered | Steelcase Inc., Herman Miller, Inc, Knoll, Grand Rapids Chair Co, California House, Tropitone Furniture Co, Plymold Seating, Woodard Furniture, MTS Seating, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Restaurant Furniture Market Trends and Innovations
Digital fabrication and regulatory pressure are rewriting how seating systems are specified, produced, and certified across the continent's foodservice operations.
Modular seating platforms with tool-free reconfiguration hardware are converging with cloud-based space-planning software, enabling fast-casual operators to redesign floor plans between lunch and dinner rushes. Chains in Denver and Portland are piloting magnetic table bases and stackable shell chairs that reduce labor hours for layout changes. This convergence is compressing the traditional distinction between fixed and movable furniture categories.
California's Title 24 energy standards now mandate daylight-responsive controls in new restaurant construction, indirectly pressuring furniture placement to maximize natural light penetration. Manufacturers are responding with lower-profile seating backs and translucent partition materials that maintain diner density while satisfying illumination requirements. The standard most acutely affects full-service operators in Los Angeles and San Francisco pursuing LEED certification.
Corporate procurement teams at multi-unit chains are consolidating vendor rosters from twelve suppliers to three preferred partners, demanding volume-tier pricing and dedicated account management. Regional restaurant groups in Chicago and Atlanta are mirroring this behavior, replacing transactional purchasing with multi-year framework agreements. Texas-based fast-casual brands exhibit the most aggressive consolidation, leveraging opening velocity to extract custom tooling concessions.
North America Restaurant Furniture Market Segmentation

Segmentation in the North America restaurant furniture market reveals how procurement patterns split across operational models and regulatory environments. Understanding these divides helps manufacturers align production capacity with the divergent replacement cycles and compliance burdens of each customer type.
Product Type:
Standalone seating systems dominate high-turnover installations, while integrated table-booth combinations embed permanently in fine-dining builds across California and Texas.
- Chairs:Metal and wood frame constructions rated for ANSI/BIFMA load-bearing standards serve as the workhorse category for fast-casual chains. Demand concentrates in Dallas-Fort Worth and Houston, where rapid restaurant openings force suppliers to maintain stockpiles of stackable shell designs for immediate deployment.
- Tables:Surface systems span laminate, solid surface, and reclaimed wood options, with fire-rated edge banding mandatory under California Title 24. Texas-based fast-casual operators are consolidating procurement around standardized 30-inch and 42-inch diameters to simplify inventory management across multi-unit expansions.
- Booths:Upholstered bench seating with fixed pedestal mounting commands premium positioning in full-service establishments.
- Bar Stools:Elevated seating for counter service and bar areas, typically specifying footrest integration and swivel mechanisms.
Chairs lead volumes today; booths are gaining share fastest as ADA knee-clearance mandates trigger replacement waves across Florida and California dining rooms.
Material:
Cost tiering separates structural materials, with premium hardwoods and commercial-grade metals anchoring fine-dining specifications while engineered substitutes penetrate price-sensitive quick-service accounts.
- Wood:Solid hardwood and cross-laminated timber variants deliver fire-rated structural performance with lower embodied carbon than conventional alternatives. California operators pursuing LEED certification are specifying FSC-certified oak and walnut for visible surfaces, though Michigan manufacturers report supply tightness on thick stock suitable for booth framing.
- Metal:Steel and aluminum frame constructions dominate quick-service and fast-casual seating, with powder-coated finishes resisting corrosion in high-humidity kitchen environments. Section 232 tariff volatility on imported aluminum has pushed Dallas-area fabricators toward domestic steel sourcing despite higher per-unit costs.
- Plastic:Polypropylene and fiberglass-reinforced shell chairs displace wood in economy-tier fast-food installations.
- Upholstered:Foam-core seating with commercial vinyl or fabric coverings, subject to Health Canada and U.S. CPSC flammability coordination.
Metal leads volumes today; wood is climbing the fastest as cross-laminated timber penetrates mid-market sustainability specifications.
End User:
Application intensity varies sharply, with fast-food operators compressing replacement cycles to three years while fine-dining establishments amortize seating investments over decade-long horizons.
- Casual Dining:Full-service establishments with moderate price points, typically specifying mixed seating arrays of chairs, booths, and community tables. Operators in Chicago and Atlanta are consolidating vendor rosters from twelve suppliers to three preferred partners, demanding dedicated account management for multi-location frameworks.
- Fast Food:High-turnout quick-service concepts prioritize durability and cleanability over aesthetics, specifying molded plastic and powder-coated metal for survival in abrasive cleaning protocols. Texas-based chains exhibit the most aggressive procurement consolidation, leveraging opening velocity to extract custom tooling concessions from regional manufacturers.
- Fine Dining:Luxury establishments emphasizing bespoke craftsmanship and brand differentiation.
- Cafés:Coffee-focused and light-meal concepts with flexible seating for laptop workers and brief encounters.
Fast food leads volumes today; fine dining is expanding most quickly as post-pandemic experiential spending redirects toward destination dining.
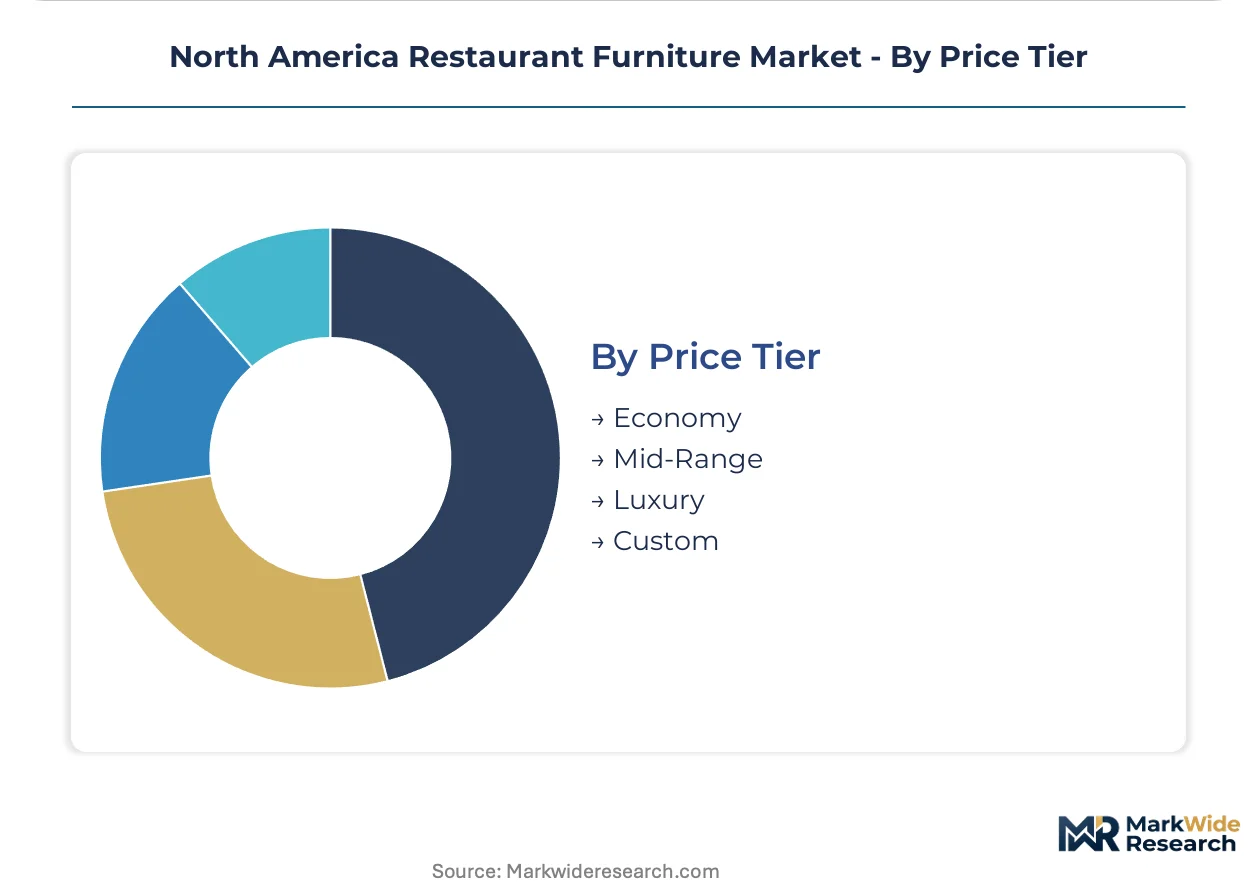
Price Tier:
Customer type and margin structure map directly onto four pricing strata, with procurement authority increasingly centralized at corporate level for multi-unit operators.
- Economy:Injection-molded plastic and basic metal stacking chairs serving price-sensitive independent operators and institutional foodservice. Mexican manufacturing in Guanajuato and Querétaro supplies this tier through USMCA-advantaged production corridors.
- Mid-Range:Commercial-grade wood and metal hybrids with standardized upholstery options, capturing the bulk of fast-casual procurement. Denver and Portland operators are piloting magnetic table bases and reconfigurable shell chairs that reduce labor hours for layout changes.
- Luxury:Designer-specified seating with premium materials and extended warranties for fine-dining and hospitality groups.
- Custom:Bespoke fabrication for flagship locations and celebrity chef concepts, typically involving hand-tufted booth construction from dwindling Michigan and North Carolina specialist pools.
Mid-range leads volumes today; custom is gaining share fastest as flagship location competition intensifies among emerging fast-casual brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's upholstery mills supply flame-retardant textiles across the continent, while U.S. state-level energy codes fragment procurement specifications. Mexico's manufacturing corridors attract brands seeking duty-advantaged production capacity within USMCA trade zones.
United States
Texas concentrates restaurant opening velocity, with Dallas-Fort Worth, Houston, and Austin outpacing national averages. California's Title 24 energy standards mandate daylight-responsive controls that reshape furniture placement for natural light optimization. Michigan manufacturers anchor hardwood supply relationships with regional restaurant groups seeking fire-rated structural seating.
Canada
Three Ontario textile mills supply the majority of North American commercial-grade vinyl for upholstered seating. Health Canada coordinates flammability standards with U.S. CPSC, creating dual-jurisdiction certification burdens for cross-border suppliers. Toronto-area fabricators face testing bottlenecks extending product launch timelines by four to six months.
Mexico
Guanajuato and Querétaro attract U.S. furniture brands seeking production capacity within USMCA trade corridors. Mexican manufacturing serves economy-tier injection-molded plastic and basic metal stacking chair demand for price-sensitive operators. Northern border states concentrate upholstery assembly operations serving quick-service procurement consolidation.
North America Restaurant Furniture Market Competitive Landscape
Michigan producers anchor one tier; Canadian textile specialists hold supply-side concentration for flame-retardant components. The vendor base splits between scale-driven manufacturers with dedicated sales teams and regional fabricators serving local restaurant groups. Three strategic archetypes emerge: design-forward seating systems for fine-dining differentiation, modular platforms for fast-casual reconfiguration, and economy-tier commodity producers. Competitive moves center on Mexico manufacturing expansion and direct-to-franchise digital platform development.
Among Michigan-based manufacturers, Grand Rapids Chair Co exemplifies regional supply relationships with restaurant groups, while Steelcase Inc. occupies a position serving national franchise operators through direct sales infrastructure. Herman Miller, Inc represents the design-forward archetype competing on seating systems that differentiate within premium dining segments. These three companies illustrate how geographic origin and organizational structure map onto distinct competitive vectors in procurement consolidation.
| Leading Market Players |
|---|
| Steelcase Inc. |
| Herman Miller, Inc |
| Knoll |
| Grand Rapids Chair Co |
| California House |
| Tropitone Furniture Co |
| Plymold Seating |
| Woodard Furniture |
| MTS Seating |
| Others |
Pricing and Supply Chain Analysis
Commercial upholstery craft concentration in Michigan and North Carolina generates labor-cost differentials that widen spreads between custom hand-tufted booth pricing and economy-tier injection-molded alternatives. These regional skill pools anchor premium-tier margins while Mexican manufacturing corridors compress floor pricing for standardized quick-service seating.
Pricing Analysis
Capacity additions in Guanajuato and Querétaro are reshaping price floors for economy-tier metal and plastic seating serving USMCA-advantaged procurement. Three-tier pricing structure across custom, mid-range, and economy levels separates hand-crafted booth construction from modular fast-casual platforms and commodity quick-service shells. Price differentiation hinges on flame-retardant certification grade and customization depth. Cost compression in mid-range metal-frame categories is intensifying because Section 232 steel tariff volatility destabilizes input costs. Quick-service operators exhibit highest price sensitivity; fine-dining hospitality groups absorb premium positioning for bespoke craftsmanship.
Supply Chain Analysis
Refurbishment flows for commercial-grade vinyl upholstery create secondary material circuits extending component lifecycles beyond initial deployment. Geographic supply concentration centers on Mexico for economy-tier fabrication, Michigan and North Carolina for hardwood structural seating, and Ontario for flame-retardant textile inputs. Raw material dependencies encompass FSC-certified oak and walnut, powder-coated domestic steel, and commercial-grade vinyl from three Ontario mills. Single-source vulnerability in Canadian upholstery concentration threatens seating component availability. Distribution runs through direct sales teams serving national franchise operators alongside regional fabricator relationships with independent restaurant groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America restaurant furniture market functions as a stable compounder anchored by persistent replacement demand from fast-casual expansion and ADA compliance mandates. Physical footprint growth across Texas, California, and Florida generates recurring procurement volumes regardless of macroeconomic cycles.
For Market Incumbents: Cement supply relationships with Texas-based fast-casual chains by anchoring rapid-turn upholstery and metal fabrication capacity in Dallas-Fort Worth corridors. Defend against Mexican manufacturing encroachment by investing in cross-laminated timber fire-rating certifications that differentiate sustainable structural seating. Deepen backward integration into FSC-certified hardwood sourcing to control embodied-carbon compliance costs as California Title 24 standards tighten.
For New Entrants and Emerging Players: Launch via direct-to-franchise digital configurators that bypass established dealer networks and capture margin previously allocated to distribution intermediaries. Target mid-market fast-casual operators in Denver and Portland piloting magnetic table bases and reconfigurable shell chairs. Exploit white-space in California Title 24 compliance consulting services as municipalities from San Diego to Sacramento mandate daylight-responsive furniture placement optimization.
For Investors and Strategic Acquirers: Multi-unit fast-casual corporate procurement teams are the most active acquirer in this space, consolidating vendor rosters to extract volume-tier pricing and custom tooling concessions. Long-term viability rests on exposure to replacement-cycle compression and regulatory-driven refresh demand. Acquisition target archetype: regional manufacturers with Ontario textile mill relationships and USMCA-advantaged Mexican production footprints. Monitor Health Canada and U.S. CPSC flammability coordination delays as inflection indicator for cross-border supply chain disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Mexico Manufacturing Expansion | Guanajuato and Querétaro production capacity secures USMCA duty advantages for economy-tier seating exports. |
| Direct-to-Franchise Digital Platform | Configurator tools capture dealer-network margin by enabling unit-level manager specification autonomy. |
| Cross-Laminated Timber Certification | Fire-rated engineered wood penetration addresses California LEED procurement mandates with lower embodied carbon. |
| ADA Compliance Service Layer | Title 24 consulting revenue diversifies manufacturers beyond product sales into regulatory advisory streams. |
| Canadian Textile Supply Integration | Vertical control over Ontario flame-retardant vinyl mills mitigates single-source vulnerability for upholstered components. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fast-casual procurement directors, commercial upholstery specialists, Michigan hardwood suppliers, and Ontario textile mill operators alongside secondary validation. Secondary sources encompassed ANSI/BIFMA certification databases, U.S. Access Board ADA compliance filings, Health Canada flammability coordination records, and USMCA trade corridor customs data. Bottom-up unit economics from restaurant opening velocity in Texas, California, and Florida converged with top-down market sizing across the analysis window.
Segment-weighting approaches distributed value and volume across product type, material composition, end-user operational model, and price tier dimensions. Modeled categories included fixed versus movable seating systems, wood-metal-plastic material splits, fast-casual versus fine-dining application intensity, and custom-to-economy pricing stratification. CAGRs derived from replacement cycle compression rates, regulatory refresh mandates, and regional opening velocity differentials. Industry-specific forecast inputs incorporated Title 24 energy standard adoption curves and ADA knee-clearance specification rollout timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel tariff volatility and Canadian upholstery supply disruption scenarios. Practitioners should monitor Health Canada-U.S. CPSC flammability testing bottlenecks, Section 232 duty adjustments, and Texas restaurant opening velocity for early signals of supply-demand rebalancing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Hospitality Furniture Market
Hospitality Management and Services
US Catering Services Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market