
 Curcumin Food Color Market | 2026-2036
Curcumin Food Color Market Size, Share, and Industry Trends Forecast 2026-2036
Curcumin Food Color Market Outlook
India is tilting toward expanded curcumin extraction capacity as domestic turmeric processors scale colorant-grade output. Synthite Industries Ltd leverages vertical integration from raw turmeric sourcing to refined oleoresin production. Arjuna Natural Pvt Ltd anchors its position through sustained R&D intensity in bioavailable curcumin formulations. Sabinsa Corporation competes on technology leadership in solvent-free extraction methods that preserve color stability.
Curcumin food color denotes a yellow-orange pigment extracted from Curcuma longa rhizomes, typically standardized to 90-95% curcuminoid content for commercial food applications, functioning primarily as a pH-sensitive natural colorant in acidic to neutral matrices. The natural product type segment dominates value capture as clean-label mandates from retail chains displace synthetic alternatives. Powder form concentrates margin pools among food manufacturers seeking shelf-stable, high-concentration inputs for dry-mix applications. Beverage application shows the fastest structural expansion, driven by demand for visually differentiated functional drinks.
FDA GRAS determinations and EFSA food additive evaluations shape formulation standards and cross-border market access for curcumin colorants. India's FSSAI purity specifications and BIS extraction residue limits govern domestic production quality thresholds. Stakeholders must monitor evolving EU Novel Food classifications for nano-encapsulated curcumin delivery systems that promise enhanced color stability.
Market Dynamics
Clean-label mandates from major retail chains are compressing synthetic colorant demand while accelerating procurement shifts toward turmeric-derived alternatives. This structural pull is forcing beverage manufacturers to reformulate around pH-sensitive natural pigments that deliver visual differentiation without artificial additives.
Growth Catalysts
- FDA GRAS Expansion:Broader safety clearances for turmeric-derived ingredients reduce regulatory friction for new food colorant entrants, shortening time-to-market for novel formulations.
- Beverage Clean-Label Mandates:Functional drink producers are specifying natural colorants in supplier contracts, creating dedicated procurement channels for curcumin suppliers.
- India's Cultivation Clusters:Concentrated turmeric farming regions around Erode and Nizamabad provide feedstock proximity that lowers extraction input costs.
Market Restraints
- Input Cost Volatility:Turmeric rhizome prices fluctuate with monsoon patterns, squeezing margin stability for extraction processors dependent on spot market sourcing.
- Technical Color Instability:Curcumin's pH sensitivity above neutral matrices limits application breadth, excluding alkaline food categories from addressable demand.
- Substitution Threat:Carotenoid and anthocyanin alternatives offer superior light stability, capturing shelf-life-critical applications where curcumin degrades.
Strategic Opportunities
- Nano-Encapsulation Convergence:Liposomal and micellar delivery technologies promise enhanced color stability, opening alkaline beverage applications previously closed to curcumin.
- EU Novel Food Pathway:EFSA evaluation frameworks for enhanced bioavailability formats create regulatory runway for premium colorant-positioned ingredients.
- Direct-to-Manufacturer Channels:Bypassing traditional ingredient distributors through digital procurement platforms reduces margin capture by intermediaries.
Industry Challenges
- Extraction Skill Scarcity:Solvent-free processing expertise remains concentrated among a limited pool of chemical engineers, constraining capacity scaling.
- Certification Timeline Compression:FSSAI purity audits and BIS residue testing create multi-month approval bottlenecks for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curcumin Food Color Market |
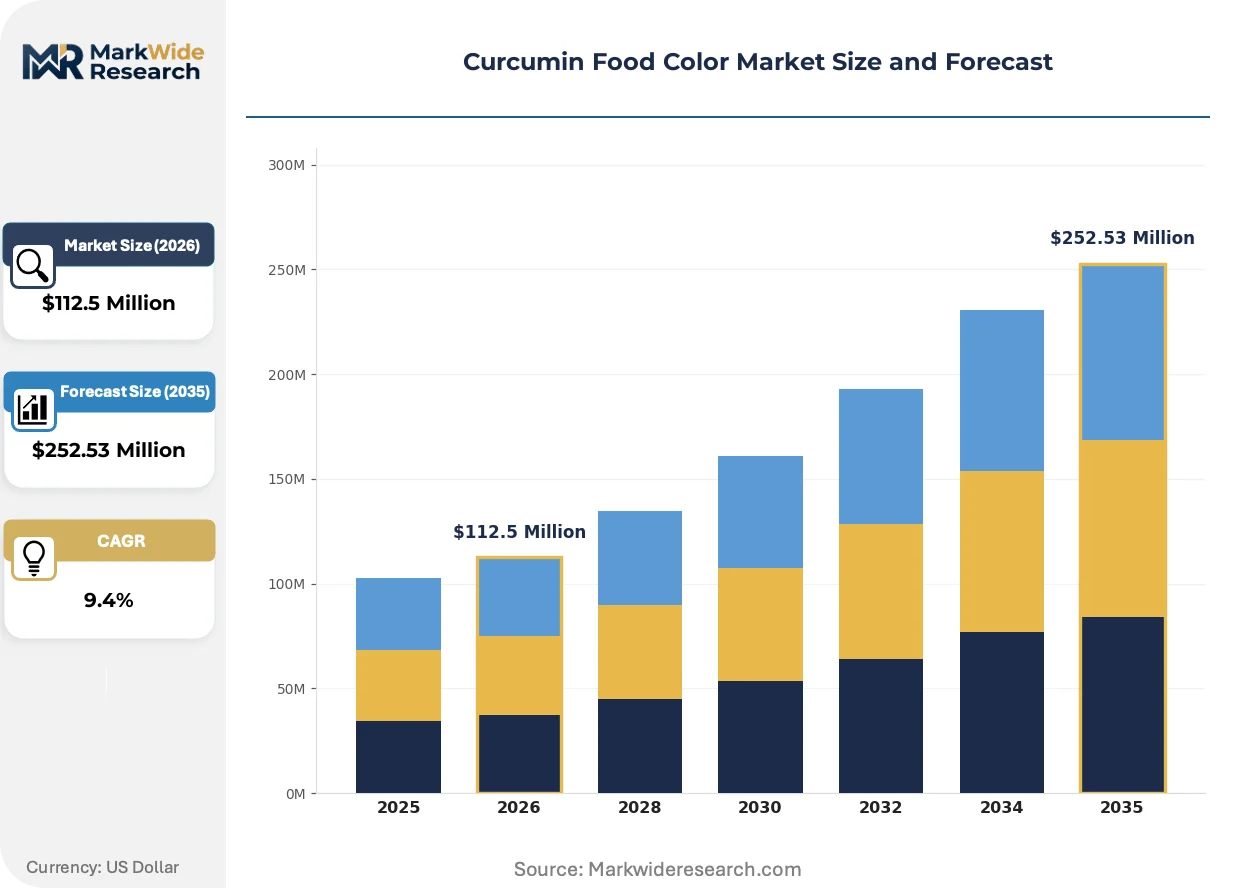
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $252.53 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Conventional Application: Beverages, Dairy Products, Bakery Goods, Sauces Form: Powder, Liquid, Gel, Granular End User: Food Manufacturers, Beverage Producers, Retail Chains, Caterers |
| Companies Covered | Synthite Industries Ltd, Arjuna Natural Pvt Ltd, Sabinsa Corporation, Biomax Life Sciences Limited, Kancor Ingredients Limited, Roha Dyechem Pvt. Ltd., GNT International B.V., D.D. Williamson & Co. Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curcumin Food Color Market Strategic Shifts
Technology convergence around stabilization and delivery systems is expanding curcumin's addressable application matrix beyond traditional acidic foods. These advances are compressing the performance gap with synthetic alternatives while preserving clean-label positioning.
Solvent-free supercritical CO2 extraction is rendering obsolete conventional ethanol-based processing that degrades heat-sensitive curcuminoids. Premium beverage manufacturers are specifying this method in supplier qualification protocols. The technology is compressing color variance between batches, reducing reformulation costs for brand owners.
EFSA's evolving stance on nano-encapsulated food additives is creating compliance complexity for enhanced-stability formats. The regulator's draft guidance on particle-size thresholds demands additional toxicological data packages. European functional drink producers are delaying launch timelines pending classification clarity.
Brand owners are consolidating supplier relationships around vertically integrated turmeric processors capable of traceability documentation from farm to finished colorant. This behavioral shift is disintermediating traditional spice traders who lack extraction capabilities. India's domestic market exhibits this pattern most acutely as FSSAI mandates tighten provenance requirements.
Curcumin Food Color Market Segmentation
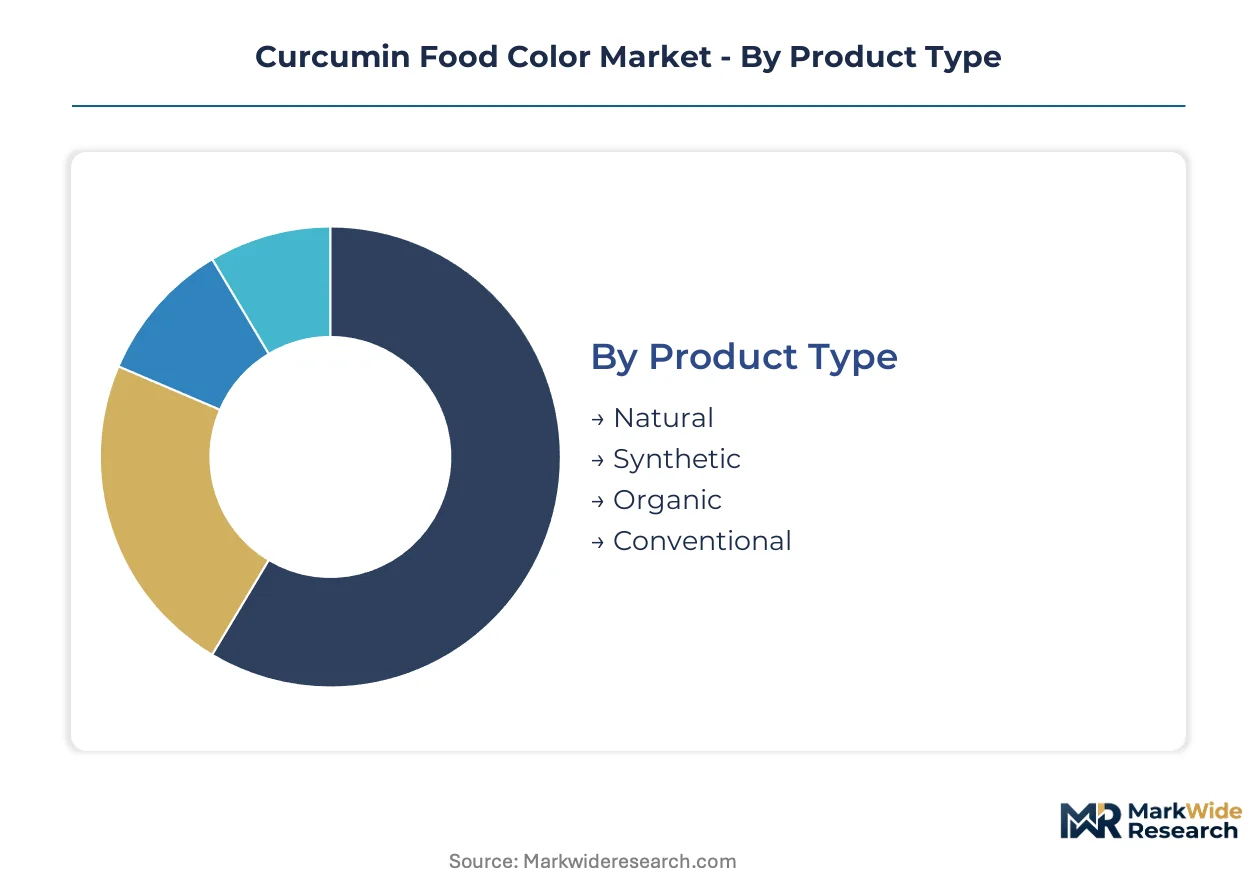
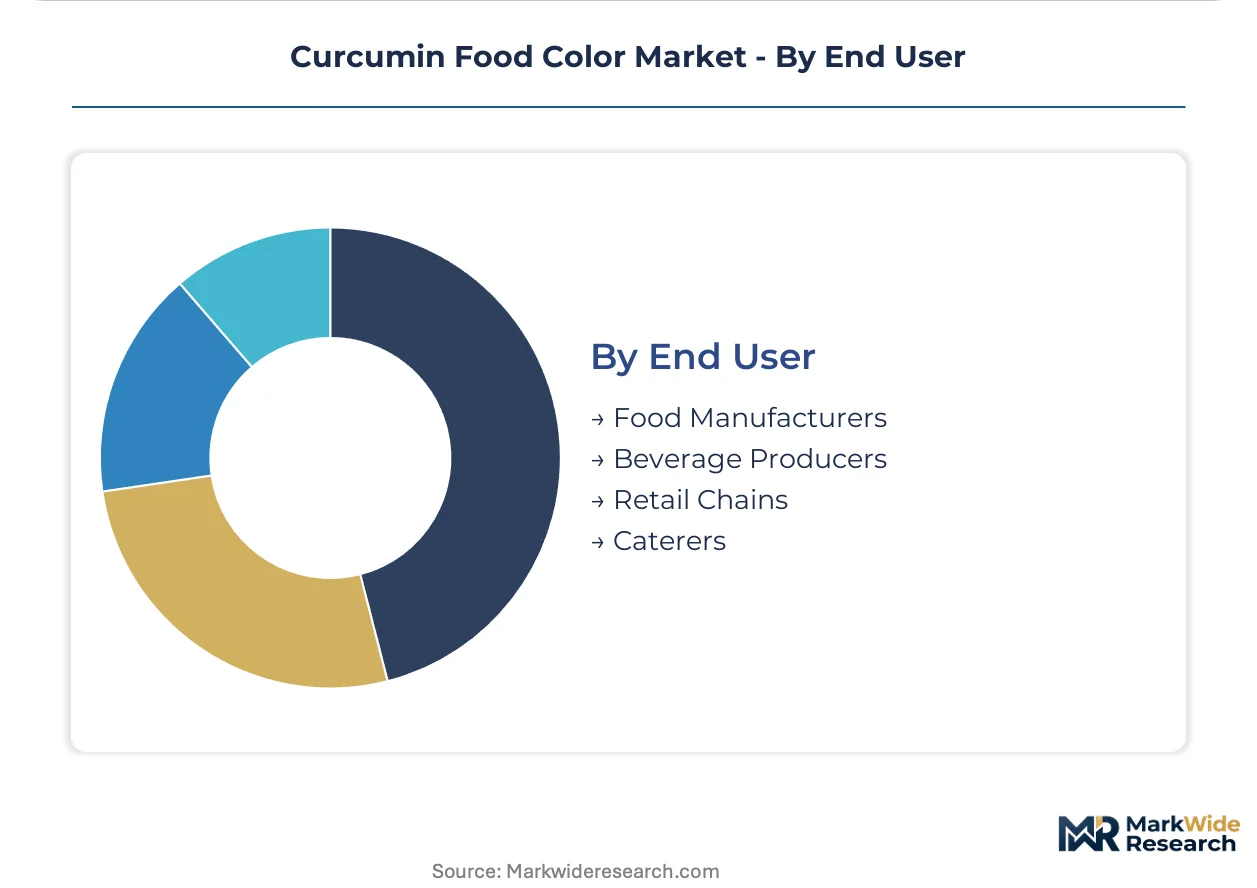
Curcumin food color procurement varies sharply across buyer types, with beverage producers demanding rapid technical support for pH-sensitive formulations while retail chains prioritize documentation traceability. Segmentation reveals where margin pools concentrate and which customer relationships require dedicated service investment.
Product Type:
After-sales intensity spikes for natural curcumin buyers who need shelf-life troubleshooting and reformulation guidance when color degradation occurs.
- Natural:Extracted from Curcuma longa rhizomes and standardized to 90-95% curcuminoid content, this grade commands premium positioning as FDA GRAS notifications expand. Beverage producers in India specify natural grades in supplier contracts to meet clean-label mandates from domestic retail chains.
- Synthetic:Chemically manufactured tartrazine and sunset yellow alternatives offer superior light stability and lower unit costs. Demand concentrates in cost-sensitive sauce applications where regulatory scrutiny of artificial additives remains lighter.
- Organic:Certified organic extraction from pesticide-free turmeric cultivation meets EU organic labeling requirements. European functional drink producers source this grade for premium positioning despite 40-60% price premiums over conventional natural.
- Conventional:Non-certified natural curcumin from standard agricultural practices serves price-sensitive bakery and dairy applications. Indian domestic manufacturers favor this grade for turmeric-flavored snacks and traditional sweets.
By volume, Conventional leads. By growth pace, Natural is ahead.
Application:
Margin structure varies dramatically across food matrices, with acidic beverages tolerating curcumin's pH sensitivity while alkaline dairy demands stabilization investments.
- Beverages:Functional drinks, juices, and flavored waters leverage curcumin's yellow-orange hue for visual differentiation. Clean-label procurement from beverage producers is accelerating as retail chains ban synthetic colorants from store-brand offerings.
- Dairy Products:Yogurt, cheese, and ice cream applications require nano-encapsulation to prevent color shift in neutral-to-alkaline pH. EFSA's pending classification of encapsulated formats creates compliance uncertainty for European processors.
- Bakery Goods:Breads, cakes, and pastries utilize heat-stable curcumin variants for golden crust coloring. Indian commercial bakeries source powder forms for dry-mix integration in traditional festival sweets.
- Sauces:Mustard, curry sauces, and dressings exploit curcumin's natural affinity for acidic matrices. Shelf-life requirements here are less stringent than retail beverage applications.
Beverages capture the steepest expansion trajectory, though Dairy commands the highest per-kilogram pricing.
Form:
Supply chain configuration determines which formats processors can economically produce from their extraction infrastructure.
- Powder:Spray-dried curcumin concentrate offers 24-month shelf stability and precise dosing for dry-mix manufacturers. Food manufacturers in India's turmeric belt prefer this form for logistics efficiency.
- Liquid:Oil-based or propylene glycol suspensions enable direct injection into beverage production lines. Solvent-free extraction methods from supercritical CO2 processing yield premium liquid grades.
- Gel:Viscous water-dispersible formats suit small-batch artisanal producers and catering applications. Limited commercial scale keeps this niche expensive.
- Granular:Agglomerated particles reduce dust exposure and improve flow properties for automated dosing equipment. Bakery manufacturers specify this form for occupational safety compliance.
Powder dominates tonnage shipments, while Liquid formats are climbing fastest on beverage industry demand.
End User:
Procurement sophistication separates multinational beverage producers with dedicated colorant laboratories from fragmented catering operators buying spot quantities.
- Food Manufacturers:Large-scale processors of snacks, cereals, and prepared meals negotiate multi-year supply agreements with traceability documentation. FSSAI purity audits drive consolidation toward vertically integrated turmeric processors.
- Beverage Producers:Functional drink specialists and private-label bottlers specify supercritical CO2 extracted grades with batch-to-batch color consistency. This segment demands the most intensive technical service relationships.
- Retail Chains:Supermarket private-label buyers mandate clean-label ingredient decks and farm-to-fork documentation. Their collective procurement power is disintermediating traditional spice traders lacking extraction capabilities.
- Caterers:Institutional food service and restaurant chains purchase smaller volumes with less stringent stability requirements. Price sensitivity here favors conventional grades over premium natural positioning.
Food Manufacturers move the largest absolute volumes, yet Beverage Producers are gaining share fastest on clean-label reformulation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI purity specifications and BIS extraction residue limits anchor India's regulatory framework for curcumin food color production. India dominates cultivation clusters and extraction infrastructure, while import demand concentrates in North America and Europe where clean-label mandates accelerate procurement shifts.
India
Erode and Nizamabad cultivation belts supply raw turmeric to domestic extraction facilities. FSSAI mandates tighten provenance documentation requirements for food colorant-grade output. Synthite Industries Ltd leverages vertical integration from farm sourcing through refined oleoresin production in Kerala.
United States
FDA GRAS notifications for turmeric-derived ingredients reduce regulatory friction for beverage reformulation cycles. Archer Daniels Midland Company maintains distribution networks serving clean-label procurement from retail chains. California functional drink producers specify natural colorants in supplier qualification protocols.
Germany
EFSA food additive evaluations shape formulation standards for cross-border EU market access. GNT International B.V. operates extraction capabilities serving German beverage manufacturers. Bavarian dairy processors demand nano-encapsulated grades for neutral pH applications pending classification clarity.
Netherlands
Rotterdam logistics hubs facilitate re-export of Indian-origin curcumin to European compounders. REACH compliance requirements govern import documentation for food-grade oleoresins. GNT International B.V. maintains refining operations serving Benelux bakery and confectionery manufacturers.
China
SAMR food additive standards govern domestic curcumin colorant approvals for beverage applications. Zhejiang and Shandong provinces host extraction facilities serving regional sauce and seasoning manufacturers. Import substitution policies favor domestic processors over Indian supply for institutional catering channels.
Curcumin Food Color Market Competitive Environment
Capability concentration sits with vertically integrated turmeric processors; scale advantage sits with multinational ingredient distributors. The vendor base stratifies into three tiers: plantation-linked extractors commanding traceability premiums, mid-scale oleoresin specialists, and commodity traders lacking processing assets. Dominant competitive moves include backward integration into captive turmeric cultivation and technology licensing for solvent-free extraction methods.
Within the plantation-integrated tier, Synthite Industries Ltd and Arjuna Natural Pvt Ltd exemplify Indian-origin specialists leveraging proximity to Erode and Nizamabad feedstock clusters. Sabinsa Corporation occupies a position among technology-focused extractors emphasizing purity-grade positioning. These three anchors represent distinct strategic postures: captive agricultural supply, sustained R&D intensity, and processing technology leadership respectively.
| Leading Market Players |
|---|
| Synthite Industries Ltd |
| Arjuna Natural Pvt Ltd |
| Sabinsa Corporation |
| Biomax Life Sciences Limited |
| Kancor Ingredients Limited |
| Roha Dyechem Pvt. Ltd. |
| GNT International B.V. |
| D.D. Williamson & Co. Inc. |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in India's Erode extraction zone is compressing spot market premiums and forcing processors toward long-term offtake contracts with beverage manufacturers. This utilization dynamic rewards vertically integrated operators with captive turmeric supply while squeezing margin pools for traders dependent on auction-sourced feedstock.
Pricing Analysis
Indian-origin curcumin commands a 15-25% spread over Chinese processed material due to FSSAI traceability documentation and supercritical CO2 extraction premiums. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and solvent-free processing method. Cost compression in the conventional grade is intensifying as Nizamabad spot turmeric prices fluctuate with monsoon reliability. Retail chains exhibit the least price sensitivity, prioritizing farm-to-fork documentation over unit economics.
Supply Chain Analysis
Contract extraction capacity concentrates with Synthite Industries Ltd, Arjuna Natural Pvt Ltd, and Sabinsa Corporation, which collectively anchor solvent-free processing expertise. Raw material sourcing draws from Erode and Nizamabad cultivation belts in India, with secondary feedstock clusters in Zhejiang province, China. Single-source vulnerability sits with monsoon-dependent turmeric rhizome harvests that dictate annual extraction input costs. Distribution runs through Rotterdam logistics hubs for European compounders and direct manufacturer relationships for North American beverage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solvent-free extraction expertise represents a binding constraint that stratifies competitive returns, with technology licensing and skilled chemical engineering talent determining which processors capture premium pricing tiers.
For Market Incumbents: Build regulatory moats through preemptive FDA GRAS notification filings for novel delivery formats. Secure backward integration into captive turmeric cultivation around Erode to insulate margin stability from spot market volatility. Anthocyanin and carotenoid substitution threats demand accelerated nano-encapsulation R&D investment to close the light-stability performance gap. For New Entrants and Emerging Players: Establish a beachhead in the nano-encapsulated dairy application segment where EFSA classification uncertainty has frozen incumbent launch timelines. European functional drink producers represent the most penetrable buyer archetype pending Novel Food clarity. A go-to-market angle emphasizing pH-stability technical service partnerships differentiates against commodity powder traders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plantation-integrated extractors with multi-year supply agreements to retail chains. Five-to-ten-year viability favors operators with demonstrated supercritical CO2 scale and FSSAI audit compliance histories. The signal to watch is EFSA's final nano-particle guidance publication, which will unlock or foreclose premium dairy application demand.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Extraction Scale-Up | Supercritical CO2 capacity expansion preserves color stability for beverage manufacturers specifying batch consistency. |
| Captive Turmeric Cultivation | Backward integration into Erode farming clusters secures feedstock proximity and FSSAI traceability documentation. |
| Nano-Encapsulation R&D Partnership | Liposomal delivery technology licensing opens alkaline dairy applications previously closed to pH-sensitive curcumin. |
| Direct-to-Manufacturer Digital Platform | Bypassing traditional spice traders captures margin pools through streamlined procurement for retail chain private labels. |
| EU Novel Food Pre-Submission | Early EFSA engagement on enhanced bioavailability formats creates regulatory runway for premium colorant positioning. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with extraction plant managers, beverage procurement leads, FSSAI compliance officers, and retail chain category buyers; and secondary validation through customs trade records, BIS extraction residue filings, FDA GRAS notification databases, and EFSA food additive evaluation archives. Bottom-up triangulation against top-down cultivation and processing capacity estimates anchored volume and value outputs.
Forecast inputs span product type segmentation, application matrix by pH sensitivity, form factor logistics economics, and end-user procurement sophistication tiers across the projection horizon. CAGRs were derived from elasticity modeling against clean-label mandate adoption curves and turmeric rhizome price volatility bands. Industry-specific forecast inputs include monsoon pattern reliability indices and EFSA nano-particle classification trajectory assumptions.
Stress conditions across turmeric yield variance, EFSA regulatory timeline compression, and synthetic colorant substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on GRAS expansion velocity and retail chain clean-label enforcement intensity. Quarterly review of FSSAI purity audit backlogs and EFSA guidance publication timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Powdered Fats Market