
 Global Baking Powder Market | 2026-2036
Global Baking Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baking Powder Market Analysis
Monocalcium phosphate is expanding its share in double-acting formulations as bakers seek faster, more consistent rise profiles without aluminum compounds. Puratos NV leverages its global R&D network to sustain leadership in clean-label leavening systems across European industrial channels. Kerry Group plc anchors its position through backward integration into acidulant supply, while Lesaffre SA competes on fermentation-derived bicarbonate sourcing for organic-certified lines.
Baking powder is a dry chemical leavening agent comprising an alkaline component, typically sodium bicarbonate, paired with one or more acid salts and a moisture-absorbing starch buffer; it releases carbon dioxide upon hydration and heat exposure to aerate dough and batter matrices in commercial and household baking. The double-acting category dominates industrial volume because its staged gas release tolerates extended proofing and transport cycles, while organic formulations command premium shelf placement in specialty retail channels. Household end users represent the most price-sensitive segment, whereas food services and industrial bakeries prioritize batch consistency and supplier certification over unit cost.
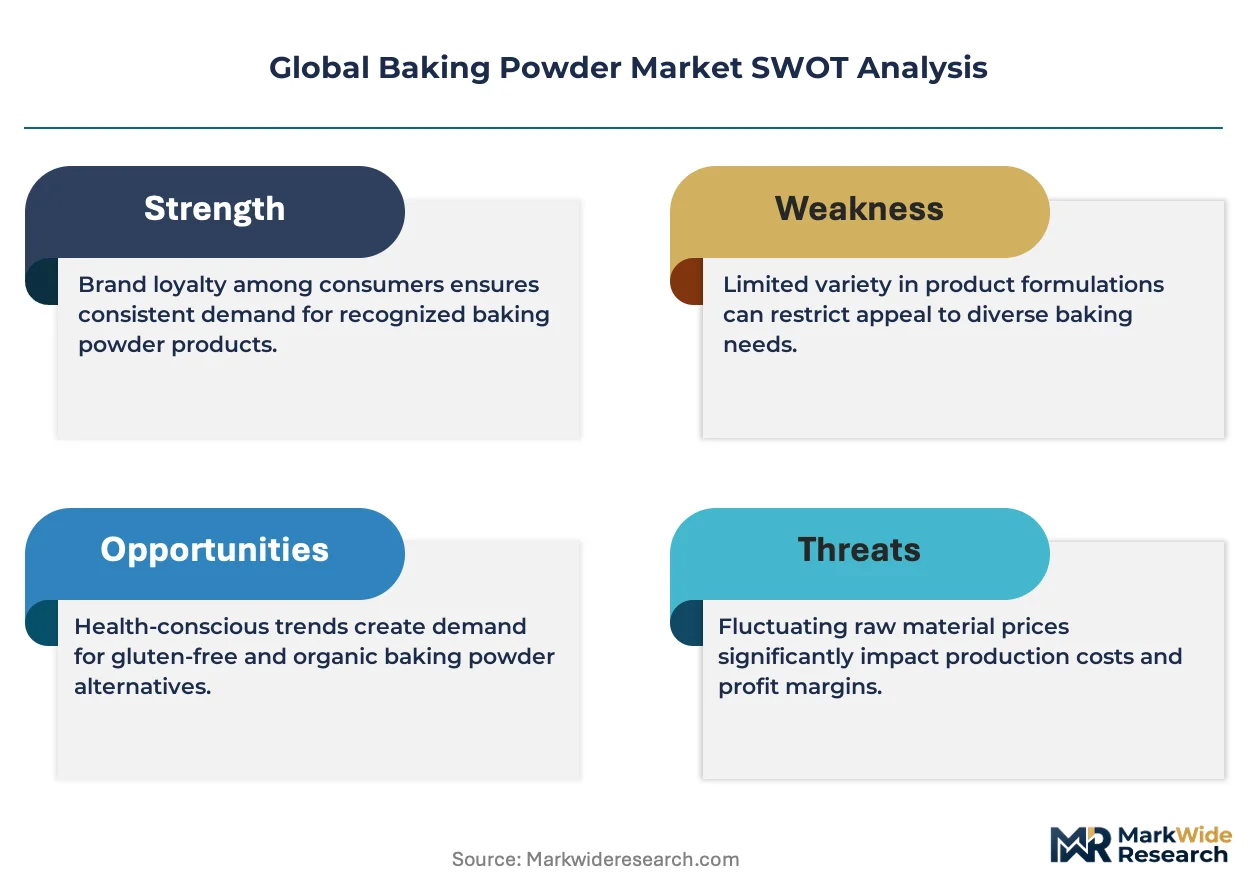
FDA food additive regulations and USDA organic certification standards govern product composition and label claims in the United States, while REACH and EU Green Deal frameworks in Europe restrict phosphate discharge and incentivize sustainable acidulant sourcing. BIS standards in India mandate labeling disclosures that shape consumer trust and import compliance for multinational suppliers. Stakeholders must monitor evolving phosphate regulations and acidulant substitution pathways to align product portfolios with jurisdiction-specific compliance timelines.
Market Dynamics
Clean-label reformulation is compressing traditional aluminum-based supply chains as industrial bakeries and retail brands requalify acidulant sources to meet phosphate-reduction mandates across multiple jurisdictions.
Growth Catalysts
- EU Green Deal phosphate restrictions:REACH compliance deadlines are forcing reformulation toward organic acid sources, creating replacement demand for monocalcium phosphate and sodium acid pyrophosphate alternatives in German and French industrial channels.
- Urban household expansion in India:Double-acting powder penetration through modern retail formats in Mumbai, Delhi, and Bangalore is accelerating as nuclear families shift from fresh yeast to convenience baking inputs.
- Aluminum-free certification:FSSAI disclosure requirements and BIS labeling standards are elevating consumer scrutiny, pulling reformulated products into premium shelf positions in domestic and import-competing segments.
Market Restraints
- Tartaric acid supply volatility:Concentrated vineyard sourcing in Argentina and South Africa exposes formulators to harvest fluctuation and currency risk, compressing margin stability for cream of tartar-dependent blends.
- Phosphate discharge limits:ECHA wastewater frameworks impose treatment cost burdens on acidulant producers in the Rhine-Ruhr manufacturing cluster, raising input costs for European-sourced baking powder.
- Fresh yeast substitution:Artisan bakery segments in Italy and Spain retain preference for live fermentation cultures, capping baking powder penetration in traditional bread categories.
Strategic Opportunities
- Organic-certified lines:USDA organic and EU organic logo eligibility creates pricing power in North American specialty retail and European health-food channels where certification premiums hold.
- Food service direct distribution:Bypassing traditional wholesale layers to supply quick-service bakery chains in the Gulf Cooperation Council states unlocks volume contracts with technical service attachments.
- Sodium-reduction convergence:Pairing potassium bicarbonate with glucono-delta-lactone addresses dual clean-label and salt-reduction positioning for hypertension-conscious consumer segments in Japan and South Korea.
Industry Challenges
- Acidulant compatibility testing:Reformulation timelines stretch 18-24 months as industrial bakeries validate new leavening systems across variable flour protein contents and hydration levels.
- Cross-border label harmonization:Divergent organic certification requirements between USDA, EU organic, and Indian NPOP standards fragment SKU rationalization for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baking Powder Market |
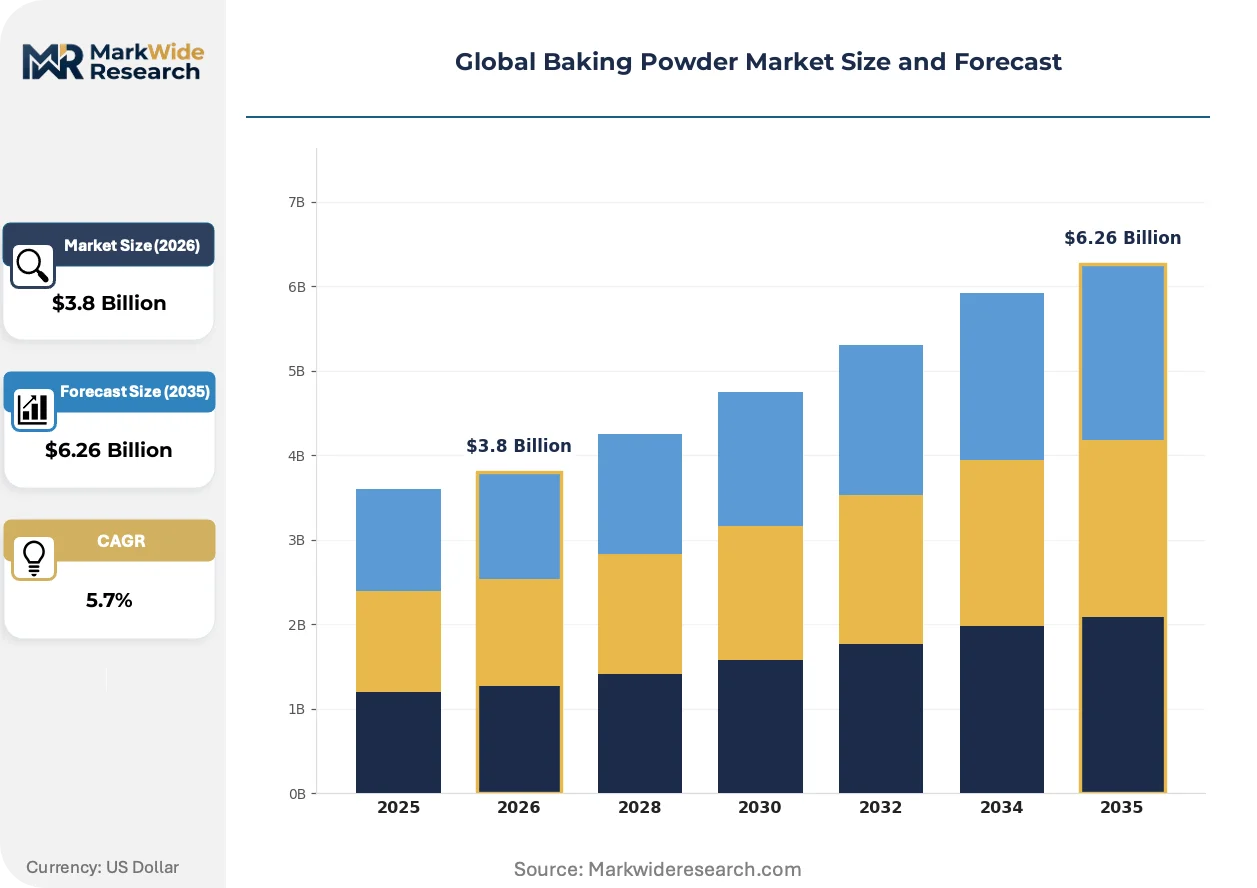
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Acting, Double-Acting, Organic, Gluten-Free End User: Households, Bakeries, Food Services, Industrial Packaging Type: Bags, Boxes, Tubs, Sachets Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Retailers |
| Companies Covered | Bakels Worldwide, AB Mauri UK Ltd., Puratos NV, ACH Food Companies, Inc., Clabber Girl Corporation, Dawn Food Products, Inc., IREKS GmbH, Kerry Group plc, Lesaffre SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baking Powder Market Emerging Trajectories
Formulation chemistry and regulatory compliance are converging to redefine competitive advantage, with acidulant sourcing and gas-release engineering becoming primary differentiation vectors.
Encapsulated acidulant technology is electrifying controlled-release performance in frozen dough applications. North American pizza chains and frozen bakery suppliers are adopting lipid-coated monocalcium phosphate to delay initial reaction until proofing stages. This architecture is compressing waste rates in extended-distribution supply chains by stabilizing pre-bake inventory.
REACH authorization requirements for phosphate compounds are tightening discharge accountability across ECHA-registered facilities. Industrial acidulant producers in Belgium and the Netherlands are retrofitting wastewater treatment to meet 2025 concentration thresholds. German industrial bakeries are qualifying reduced-phosphate formulations earlier than compliance deadlines to secure supply continuity.
Modern retail consolidation in Indian metropolitan markets is compressing distributor layers and concentrating procurement decisions at chain headquarters. Reliance Retail and BigBasket are direct-sourcing aluminum-free double-acting powders for private-label placement, bypassing traditional kirana-channel intermediaries. This channel shift is visible most acutely in Mumbai and Bangalore where modern trade penetration exceeds 35 percent.
Global Baking Powder Market Segmentation
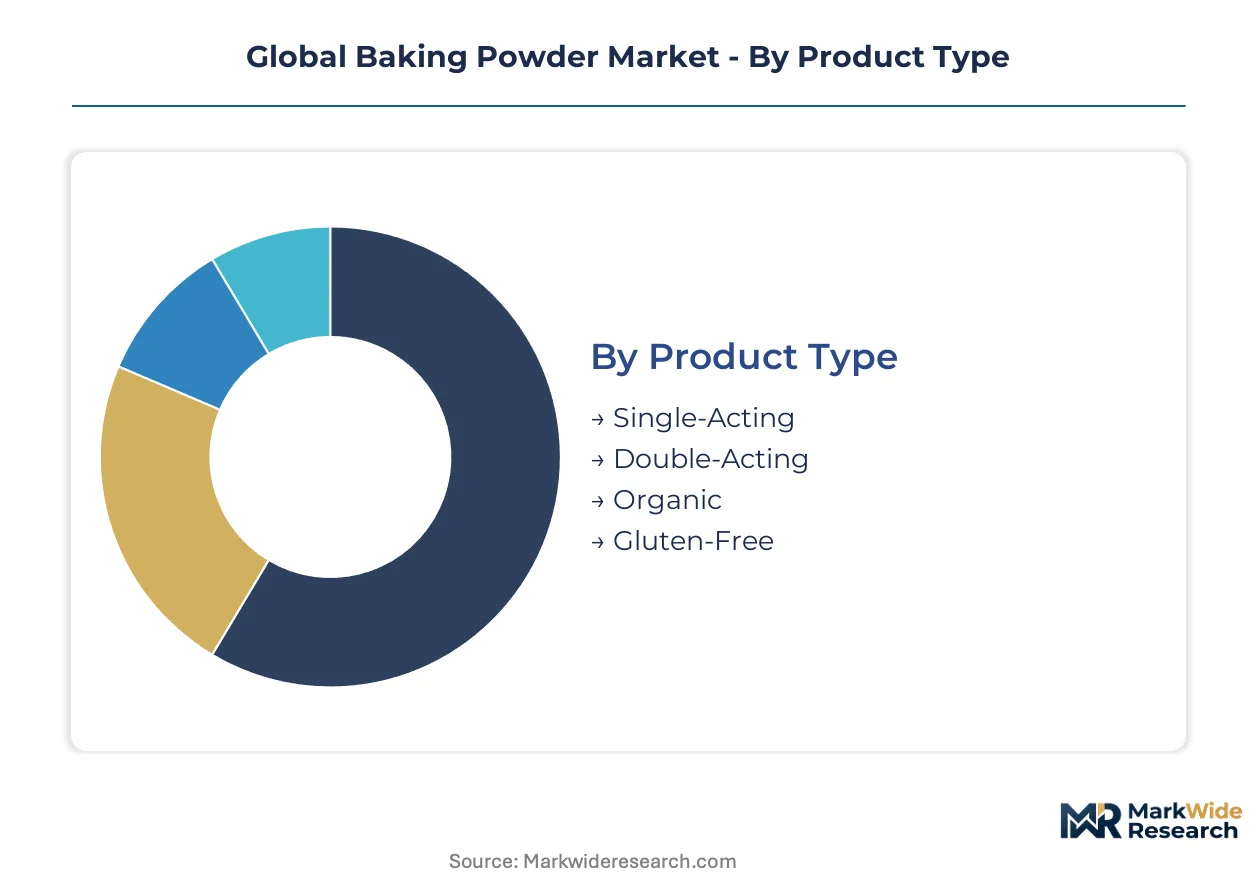
Leavening chemistry and buyer procurement sophistication fragment the baking powder landscape into distinct value tiers. Product formulation determines performance specifications, while end-use concentration shapes packaging and channel strategies across industrial and retail channels.
Product Type:
Acidulant chemistry and release kinetics separate buyers by proofing tolerance and clean-label requirements.
- Double-Acting:Staged gas release through dual acid salts (typically sodium aluminum sulfate or monocalcium phosphate paired with sodium bicarbonate) tolerates extended hold times in frozen dough supply chains. German industrial bakeries and North American pizza chains anchor procurement volume for this category due to distribution flexibility requirements.
- Organic:Fermentation-derived bicarbonate paired with cream of tartar or organic acid salts meets USDA and EU organic logo standards. Premium shelf placement in specialty retail channels across France, Germany, and California commands price multiples over conventional formulations.
- Single-Acting:Immediate carbon dioxide release upon hydration suits scratch baking with minimal delay; tartaric acid or citric acid bases dominate traditional household formulations in India and Southern Europe.
- Gluten-Free:Acidulant systems validated against ppb gluten thresholds serve celiac-sensitive segments; rice starch buffers replace wheat-derived carriers in certified production lines.
Volume sits with Double-Acting; growth tilts toward Organic.
End User:
Batch scale and technical service requirements stratify procurement behavior from household pantry replenishment to industrial tender contracts.
- Industrial:Automated dosing systems and flour-protein variability demand acidulant consistency and supplier technical support. Large-scale bakeries in Mumbai, Chicago, and São Paulo negotiate annual contracts with specification lock.
- Food Services:Quick-service bakery chains and hotel kitchens prioritize sachet convenience and inventory turnover over unit cost optimization.
- Bakeries:Artisan operations in Italy and Spain retain fresh yeast preference for bread categories, limiting baking powder penetration to pastry and quick-bread applications.
- Households:Price sensitivity concentrates purchasing around promotional cycles and private-label placement in modern retail formats.
Procurement sophistication peaks with Industrial; expansion is steepest in Food Services.
Packaging Type:
Shelf-life requirements and usage frequency determine moisture protection investment and unit economics.
- Sachets:Single-use aluminum-laminate pouches eliminate caking risk in humid climates; food service and travel retail channels in Southeast Asia and the Gulf Cooperation Council states drive uptake.
- Tubs:Screw-cap polypropylene containers with desiccant inserts serve high-frequency household bakers in the United States and United Kingdom.
- Bags:Multi-layer paper-plastic laminates balance cost and moisture barrier for industrial bulk procurement.
- Boxes:Secondary packaging for retail shelf presence; often contains inner sachets or pouches for portion control.
Industrial procurement favors Bags; premium positioning clusters around Sachets.
Distribution Channel:
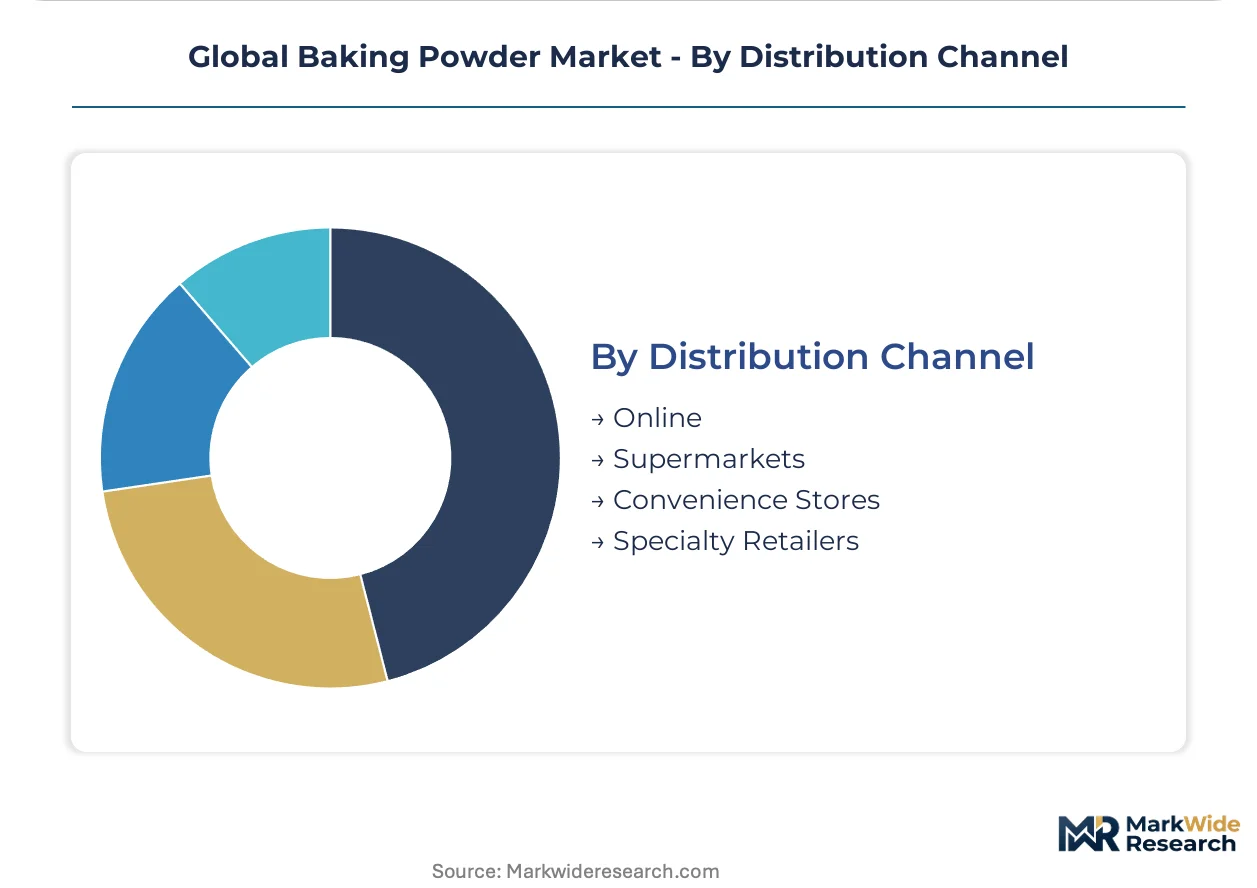
Channel selection reflects buyer urgency, certification verification needs, and private-label penetration depth.
- Supermarkets:Modern trade consolidation in India and Brazil concentrates baking powder placement in chain-controlled planograms; Reliance Retail and BigBasket direct-source aluminum-free formulations for private-label expansion.
- Specialty Retailers:Health-food and organic-certified channels in Germany, France, and California validate acidulant sourcing claims for clean-label consumers.
- Online:Subscription replenishment and bulk purchasing gain traction among household bakers in Japan and South Korea; platform algorithms favor aluminum-free and organic search terms.
- Convenience Stores:Emergency replenishment and travel-size sachets serve urban convenience demand in dense metropolitan markets.
Volume concentrates in Supermarkets; digital share is climbing fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate industrial baking ingredient manufacturing, drawing multinational suppliers through tax incentives and port-access advantages. These zones anchor procurement hubs serving both domestic Indian demand and export markets across the Middle East and Southeast Asia.
Germany
Industrial bakeries in the Rhine-Ruhr corridor anchor European volume demand for double-acting formulations with extended proofing tolerance. REACH authorization requirements for phosphate compounds are forcing acidulant producers to retrofit wastewater treatment ahead of 2025 ECHA thresholds. Munich-based ingredient distributors are pre-qualifying reduced-phosphate supply chains to secure batch consistency for automated dosing systems.
United States
Frozen pizza chains and quick-service bakery networks drive encapsulated acidulant uptake for controlled-release performance in extended-distribution supply chains. FDA food additive regulations and USDA organic certification standards govern label claims and composition requirements across interstate commerce. Chicago and Minneapolis industrial baking clusters negotiate annual supply contracts with specification locks for flour-protein variability tolerance.
India
Urban nuclear households in Mumbai, Delhi, and Bangalore are shifting from fresh yeast to convenience baking inputs through modern retail penetration exceeding 35 percent in metropolitan markets. FSSAI disclosure requirements and BIS labeling standards elevate consumer scrutiny and pull aluminum-free formulations into premium shelf positions. Reliance Retail and BigBasket direct-source double-acting powders for private-label placement, bypassing traditional kirana-channel intermediaries.
France
Artisan bakery segments retain fresh yeast preference for traditional bread categories, limiting baking powder penetration to pastry and quick-bread applications in Lyon and Bordeaux clusters. EU Green Deal phosphate restrictions are accelerating reformulation timelines toward organic acid sources in industrial channels. Paris-based specialty retailers validate acidulant sourcing claims for clean-label consumers seeking USDA and EU organic logo eligibility.
Japan
Hypertension-conscious consumer segments drive sodium-reduction convergence, pairing potassium bicarbonate with glucono-delta-lactone for dual clean-label positioning. Subscription replenishment and bulk purchasing gain traction among household bakers through platform algorithms favoring aluminum-free and organic search terms. Osaka and Nagoya industrial zones supply technical service attachments to quick-service bakery chains demanding batch consistency certification.
Global Baking Powder Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement at industrial bakeries contrasting fragmented household retail channels. Three strategic archetypes dominate: multinational ingredient conglomerates with backward integration into acidulant supply, regional specialists competing on fermentation-derived sourcing for organic-certified lines, and private-label contract manufacturers serving modern retail consolidation. M&A activity concentrates on captive acidulant production assets, while portfolio diversification into encapsulated and sodium-reduced formulations accelerates reformulation partnerships with industrial end users.
Among European-based ingredient conglomerates, Puratos NV and Kerry Group plc exemplify archetypes spanning global R&D networks and upstream supply control. Lesaffre SA occupies a position within fermentation-derived bicarbonate sourcing for organic-certified production lines. These three entities represent distinct competitive vectors: clean-label leavening system leadership, backward integration into acidulant manufacturing, and organic supply chain certification respectively.
| Leading Market Players |
|---|
| Bakels Worldwide |
| AB Mauri UK Ltd. |
| Puratos NV |
| ACH Food Companies, Inc. |
| Clabber Girl Corporation |
| Dawn Food Products, Inc. |
| IREKS GmbH |
| Kerry Group plc |
| Lesaffre SA |
| Others |
Supply Flow & Price Mechanics
Acidulant raw material costs flow from vineyard and phosphate rock extraction through formulation tiers to downstream buyers, with cream of tartar volatility and REACH compliance expenses stratifying price positions across organic-certified, aluminum-free, and commodity double-acting segments.
Pricing Analysis
Short lead-time premiums compress margins for spot tartaric acid purchases from Argentina and South Africa, while annual contract structures lock acidulant supply for German industrial bakeries and North American frozen dough chains. Pricing stratifies across premium organic-certified, standard aluminum-free, and economy phosphate-containing tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in organic lines intensifies because fermentation-derived bicarbonate sourcing limits supplier pools. Household retail channels exhibit highest price sensitivity, whereas food service chains prioritize batch consistency over unit cost optimization.
Supply Chain Analysis
Return flows of expired or moisture-compromised baking powder are negligible given low unit value and food safety protocols, though industrial bakeries in Chicago and Mumbai negotiate take-back arrangements for bulk bag packaging to satisfy sustainability audits. Acidulant supply concentrates in Belgium, the Netherlands, and Germany for phosphate compounds, while cream of tartar draws from Argentina and South Africa. Raw material dependencies center on phosphate rock, tartaric acid from wine production byproducts, and fermentation-derived bicarbonate. Single-source vulnerability in tartaric acid exposes formulators to harvest fluctuation and currency risk. Distribution runs through ingredient distributors to industrial bakeries, modern retail chains for household segments, and direct supply agreements for quick-service bakery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive acidulant production and fermentation-derived bicarbonate sourcing separate margin leaders from price-takers dependent on spot phosphate and tartaric acid markets.
For Market Incumbents: Deploy backward integration into acidulant manufacturing to secure supply continuity ahead of REACH phosphate discharge deadlines. Lock annual specification contracts with German and North American industrial bakeries before reformulation validation cycles extend procurement timelines. Capture channel control through direct distribution to quick-service chains in Gulf Cooperation Council states, bypassing wholesale margin erosion from modern retail consolidation.
For New Entrants and Emerging Players: E-commerce subscription models unlock penetration in Japan and South Korea where platform algorithms favor aluminum-free and organic search terms. Target sodium-reduction convergence segments pairing potassium bicarbonate with glucono-delta-lactone for hypertension-conscious households. Private-label supply contracts with Reliance Retail and BigBasket in India offer fastest volume scale given their direct-sourcing bypass of traditional kirana intermediaries.
For Investors and Strategic Acquirers: Encapsulated acidulant technology licensing agreements with North American frozen pizza chains are the leading indicator that controlled-release intellectual property commands acquisition premiums. Five-to-ten year viability favors suppliers with in-house acidulant production and organic certification pathways rather than toll manufacturers exposed to input cost volatility. Monitor ECHA wastewater retrofit completion rates among Belgian and Dutch acidulant producers as inflection signal for supply-constrained pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acidulant Manufacturing | Kerry Group plc's captive sodium acid pyrophosphate production insulates margin from ECHA discharge cost pass-through. |
| Organic Certification Program | USDA and EU organic logo eligibility unlocks price multiples in California and German specialty retail channels. |
| Encapsulated Technology Licensing | Lipid-coated monocalcium phosphate patents secure technical service attachments with frozen dough supply chains. |
| Direct Distribution Expansion | Bypassing wholesale layers to supply GCC quick-service chains captures volume contracts with inventory management bundling. |
| Sodium-Reduced Formulation Development | Potassium bicarbonate paired with glucono-delta-lactone addresses dual clean-label and salt-reduction positioning in East Asian markets. |
Methodological Framework
Trade databases, BIS and FSSAI regulatory filings, and customs import records formed the secondary backbone, cross-referenced against primary interviews with acidulant plant managers, industrial bakery procurement leads, modern retail category buyers, and fermentation technology R&D directors. Bottom-up volume estimates from acidulant production capacity and top-down demand validation from flour consumption statistics were triangulated to reconcile segment splits.
Historical trendline analysis of phosphate compound pricing and tartaric acid harvest cycles informed elasticity assumptions across the projection horizon. The modeling framework segmented by acidulant chemistry, end-use procurement sophistication, packaging moisture protection tier, and distribution channel control type. CAGRs were derived from regression against flour processing volume growth and clean-label penetration indices in metropolitan Indian and East Asian markets.
The model holds under stable REACH enforcement timelines and no severe tartaric acid harvest disruption; deviation in ECHA threshold acceleration or Argentine vineyard climate shocks would shift acidulant cost curves and reformulation adoption rates. Practitioners should monitor ECHA wastewater retrofit completion announcements and Reliance Retail private-label expansion pace for early signals of supply constraint and channel consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
North America Food Additives Market