
 UK Mortgage / Loan Broker Market | 2026-2036
UK Mortgage / Loan Broker Market Size, Share, and Industry Trends Forecast 2026-2036
UK Mortgage / Loan Broker Market Outlook
Unbundling of mortgage advice from estate agency and conveyancing services is restructuring how UK consumers source financing. Habito leverages proprietary algorithms to automate product matching across lenders. John Charcol anchors its position through specialist buy-to-let and complex income expertise. Mortgage Advice Bureau sustains national scale through its network of appointed representative firms.
A mortgage or loan broker intermediates between borrowers and lenders, assessing affordability, sourcing products across multiple providers, and managing application submission to completion. The role requires FCA authorization, adherence to Mortgage Conduct of Business rules, and maintenance of professional indemnity cover. Independent brokers dominate transaction volume by offering whole-of-market comparison, while online brokers represent the fastest-growing channel as consumers shift from branch-based origination. First-time buyer segments concentrate margin pools where brokers command higher arrangement fees due to complexity and hand-holding requirements.
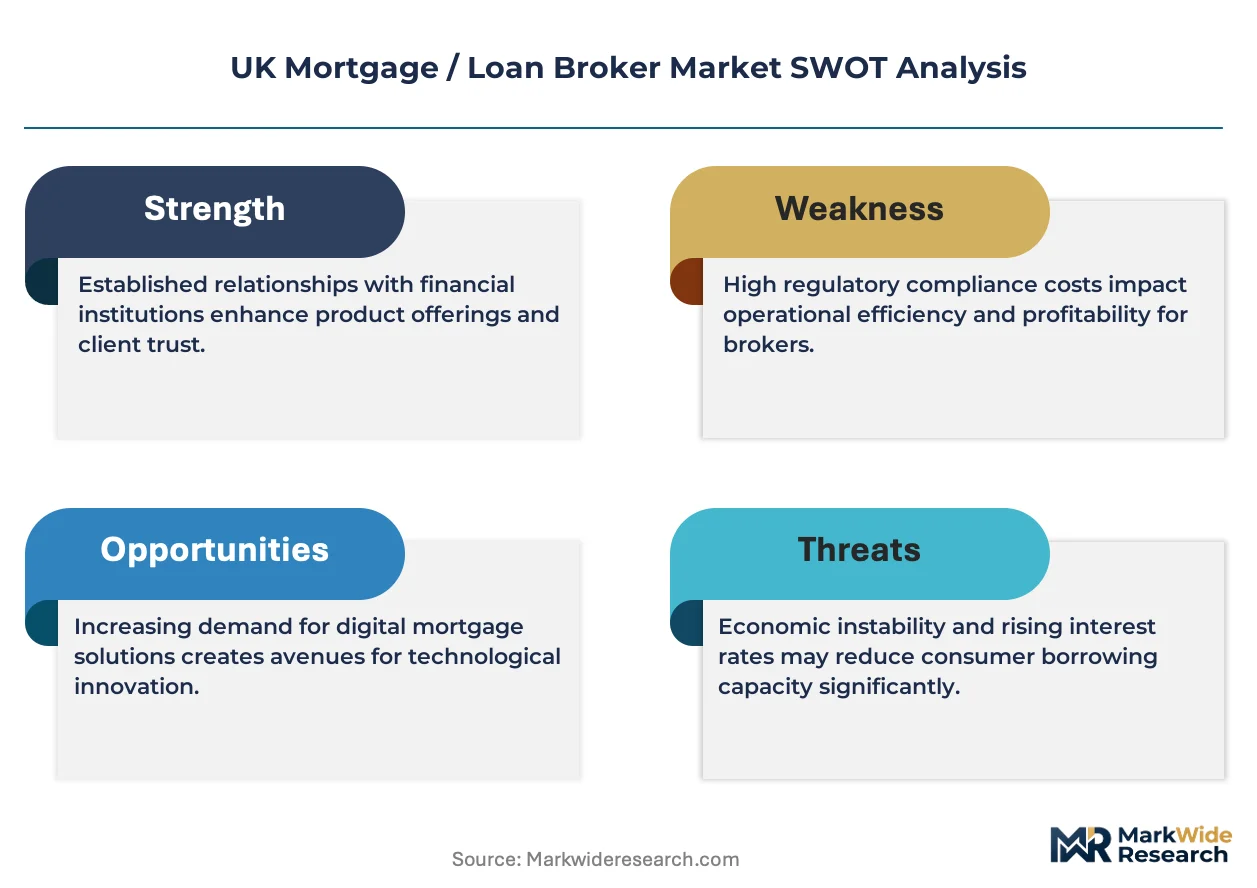
The Financial Conduct Authority enforces Consumer Duty obligations requiring brokers to deliver fair value and avoid foreseeable harm. The Prudential Regulation Authority shapes lender capital requirements, indirectly constraining product availability that brokers can source. Stakeholders must monitor whether the FCA extends duty-of-care rules to execution-only channels, as this would redefine competitive boundaries between advised and non-advised service models.
Market Dynamics
The Financial Conduct Authority's Consumer Duty rules are compressing fee structures and forcing brokers to demonstrate demonstrable value beyond product placement. This regulatory pressure is accelerating platform consolidation and technology investment across the intermediary sector.
Growth Catalysts
- Digital onboarding infrastructure:Cloud-based application processing is reducing time-to-offer from weeks to days. First-time buyer segments are migrating to mobile-first broker interfaces.
- FCA Consumer Duty compliance:The 2023 fair value framework is professionalizing advice standards and driving out execution-only operators. This elevates the perceived value of qualified intermediaries.
- Complex income specialization:Gig economy employment patterns are expanding demand for brokers with expertise in contractor, self-employed, and portfolio income verification.
Market Restraints
- Lender panel concentration:The top ten mortgage lenders control over eighty percent of broker-sourced origination. This supplier power compresses procuration fee negotiation leverage.
- Professional indemnity cost inflation:Regulatory claims activity is driving cover premiums upward. Smaller appointed representative firms face solvency pressure from insurance obligations.
- Direct-to-consumer platform substitution:Lender proprietary comparison tools and execution-only channels are capturing rate-sensitive remortgage segments.
Strategic Opportunities
- Buy-to-let portfolio restructuring:Section 24 tax changes and EPC targets are creating advisory demand among landlord investors seeking refinancing strategies.
- Later-life lending expansion:Equity release and retirement interest-only products represent underpenetrated margin pools. Demographic aging is expanding the addressable borrower base.
- Open Banking integration:Real-time affordability verification is streamlining lender-broker data exchange. This technology convergence reduces documentation friction.
Industry Challenges
- CeMAP qualification pipeline:The sector faces acute adviser recruitment constraints. Training throughput has not kept pace with adviser retirement and firm expansion.
- Legacy CRM integration:Established broker networks operate on fragmented technology stacks. Migrating to unified platforms demands capital deployment and operational disruption.
- Compliance documentation burden:Suitability letter requirements and audit trails are extending case handling time. This productivity drag affects per-adviser capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Mortgage / Loan Broker Market |
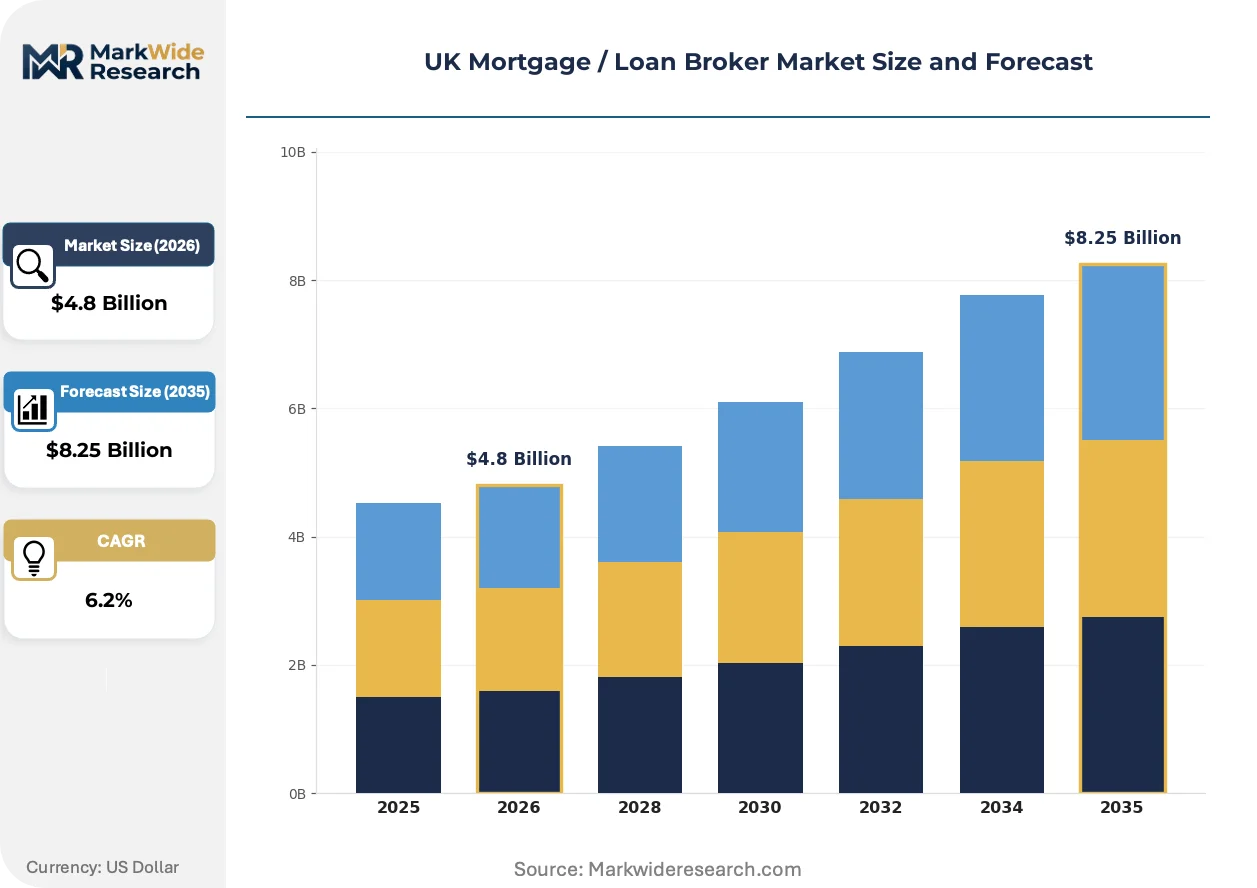
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Broker Type: Independent Brokers, National Brokers, Online Brokers, Bank-affiliated Brokers Loan Type: Fixed-rate Mortgages, Variable-rate Mortgages, Buy-to-let Loans, Home Equity Loans Client Profile: First-time Buyers, Home Movers, Remortgagers, Investment Buyers Service Model: Fee-based, Commission-based, Hybrid, Advice-free |
| Companies Covered | London & Country Mortgages Ltd, SPF Private Clients Ltd, Knight Frank Finance LLP, Mortgage Advice Bureau, John Charcol, Alexander Hall, Habito, Mojo Mortgages, L&C Mortgages, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Mortgage / Loan Broker Market Strategic Shifts
Algorithmic product matching and API-enabled lender connectivity are displacing manual sourcing workflows. The sector is bifurcating between technology-scaled platforms and high-touch specialist advice.
Artificial intelligence-driven affordability engines are expanding into complex income assessment and lender criteria matching. Brokers serving self-employed and contractor segments are adopting these tools fastest. This capability compression is narrowing the gap between generalist and specialist advice quality.
The FCA's Consumer Duty implementation is mandating enhanced disclosure of total cost of credit and ongoing service value. Broker networks are restructuring remuneration models to separate advice fees from lender commissions. Smaller appointed representative firms are most exposed to compliance infrastructure costs.
First-time buyers are exhibiting channel-switching behavior, initiating research through comparison sites before converting through advised brokerage. London and South East concentrations sustain hybrid service demand. This pattern is elevating lead acquisition costs for traditional introducer relationships.
UK Mortgage / Loan Broker Market Segmentation
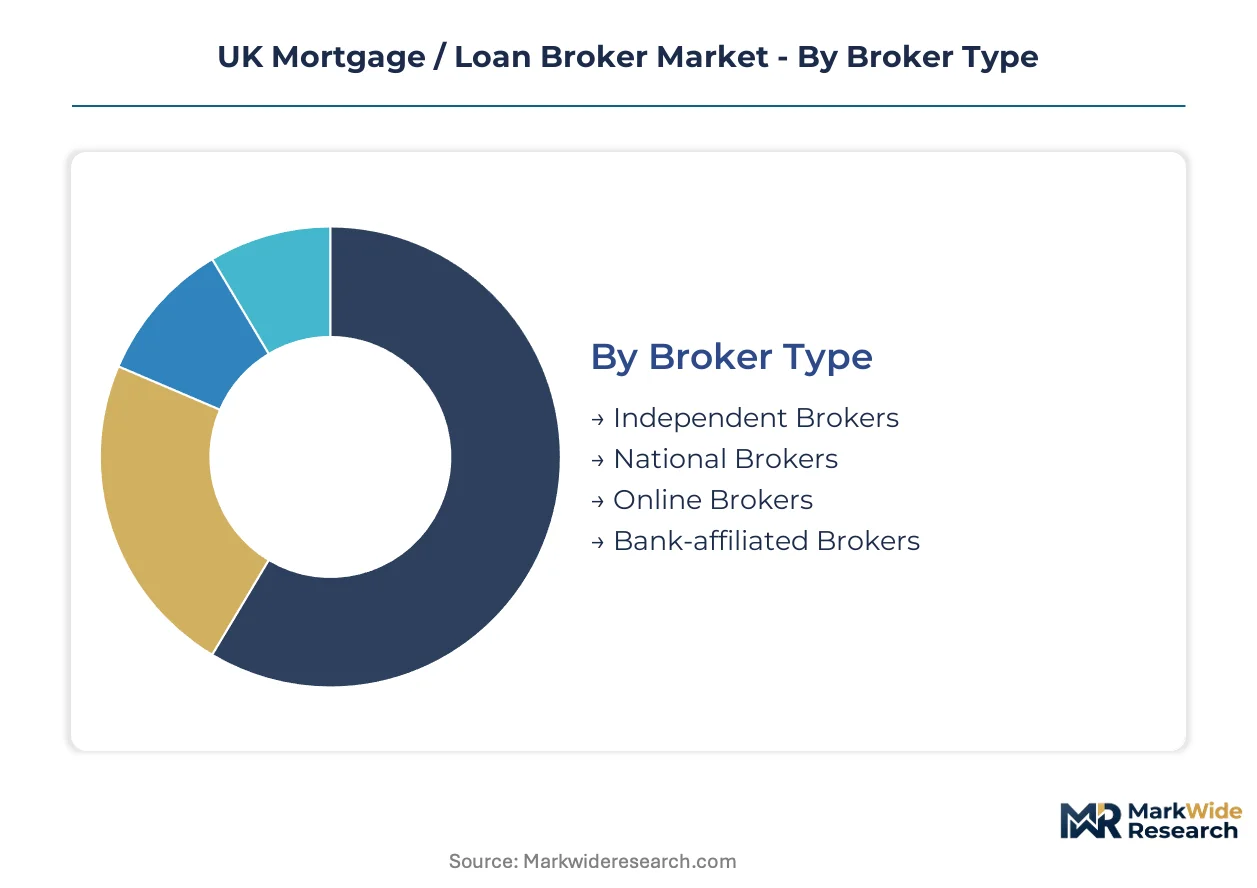
Segmentation in the UK mortgage broker market reveals how regulatory pressure and digital disruption are reshaping competitive boundaries. Each axis exposes different margin pools, compliance burdens, and technology investment requirements. Understanding these divisions clarifies where scale economies concentrate versus where specialist expertise commands premium positioning.
Broker Type:
Technology infrastructure and regulatory capital requirements differentiate competitive positioning across the intermediary landscape.
- Independent Brokers:Whole-of-market access defines this segment, with advisers sourcing products across 90-plus lender panels. Demand concentrates in complex income cases across Greater London and the South East where bespoke underwriting navigation justifies arrangement fees. FCA Consumer Duty compliance costs are forcing consolidation among smaller operators.
- Online Brokers:Proprietary algorithms automate product matching and affordability assessment. First-time buyers in metropolitan areas are migrating to mobile-first interfaces that compress time-to-offer. This channel is expanding most quickly as branch-based origination declines.
- National Brokers:Appointed representative networks achieve geographic coverage through franchise structures. Scale advantages sit with compliance infrastructure and lender relationship management.
- Bank-affiliated Brokers:Tied distribution channels restrict product sourcing to parent group lenders. Captive flow advantages persist in remortgage segments where existing customer data reduces acquisition costs.
Mature deployment sits with Independent Brokers. Newer deployment is concentrated in Online Brokers.
Loan Type:
Interest rate risk allocation and regulatory treatment create distinct advisory complexity tiers.
- Buy-to-let Loans:Portfolio landlord restructuring around Section 24 tax changes and EPC targets generates specialist advisory demand. London and Birmingham property investors dominate transaction flow, with brokers commanding higher fees for limited company structures and stress-test navigation. Complexity is accelerating technology adoption for portfolio analysis tools.
- Fixed-rate Mortgages:Rate certainty products dominate first-time buyer origination through predictable monthly payment structures. Demand clusters in regions with stretched affordability ratios where rate shock protection outweighs flexibility premiums.
- Variable-rate Mortgages:Tracker and discount products appeal to borrowers with repayment flexibility and risk tolerance. Remortgage segments show concentration as base rate uncertainty persists.
- Home Equity Loans:Later-life lending products including retirement interest-only and lifetime mortgages address underpenetrated demographic segments. Advice requirements are stringent given equity release safeguards.
Volume concentration remains with Fixed-rate Mortgages. Margin expansion is steepest in Buy-to-let Loans.
Client Profile:
Customer lifecycle position determines hand-holding intensity and fee capture potential.
- First-time Buyers:Maximum advisory touchpoints define this segment, with brokers guiding deposit schemes, affordability verification, and solicitor coordination. London and South East concentrations sustain hybrid service demand where digital research converts to advised completion. FCA suitability requirements extend case handling time.
- Remortgagers:Existing equity and payment history reduce documentation friction. Rate-sensitive behavior is driving execution-only capture, compressing broker-sourced volume in straightforward cases.
- Home Movers:Chain-dependent transactions require coordination across sale and purchase timelines. Complexity elevates broker retention of existing clients.
- Investment Buyers:Portfolio expansion and restructuring activity concentrates among specialist intermediaries with landlord tax expertise.
Fee per case peaks with First-time Buyers. Volume efficiency concentrates in Remortgagers.
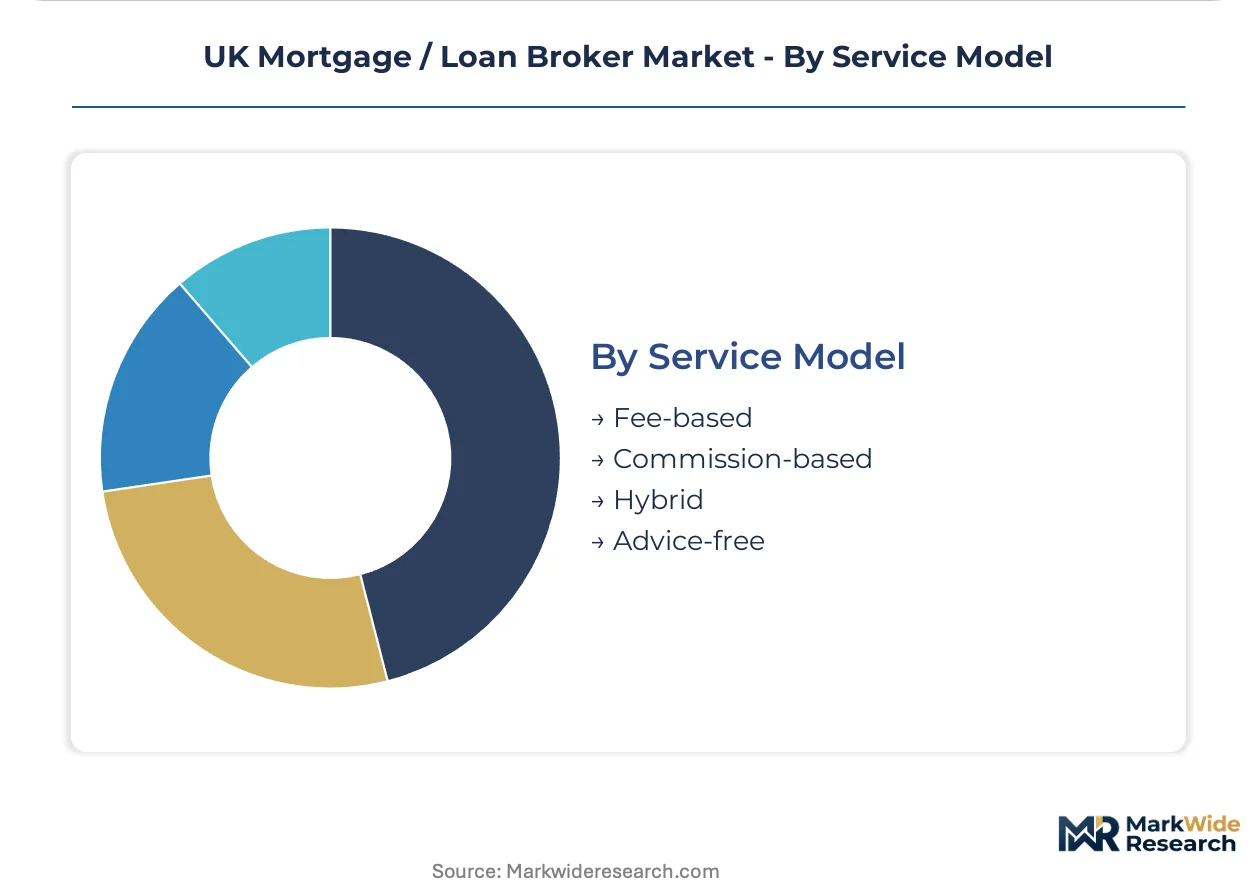
Service Model:
Remuneration structure alignment with fair value disclosure is restructuring competitive boundaries.
- Fee-based:Transparent client charging separates advice value from lender commissions. FCA Consumer Duty implementation is elevating this model's perceived integrity among first-time buyers.
- Commission-based:Procuration fee dependency creates lender panel concentration risk. Top ten mortgage lenders control over eighty percent of broker-sourced origination, compressing negotiation leverage.
- Hybrid:Blended structures balance upfront client fees with reduced commission retention. Emerging adoption sits with networks restructuring remuneration disclosure.
- Advice-free:Execution-only channels face regulatory scrutiny under fair value frameworks. FCA extension of duty-of-care rules would redefine competitive boundaries.
Regulatory pressure is accelerating migration from Commission-based toward Hybrid structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broker service consumption concentrates in London and the South East while advisory capacity distributes more broadly across England, Scotland, Wales and Northern Ireland. Housing transaction velocity and property price tiers determine regional revenue intensity rather than adviser population density.
London and South East
First-time buyer complexity and buy-to-let portfolio restructuring sustain the highest arrangement fees nationally. The Financial Conduct Authority's Consumer Duty rules apply uniformly here, elevating compliance infrastructure requirements for firms operating in high-value postcodes. Central London clusters around Mayfair and Canary Wharf host specialist intermediaries handling complex income verification for international borrowers.
Midlands
Remortgage efficiency and home mover chain coordination dominate advisory workflows in Birmingham and surrounding urban centers. The region's lender panel access remains comprehensive despite lower average property values than southern markets. West Midlands conurbation broker networks emphasize digital-first client acquisition to offset thinner margins per case.
North England
Affordability-stretched first-time buyers drive demand for deposit scheme navigation and shared ownership expertise. Manchester and Leeds sustain the densest adviser concentrations outside London, with satellite offices extending into Yorkshire and Merseyside. Northern Powerhouse housing initiatives have modestly expanded transaction volumes in core metropolitan zones.
Scotland
Distinct land tenure systems and Scottish Government homeownership programs require specialized advisory knowledge. Edinburgh and Glasgow broker practices maintain separate qualification pathways through the Scottish Financial Services Framework. Property transaction timelines differ from English norms, affecting case handling capacity metrics.
Wales and Northern Ireland
Smaller market scale constrains standalone broker viability, favoring appointed representative network membership over independent authorization. Cardiff and Belfast host the primary advisory clusters, with rural coverage dependent on remote service delivery models. Devolved housing policy creates regulatory overlay complexity for cross-border operators.
UK Mortgage / Loan Broker Market Competitive Environment
The competitive structure tilts toward technology-scaled platforms and specialist advice boutiques. Independent broker networks and digital-first intermediaries divide transaction volume, with consolidation pressure mounting on mid-sized regional operators. Three archetypes dominate: algorithm-driven product matchers, complex income specialists, and national appointed representative networks. M&A activity concentrates on technology acquisition and adviser team recruitment rather than geographic expansion.
Among established advisory firms, John Charcol occupies a position exemplifying specialist buy-to-let and complex income expertise. Mortgage Advice Bureau sits within the scale-driven network tier, its appointed representative model achieving national coverage through franchise structures. Habito represents the technology-native archetype, its proprietary algorithms automating product matching across lender panels. These three anchors illustrate how remuneration transparency and digital infrastructure now separate competitive tiers more decisively than traditional lender relationships.
| Leading Market Players |
|---|
| London & Country Mortgages Ltd |
| SPF Private Clients Ltd |
| Knight Frank Finance LLP |
| Mortgage Advice Bureau |
| John Charcol |
| Alexander Hall |
| Habito |
| Mojo Mortgages |
| L&C Mortgages |
| Others |
Value Chain & Pricing Dynamics
First-time buyer concentration in London and the South East sustains premium arrangement fees, while procuration fee compression from lender panel concentration reshapes revenue models across the intermediary sector.
Pricing Analysis
Margin tightening in commission-based tiers reflects FCA Consumer Duty compliance costs and procuration fee negotiation pressure from the top ten mortgage lenders. Three-tier pricing structure across premium, standard, and economy levels separates complex income specialists from generalist advisers and execution-only channels. Cost-down pressure on smaller appointed representative firms accelerates because professional indemnity premium inflation erodes per-case economics. Rate-sensitive remortgagers exhibit highest price sensitivity, while first-time buyers accept higher fees for hand-holding intensity.
Supply Chain Analysis
Domestic-content mandates from the Financial Conduct Authority's authorization requirements reshape sourcing toward UK-qualified CeMAP advisers and FCA-regulated compliance infrastructure. Technology development concentrates in England, with proprietary algorithm providers and cloud-based CRM platforms anchoring digital broker operations. Raw material dependencies span adviser qualification pipelines, professional indemnity cover, and lender API connectivity. Single-source vulnerability sits with concentrated lender panel access, as the top ten mortgage lenders control over eighty percent of broker-sourced origination. Distribution runs through appointed representative networks, direct-to-consumer platforms, and hybrid digital-advised channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK mortgage broker market functions as a vertical-integration race, with technology platforms capturing upstream algorithm development and downstream client acquisition simultaneously.
For Market Incumbents: Acquire proprietary affordability engines and CeMAP-qualified adviser teams to defend against digital-native entrants. Consolidate smaller appointed representative firms facing solvency pressure from professional indemnity cost inflation. Backward integration into Open Banking data partnerships reduces documentation friction and accelerates time-to-offer. For New Entrants and Emerging Players: Begin with later-life lending segments in Wales and Northern Ireland, where standalone broker viability constraints create white-space for remote service delivery models. Target equity release and retirement interest-only products, as demographic aging expands the addressable borrower base. Launch through hybrid fee-based remuneration structures that align with FCA Consumer Duty transparency expectations. For Investors and Strategic Acquirers: The window for entry favors technology-scaled platforms with algorithmic product matching capabilities over traditional branch-based networks. Long-term viability hinges on compliance infrastructure that absorbs regulatory documentation burdens without per-adviser productivity drag. Watch FCA extension of duty-of-care rules to execution-only channels as the inflection signal for advised model revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Acquisition | Algorithmic product matching capabilities compress sourcing workflows and reduce adviser training overhead. |
| CeMAP Qualification Pipeline Investment | Adviser recruitment constraints create scarcity value for firms with captive training capacity. |
| Open Banking Integration Partnership | Real-time affordability verification streamlines lender-broker data exchange and reduces documentation friction. |
| Later-Life Lending Product Expansion | Equity release and retirement interest-only products address underpenetrated demographic segments with stringent advice requirements. |
| Compliance Infrastructure Centralization | FCA Consumer Duty documentation burdens favor networks with shared suitability letter and audit trail systems. |
Study Parameters
Multi-period observation of mortgage origination volumes, procuration fee structures, and adviser headcount trends anchored the trend analysis, supplemented by interviews with network compliance officers, appointed representative principals, lender distribution heads, and FCA policy specialists. Secondary validation drew from FCA authorization databases, Prudential Regulation Authority capital requirement disclosures, and lender panel relationship filings. Bottom-up transaction flow analysis triangulated against top-down market sizing from housing transaction data.
Input-output matrices modeled volume and value projections across broker type, loan type, client profile, and service model dimensions throughout the forecast period. CAGRs derived from segmented growth rate assumptions calibrated to housing market transaction velocity and regulatory implementation timelines. Forecast inputs incorporated CeMAP qualification throughput, Open Banking adoption curves, and FCA Consumer Duty compliance cost estimates.
Base rate volatility, housing transaction cycle turns, and FCA regulatory extension beyond advised channels are the dominant revision risks to projection assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Debt Financing Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
China Home Loan Market