
 North America Food Preservatives Market | 2026-2036
North America Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Preservatives Market Analytics
Subscription-based technical service packages for preservative blend optimization is rebalancing how suppliers capture recurring value beyond commodity chemical sales. Cargill, Incorporated leverages its integrated agricultural supply chain to anchor clean-label preservative development from crop to formulation. Kerry Group, Plc. differentiates through taste-preservation synergy platforms that combine antimicrobial function with flavor masking. BASF SE competes on synthetic preservative manufacturing scale and regulatory dossier depth across North American food additive registrations.
Food preservatives comprise chemical substances or natural extracts added to food matrices to inhibit microbial spoilage, enzymatic degradation, or oxidative rancidity, typically dosed at 0.01% to 0.3% by weight depending on matrix water activity and pH. Their primary commercial purpose is extending shelf stability while maintaining sensory and nutritional integrity throughout distribution chains. Sorbates dominate volume in high-moisture applications where yeast and mold control commands premium positioning, while phosphate blends in meat products represent a mature margin pool constrained by sodium reduction mandates. Benzoate demand in beverage acidification systems shows structural growth as carbonated and functional drink portfolios expand across Mexico and the United States.
The FDA governs direct food additive petitions and GRAS self-determinations that shape which preservative chemistries gain rapid market access, while the USDA FSIS imposes residue limits and labeling requirements on preserved meat and poultry products that directly constrain formulation choices. Health Canada's Food Directorate maintains parallel but non-identical approval lists that create regulatory friction for cross-border product standardization. Stakeholders must monitor evolving state-level clean-label legislation in California and New York that threatens to fragment permissible preservative inventories below federal baselines.
Market Dynamics
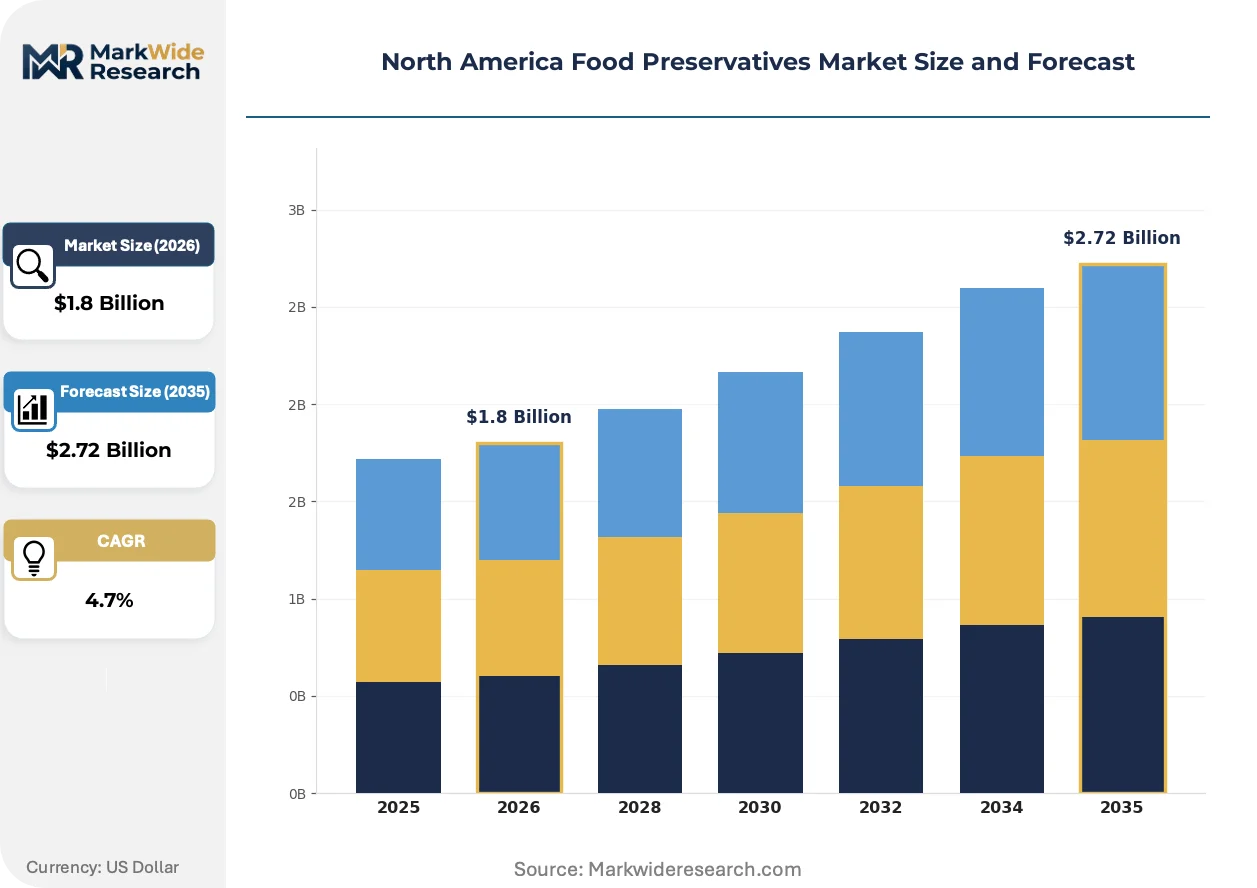
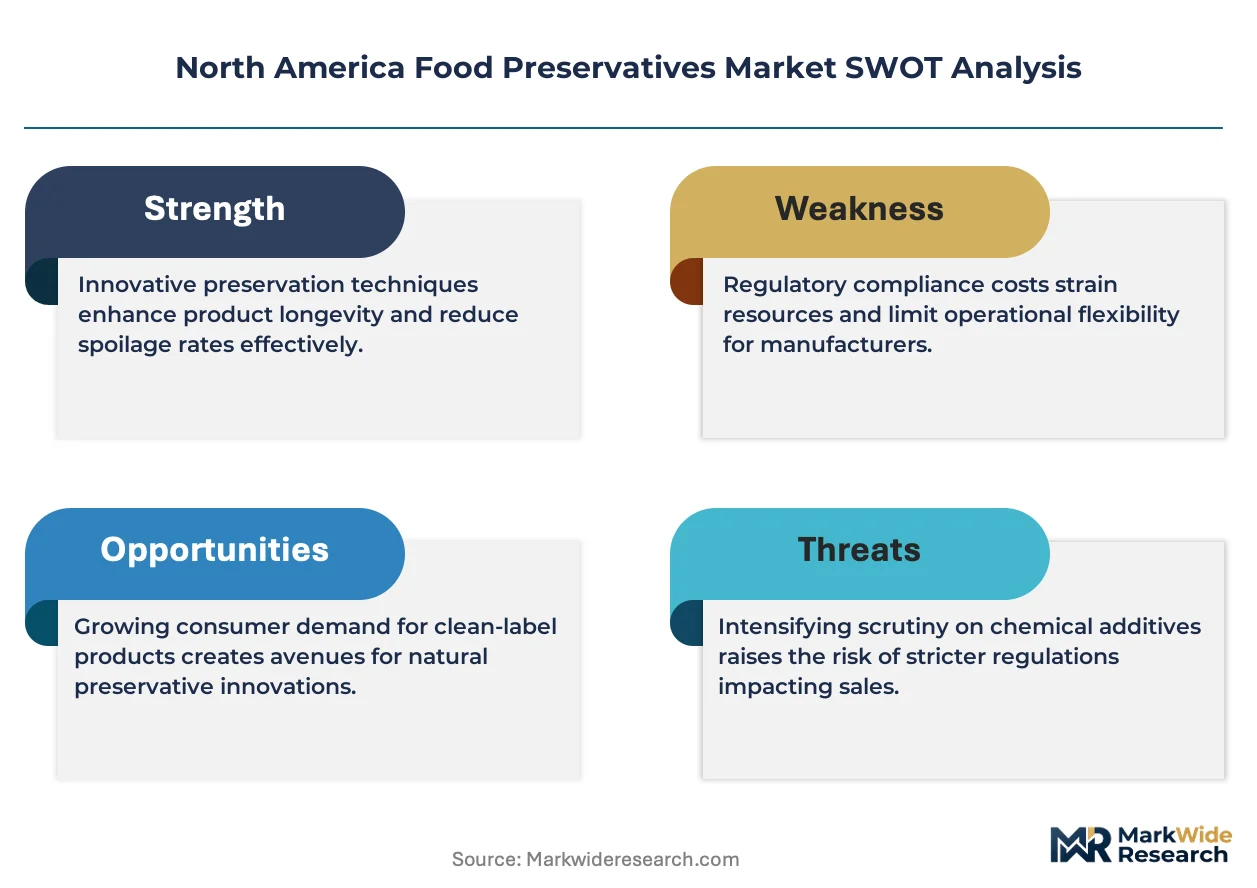
Clean-label mandates from California and New York state legislatures are fragmenting permissible preservative inventories below federal baselines, forcing reformulation cycles across the packaged food corridor. This regulatory layering is compressing approval timelines and rebalancing supplier relationships toward technical service capabilities.
Growth Catalysts
- GRAS Self-Determination Pathway:The FDA's streamlined notification process accelerates natural preservative market entry, cutting time-to-shelf for fermented vinegars and cultured dextrose derivatives.
- High-Moisture Bakery Expansion:Extended shelf-life demands in tortillas and flatbreads drive sorbate and propionate blend volumes across Texas and California production clusters.
- Phosphate Replacement Chemistry:Sodium reduction mandates in USDA-regulated meat applications pull clean-label alternatives into brine and marinade systems.
Market Restraints
- Corn-Derived Input Volatility:Sorbic acid and potassium sorbate pricing ties to Midwest grain futures, exposing margin compression during drought cycles.
- Canadian Regulatory Friction:Health Canada's Food Directorate maintains non-identical approved additive lists, forcing dual dossier submissions for cross-border product lines.
- Natural Extract Yield Limits:Rosemary and green tea extract antioxidant production faces agricultural capacity ceilings that constrain volume scaling.
Strategic Opportunities
- Mexico Beverage Acidification:Carbonated and functional drink portfolio expansion across Mexican bottling corridors drives benzoate and citrate demand for pH stabilization.
- Precision Fermentation Platforms:Biosynthesized antimicrobial peptides from engineered yeast strains converge with clean-label positioning to unlock premium meat preservation contracts.
- Subscription Technical Services:Preservative blend optimization contracts rebalance supplier revenue toward recurring value capture beyond commodity chemical sales.
Industry Challenges
- Formulation Scientist Scarcity:Food matrix compatibility expertise combining antimicrobial efficacy with sensory neutrality commands premium compensation in Chicago and Minneapolis talent markets.
- Dual-Label Packaging Complexity:Divergent state-level clean-label legislation forces SKU proliferation and inventory segmentation for California versus Midwest distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Preservatives Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Nitrates, Benzoates, Phosphates Application: Dairy Products, Bakery Products, Beverages, Meat Products End User: Food Manufacturers, Retailers, Foodservice Providers, Home Consumers Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Kerry Group, Plc., BASF SE, Kemin Industries, Inc., Koninklijke DSM N.V., Tate & Lyle Plc., Corbion N.V., Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Preservatives Market Evolving Landscape
Preservation technology is bifurcating toward bio-based active systems and precision-delivery mechanisms that decouple antimicrobial function from traditional chemical loadings. This shift is compressing the viable shelf for legacy synthetic portfolios while opening formulation partnerships between ingredient suppliers and equipment manufacturers.
Encapsulated essential oil systems are modularizing preservation architecture across refrigerated pasta and sauce applications. Mid-sized co-manufacturers in Wisconsin and Ohio adopt these platforms to extend clean-label claims without sacrificing mold-free shelf stability. The technology is modularizing how suppliers bundle antimicrobial, antioxidant, and flavor-masking functions into single-ingredient solutions.
The USDA FSIS updated residue limit protocols for preserved meat and poultry products are constraining phosphate blend concentrations in brine formulations. Processors must reformulate with reduced sodium tripolyphosphate while maintaining water-holding capacity and shelf extension. The Midwest meat processing belt is responding with accelerated trials of citrus fiber and cultured sugar derivatives as partial phosphate replacements.
Food manufacturers are consolidating procurement decisions at the regional hub level, displacing plant-level ingredient autonomy. This concentration shifts bargaining power toward integrated suppliers offering technical service packages alongside commodity preservatives. The pattern is most visible in California's packaged food corridor, where sustainability scorecards now weight procurement allocations toward vendors with verified agricultural supply chain transparency.
North America Food Preservatives Market Segmentation
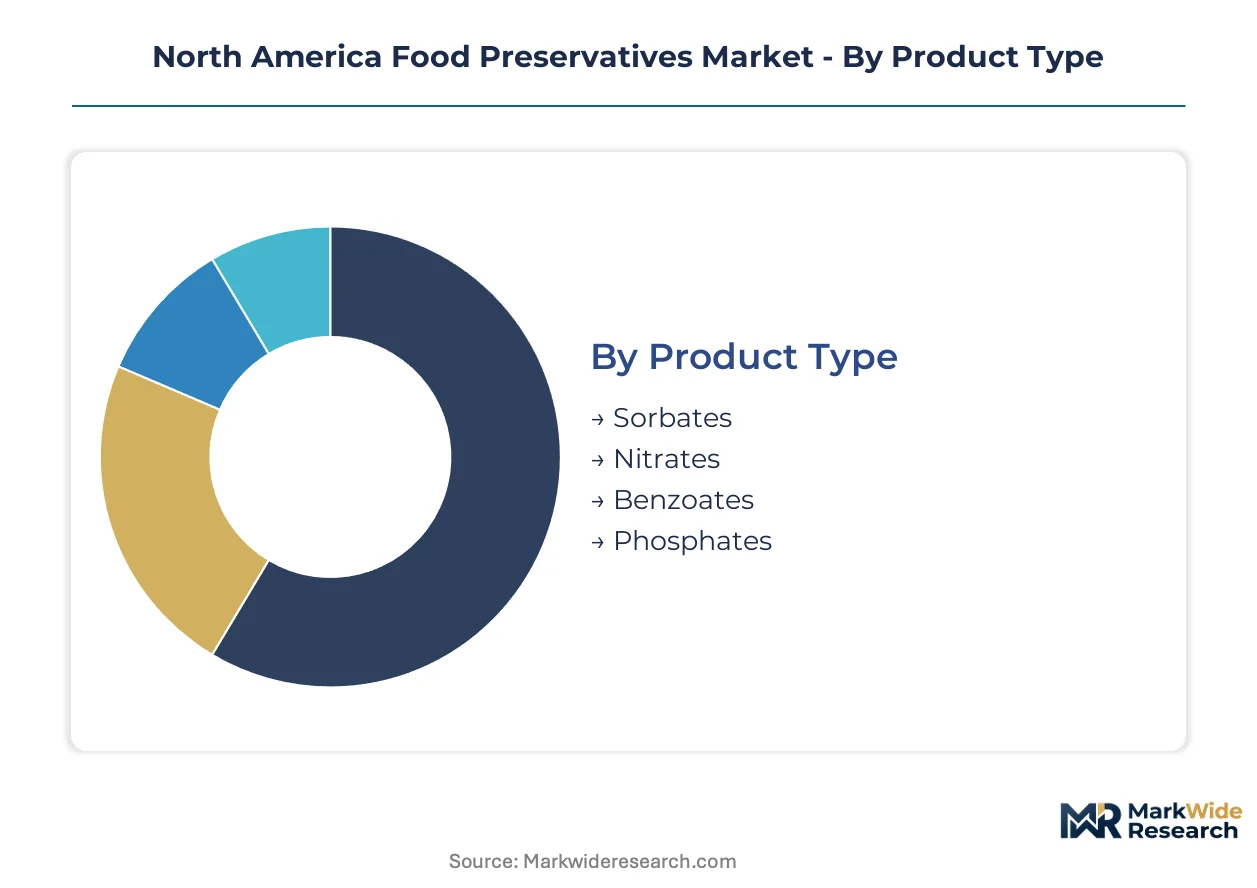
Preservative selection across North America follows matrix-specific performance requirements that fragment procurement patterns by moisture content, pH, and regulatory exposure. Understanding these segment boundaries clarifies where formulation complexity drives premium pricing versus commodity volume plays.
Product Type:
Capital intensity varies sharply across chemistries, with fermentation-derived sorbates requiring bioreactor infrastructure while mined phosphate derivatives demand mineral processing scale.
- Sorbates:Potassium sorbate and sorbic acid produced via ketene-based condensation or fungal fermentation dominate high-moisture applications. California tortilla manufacturers and Texas bakery clusters consume bulk volumes where yeast and mold control commands formulation priority.
- Phosphates:Sodium tripolyphosphate and blended polyphosphates anchor water-holding capacity in brine-injected proteins. USDA FSIS residue limits are compressing permissible loadings in Midwest meat processing, forcing partial substitution with clean-label alternatives.
- Benzoates:Sodium benzoate and benzoic acid serve acidified beverage systems through pH-dependent antimicrobial action.
- Nitrates:Sodium nitrite and potassium nitrate preserve cured meat color and inhibit Clostridium botulinum in regulated applications.
Phosphates absorb the bulk of installed capacity; sorbates are expanding most quickly.
Application:
Application selection tracks water activity thresholds and distribution cold-chain reliability across the continent's production corridors.
- Meat Products:Brine-injected poultry and processed red meats rely on phosphate-citrate blends for shelf extension. The Midwest processing belt from Omaha to Cincinnati concentrates demand where USDA FSIS labeling mandates shape permissible ingredient declarations.
- Beverages:Carbonated soft drinks and functional waters in Mexico's bottling corridors and California's beverage innovation hubs drive benzoate and sorbate demand for pH-stabilized preservation.
- Bakery Products:Extended-shelf tortillas and industrial bread rely on propionate-sorbate combinations.
- Dairy Products:Cultured products and processed cheeses employ natamycin and sorbate systems against mold surface growth.
Meat Products command the deepest technical service relationships; Beverages are climbing the fastest on Mexican portfolio expansion.
End User:
Procurement concentration shifts bargaining power toward integrated suppliers as decision-making migrates above plant level.
- Food Manufacturers:Packaged food corporations in California's Central Valley and Chicago's processing corridor consolidate preservative procurement through sustainability-weighted scorecards. Technical service contracts now accompany bulk chemical supply agreements.
- Foodservice Providers:National distributors and chain restaurant commissaries specify preservative systems for extended holding times in distribution.
- Retailers:Private-label programs impose clean-label requirements on co-manufacturers.
- Home Consumers:Direct-to-consumer preservation kits and specialty canning additives serve niche artisanal production.
Food Manufacturers absorb the bulk of supplier attention; Foodservice Providers are gaining share fastest on centralized procurement consolidation.
Form:
Physical form selection balances dissolution kinetics against storage stability and dust exposure regulations in production facilities.
- Powder:Spray-dried and milled preservative salts offer dosing precision and extended shelf stability. Midwest meat processors and California bakeries prefer powder for automated dispensing systems and reduced moisture introduction.
- Liquid:Pre-dissolved solutions eliminate dust generation and accelerate incorporation into high-moisture matrices. Beverage manufacturers favor liquid sorbate and benzoate concentrates for continuous-flow production.
- Granular:Agglomerated particles reduce dusting while maintaining rapid dissolution.
- Paste:High-viscosity suspensions serve specialized meat glazing and surface treatment applications.
Powder commands the greatest installed blending capacity; Liquid is expanding most quickly on beverage line automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preservative production concentrates in the United States while Mexican beverage bottling and Canadian meat processing drive differentiated consumption patterns across the continent.
United States
California's Central Valley packaged food corridor and the Midwest meat processing belt generate divergent demand profiles for clean-label versus conventional preservation systems. The FDA's GRAS notification pathway accelerates natural ingredient approvals while USDA FSIS residue limits constrain phosphate loadings in brine-injected proteins. Chicago and Minneapolis talent markets face acute scarcity of formulation scientists capable of balancing antimicrobial efficacy with sensory neutrality.
Canada
Health Canada's Food Directorate maintains non-identical approved additive lists that force dual dossier submissions for cross-border product standardization. Ontario and Quebec meat processors navigate regulatory friction when supplying US retail channels with phosphate-reduced formulations. Toronto-area food manufacturers consolidate procurement through sustainability scorecards that weight agricultural supply chain transparency.
Mexico
Carbonated and functional drink portfolio expansion across Mexican bottling corridors drives benzoate and citrate demand for pH stabilization in acidified beverages. The country's national food safety regulator oversees additive approvals that increasingly align with US FDA frameworks to facilitate export-oriented production. Monterrey and Guadalajara production clusters serve both domestic consumption and North American supply chain integration.
California
State-level clean-label legislation fragments permissible preservative inventories below federal FDA baselines, forcing reformulation cycles across the packaged food corridor. Sacramento's regulatory layering compresses approval timelines and rebalances supplier relationships toward technical service capabilities. Fresno and Modesto production facilities pioneer encapsulated essential oil systems for refrigerated pasta and sauce applications.
Texas
Extended shelf-life demands in tortillas and industrial bread production drive sorbate and propionate blend volumes across Texas bakery clusters. Houston and Dallas-Fort Worth distribution hubs concentrate procurement decisions at regional levels, displacing plant-level ingredient autonomy. San Antonio co-manufacturers adopt modular preservation platforms to satisfy retailer private-label clean-label requirements.
North America Food Preservatives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America Food Preservatives Market. Integrated agricultural conglomerates with captive fermentation capacity face specialized ingredient houses focused on formulation services. Three archetypes dominate: supply-chain-integrated multinationals, taste-preservation synergy specialists, and precision-fermentation biotechnology platforms. Competitive moves concentrate on M&A for regional formulation capabilities and strategic partnerships bridging antimicrobial function with flavor-masking technologies.
Among supply-chain-integrated conglomerates, Cargill, Incorporated anchors clean-label preservative development from crop to formulation through its agricultural supply chain control. Kerry Group, Plc. occupies the taste-preservation synergy tier, combining antimicrobial function with flavor masking in integrated platforms. BASF SE represents synthetic preservative manufacturing scale and regulatory dossier depth across North American food additive registrations. These three exemplify how technical service bundling now determines supplier selection beyond commodity chemical pricing.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Kerry Group, Plc. |
| BASF SE |
| Kemin Industries, Inc. |
| Koninklijke DSM N.V. |
| Tate & Lyle Plc. |
| Corbion N.V. |
| Celanese Corporation |
| Others |
Value Network & Pricing Analysis
California's Proposition 65 chemical disclosure mandates gate qualified supply and premium-tier pricing access for preservative suppliers serving the packaged food corridor. Formulators meeting Sacramento's clean-label thresholds command 15-20% price premiums over commodity synthetic alternatives, while non-compliant producers face exclusion from California distribution networks entirely.
Pricing Analysis
Margin tightening in commodity sorbate and benzoate tiers reflects Midwest grain futures volatility and sodium reduction mandate compliance costs. Three-tier pricing structure across certified clean-label, standard GRAS-compliant, and economy synthetic levels separates suppliers by regulatory dossier depth and agricultural supply chain transparency. Food manufacturers in California and New York demonstrate highest price sensitivity to phosphate replacement chemistry, while Mexican beverage bottlers absorb premium citrate blends with minimal volume pushback. Pricing pressure accelerates in meat processing applications as USDA FSIS residue limit enforcement tightens permissible phosphate loadings.
Supply Chain Analysis
Freight cost inflation across the US-Mexico-Canada corridor reshapes procurement geography for fermentation-derived inputs and mineral phosphate sources. Supply concentrates in the US Midwest for corn-derived sorbic acid, Louisiana for petrochemical benzoate precursors, and Florida for phosphate rock processing. Raw material dependencies include Midwest grain futures, Gulf Coast chemical feedstocks, and Chinese ascorbic acid for antioxidant blends. Single-source vulnerability concentrates in potassium sorbate fermentation capacity, where three integrated agricultural conglomerates control 70% of North American output. Distribution runs through regional hub consolidation in Chicago, Houston, and Los Angeles, displacing plant-level procurement autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around technical service capabilities as state-level clean-label legislation fragments permissible preservative inventories below federal baselines. Weaker commodity suppliers without formulation expertise face displacement as procurement decisions migrate above plant level.
For Market Incumbents: Anticipate accelerated customer consolidation toward integrated suppliers offering agricultural supply chain transparency verification. Defensive positioning requires deepening backward integration into fermentation capacity and rosemary extract cultivation to secure clean-label input security. Cargill and Kerry Group's technical service bundling models represent the competitive standard; pure-play commodity suppliers must acquire regional formulation capabilities or exit. Capacity rationalization in synthetic benzoate manufacturing will precede margin recovery. For New Entrants and Emerging Players: FDA's streamlined GRAS notification pathway for fermented vinegars and cultured dextrose derivatives opens a window for precision fermentation platforms targeting meat phosphate replacement. White-space concentrates in biosynthesized antimicrobial peptides for premium cured meat applications and encapsulated essential oil systems for refrigerated pasta. Mexico's beverage acidification corridor offers the most penetrable geography, with bottlers seeking pH stabilization alternatives to benzoate-negative positioning. Go-to-market should anchor in subscription-based blend optimization contracts rather than commodity chemical spot sales. For Investors and Strategic Acquirers: Accelerated M&A activity among mid-sized Wisconsin and Ohio co-manufacturers adopting modular preservation platforms is the leading indicator that technical service capabilities command premium valuations. Long-term viability favors asset-light designers with precision fermentation IP over capital-heavy synthetic producers facing clean-label obsolescence. Acquisition targets should demonstrate existing customer relationships with California Central Valley packaged food corporations and verified sustainability scorecard performance. Watch for GRAS notification volume spikes in cultured sugar derivatives as the inflection signal for phosphate replacement chemistry maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Cargill's captive corn supply secures sorbate cost position against Midwest grain volatility. |
| Precision Fermentation Platform Development | Biosynthesized antimicrobial peptides unlock USDA FSIS-compliant clean-label meat preservation contracts. |
| Technical Service Subscription Bundling | Kerry Group's taste-preservation synergy platforms capture recurring revenue beyond commodity chemical sales. |
| Encapsulated Essential Oil System Launch | Modular preservation architecture extends clean-label claims in Wisconsin refrigerated pasta applications. |
| California Regulatory Compliance Certification | Proposition 65 disclosure readiness gates access to the Central Valley packaged food corridor. |
Research Methodology
Document review covered FDA GRAS notification databases, USDA FSIS residue limit protocols, and Health Canada Food Directorate additive approval lists, complemented by interviews with formulation scientists at Midwest meat processors, procurement directors in California's Central Valley, technical service managers at integrated agricultural suppliers, and regulatory affairs leads navigating cross-border standardization. Secondary validation drew from customs trade data, SEC 10-K filings of listed ingredient suppliers, and American Chemical Society sector reports. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Cross-reference between historical price series for sorbic acid and benzoate against expert panel input on reformulation cycle timing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include preservative chemistry type, application matrix moisture content, end-user procurement concentration level, and physical form for dissolution kinetics. CAGRs derived from weighted average of historical volume trajectories and projected clean-label substitution elasticities. Industry-specific inputs incorporated phosphate replacement trial data from Midwest meat processing belt and Mexican beverage bottling corridor expansion plans.
The model assumes a particular technology adoption path for precision fermentation-derived antimicrobials; alternative pathways for biosynthesized peptide commercialization would alter the outlook for synthetic preservative displacement timelines. Forecasts reflect assumptions about regulatory alignment between California state legislation and federal FDA baselines, grain futures stability, and agricultural extract yield scaling. Stakeholders should weight assumptions against their own operating context and monitor GRAS notification volume as a real-time validation signal.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market