
 Fortified Milk and Milk Products Market | 2026-2036
Fortified Milk and Milk Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Milk and Milk Products Market Foresight
A2 protein certification and ultra-high temperature organic fortification standards are unwinding price compression across commodity dairy shelves. Fonterra Co-operative Group Limited leverages its New Zealand grass-fed supply base to command premium shelf positioning in Asian retail channels. Nestlé S.A. sustains pediatric nutrition dominance through healthcare facility partnerships spanning Latin America and Southeast Asia. Danone S.A. specializes in medical-grade protein fortification for geriatric and post-surgical recovery segments.
Fortified milk and milk products denote fluid milk, fermented derivatives, and processed formats enhanced with micronutrients, functional proteins, or bioactive lipids through standardized homogenization and aseptic injection protocols, delivering targeted nutritional density for populations with documented deficiency risks or elevated metabolic demands. Vitamin D Fortified Milk and Protein Fortified Milk anchor volume throughput in North American retail, while Omega-3 Fortified Milk captures accelerating functional food positioning in European cardiovascular health positioning. Application demand clusters in Infant Nutrition and Geriatric Nutrition, where margin pools deepen around clinical validation requirements and prescription-channel access controls.
FDA nutrition labeling mandates and EFSA health claim authorization frameworks shape product formulation thresholds and commercial messaging boundaries across their respective jurisdictions, with India's FSSAI fortification standards now requiring micronutrient disclosure on all packaged dairy entering institutional channels. Stakeholders must monitor divergence between Codex Alimentarius guidelines and emerging national bioavailability testing protocols, as compliance fragmentation threatens cross-border formulation standardization. Procurement officers in healthcare and education sectors face escalating vendor qualification complexity that favors processors with captive laboratory certification capacity.
Market Dynamics
India's FSSAI fortification mandates are compressing formulation cycles as institutional buyers demand micronutrient disclosure compliance before contract award, forcing processors to revalidate homogenization protocols against bioavailability testing standards.
Growth Catalysts
- Pediatric Nutrition Procurement:India's school feeding programs under ICDS and PM POSHAN schemes are mandating vitamin-fortified dairy inclusion, creating institutional volume anchors for processors with FSSAI-certified production lines.
- Geriatric Protein Density Standards:Japan's METI guidelines for sarcopenia prevention are elevating medical-grade protein fortification requirements in aged-care facilities, opening prescription-channel access for validated formulations.
- A2 Beta-Casein Certification:New Zealand's grass-fed supply base verification protocols are enabling premium shelf positioning in Asian retail channels where digestive tolerance claims command price premiums.
Market Restraints
- Fortificant Input Volatility:Vitamin D3 and omega-3 algal oil concentrate prices fluctuate with marine harvest cycles and pharmaceutical extraction capacity, squeezing margin predictability for mid-scale processors.
- Export-Grade Technology Concentration:Ultra-high temperature organic fortification equipment and aseptic injection systems are controlled by Dutch and New Zealand engineering firms, creating procurement bottlenecks for emerging market entrants.
- Regulatory Divergence Friction:Codex Alimentarius micronutrient thresholds diverge from India's FSSAI bioavailability testing protocols and EFSA health claim authorization frameworks, forcing multi-jurisdictional players to maintain parallel formulation databases.
Strategic Opportunities
- Post-Surgical Recovery Segments:Medical-grade protein fortification for hospital discharge nutrition protocols represents underpenetrated white space in China's tier-2 urban maternal health channels where clinical validation requirements are still forming.
- Plant-Dairy Hybrid Convergence:Pea-protein and oat-lipid emulsion technologies combined with traditional dairy fortification infrastructure are enabling novel texture-nutrition positioning in European flexitarian retail.
- Direct-to-Institution Platforms:Healthcare facility purchasing cooperatives in Latin America are consolidating procurement authority, creating channel innovation opportunities for processors with captive laboratory certification capacity.
Industry Challenges
- Bioanalytical Talent Scarcity:Micronutrient stability testing and in-vitro bioavailability assay execution require specialized food chemistry expertise that outpaces current technical training pipeline output in emerging dairy processing regions.
- Legacy System Integration:Homogenization and aseptic packaging lines installed before 2018 lack digital traceability modules required for FSSAI-mandated batch-level fortification disclosure, forcing costly retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Milk and Milk Products Market |
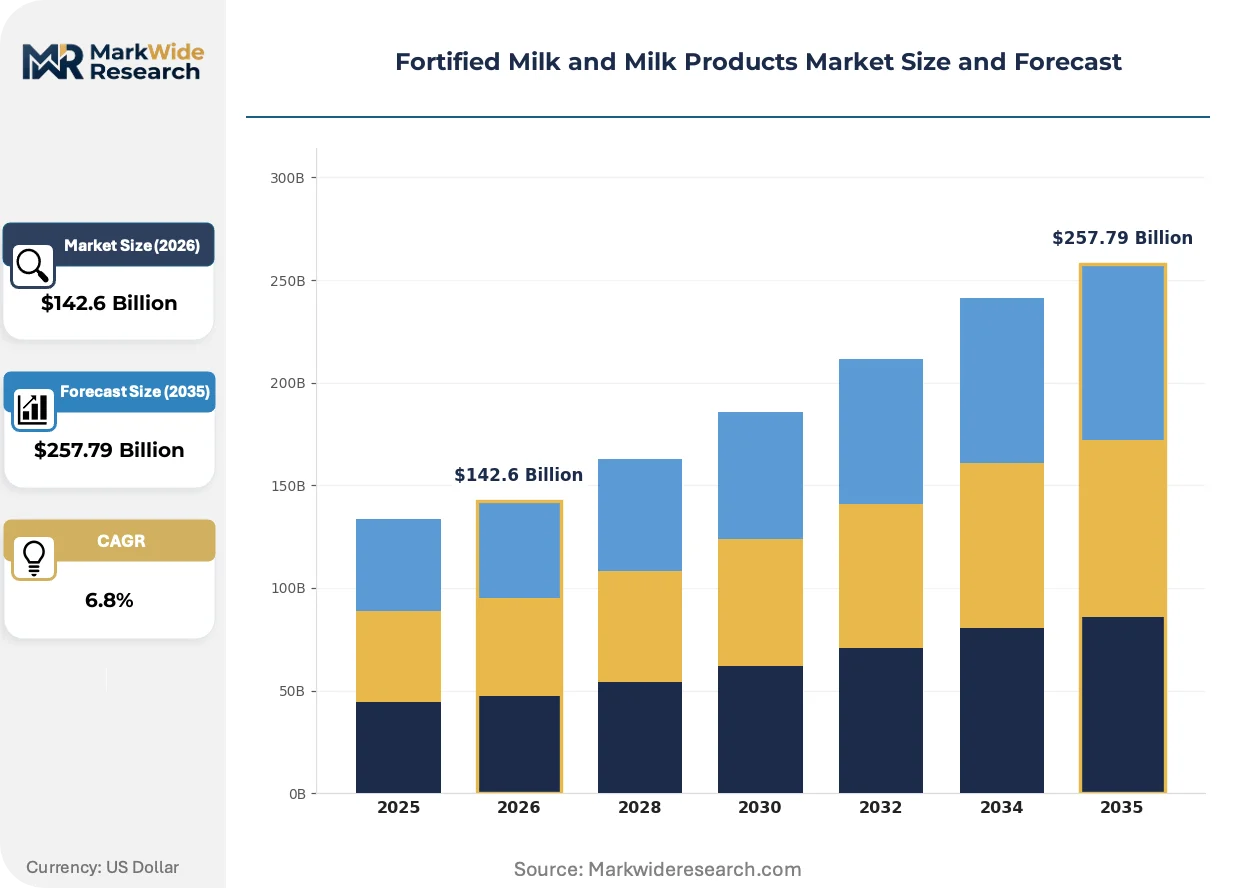
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $257.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin D Fortified Milk, Calcium Enriched Milk, Protein Fortified Milk, Iron Enhanced Milk, Omega-3 Fortified Milk Application: Infant Nutrition, Geriatric Nutrition, Sports Nutrition, Dietary Supplements, Weight Management End User: Healthcare Facilities, Fitness Centers, Educational Institutions, Food Service Providers Packaging Type: Tetra Pak, Plastic Bottles, Glass Bottles, Cartons, Pouches |
| Companies Covered | Fonterra Co-operative Group Limited, FrieslandCampina, Nestlé S.A., Dairy Farmers of America, Yili Group, Lactalis, Arla Foods, The Kraft Heinz Company, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Milk and Milk Products Market Shifts & Advancements
Microencapsulation and lipid-delivery vector technologies are reshaping fortification efficacy claims, while regulatory disclosure mandates and institutional procurement consolidation are rewiring competitive access to volume channels.
Microencapsulation of heat-sensitive vitamins using lipid-shell and alginate-matrix technologies is bifurcating fortification efficacy standards between premium clinical-grade and commodity retail segments. Pediatric nutrition formulators in hospital and early childhood development channels are adopting these systems at accelerated validation cycles. This technology is bifurcating margin pools as bioavailability-certified products capture prescription-channel pricing while conventional fortified milk faces retail shelf compression.
EFSA's 2023 revision to nutrition and health claims regulation on calcium absorption and vitamin D status biomarkers is tightening evidentiary thresholds for commercial messaging. Processors must now submit human intervention study data for authorization, extending product launch timelines by 18-24 months. Infant nutrition applications in European retail face the steepest compliance burden, with several legacy fortification claims now restricted to medical food classification.
Healthcare facility purchasing cooperatives are consolidating vendor qualification around single-source laboratory certification capacity, displacing fragmented distributor networks in Latin American and Southeast Asian markets. Hospital nutrition committees now mandate batch-level fortification disclosure and stability documentation before contract inclusion. This concentration is most visible in Brazil's SUS-affiliated facilities and Thailand's provincial health system procurement, where three-tier vendor classification systems favor integrated processors.
Fortified Milk and Milk Products Market Segmentation
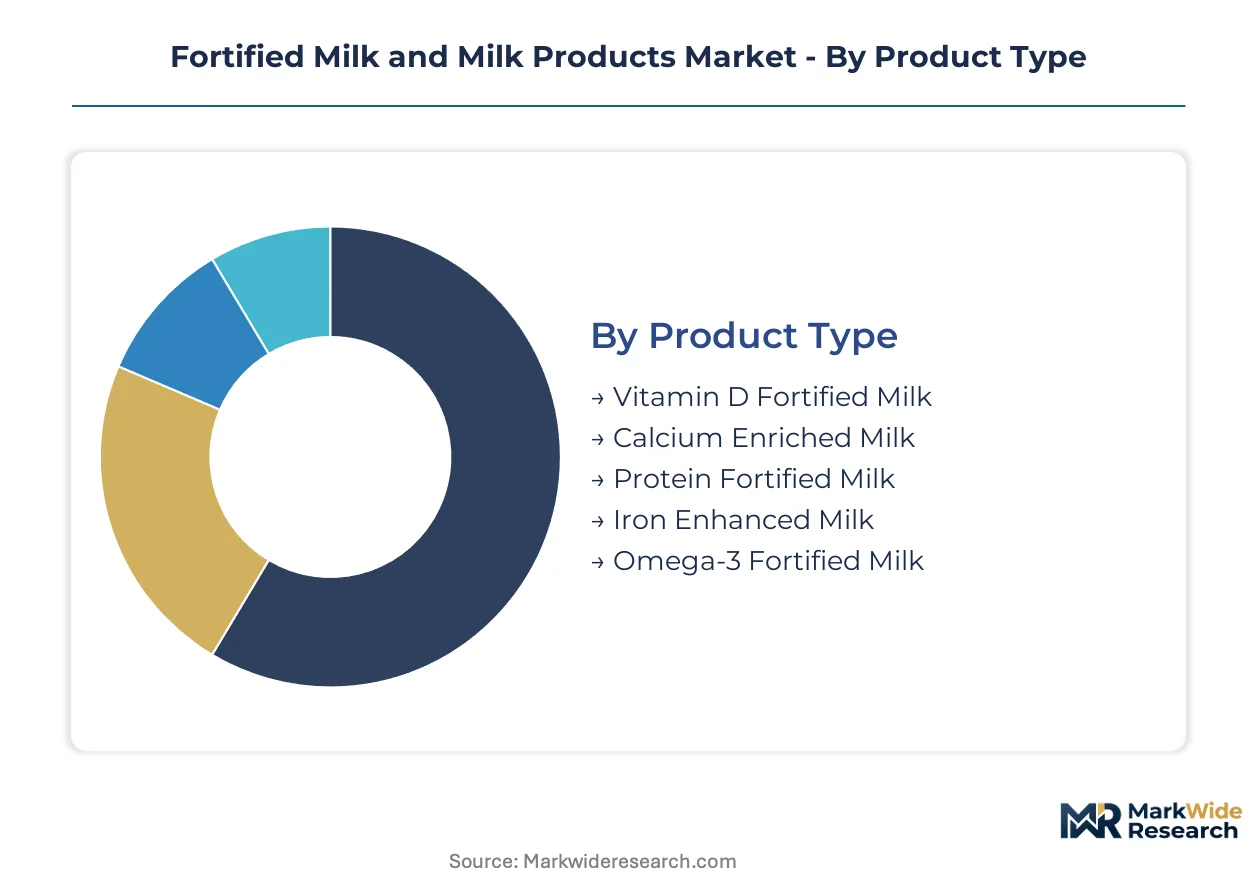
Segmentation in fortified dairy reveals how micronutrient targeting, institutional procurement channels, and packaging shelf-life requirements create distinct margin architectures. Each category exposes where formulation complexity translates into pricing power versus commodity compression.
Product Type:
Margin pools concentrate around bioavailability-certified formats where clinical validation supports prescription-channel access, while commodity fortification faces retail price compression.
- Vitamin D Fortified Milk:Fluid milk enhanced with cholecalciferol through homogenized dispersion, targeting populations with documented deficiency risks. Demand anchors in North American retail where FDA labeling mandates drive category standardization, though margin pressure intensifies from private-label competition.
- Protein Fortified Milk:Milk with added whey or casein fractions achieving elevated protein density per serving, often deployed in medical nutrition protocols. Japan's METI sarcopenia prevention guidelines are elevating requirements in aged-care facilities, opening prescription-channel pricing for validated formulations.
- Calcium Enriched Milk:Tricalcium phosphate or calcium carbonate fortification for bone health positioning, common in pediatric and geriatric segments.
- Iron Enhanced Milk:Ferrous sulfate or ferric pyrophosphate addition addressing anemia prevalence in institutional feeding programs.
- Omega-3 Fortified Milk:Algal oil or fish oil emulsion delivering EPA/DHA for cardiovascular positioning, capturing functional food premiums in European retail channels.
The dominant share belongs to Vitamin D Fortified Milk, while Protein Fortified Milk is closing the gap fastest through medical-grade certification requirements.
Application:
Volume throughput clusters where institutional procurement mandates create contract anchors, while clinical validation requirements deepen margin pools in medical nutrition.
- Infant Nutrition:Specialized fortification meeting stringent micronutrient density and safety thresholds for early childhood development. India's ICDS and PM POSHAN schemes are mandating vitamin-fortified dairy inclusion, creating volume anchors for FSSAI-certified processors.
- Geriatric Nutrition:Protein-dense and vitamin-enhanced formats addressing sarcopenia, bone density loss, and malabsorption in aged populations. Japan's aged-care facility procurement standards are elevating medical-grade requirements, with hospital nutrition committees demanding batch-level stability documentation.
- Sports Nutrition:High-protein and electrolyte-fortified recovery formats targeting athletic performance and muscle protein synthesis.
- Dietary Supplements:Concentrated micronutrient delivery in beverage formats competing with traditional pill and powder supplements.
- Weight Management:Portion-controlled, protein-enhanced formats with reduced caloric density for metabolic health positioning.
Infant Nutrition holds the volume base through school feeding mandates, though Geriatric Nutrition is expanding most quickly via prescription-channel access controls.
End User:
Procurement authority concentration is rewiring competitive access, with integrated laboratory certification becoming a vendor qualification threshold.
- Healthcare Facilities:Hospital and aged-care nutrition committees requiring clinical validation, batch traceability, and stability documentation. Brazil's SUS-affiliated facilities and Thailand's provincial health systems are consolidating purchasing cooperatives around three-tier vendor classification systems.
- Educational Institutions:School feeding programs under government-mandated nutrition schemes with FSSAI disclosure requirements. India's institutional procurement is compressing formulation cycles as buyers demand micronutrient compliance before contract award.
- Fitness Centers:Sports nutrition retail and recovery beverage provisioning with performance-focused positioning.
- Food Service Providers:Commercial and institutional catering requiring extended shelf-life and portion-control formats.
Healthcare Facilities command the steepest vendor qualification barriers, while Educational Institutions are scaling fastest through government program expansion.
Packaging Type:
Technology concentration in aseptic systems creates procurement bottlenecks, with shelf-life extension and fortification stability driving format selection.
- Tetra Pak:Aseptic carton systems enabling extended shelf-life without refrigeration through ultra-high temperature processing and multilayer barrier construction. Dutch and New Zealand engineering firms control export-grade fortification equipment, creating supply constraints for emerging market entrants.
- Plastic Bottles:HDPE and PET formats with varying oxygen barrier properties for refrigerated distribution chains.
- Glass Bottles:Premium positioning with inert material properties preserving flavor and micronutrient stability.
- Cartons:Gable-top and refrigerated formats for shorter shelf-life, lower-cost distribution.
- Pouches:Flexible film formats for portion control and emerging market affordability positioning.
Tetra Pak dominates institutional and export channels through aseptic certification, though Pouches are gaining share fastest in emerging market affordability segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-grade fortification technology concentrates with Dutch engineering firms and New Zealand dairy processors, while procurement mandates in India's school systems and China's urban maternal health channels reshape demand geography. National bioavailability testing protocols are fragmenting compliance requirements across jurisdictions.
India
FSSAI-mandated micronutrient disclosure requirements are compressing vendor qualification cycles for institutional dairy procurement. The PM POSHAN and ICDS school feeding schemes now require vitamin-fortified dairy inclusion, creating volume anchors for certified processors. Maharashtra and Gujarat house the densest clusters of FSSAI-compliant production lines serving institutional channels.
China
Urban maternal health channels in tier-2 cities are elevating clinical validation requirements for post-surgical recovery nutrition formats. SAMR oversight of functional food claims intersects with hospital nutrition committee procurement consolidation. The Yangtze River Delta region concentrates demand for medical-grade protein fortification in aged-care and discharge protocols.
United States
FDA nutrition labeling mandates drive category standardization for vitamin D fortification across retail dairy shelves. Private-label competition intensifies margin pressure on commodity fortification formats. Wisconsin and California anchor fluid milk processing capacity with integrated homogenization and aseptic packaging infrastructure.
Netherlands
Dutch engineering firms control ultra-high temperature organic fortification equipment and aseptic injection systems, creating technology export bottlenecks for emerging market entrants. FrieslandCampina leverages domestic processing expertise to serve European institutional channels. The Randstad region concentrates R&D activity for lipid-delivery vector and microencapsulation technologies.
Japan
METI guidelines for sarcopenia prevention are elevating medical-grade protein fortification requirements in aged-care facilities. Hospital nutrition committees demand batch-level stability documentation before contract inclusion. The Kanto region around Tokyo anchors prescription-channel access for validated formulations targeting geriatric nutrition segments.
Fortified Milk and Milk Products Market Competitive Landscape
Concentration sits with integrated dairy cooperatives and multinational nutrition conglomerates that control captive laboratory certification capacity. The vendor base stratifies across three tiers: premium clinical-grade formulators with prescription-channel access, standard institutional-grade suppliers with FSSAI or EFSA compliance, and commodity private-label processors facing retail price compression. Dominant competitive moves include backward integration into fortificant supply chains and technology licensing partnerships with Dutch equipment engineering firms.
Within the cooperative-processor tier, Fonterra Co-operative Group Limited and FrieslandCampina exemplify grass-fed supply base verification and export-grade fortification technology control. Among multinational nutrition specialists, Nestlé S.A. and Danone S.A. occupy positions anchored by healthcare facility partnerships and medical-grade protein fortification expertise. Yili Group represents the scale-driven Chinese dairy processor archetype serving domestic maternal health and institutional channels.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| FrieslandCampina |
| Nestlé S.A. |
| Dairy Farmers of America |
| Yili Group |
| Lactalis |
| Arla Foods |
| The Kraft Heinz Company |
| Danone S.A. |
| Others |
Supply & Pricing Matrix
FSSAI micronutrient disclosure mandates gate both supplier qualification and price tier differentiation in India's institutional dairy channels. Procurement officers now demand batch-level fortification documentation before contract award, compressing margin pools for processors lacking captive laboratory certification while enabling premium positioning for bioavailability-validated formats.
Pricing Analysis
FDA nutrition labeling and EFSA health claim authorization dictate the pricing tier structure across North American and European retail channels. Three-tier pricing structure across premium clinical-grade, standard institutional-grade, and economy private-label levels separates prescription-channel medical nutrition from commodity fluid milk. Price differentiation rests on bioavailability certification status and homogenization protocol validation. Cost compression in standard retail tiers is intensifying because private-label competition erodes brand premiums. Educational institutional buyers exhibit highest price sensitivity, while hospital nutrition committees demonstrate lowest sensitivity due to clinical outcome requirements.
Supply Chain Analysis
Inventory cycles for vitamin D3 and omega-3 algal oil concentrates extend 8-14 weeks due to marine harvest seasonality and pharmaceutical extraction scheduling. Ultra-high temperature fortification equipment concentrates with Dutch engineering firms and New Zealand dairy technology exporters. Raw material dependencies center on cholecalciferol suppliers, algal oil concentrate processors, and whey protein fractionation facilities. Single-source vulnerability in aseptic injection system engineering creates procurement bottlenecks for emerging market entrants. Distribution runs through healthcare facility purchasing cooperatives in Latin America and government procurement aggregators in India's school feeding programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fortified dairy markets increasingly reward service-attach revenue streams, with laboratory certification services and batch-level stability documentation expanding faster than base product throughput. Recurring certification contracts and validation partnerships now generate margin pools that exceed commodity processing returns.
For Market Incumbents: Secure backward integration into fortificant supply chains to buffer input volatility from marine harvest cycles. Lock in multi-year laboratory certification service contracts with institutional buyers to displace fragmented distributor networks. Plant-dairy hybrid R&D partnerships represent the critical capability gap threatening grass-fed supply base positioning. For New Entrants and Emerging Players: FSSAI fast-track certification for micronutrient disclosure compliance opens procurement access to India's PM POSHAN and ICDS school feeding schemes. Post-surgical recovery nutrition in China's tier-2 urban maternal health channels offers the most penetrable white space with still-forming clinical validation requirements. Direct-to-institution platform development bypasses entrenched retail shelf competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale processors holding FSSAI-compliant production lines but lacking integrated laboratory capacity. Five-to-ten year viability hinges on prescription-channel access controls deepening around bioavailability certification. Watch for consolidation signals when hospital purchasing cooperatives in Brazil's SUS-affiliated facilities reduce vendor tiers from three to two classification levels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fortificant Supply | Captive vitamin D3 and algal oil sourcing buffers margin volatility from marine harvest cycles. |
| Laboratory Certification Capacity Expansion | In-house bioavailability testing meets FSSAI disclosure mandates and hospital procurement requirements. |
| Direct-to-Institution Platform Development | Bypasses retail shelf compression by accessing consolidated healthcare and education purchasing cooperatives. |
| Microencapsulation Technology Licensing | Lipid-shell and alginate-matrix systems unlock prescription-channel pricing for heat-sensitive vitamin delivery. |
| Plant-Dairy Hybrid Product Line Launch | Pea-protein and oat-lipid emulsions capture European flexitarian positioning without abandoning dairy infrastructure. |
Research Methodology
Operator-level perspectives from dairy processing plant managers, FSSAI compliance officers, hospital nutrition committee chairs, and institutional procurement directors anchored the qualitative base. Secondary validation drew from FSSAI regulatory filings, EFSA health claim authorization databases, FDA nutrition labeling guidance documents, and Codex Alimentarius micronutrient threshold standards. Bottom-up volume estimates triangulated against top-down category expenditure data from government nutrition program budgets and healthcare facility purchasing records.
Sensitivity analysis tested forecast robustness across alternative bioavailability testing protocol adoption timelines and fortificant input cost scenarios. Segmentation modeling spanned fortification type, application channel, end-user procurement authority, and packaging technology shelf-life tier. CAGRs derived from regression against institutional procurement expansion trajectories and clinical validation requirement diffusion patterns. Modeled inputs included ICDS and PM POSHAN scheme budget allocations, METI sarcopenia guideline implementation schedules, and EFSA health claim authorization pipeline backlogs.
Underlying assumptions cover sustained FSSAI enforcement intensity, stable marine harvest cycles for algal oil feedstock, and gradual EFSA evidentiary threshold tightening, with deviation risk concentrated in regulatory divergence acceleration or single-source equipment supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market