
 Global Fortified Dairy Products Market | 2026-2036
Global Fortified Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fortified Dairy Products Market Intelligence
Personalized nutrition planning, often delivered through digital applications, is broadening the core product offering beyond the physical item. Nestlé leverages its extensive R&D to develop products for specific health outcomes, from infant development to geriatric care. Danone differentiates its portfolio by focusing on probiotic-fortified yogurts and drinks. Meanwhile, Arla Foods sustains its market position through a strong focus on organic and naturally fortified milk products across Europe.
Fortified dairy products are conventional dairy items, such as milk or yogurt, to which essential micronutrients are added post-pasteurization. These additions, including Vitamin D, calcium, or Omega-3 fatty acids, are not naturally present in sufficient quantities. Fortified milk remains the largest product type, but enriched yogurt shows significant expansion, particularly with added probiotics. Within applications, infant nutrition and geriatric nutrition command premium pricing due to stringent formulation requirements and targeted health benefits.
Regulatory frameworks from the U.S. FDA and the European Food Safety Authority (EFSA) govern permissible nutrient levels and health claims on packaging. In India, the FSSAI's standards for fortified foods directly influence product composition and market entry for manufacturers. Producers must continually balance the cost of fortification against evolving consumer expectations for clean labels and scientifically validated health benefits.
Market Dynamics
The central dynamic shaping the fortified dairy market is the tension between mounting regulatory pressure for scientifically validated nutrient content and a parallel consumer demand for clean-label, minimally processed products. This forces producers to innovate formulations that deliver proven health benefits without compromising perceived naturalness or taste.
Growth Catalysts
- Government Health Initiatives:National wellness campaigns, such as those promoted by China's government and food standards set by India's FSSAI, encourage the consumption of nutrient-fortified foods to address public health deficiencies, directly stimulating market demand.
- Geriatric Nutrition Demand:An aging global population is driving consumption of dairy products fortified with calcium, Vitamin D, and proteins to support bone health, muscle maintenance, and combat age-related nutritional gaps.
- Ingredient Technology:Advances in microencapsulation are enabling the effective delivery of sensitive ingredients like Omega-3 fatty acids and probiotics, protecting their stability and bioavailability through processing and digestion, thereby expanding product possibilities.
Market Restraints
- Ingredient Cost Volatility:The price of specialized micronutrients, particularly high-purity vitamins, patented probiotic strains, and marine-derived Omega-3s, is subject to significant fluctuation, impacting final product pricing and manufacturer margins.
- Sensory Profile Challenges:Fortification with certain minerals, notably iron and zinc, can impart undesirable metallic tastes or alter the texture of dairy products, creating a significant technical barrier to consumer acceptance.
- Divergent Health Claim Rules:Navigating the different regulatory standards for health claims between jurisdictions, such as the stringent requirements of the EFSA in Europe versus the FDA in the United States, creates complexity and cost for global brands.
Strategic Opportunities
- Plant-Based Fortification:The expansion of plant-based milks and yogurts presents a significant opportunity to apply fortification expertise to non-dairy alternatives, targeting flexitarian and vegan consumers with enriched oat, soy, and almond products.
- Personalized Nutrition Platforms:Developing fortified dairy products that integrate with digital health apps and direct-to-consumer (D2C) subscription services allows for customized nutritional solutions tailored to individual consumer needs and health goals.
- Emerging Market Penetration:Untapped demand in regions like Southeast Asia and Latin America, where awareness of nutritional benefits is rising alongside disposable income, offers substantial growth potential for fortified dairy products.
Industry Challenges
- Supply Chain Transparency:Manufacturers face the operational challenge of ensuring and documenting the traceability and purity of fortification ingredients to satisfy consumer demands for clean labels, non-GMO, and organic certifications.
- Benefit Communication:Communicating the specific, scientifically-backed health benefits of fortified products on packaging without violating strict advertising and health claim regulations from bodies like the EFSA remains a persistent marketing and legal hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fortified Dairy Products Market |
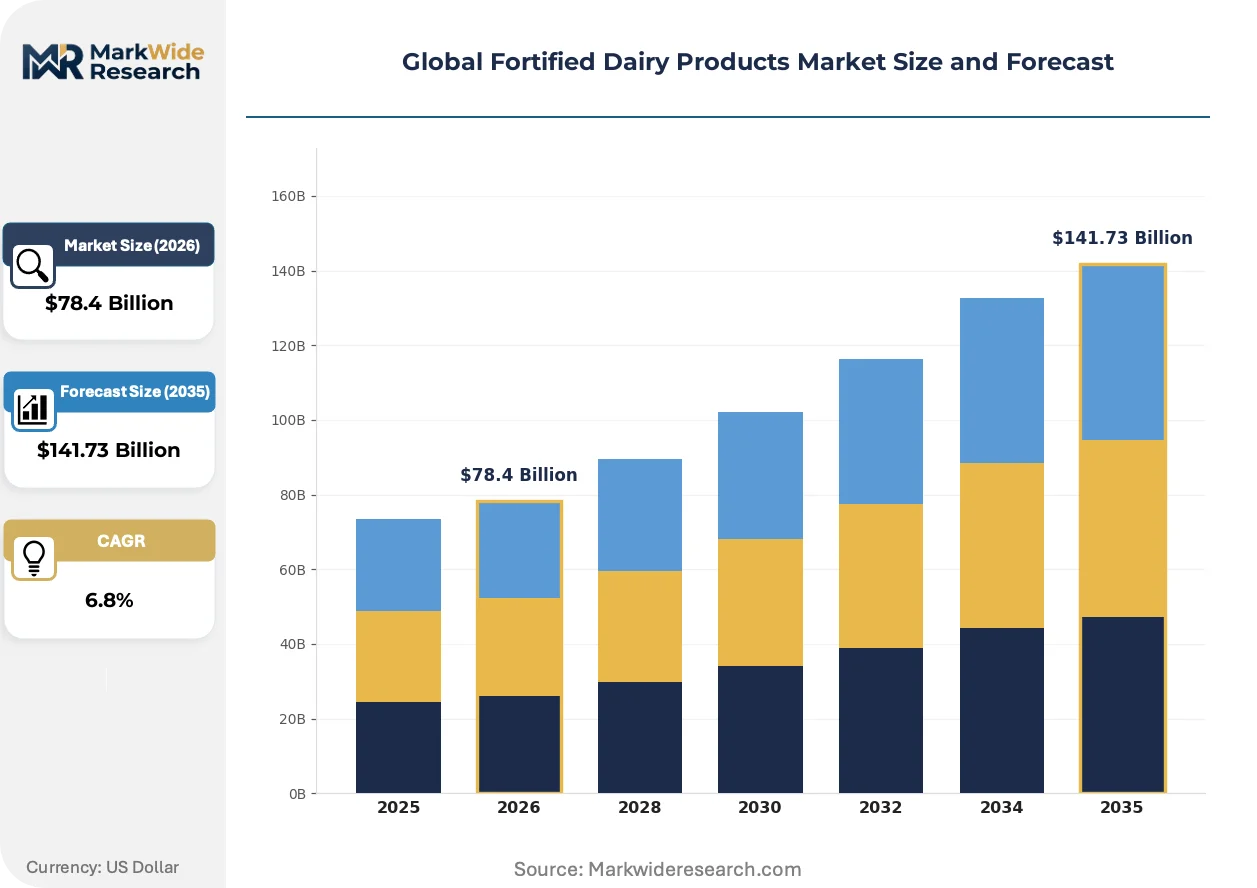
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fortified Milk, Enriched Yogurt, Nutrient-Enhanced Cheese, Vitamin D Pasteurized Cream, Mineral-Fortified Butter Fortifying Nutrient: Calcium, Vitamin A, Vitamin D, Omega-3 Fatty Acids, Probiotics Application: Infant Nutrition, Geriatric Nutrition, Sports Nutrition, Weight Management, Prenatal Supplements End User: Food Manufacturers, Nutraceutical Companies, Retail Chains, Health Clinics, Dietary Supplement Producers |
| Companies Covered | Arla Foods, China Mengniu Dairy Company, Nestlé, FrieslandCampina, Yili Group, Danone, Fonterra Co-operative Group, GCMMF, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fortified Dairy Products Market Strategic Shifts & Innovations
Product development is shifting from broad, population-wide fortification toward highly targeted formulations designed for specific life stages and health outcomes. This evolution is driven by advancements in nutritional science and the integration of digital tools that enable greater personalization of dietary choices.
Digital health platforms are increasingly connecting consumers with personalized dietary advice. These applications gather user data on lifestyle, activity, and health goals to generate specific nutritional recommendations. The sports nutrition and proactive wellness segments are the fastest adopters, seeking data-driven approaches to optimize performance and health. This technology is unifying the advisory service with the physical product, creating integrated nutritional systems rather than just selling a fortified item.
Regulatory scrutiny over health claims is intensifying, particularly from the European Food Safety Authority (EFSA) and the U.S. FDA. This pressure compels manufacturers to provide robust scientific evidence, often from human clinical trials, to substantiate any benefit marketed on the package. The infant nutrition and medical foods segments are most affected, leading to increased R&D investment and reformulation to meet these higher standards of proof.
Consumer purchasing behavior is evolving from one-off retail buys to subscription-based services for specialized nutritional products. This shift disrupts the dominance of traditional grocery channels for certain high-value fortified items, such as personalized probiotic yogurts or cognitive health drinks. This direct-to-consumer (D2C) model is most visible in major urban centers in North America and Western Europe, where logistics infrastructure supports customized, scheduled deliveries.
Global Fortified Dairy Products Market Segmentation
The fortified dairy products market segmentation provides a granular view of consumer preferences and manufacturer strategies. This analysis dissects the market by product type, fortifying nutrient, application, and end user, revealing distinct value propositions across various segments. Understanding these segments allows market participants to tailor product development and marketing efforts effectively.
Product Type:
The purchasing decisions for fortified dairy products often depend on the format and convenience offered by each product type.
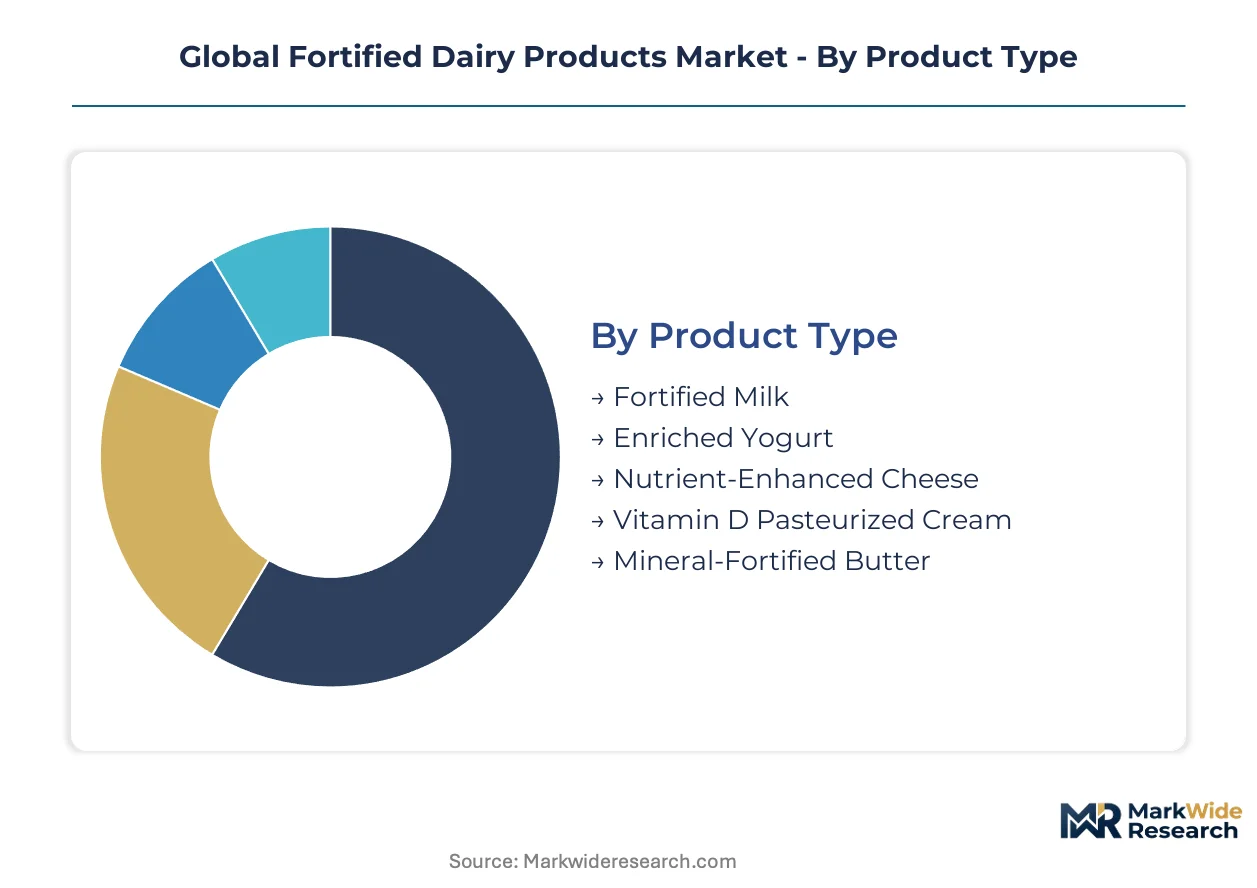
- Fortified Milk:This segment includes cow's milk, goat's milk, and plant-based alternatives enhanced with essential vitamins and minerals. Fortified milk dominates household consumption in North America due to its versatility in cooking and direct consumption.
- Enriched Yogurt:Yogurts infused with probiotics, vitamins, or minerals address specific dietary needs and taste preferences. Demand for enriched yogurt is expanding quickly in European markets, driven by consumer interest in gut health and convenient, nutrient-dense snacks.
- Nutrient-Enhanced Cheese:Cheeses fortified with calcium or Vitamin D offer a savory option for nutrient intake. This category targets consumers seeking functional foods within their regular diet.
- Vitamin D Pasteurized Cream:Cream products supplemented with Vitamin D provide an additional source of this essential nutrient. Manufacturers focus on culinary applications for this segment.
- Mineral-Fortified Butter:Butter products enhanced with minerals serve as an alternative for consumers seeking fortified dietary fats. This segment addresses specific nutritional gaps in traditional diets.
Volume sits with Fortified Milk; growth tilts toward Enriched Yogurt.
Fortifying Nutrient:
The functional impact of specific fortifying nutrients guides product development and consumer choice within this market.
- Probiotics:Live microorganisms added to dairy products support gut health and immune function. Danone actively promotes probiotic-fortified yogurts across global markets, leveraging scientific research for product claims.
- Omega-3 Fatty Acids:These essential fatty acids, often derived from marine sources, support brain and heart health. Advances in microencapsulation technology enable stable integration of Omega-3s into dairy products, expanding their market reach in countries like Japan.
- Calcium:This mineral is crucial for bone health and is a common fortification in milk and yogurt. Calcium fortification addresses widespread dietary deficiencies, particularly in aging populations.
- Vitamin A:Fortification with Vitamin A targets vision health and immune support. Public health initiatives in regions like Southeast Asia often emphasize Vitamin A supplementation.
- Vitamin D:Essential for calcium absorption and bone density, Vitamin D is frequently added to dairy products. Consumers in northern climates show higher demand for Vitamin D fortified products.
The largest share of revenue accrues to Calcium-fortified products; Probiotics are gaining share fastest.
Application:
The specific health needs and life stages of consumers drive demand across different application segments.
- Infant Nutrition:Formulations for infants require stringent regulatory compliance and precise nutrient profiles to support early development. Products for infant nutrition command premium pricing, especially in markets like China, due to high parental investment in child health.
- Geriatric Nutrition:Dairy products tailored for older adults focus on bone health, muscle maintenance, and cognitive function. The aging population in countries like Germany drives substantial demand for protein and Vitamin D-fortified dairy.
- Sports Nutrition:Athletes and active individuals seek dairy products fortified with protein for muscle recovery and energy. This segment often integrates with digital health apps for personalized recommendations.
- Weight Management:Fortified dairy items with added protein or fiber support satiety and metabolic health. Consumers in North America increasingly use these products as part of controlled dietary plans.
- Prenatal Supplements:Products designed for pregnant women often include folic acid, iron, and calcium. These specialized dairy products address the unique nutritional requirements during pregnancy.
Infant Nutrition holds the largest market share; Geriatric Nutrition exhibits the steepest expansion trajectory.
End User:
The distribution channels and purchasing power of various end-user groups shape market dynamics for fortified dairy products.
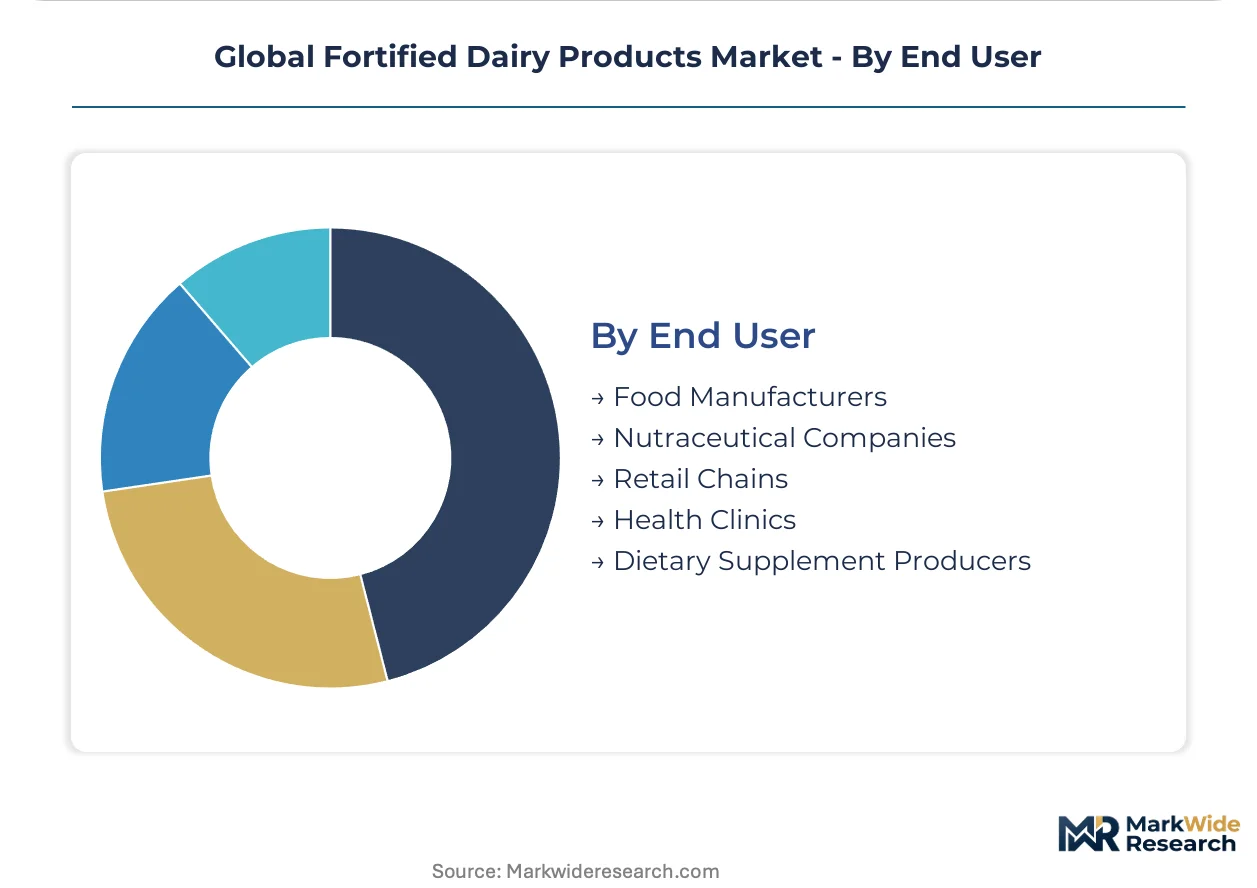
- Food Manufacturers:These entities incorporate fortified dairy ingredients into a wide range of consumer products. Large-scale food manufacturers are primary buyers of bulk fortified dairy components for further processing.
- Retail Chains:Supermarkets and grocery stores serve as the main distribution channels for direct-to-consumer fortified dairy products. Retail chains influence product visibility and consumer access across urban and rural areas.
- Nutraceutical Companies:These companies utilize fortified dairy components in their health supplements and functional food lines. Nutraceutical firms often require specific, high-purity fortification ingredients.
- Health Clinics:Medical institutions and dietitians recommend fortified dairy products for patients with specific nutritional deficiencies. Health clinics act as trusted sources for dietary advice.
- Dietary Supplement Producers:Producers of dietary supplements integrate fortified dairy ingredients into their formulations. This segment focuses on concentrated nutrient delivery.
Food Manufacturers represent the largest end-user segment; Retail Chains drive significant consumer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fortified dairy products market exhibits a significant divide between production capabilities and consumer demand across various regions. While some nations lead in ingredient sourcing and processing, others drive substantial consumption due to demographic shifts and health awareness. This dynamic influences investment and product distribution strategies globally.
China
Demand for fortified dairy products in China is driven by national health campaigns and high parental investment in infant nutrition. The Chinese government's health and wellness initiatives actively promote nutrient-rich diets for all age groups. Cities like Beijing and Shanghai demonstrate robust consumption, with manufacturers developing specialized formulations for urban consumers.
India
India's demand for fortified dairy stems from public health initiatives addressing widespread nutritional deficiencies, particularly among children and women. The FSSAI's standards for fortified foods directly influence product composition and market entry for manufacturers. Mumbai and Delhi serve as key distribution hubs, facilitating market penetration for enriched milk and yogurt.
United States
Consumer preferences in the United States favor fortified milk and enriched yogurts, driven by a focus on bone health and gut wellness. The U.S. FDA governs permissible nutrient levels and health claims on packaging, ensuring product efficacy. California and New York show high adoption rates, with innovation in personalized nutrition platforms gaining traction.
Germany
An aging population in Germany fuels the demand for geriatric nutrition products, particularly dairy fortified with protein and Vitamin D. The European Food Safety Authority (EFSA) sets stringent requirements for health claims, impacting product development across the EU. Bavaria and North Rhine-Westphalia house significant dairy processing facilities, focusing on organic and naturally fortified options.
Japan
Health-conscious consumers in Japan seek dairy products fortified with Omega-3 fatty acids and probiotics for brain and gut health benefits. Advances in microencapsulation technology enable stable integration of sensitive nutrients into dairy items, expanding product possibilities. Tokyo and Osaka are centers for innovation, where manufacturers introduce novel fortified dairy beverages.
Global Fortified Dairy Products Market Key Industry Players
Top-tier vendors anchor the global fortified dairy products market, while numerous regional and niche players cater to specific local demands. The market structure exhibits a tiered consolidation, with large multinational corporations holding significant shares alongside specialized ingredient suppliers. Strategic archetypes include diversified food conglomerates, dairy specialists, and nutraceutical-focused firms. Competitive moves frequently involve portfolio diversification and strategic partnerships to expand geographic reach.
Specialists in dairy and nutrition, such as Nestlé and Danone, exemplify multinational players with extensive research and development capabilities. These global entities leverage their broad market presence to introduce a wide array of fortified dairy products, spanning from advanced infant formulas to innovative probiotic yogurts. Their strategies often involve significant investment in scientific validation to meet stringent regulatory requirements. Arla Foods, a European dairy cooperative, represents another key player, maintaining its market position through a strong focus on organic and naturally fortified milk products across Europe. This cooperative model emphasizes sustainable sourcing and clean-label formulations, appealing to a distinct consumer segment.
| Leading Market Players |
|---|
| Arla Foods |
| China Mengniu Dairy Company |
| Nestlé |
| FrieslandCampina |
| Yili Group |
| Danone |
| Fonterra Co-operative Group |
| GCMMF |
| General Mills |
| Others |
Cost & Logistics Intelligence
Food manufacturers, as bulk buyers of fortified dairy ingredients, primarily engage in contract-based pricing for long-term supply agreements. This structure provides cost predictability for large-scale production.
Pricing Analysis
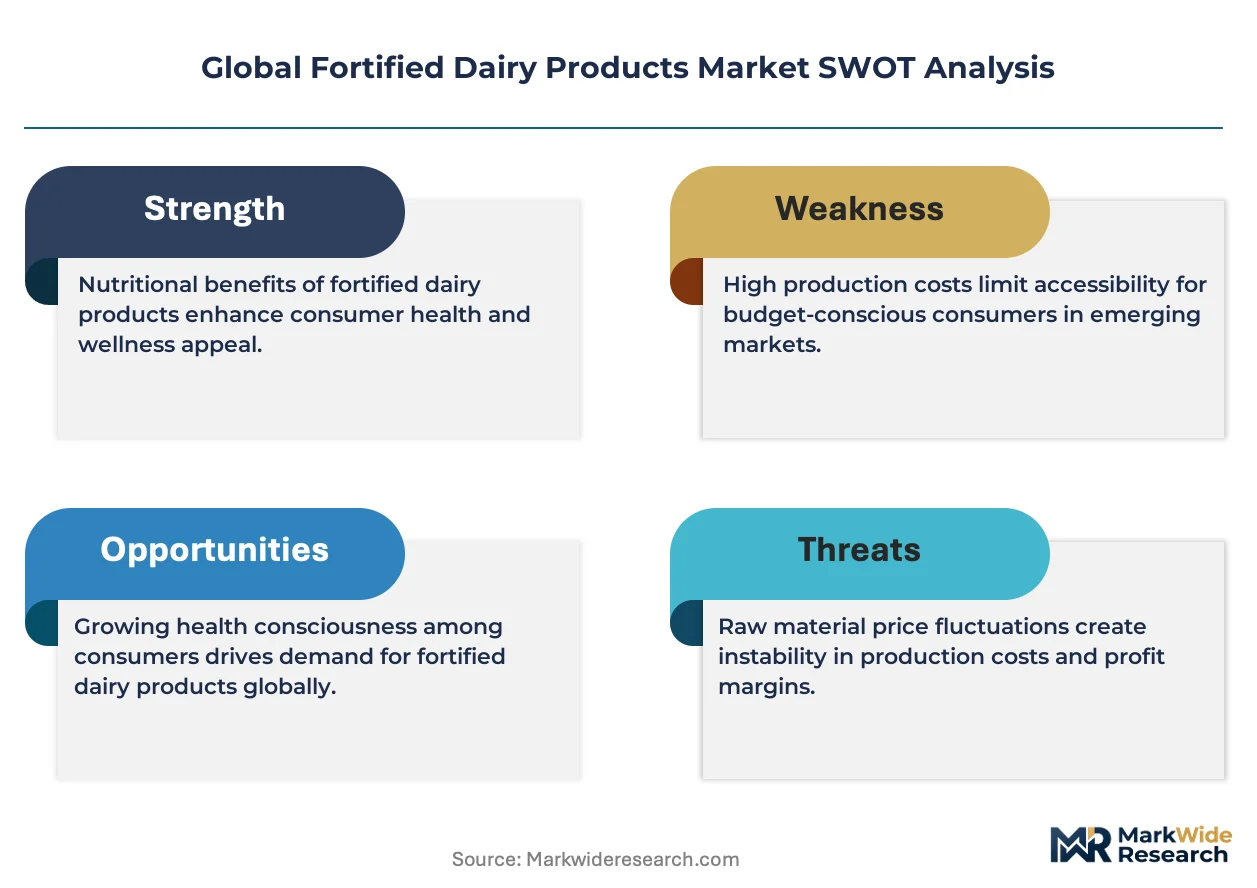
Margin compression in fortified dairy products intensifies as ingredient cost volatility for specialized micronutrients impacts profitability. The dominant pricing model is a hybrid of value-based and tiered premium-mid-economy differentiation. Price differentiation stems from certification levels, such as organic or non-GMO, and specific health claims validated by regulatory bodies. Infant nutrition and medical foods segments exhibit lower price sensitivity due to stringent formulation requirements, while general fortified milk consumers are highly price-sensitive.
Supply Chain Analysis
Fortifying ingredient supply relies heavily on specialized chemical producers in China, India, and Europe for vitamins and minerals. Marine-derived Omega-3s source from Nordic countries, while patented probiotic strains often originate from Western European biotech firms. A key structural risk involves commodity price volatility for these high-purity micronutrients. Distribution runs through established retail chains and direct-to-consumer channels, connecting manufacturers to end-users globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fortified dairy market is consolidating, driven by mounting regulatory pressure for scientific validation of health claims. This environment favors well-resourced players capable of significant R&D investment.
For Market Incumbents: Anchor market leadership by investing heavily in clinical trials to substantiate health claims, particularly for infant and geriatric nutrition segments. Expand production capacity in emerging markets like Southeast Asia to capture rising demand, leveraging established distribution networks. This defends against threats from new plant-based alternatives and strengthens brand trust through rigorous scientific validation.
For New Entrants and Emerging Players: Direct-to-consumer (D2C) subscription services offer a penetrable segment for personalized probiotic yogurts or cognitive health drinks. Target urban consumers in North America and Western Europe with highly specialized formulations that integrate with digital health apps for tailored dietary advice. Focus on clean-label, plant-based fortified products, using agile marketing to highlight specific, scientifically-backed benefits to health-conscious flexitarians.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to integrate specialized ingredient technologies or expand into high-growth application segments. Long-term viability over the next 5-10 years depends on securing access to patented probiotic strains and microencapsulation expertise. Target mid-sized nutraceutical firms with strong R&D pipelines. Increased M&A activity in plant-based fortification signals market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Substantiates health claims for premium pricing and regulatory compliance. |
| Plant-Based Portfolio Diversification | Captures flexitarian and vegan consumer segments with enriched non-dairy options. |
| Digital Health Platform Integration | Connects personalized nutrition advice with product offerings for tailored solutions. |
| Emerging Market Distribution Expansion | Penetrates untapped demand in Southeast Asia and Latin America. |
| Microencapsulation Technology Adoption | Improves stability and bioavailability of sensitive fortifying nutrients. |
Research Approach
Independent corroboration across industry reports, academic literature, and regulatory filings underwrites the qualitative findings and quantitative projections. Primary interviews engaged R&D directors, procurement managers, brand strategists, and food safety experts across the value chain. Secondary data included EFSA scientific opinions, FDA guidance, FSSAI standards, and company annual reports. Both bottom-up market sizing and top-down revenue validation were employed.
Rate-of-change decomposition analyzes historical growth drivers and projects future market trajectories across the analysis window. The model segments the market by product type, fortifying nutrient, application, end-user, and specific life-stage nutrition. Compound Annual Growth Rates were derived from a weighted average of segment-specific growth rates. Key inputs include demographic shifts and ingredient technology advancements.
The model holds under current regulatory frameworks and consumer preference trends; deviation in global economic stability or dietary guideline shifts would alter market dynamics. Forecasts reflect documented assumptions on raw material availability and technological adoption. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Recombined Milk Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Milk Mineral Market
Dairy Products
Cheese Packaging Market
Dairy Products
China Dairy Market
Dairy Products
United States Casein Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Butter Powder Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
Dairy Foods Market
Dairy Products
Sweet Whey Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Goat Milk Market