
 Rally Sport Riding Gear Market | 2026-2036
Rally Sport Riding Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Rally Sport Riding Gear Market Analytics
Amateur rally schools and off-road training academies are rebalancing the end-use mix away from pure professional racing. Alpinestars SPA leverages its Italian manufacturing heritage to sustain premium positioning across European distribution channels. Bell Helmets anchors the protective headgear segment through deep relationships with North American racing federations. Klim Technical Riding Gear differentiates via waterproof-breathable membrane integration for variable-terrain endurance events.
Rally sport riding gear encompasses purpose-built protective apparel engineered for motorcycle navigation across unpaved surfaces, gravel stages, and desert terrain, typically incorporating CE-rated armor inserts, abrasion-resistant chassis materials, and ventilation systems calibrated for sustained high-exertion riding. The primary commercial purpose centers on reducing rider injury severity during high-speed off-road incidents while maintaining mobility and climate control across multi-day competitive stages. Leather dominates the material segment for professional racing applications where slide abrasion resistance is paramount, while textile and waterproof laminates capture growth in adventure-touring crossover demand. Impact protection features command premium positioning as integrated back protectors and limb armor become standard rather than optional specifications across amateur and professional end-user categories.
CE marking requirements under the EU's Personal Protective Equipment Regulation shape product design and market access for European distribution, while the US Consumer Product Safety Commission oversees baseline safety claims for helmets sold domestically. The Federal Motor Vehicle Safety Standard 218 administered by the National Highway Traffic Safety Administration mandates minimum impact absorption for helmets, creating a dual-compliance burden for manufacturers serving transatlantic markets. Stakeholders must monitor evolving harmonization between European EN 1621 impact standards and emerging testing protocols in Asian markets to anticipate certification investment requirements.
Market Dynamics
The rally sport riding gear sector is experiencing structural compression as CE certification standards under the EU's Personal Protective Equipment Regulation force simultaneous redesign of legacy product lines and inventory cycles. This regulatory tightening is synchronizing with amateur rider expansion across North American and European training academies, creating dual pressure on manufacturers to serve divergent performance tiers with unified product architectures.
Growth Catalysts
- Amateur Training Infrastructure:Off-road riding academies in the United States and Germany are generating sustained replacement demand as novice riders progress through certification levels. Structured curriculum programs mandate protective equipment upgrades at defined skill milestones.
- CE Marking Harmonization:The EU's EN 1621 impact standards are converging with emerging Asian testing protocols, reducing duplicate certification costs for manufacturers serving transatlantic distribution networks.
- Waterproof-Breathable Membranes:Adventure-touring crossover applications are absorbing technical textile innovations originally developed for endurance motorsport, expanding addressable use cases beyond pure competition.
Market Restraints
- Leather Input Volatility:Premium-grade cowhide supply concentrates in Italian and Argentinian tanneries, exposing cost structures to livestock commodity cycles and environmental regulation shifts in source regions.
- Dual-Compliance Burden:Manufacturers serving both European and North American markets must satisfy divergent helmet testing protocols—ECE 22.06 and FMVSS 218—without volume scale to amortize separate certification investments.
- Technical Textile Substitution:Abrasion-resistant synthetic chassis materials are displacing leather in amateur segments, compressing margin premiums for traditional material suppliers.
Strategic Opportunities
- Indian Amateur Motorsport:The Federation of Motor Sports Clubs of India is expanding rally-raid event calendars, creating first-mover positioning for CE-certified gear distributors in an underpenetrated enforcement environment.
- Integrated Sensor Platforms:Convergence of impact telemetry systems with protective armor inserts enables post-incident data capture for insurance and training optimization.
- Direct-to-Rider Digital Channels:Brand-owned e-commerce platforms are bypassing traditional powersports retailers, capturing full margin on replacement-part sales and fit-customization services.
Industry Challenges
- Pattern-Making Talent Scarcity:Specialized knowledge of motorcycle-specific ergonomic pattern development is concentrating among aging European technical staff, constraining new product velocity.
- Multi-Standard Certification Timelines:Simultaneous pursuit of CE marking, SNELL, and FIM homologation extends product development cycles by 8-14 months, delaying revenue recognition on redesigned platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rally Sport Riding Gear Market |
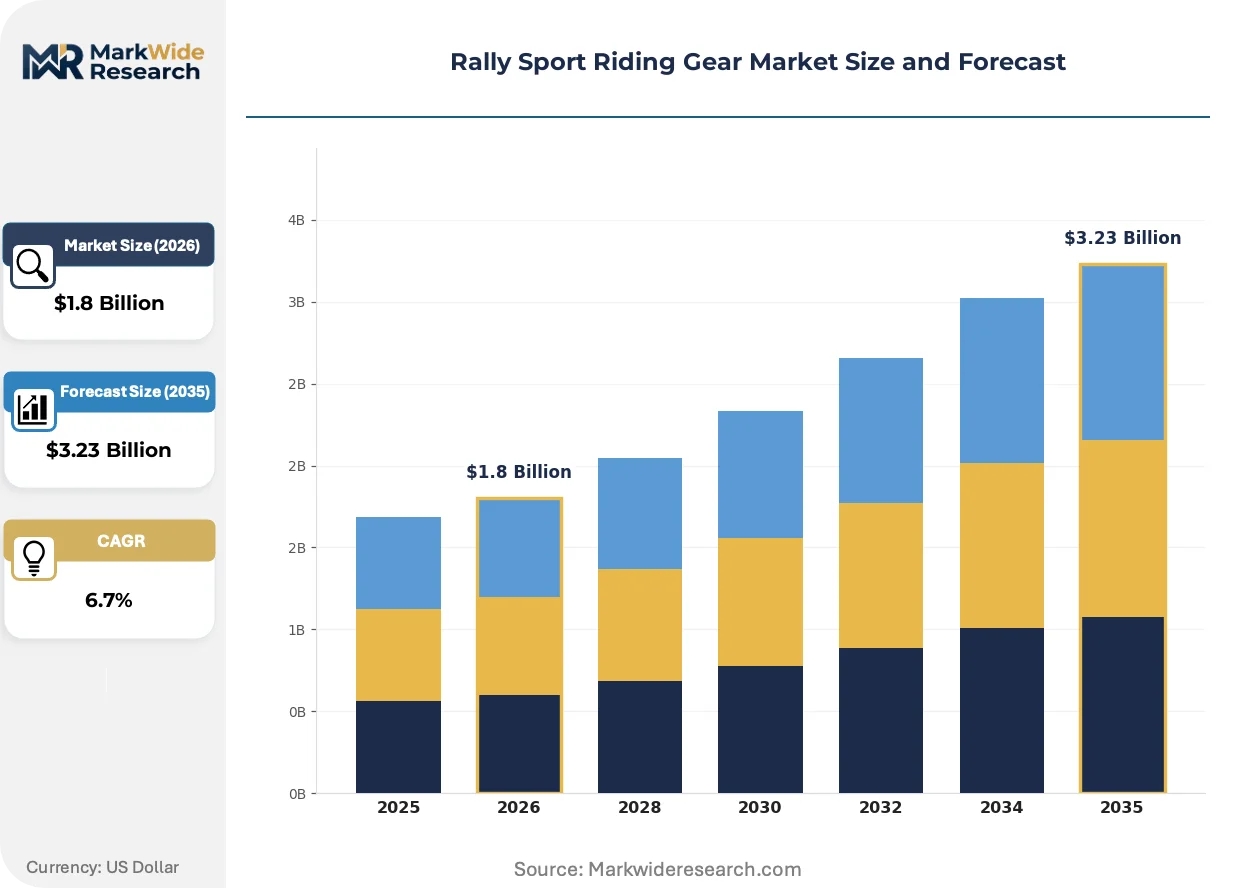
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Pants, Gloves, Footwear Material: Leather, Textile, Mesh, Waterproof Feature: Impact Protection, Breathability, Waterproofing, Visibility End User: Amateur Riders, Professional Racers, Track Day Participants, Enthusiasts |
| Companies Covered | Alpinestars SPA, AGVSport, FLY Racing Jackets, Klim Technical Riding Gear, Kushitani Hamamatsu, Ride Icon, Spartan Pro Gear Co., HKM Sports Equipment GmbH, Bell Helmets, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rally Sport Riding Gear Market Evolving Landscape
Active unification of disparate protective technologies is compressing the traditional segmentation between professional racing and amateur touring equipment. Manufacturers are responding by engineering modular chassis systems that adapt armor density and ventilation profiles across use cases without full product replacement.
Smart armor systems incorporating non-Newtonian shear-thickening polymers are unifying impact absorption across low-speed training falls and high-speed race incidents. Amateur riders at German and Italian training centers are specifying these materials at accelerating rates. The technology is unifying previously separate product lines into single SKUs, reducing inventory complexity for distributors serving mixed rider populations.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy durable water repellent chemistries from textile laminates used in rally gear. European manufacturers are reformulating membrane bonding agents and surface treatments to maintain breathability performance. The KBA in Germany is scrutinizing substitute chemistries for skin-contact safety, delaying product launches for brands dependent on German market entry.
Subscription-based gear refresh programs are displacing outright purchase patterns among amateur riders enrolled in North American rally schools. Riders pay monthly access fees for equipment that is inspected, sanitized, and component-upgraded between training sessions. This model concentrates most visibly in California and Colorado markets where seasonal riding patterns create predictable turnover cycles.
Rally Sport Riding Gear Market Segmentation
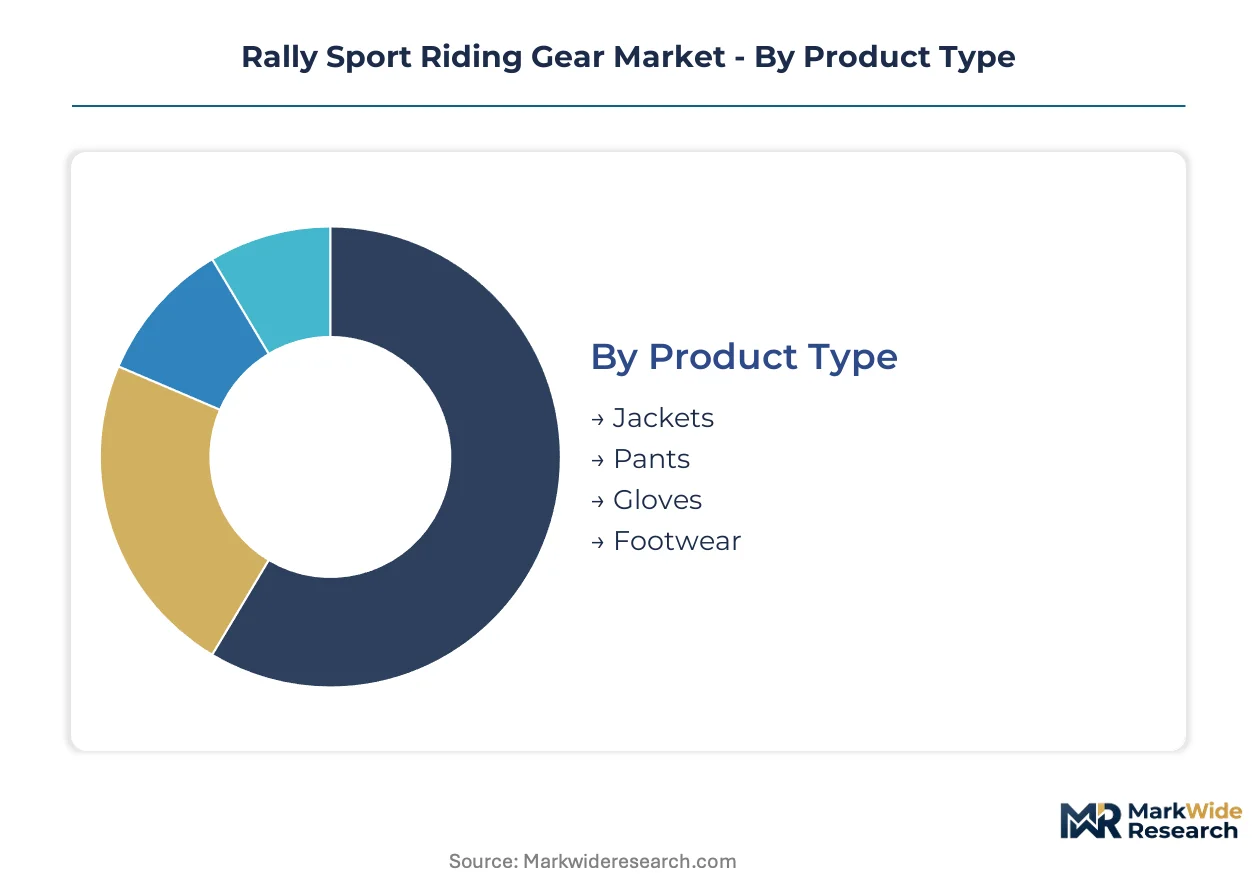
Rally sport riding gear segmentation reflects divergent performance requirements across amateur training circuits and professional competition tiers. Manufacturers engineer distinct product architectures for each segment, with material selection and armor density calibrated to specific incident severity profiles and climate exposure durations.
Product Type:
Supply concentration in Italian and Portuguese cut-and-sew operations favors integrated jacket-pant systems over standalone accessories, compressing lead times for full-ensemble orders while fragmenting component sourcing.
- Jackets:CE-rated back protectors and shoulder armor integrate into abrasion-resistant chassis materials, with ventilation panels mapped to high-perspiration zones. Demand concentrates in Germany and Italy where training academies mandate certified upper-body protection for curriculum progression.
- Pants:Knee sliders and hip armor attach to reinforced seat panels engineered for prolonged saddle contact during multi-day endurance stages. Professional teams in the United States specify integrated hip protection as standard issue, eliminating aftermarket retrofit cycles.
- Gloves:Knuckle armor and palm reinforcement balance dexterity with impact absorption for handlebar control precision.
- Footwear:Ankle bracing and sole rigidity protect against peg strikes and terrain irregularities while preserving shift-lever feedback sensitivity.
Today's leader: Jackets. Tomorrow's challenger: Pants.
Material:
Cost tier differentiation separates professional racing applications from amateur touring crossover demand, with raw material selection driving 40-60% of finished goods pricing.
- Leather:Full-grain cowhide from Argentinian and Italian tanneries delivers unmatched slide abrasion resistance at speed. Professional racers in Germany and the United States specify leather exclusively for FIM-homologated events where textile alternatives fail certification.
- Textile:High-tenacity nylon and polyester weaves incorporate aramid reinforcement zones at impact points, capturing amateur riders seeking lighter weight and lower maintenance than leather requires.
- Mesh:Open-weave construction maximizes airflow for hot-climate training environments, with armor pockets maintaining protective coverage.
- Waterproof:Laminated membranes bond to textile substrates for variable-terrain endurance events where precipitation exposure is probable.
Leather commands premium positioning. Textile is climbing the fastest.
Feature:
Application-specific engineering prioritizes protection density for competitive stages versus climate adaptability for adventure-touring crossover use.
- Impact Protection:CE EN 1621-1 and EN 1621-2 certified armor inserts absorb kinetic energy across limb and torso contact points. Mandatory specification in European markets under PPE Regulation drives universal integration across price tiers.
- Breathability:Moisture-vapor transmission rates determine comfort during high-exertion riding, with membrane technologies originally developed for mountaineering applications migrating into motorsport laminates.
- Waterproofing:Hydrostatic head ratings and seam-taping integrity sustain dry conditions during multi-hour exposure to precipitation.
- Visibility:Retroreflective paneling and high-contrast colorways enhance conspicuity for road-legal transit between off-road stages.
Impact protection is non-negotiable. Breathability is gaining specification priority.
End User:
Customer type fragmentation creates parallel demand streams with divergent replacement cycles and brand loyalty patterns.
- Amateur Riders:Structured training programs at German and Italian riding academies generate predictable upgrade demand as riders progress through certification levels. Equipment replacement correlates with skill milestone achievement rather than wear-based failure.
- Professional Racers:Factory team contracts specify season-based gear refresh protocols, with crash damage and sponsorship visibility requirements accelerating turnover beyond functional lifespan.
- Track Day Participants:Occasional high-speed circuit access drives rental and entry-level purchase patterns distinct from dedicated rally competition.
- Enthusiasts:Discretionary purchasing responds to brand narrative and aesthetic positioning rather than mandatory certification requirements.
Amateur Riders anchor volume. Professional Racers anchor margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with lighter certification burdens while maintaining European market access through modular assembly strategies. This regulatory arbitrage compresses compliance costs without sacrificing CE marking eligibility for finished goods.
Germany
The KBA enforces stringent skin-contact safety protocols for membrane bonding agents, delaying launches for brands dependent on German market entry. Amateur training academies in Bavaria and Baden-Württemberg mandate certified protective gear for curriculum progression, generating predictable replacement cycles. Manufacturing clusters concentrate around Munich and Stuttgart, where technical textile R&D facilities serve adjacent motorsport supply chains.
United States
NHTSA's FMVSS 218 helmet standards create dual-compliance burdens alongside European ECE 22.06 protocols. Off-road riding academies in California and Colorado are pioneering subscription-based gear refresh programs that displace outright purchase patterns. Bell Helmets anchors protective headgear supply through relationships with North American racing federations.
Italy
CE marking requirements under the EU's Personal Protective Equipment Regulation shape product design for European distribution. Alpinestars SPA leverages Italian manufacturing heritage to sustain premium positioning across domestic and export channels. Cut-and-sew operations concentrate in Tuscany and Veneto, favoring integrated jacket-pant systems over fragmented component sourcing.
India
The Federation of Motor Sports Clubs of India is expanding rally-raid event calendars, creating first-mover positioning for CE-certified gear distributors. BIS standards for protective equipment remain less stringent than European equivalents, attracting assembly operations seeking cost advantages. Manufacturing activity clusters around Delhi-NCR and Maharashtra as domestic amateur participation accelerates.
Argentina
Premium-grade cowhide supply concentrates in Argentinian tanneries, exposing cost structures to livestock commodity cycles. Leather input volatility affects professional racing applications where slide abrasion resistance is paramount. Industrial processing facilities in Buenos Aires province supply raw material to European and North American finished goods manufacturers.
Rally Sport Riding Gear Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among heritage European houses and volume production migrating to Asian assembly operations. The vendor base organizes around three strategic archetypes: vertically integrated heritage brands controlling full supply chains, technical specialists leveraging membrane and armor innovations, and contract manufacturers serving private-label demand. Consolidation pressure is intensifying as dual-compliance burdens favor scaled players capable of amortizing certification investments across multiple markets. Geographic expansion and technology licensing represent the dominant competitive moves as firms seek to bypass tariff barriers and accelerate product development cycles.
Within the heritage-brand tier, Alpinestars SPA and Bell Helmets occupy positions defined by motorsport federation relationships and geographic anchoring in Italian and North American markets respectively. Klim Technical Riding Gear exemplifies the technical-specialist archetype through waterproof-breathable membrane integration. Among Asian-based manufacturers, Kushitani Hamamatsu represents precision-cut-and-sew capabilities serving both domestic Japanese demand and export markets. These three companies illustrate how competitive positioning stratifies across brand equity, technical differentiation, and manufacturing scale vectors.
| Leading Market Players |
|---|
| Alpinestars SPA |
| AGVSport |
| FLY Racing Jackets |
| Klim Technical Riding Gear |
| Kushitani Hamamatsu |
| Ride Icon |
| Spartan Pro Gear Co. |
| HKM Sports Equipment GmbH |
| Bell Helmets |
| Others |
Value Network & Pricing Analysis
Waterproof-breathable membrane integration into textile laminates is simultaneously elevating material costs and concentrating supplier relationships around German and Japanese chemical specialists, reshaping both finished goods pricing and procurement risk profiles for rally gear manufacturers.
Pricing Analysis
Distributor margin layers absorb 35-45% of ex-factory pricing before retail markup, compressing manufacturer returns on mid-tier textile products. Three-tier pricing structure across premium, standard, and economy levels separates CE Level 2 armor configurations from Level 1 and uncertified alternatives. Price differentiation hinges on certification grade and brand heritage, with Italian heritage names commanding 40-60% premiums over private-label competitors. Pricing pressure stems from technical textile substitution in amateur segments, eroding leather's margin premium. Amateur training academy riders exhibit highest price sensitivity, while factory-sponsored professional racers show minimal elasticity.
Supply Chain Analysis
Direct-to-rider digital channels handle replacement-part demand and fit-customization services, bypassing traditional powersports retailers. Geographic supply concentration centers on Italy, Portugal, and Vietnam for cut-and-sew operations, with premium cowhide sourcing anchored in Argentina. Raw material dependencies include aramid fibers, polyurethane membranes, and CE-certified armor inserts from specialized European suppliers. Supply chain risk manifests in single-source vulnerability for shear-thickening polymer armor technologies. Distribution runs through motorsport federation partnerships, training academy procurement contracts, and brand-owned e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through technical textile substitution displacing leather in volume tiers, while premium positioning tightens around integrated sensor platforms and CE Level 2 armor configurations.
For Market Incumbents: Deploy backward integration into membrane bonding and armor insert manufacturing to capture margin currently flowing to German and Japanese chemical suppliers. Consolidate pattern-making talent through acquisition of specialized Italian technical studios before generational knowledge loss accelerates. Threats include emerging Asian contract manufacturers achieving CE certification parity and REACH-driven reformulation costs disrupting established textile laminates. For New Entrants and Emerging Players: BIS standards in India open a window for CE-certified gear distribution before enforcement harmonization with European PPE Regulation tightens. Target Indian amateur motorsport expansion through direct relationships with Federation of Motor Sports Clubs of India event organizers. White-space exists in subscription-based gear refresh programs for North American training academies, replicating California and Colorado pilot models. Go-to-market through riding school curriculum partnerships rather than traditional retail placement. For Investors and Strategic Acquirers: Valuations sit cheapest among precision cut-and-sew contract manufacturers in Vietnam and Portugal lacking brand equity but holding technical certification capabilities. Long-term viability favors players controlling both CE marking expertise and direct-to-rider digital channels. Acquisition target archetype: mid-tier technical specialists with waterproof-breathable membrane integration IP and established training academy relationships. Watch for Indian regulatory harmonization with EN 1621 standards as inflection signal for first-mover positioning value.| Strategic Initiative | Industry Significance |
|---|---|
| CE Level 2 Armor Integration | Mandatory PPE Regulation compliance secures European market access and premium pricing tiers. |
| Direct-to-Rider E-Commerce Platform | Bypasses distributor margin capture and enables fit-customization services for amateur segments. |
| Shear-Thickening Polymer Armor Development | Unifies professional and amateur product lines into single SKUs, reducing inventory complexity. |
| Indian Market Entry Partnership | Federation of Motor Sports Clubs of India calendar expansion creates first-mover positioning before BIS harmonization. |
| Subscription Gear Refresh Program | California and Colorado pilot models demonstrate predictable revenue streams from training academy enrollment. |
Research Methodology
Direct dialogue with product development directors at heritage European brands, procurement leads at North American training academies, technical textile R&D managers, and motorsport federation equipment officers grounded qualitative findings. Secondary validation drew from CE marking documentation, NHTSA FMVSS 218 filings, ECHA REACH substance restriction updates, and customs trade data for protective apparel categories. Bottom-up demand modeling across amateur and professional rider segments triangulated against top-down market sizing from motorsport participation statistics and equipment replacement cycle analysis.
Segmented outputs across product type, material composition, protection level, and end-user category fed into growth rate derivation across the projection horizon. The analytical framework incorporated armor certification tier migration, training academy enrollment trajectories, and membrane technology cost curves as industry-specific forecast inputs. CAGRs reflect convergence of replacement demand elasticity, regulatory compliance investment cycles, and amateur participation growth patterns.
Revisions become necessary when REACH substance restrictions expand beyond per- and polyfluoroalkyl substances, when Indian BIS standards harmonize with EN 1621 protocols, or when leather commodity cycles disrupt cost structures. Forecasts reflect documented assumptions regarding training academy expansion rates and CE marking enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Cycling Sunglasses Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Recreational Rowing Boats Market