
 North America Stand-Up Paddleboard Market | 2026-2036
North America Stand-Up Paddleboard Market Size, Share, and Industry Trends Forecast 2026-2036
North America Stand-Up Paddleboard Market Analytics
Recreational users is unwinding from casual weekend adopters toward dedicated fitness practitioners seeking full-body water workouts. BOTE leverages its direct-to-consumer channel control to capture premium positioning in the inflatable segment. ISLE Surf & SUP anchors its West Coast manufacturing footprint to serve California's dense coastal population. Tower Paddle Boards competes aggressively on price through its online retail model.
Stand-up paddleboards are buoyant watercraft typically measuring 9 to 14 feet in length, constructed from layered composites of PVC, epoxy, or fiberglass over foam cores, propelled by a single-bladed paddle while the rider stands upright. Their primary purpose spans recreational flatwater cruising, ocean surf riding, racing, and fitness training across lakes, rivers, and coastal marine environments. Inflatable boards lead volume due to transport convenience and storage efficiency in urban households. Hardboard epoxy construction commands the premium tier for performance-oriented competitive athletes and dedicated touring users. Rental services represent the fastest-growing end-user channel as coastal tourism operators expand fleet investments.
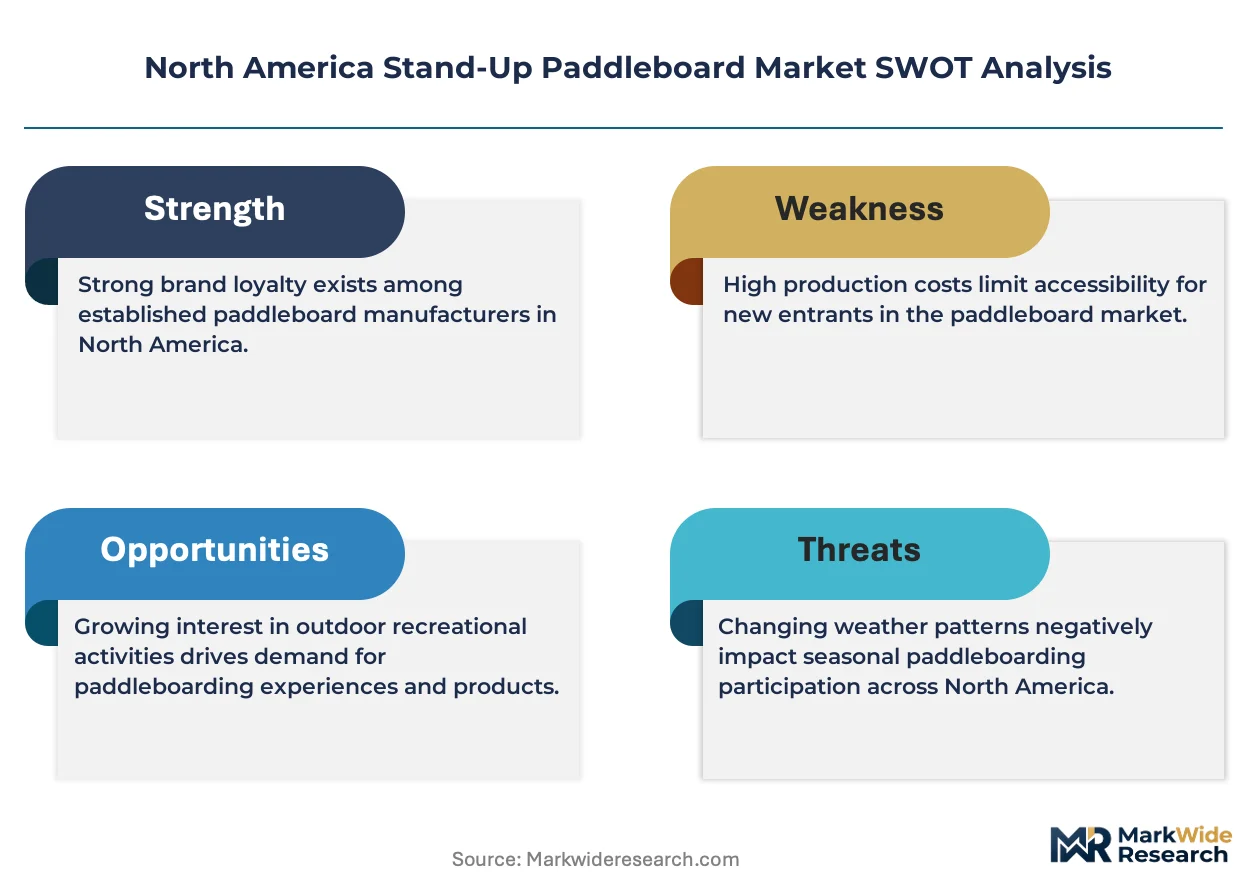
The US Coast Guard regulates paddleboard safety equipment requirements under recreational vessel guidelines, while the Consumer Product Safety Commission monitors material compliance and product recalls. California's State Water Resources Control Board imposes additional environmental standards on manufacturing effluent that affect West Coast production economics. Stakeholders must monitor evolving state-level water access policies and Coast Guard equipment mandates that could reshape product specifications and distribution economics.
Market Dynamics
The US Coast Guard's updated recreational vessel classification standards are compressing product development timelines and forcing manufacturers to redesign safety equipment integration across inflatable and hardboard categories.
Growth Catalysts
- Fitness Application Expansion:Dedicated practitioners seeking full-body water workouts are displacing casual weekend adopters, creating sustained equipment replacement cycles in metropolitan coastal zones.
- California Environmental Standards:The State Water Resources Control Board's manufacturing effluent mandates are accelerating cleaner production technology adoption among West Coast fabricators.
- Rental Channel Concentration:Coastal tourism operators in Florida's Gulf Coast corridors are scaling fleet orders, driving volume procurement contracts with specialized distributors.
Market Restraints
- PVC Resin Price Volatility:Inflatable board manufacturers face margin compression from petrochemical feedstock fluctuations affecting layered composite costs.
- West Coast Production Concentration:California's dense manufacturing footprint creates geographic supply risk from regional environmental compliance disruptions.
- Hardboard Transport Economics:Epoxy construction's dimensional constraints limit distribution radius efficiency compared to rolled inflatable alternatives.
Strategic Opportunities
- Midwest Lake Access Expansion:Underpenetrated freshwater recreation zones in Michigan and Wisconsin offer first-mover positioning for rental network development.
- Direct-to-Consumer Channel Maturation:Digital-native purchasing patterns enable margin capture previously surrendered to specialty retail intermediaries.
- Federal Equipment Mandate Alignment:US Coast Guard personal flotation device requirements create specification standardization that favors scaled manufacturers with compliance infrastructure.
Industry Challenges
- Composite Technician Scarcity:Skilled laminators for epoxy and fiberglass construction command wage premiums that constrain production scaling.
- Multi-State Distribution Licensing:Watercraft registration variance across California, Florida, and Texas jurisdictions complicates unified go-to-market operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Stand-Up Paddleboard Market |
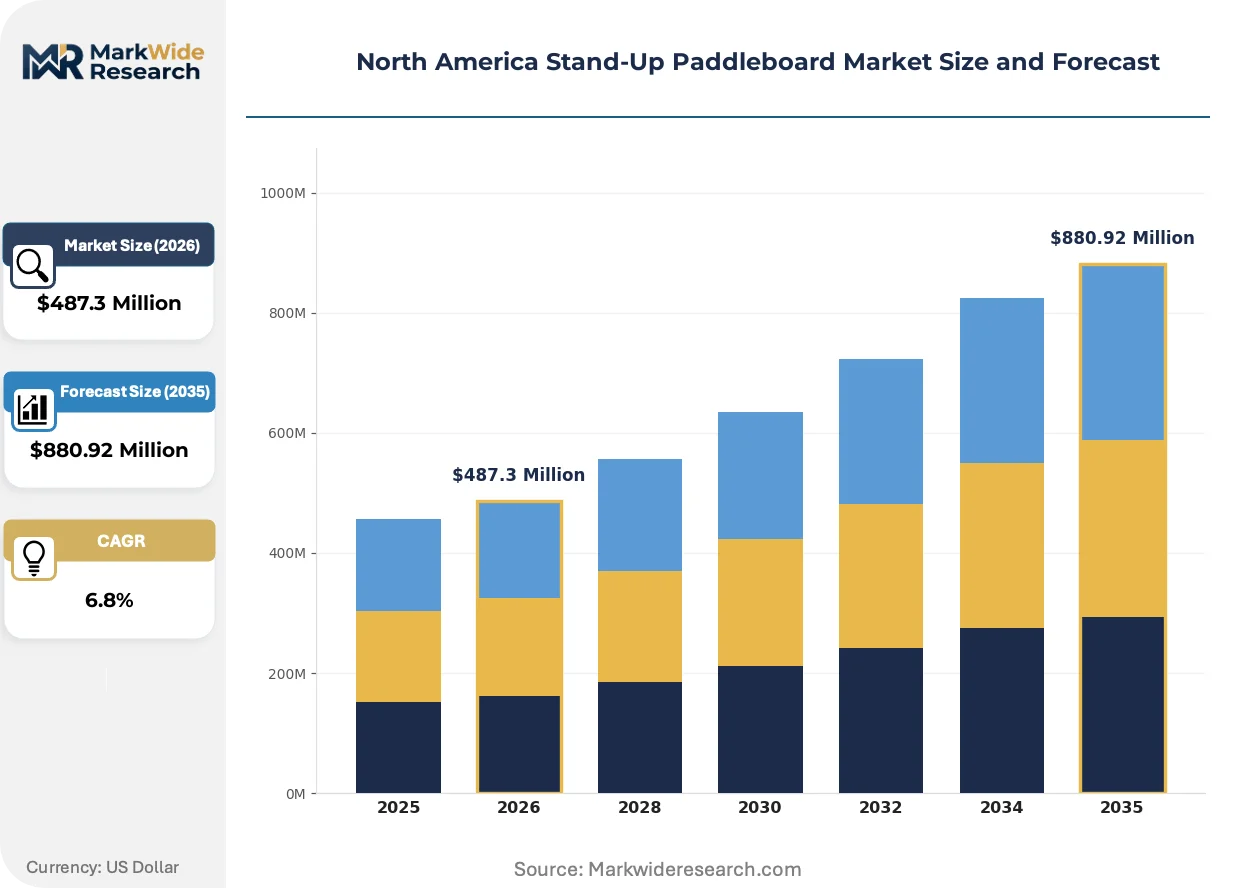
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardboard, Inflatable, Racing, Touring End User: Recreational Users, Fitness Enthusiasts, Competitive Athletes, Rental Services Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Direct Sales Material: Polyethylene, PVC, Epoxy, Fiberglass |
| Companies Covered | Boardworks, Yolo Board, BOTE, Tower Paddle Boards, ISLE Surf & SUP, SUP ATX, NRS, Thurso Surf, GILI Sports, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Stand-Up Paddleboard Market Evolving Landscape
Product architecture is splitting along performance-versus-convenience axes as rider segmentation sharpens, while regulatory pressure and channel evolution reshape how boards reach end users.
Drop-stitch inflatable construction is bifurcating the volume tier from premium hardboard demand. Recreational users prioritize transport convenience and urban storage efficiency, compressing hardboard share in entry-level segments. Performance athletes and dedicated touring riders sustain epoxy construction premiums for stiffness-to-weight ratios that inflatables cannot replicate.
The US Coast Guard's recreational vessel classification updates are mandating integrated leash attachments and visible identification markings. Manufacturers must retool molding processes and quality systems to satisfy equipment compliance verification. Florida and California rental fleets face accelerated retrofit obligations that concentrate procurement with suppliers demonstrating certification documentation.
Subscription-based equipment access is displacing outright ownership among intermittent users. Coastal tourism operators and urban fitness studios are bundling board access with instruction, capturing riders unwilling to commit to storage and transport logistics. This pattern concentrates in Southern California Bight metropolitan zones where apartment dwelling limits personal equipment retention.
North America Stand-Up Paddleboard Market Segmentation
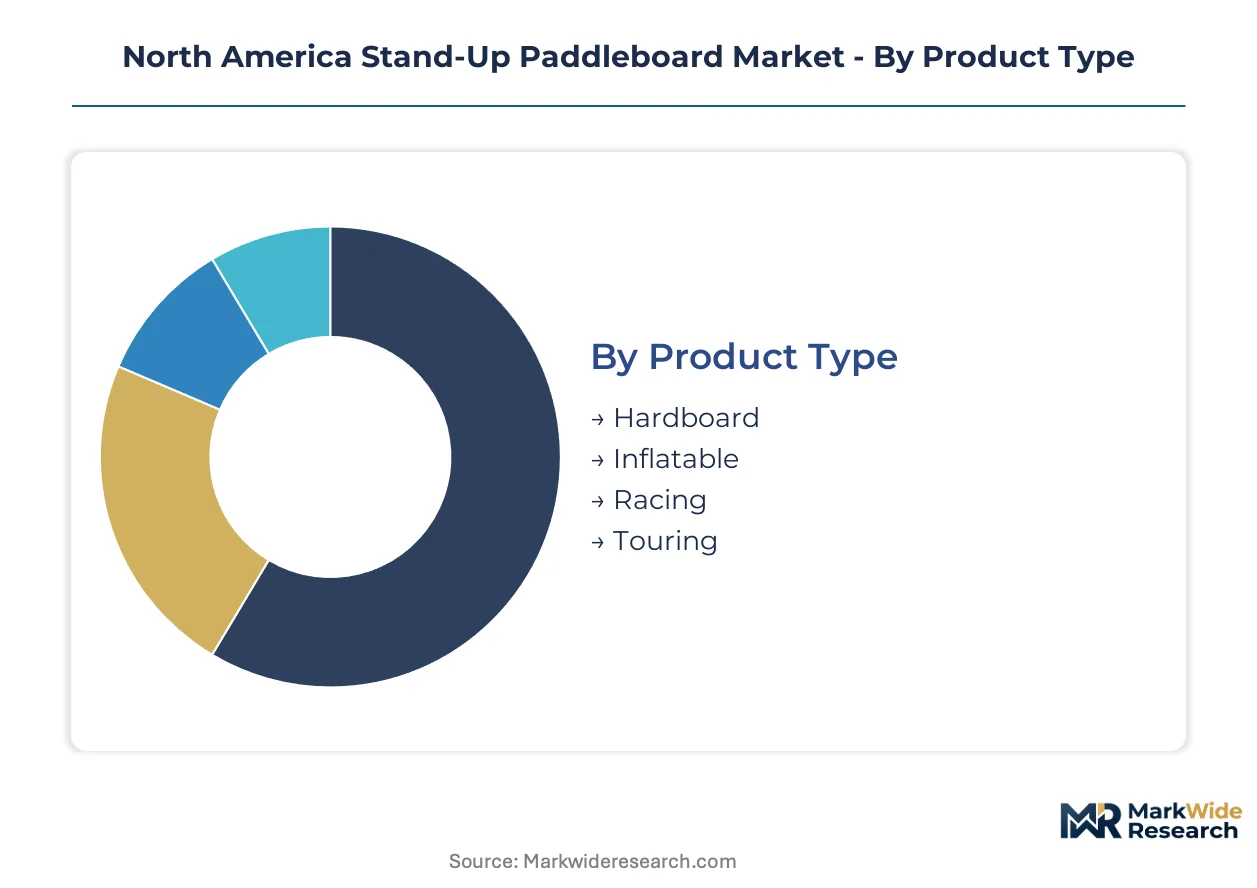
Segmentation in the North America stand-up paddleboard market reveals how substitution pressures reshape competitive dynamics across construction methods, user profiles, and procurement channels. Understanding these fault lines exposes where incumbent technologies face displacement risk and where new entrants can capture unmet demand.
Product Type:
Substitution pressure runs strongest against rigid construction as inflatable technology closes performance gaps while retaining logistics advantages.
- Hardboard:Epoxy and fiberglass composite construction delivers superior stiffness-to-weight ratios for wave riding and racing applications. Demand concentrates among competitive athletes in California's Southern California Bight and dedicated touring users along Florida's Gulf Coast where performance justifies transport complexity.
- Inflatable:Drop-stitch PVC construction with reinforced rail seams provides adequate rigidity for recreational flatwater and light surf use. Demand concentrates in metropolitan coastal zones where apartment storage constraints and vehicle transport limitations dominate purchase decisions.
- Racing:Narrow displacement hulls optimized for straight-line speed in flatwater and downwind conditions.
- Touring:Extended length designs with cargo tie-downs for multi-day expeditions and coastal exploration.
Inflatable retains volume leadership; racing holds the steepest expansion curve.
End User:
Customer type segmentation tracks how usage intensity drives equipment replacement cycles and channel preferences across the continent.
- Recreational Users:Casual weekend adopters seeking flatwater cruising and social paddling experiences. Demand concentrates in Michigan and Wisconsin lake districts where seasonal cabin culture supports equipment ownership.
- Fitness Enthusiasts:Dedicated practitioners integrating paddleboarding into structured workout regimens. Demand concentrates in Southern California Bight metropolitan zones where studio-based instruction and subscription access models displace outright ownership.
- Competitive Athletes:Racing specialists and surf competitors requiring FCS fin compatibility and custom rail profiles.
- Rental Services:Coastal tourism operators scaling fleet investments in Florida's Gulf Coast corridors.
Rental services command the steepest volume trajectory; fitness enthusiasts generate the highest per-unit margin capture.
Distribution Channel:
Channel segmentation exposes margin compression dynamics as digital-native purchasing patterns disintermediate traditional retail intermediaries.
- Online Retail:Direct-to-consumer platforms with video-guided assembly and warranty registration systems. Demand concentrates among price-sensitive entry-level buyers comparing specifications across multiple brands simultaneously.
- Direct Sales:Manufacturer-controlled channels capturing full margin stack and customer relationship data. Demand concentrates in premium inflatable and hardboard tiers where brand equity justifies bypassing wholesale discounts.
- Specialty Stores:Paddle-sports boutiques offering on-water demos and repair services.
- Sports Outlets:Big-box retailers with seasonal inventory rotation and bundled accessory promotions.
Online retail holds volume leadership; direct sales climbs fastest as brand owners invest in fulfillment infrastructure.
Material:
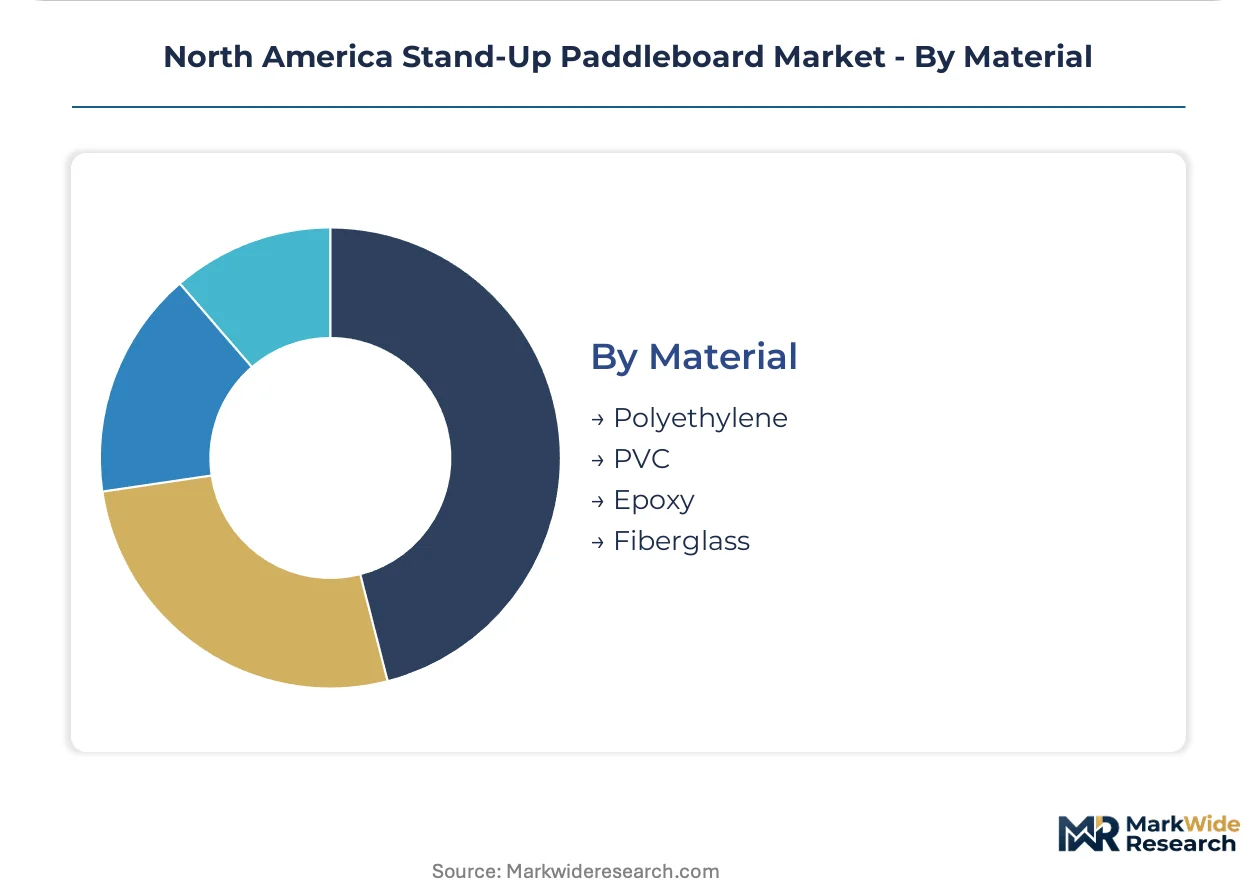
Material segmentation maps how feedstock volatility and environmental compliance reshape fabrication economics across North American production bases.
- PVC:Thermoplastic polymer forming the air-tight bladder and outer skin of inflatable boards. Demand concentrates among mass-market manufacturers seeking weldable seams and repair patch compatibility.
- Epoxy:Thermoset resin binding fiberglass cloth around foam cores in hardboard construction. Demand concentrates among West Coast fabricators subject to California State Water Resources Control Board effluent mandates accelerating cleaner production technology adoption.
- Polyethylene:Rotomolded plastic for entry-level durability in rental fleet applications.
- Fiberglass:Woven glass fiber reinforcement providing tensile strength in premium hardboard laminates.
Epoxy retains margin leadership; PVC faces the steepest cost pressure from petrochemical feedstock fluctuations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters along the Pacific Coast where environmental compliance infrastructure and composite fabrication expertise overlap. Distribution networks radiate from these production hubs toward coastal tourism corridors and inland lake recreation zones.
United States
California's Southern California Bight metropolitan zones generate concentrated demand from fitness practitioners and rental fleet operators. The US Coast Guard regulates paddleboard safety equipment under recreational vessel guidelines, mandating integrated leash attachments and visible identification markings. Florida's Gulf Coast corridors host expanding coastal tourism operations scaling fleet procurement contracts with specialized distributors.
Canada
Ontario's lake district and British Columbia's Pacific coastline sustain seasonal recreational demand from cabin owners and coastal residents. Health Canada monitors product safety compliance through the Consumer Product Safety Commission framework for watercraft equipment. Vancouver's manufacturing base serves Pacific Northwest distribution networks with inflatable construction prioritized for transport efficiency across dispersed population centers.
Mexico
Baja California Sur and Quintana Roo coastal tourism zones are emerging as rental fleet expansion targets for North American operators seeking winter season capacity. Mexico's national consumer protection agency PROFECO oversees product safety standards for imported recreational equipment. Cancún and Los Cabos hospitality corridors concentrate equipment deployment for cruise passenger and resort guest segments.
North America Stand-Up Paddleboard Market Competitive Landscape
Concentration sits with direct-to-consumer specialists and West Coast manufacturing anchors. The vendor base spans vertically integrated fabricators controlling molding and fulfillment, alongside digital-native retailers outsourcing production to Asian contract manufacturers. Three archetypes dominate: premium inflatable specialists, price-aggressive online retailers, and rental-focused fleet suppliers. Competitive moves center on channel disintermediation and compliance infrastructure investment for Coast Guard mandate alignment.
Among premium-tier inflatable specialists, BOTE and ISLE Surf & SUP exemplify archetype positioning through direct channel control and West Coast manufacturing footprints. Tower Paddle Boards represents the price-aggressive digital retailer model competing through online retail efficiency. These three companies anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Boardworks |
| Yolo Board |
| BOTE |
| Tower Paddle Boards |
| ISLE Surf & SUP |
| SUP ATX |
| NRS |
| Thurso Surf |
| GILI Sports |
| Others |
Value Network & Pricing Analysis
Long-term fleet procurement contracts between Florida Gulf Coast rental operators and West Coast fabricators lock in volume commitments and price visibility across volatile PVC resin cycles. These arrangements insulate coastal tourism corridors from spot-market petrochemical swings while concentrating negotiating leverage with scaled manufacturers.
Pricing Analysis
Volume-discount tiering separates premium hardboard epoxy construction from mass-market inflatable PVC tiers. Certification grade under US Coast Guard recreational vessel standards commands price premiums for integrated leash attachments and visible identification markings. Cost compression in the inflatable segment is intensifying because petrochemical feedstock volatility compresses margins at mass-market price points. Rental fleet operators exhibit lowest price sensitivity due to amortization across high utilization rates, while casual recreational buyers in Michigan and Wisconsin lake districts demonstrate highest elasticity.
Supply Chain Analysis
Just-in-time inventory preferences dominate among California fabricators subject to State Water Resources Control Board effluent mandates, minimizing work-in-process exposure to regulatory disruption. Manufacturing gravity centers on California, with secondary capacity in Mexico's Baja California Sur corridor and Vancouver's Pacific Northwest base. PVC resin, drop-stitch core materials, and epoxy thermoset formulations constitute critical input dependencies. Single-source vulnerability concentrates in Asian-sourced drop-stitch construction components. Distribution runs through direct-to-consumer platforms and specialty rental distributors serving coastal tourism zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as subscription-based equipment access models displace outright ownership among intermittent users in Southern California Bight metropolitan zones.
For Market Incumbents: Shield premium positioning through captive control over West Coast manufacturing footprints and Coast Guard compliance infrastructure. Invest in certification documentation systems that accelerate Florida and California rental fleet retrofit obligations. Consolidate procurement relationships with coastal tourism operators before Asian contract manufacturers achieve comparable compliance scale.
For New Entrants and Emerging Players: Coast Guard personal flotation device certification fast-tracks market entry for scaled manufacturers with testing laboratory relationships. Target underpenetrated Midwest lake access zones in Michigan and Wisconsin for rental network development. Pursue digital-native direct sales channels to bypass wholesale margin surrender to specialty retail intermediaries.
For Investors and Strategic Acquirers: Direct-to-consumer specialists with integrated fulfillment infrastructure represent the most defensible acquisition archetype in this market. Long-term viability hinges on channel control durability and regulatory compliance scalability rather than manufacturing asset intensity. Watch for inflection when subscription access penetration in Southern California Bight metropolitan zones crosses thresholds that permanently reshape ownership patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Coast Guard Compliance Infrastructure Investment | Accelerates certification documentation for Florida and California rental fleet retrofit obligations. |
| Direct-to-Consumer Channel Expansion | Captures margin stack previously surrendered to specialty retail intermediaries in metropolitan coastal zones. |
| Midwest Rental Network Development | Establishes first-mover positioning in underpenetrated Michigan and Wisconsin freshwater recreation corridors. |
| Drop-Stitch Construction Technology Advancement | Closes performance gaps with epoxy hardboards while retaining urban storage and transport logistics advantages. |
| Subscription Access Model Pilot | Displaces outright ownership among intermittent users in Southern California Bight apartment-dwelling segments. |
Research Methodology
Cross-validation between primary interviews with rental fleet operators, composite fabrication plant managers, and coastal tourism procurement leads anchors the qualitative findings against secondary validation from US Coast Guard recreational vessel guidelines, California State Water Resources Control Board effluent databases, and customs records tracking PVC resin and drop-stitch material imports. Bottom-up triangulation across equipment shipment volumes and top-down reconciliation against coastal tourism expenditure patterns ensure consistency.
Sensitivity analysis around PVC resin price volatility and Coast Guard mandate implementation timelines stress-tests projection robustness across the analysis window. Segmentation dimensions modeled include construction method, end-user intensity, distribution channel, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to fleet procurement contract disclosures and replacement cycle assumptions for fitness practitioner equipment turnover.
Decision-makers should treat outputs as directional under stable petrochemical feedstock and Coast Guard classification assumptions; material deviation would warrant model refresh. Revision becomes warranted when subscription access penetration in Southern California Bight metropolitan zones crosses thresholds that permanently alter ownership-to-access ratios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Backboard Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Global Horse Riding Equipment Market