
 Bike Saddles Market | 2026-2036
Bike Saddles Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Saddles Market Outlook
Aftermarket service revenue is fragmenting across independent fit studios, direct-to-consumer calibration tools, and warranty-backed comfort guarantees. Selle Italia s.r.l. leverages its Italian manufacturing heritage to dominate premium road racing channels. Brooks England anchors the heritage leather segment through artisan positioning and decades-long durability claims. SHIMANO INC. extends its component ecosystem control by bundling saddle compatibility within its drivetrain specification protocols.
A bike saddle constitutes a load-bearing contact point between rider and bicycle, typically engineered with a rigid base of nylon-reinforced polymer or carbon fiber, padded with polyurethane foam, viscoelastic gel, or natural leather, and shaped to distribute ischial pressure across 80–140 square centimeters of surface area. Its primary commercial purpose is to convert rider weight into pedaling efficiency while preventing perineal nerve compression during sustained contact. Road and performance designs capture the highest margin pools due to carbon rail upgrades and pressure-mapping customization, while hybrid and commuter categories sustain volume through e-bike OEM bundling. Leather materials retain niche premium positioning despite synthetic and gel compounds commanding mainstream share through lower cost and weather resistance.
Europe's REACH regulation and the EU Green Deal framework restrict phthalate-based foam formulations and mandate recyclability disclosures, pushing manufacturers toward bio-based polyurethane alternatives. The US Consumer Product Safety Commission enforces structural integrity standards for saddle rails under dynamic load testing, creating compliance barriers for unbranded imports. Stakeholders must monitor how China's GB standards for bicycle components evolve under MIIT's quality supervision mandates, as domestic certification requirements will determine market access for foreign suppliers.
Market Dynamics
E-bike commuter adoption is compressing replacement cycles while REACH compliance forces polyurethane foam reformulation across European supply chains. These intersecting pressures are restructuring procurement priorities for OEMs and aftermarket channels simultaneously.
Growth Catalysts
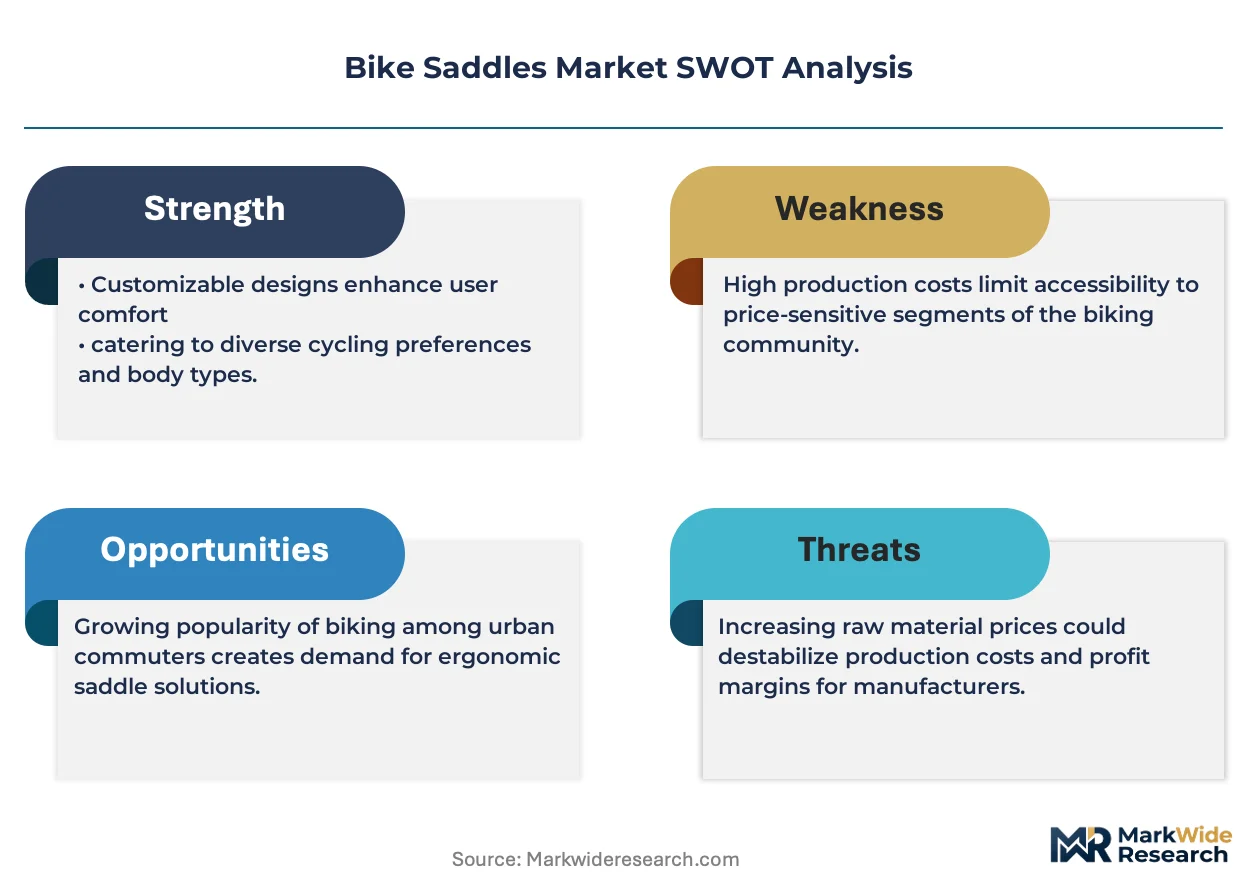
- REACH chemical restrictions:European ECHA mandates on phthalate-based foams are accelerating bio-based polyurethane R&D, creating first-mover advantages for compliant suppliers.
- China cycling infrastructure investment:MIIT quality supervision mandates under evolving GB standards are expanding domestic certification requirements and formalizing market access protocols.
- Pressure-mapping customization:Fit studio adoption of digital sit-bone measurement tools is elevating premium saddle attach rates among performance cyclists.
Market Restraints
- Carbon fiber rail supply concentration:Toray and Mitsubishi Chemical dominate aerospace-qualified carbon fiber grades, creating input bottlenecks for high-performance saddle rails.
- Leather tanning environmental compliance:Chromium VI restrictions under EU Green Deal framework are elevating processing costs for heritage leather saddle producers.
- Gel compound weather degradation:Viscoelastic polyurethane gels exhibit accelerated compression set in tropical humidity, limiting warranty terms in Southeast Asian markets.
Strategic Opportunities
- Direct-to-consumer calibration tools:Smartphone-based sit-bone width apps are disintermediating traditional bike shop fitting services and capturing first-party rider data.
- Warranty-backed comfort guarantees:30-day trial programs with full refund provisions are reducing purchase friction and building brand loyalty in premium segments.
- E-bike OEM bundling protocols:SHIMANO and Bosch system integrators are specifying saddle compatibility within drivetrain specification frameworks.
Industry Challenges
- Pressure-mapping technician certification:Independent fit studios lack standardized training protocols for interpreting digital sit-bone data, producing inconsistent recommendations.
- Dual inventory complexity:Retailers must stock separate saddle widths and rail materials across road, gravel, and e-bike categories, elevating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Saddles Market |
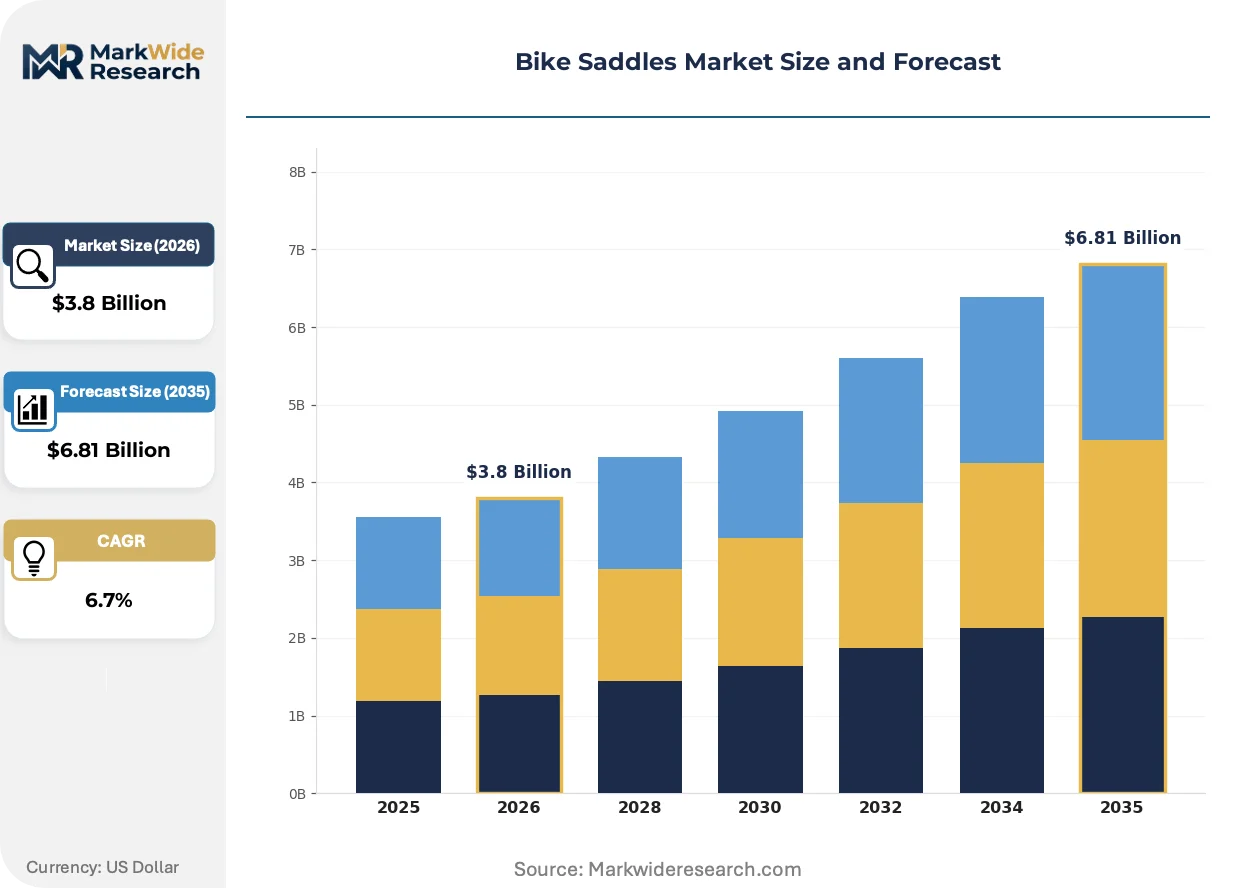
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain, Road, Hybrid, Women's Material: Leather, Synthetic, Foam, Gel Design: Racing, Comfort, Performance, Urban End User: Amateur, Professional, Recreational, Commuter |
| Companies Covered | Specialized Bicycle Components, Inc., SHIMANO INC., Selle Italia s.r.l., Fizik, Giant Bicycles, MERIDA BIKES, Selle Royal S.p.A., Brooks England, Bontrager, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Saddles Market Strategic Shifts
Material science breakthroughs and regulatory chemistry mandates are converging to reshape saddle construction methods. Three developments are altering competitive positioning across price tiers and geographic markets.
3D-printed lattice structures using thermoplastic polyurethane are replacing traditional foam padding in performance saddles. Pro teams and gran fondo participants are specifying these designs for pressure relief without weight penalty. The technology is rendering obsolete conventional CNC-milled foam blocks that dominated premium manufacturing for two decades.
REACH restrictions on isocyanate-based polyurethane precursors are forcing foam suppliers toward castor oil and soy-based polyol alternatives. German and Italian compounders are reformulating production lines ahead of 2027 enforcement deadlines. Road racing and triathlon categories face the steepest cost transitions due to performance-grade density requirements.
Rider data ownership is shifting from retailers to saddle brands through embedded pressure sensors and companion apps. Subscription-based fit optimization services are replacing one-time shop consultations. This pattern is most pronounced in Dutch and Danish urban cycling markets where e-bike penetration exceeds 40 percent of new bicycle sales.
Bike Saddles Market Segmentation
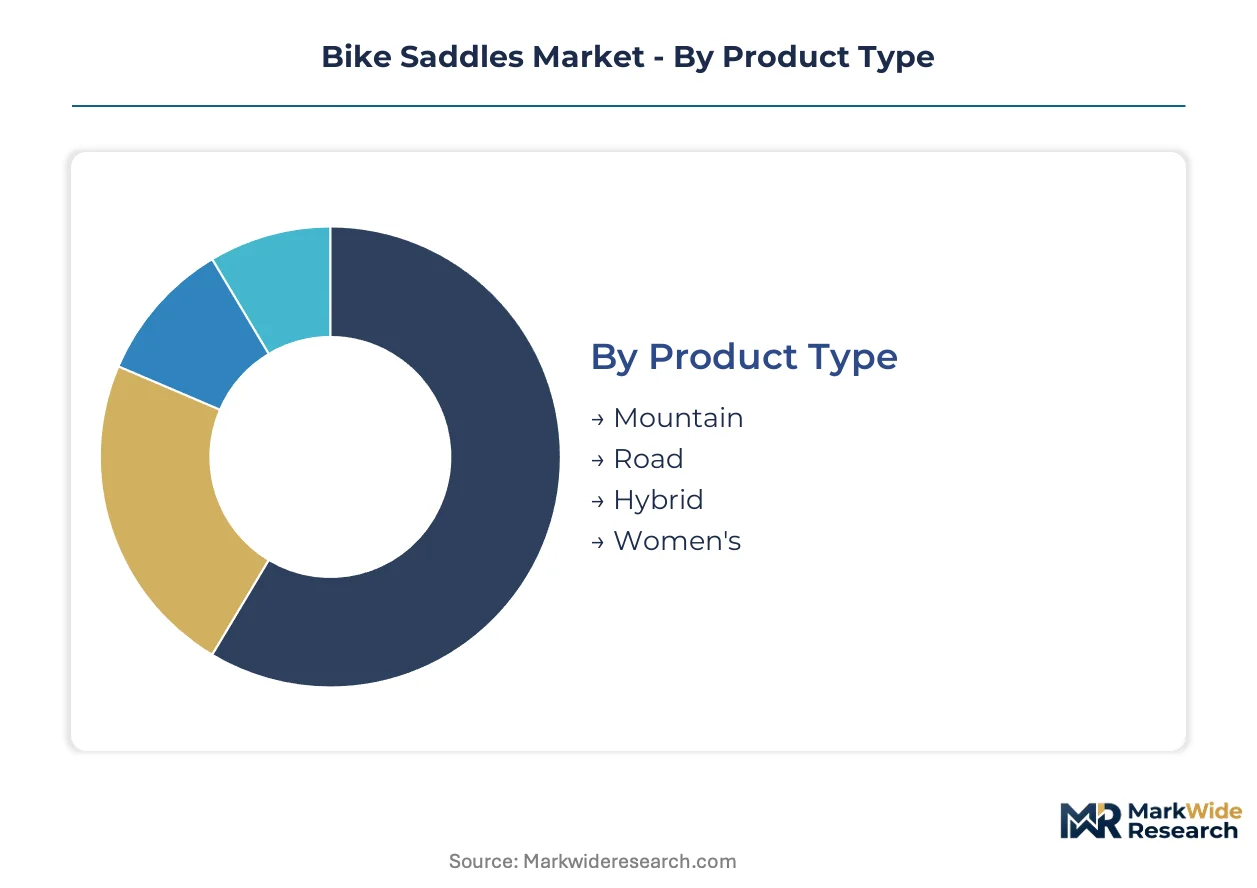
Saddle segmentation determines margin capture across replacement cycles and OEM bundling protocols. Material chemistry and design geometry create distinct procurement priorities for performance cyclists versus e-bike commuters.
Product Type:
Application use case separates volume economics from premium positioning across cycling disciplines.
- Mountain:Reinforced polymer bases with impact-resistant rail geometries withstand trail vibration and dropper post actuation. Demand concentrates in Pacific Northwest trail networks and Alpine tourism zones where enduro racing elevates durability requirements.
- Road:Carbon fiber rail constructions and pressure-relief channel geometries dominate gran fondo and racing specifications. European pro team procurement and Japanese domestic road racing sustain margin pools through weight-minimized designs.
- Hybrid:Moderate padding density and universal rail spacing accommodate multi-surface utility cycling. Commuter rail networks in Netherlands and Denmark drive replacement volume through high-mileage urban use.
- Women's:Anatomically widened rear platforms and forward-positioned relief channels address sit-bone width variation. North American fit studio adoption and UK cycling club demographics expand attach rates beyond traditional unisex stocking.
Road holds installed capacity. Mountain is rotating up the share rankings.
Material:
Cost tier and regulatory compliance reshape supplier qualification across foam chemistry and hide processing.
- Leather:Vegetable-tanned hides from British and Italian tanneries age into rider-specific contours over multi-year break-in periods. ECHA chromium VI restrictions under EU Green Deal framework elevate processing costs and consolidate heritage production to compliant facilities.
- Synthetic:Polyurethane-coated textiles and microfiber surfaces deliver weather resistance at mid-tier price positioning. Southeast Asian OEM bundling for e-bike exports and Indian domestic commuter sales sustain volume throughput.
- Foam:Open-cell polyurethane formulations balance density against weight for performance categories. REACH phthalate restrictions are accelerating bio-based polyol R&D among German and Italian compounders ahead of enforcement deadlines.
- Gel:Viscoelastic polyurethane inserts provide immediate comfort without break-in latency. Tropical humidity in Brazilian and Thai markets accelerates compression set degradation, limiting warranty terms and regional distribution.
Synthetic commands volume throughput. Foam is gaining share fastest through regulatory-driven chemistry transitions.
Design:
Rider posture and contact duration determine structural geometry and rail material specifications.
- Racing:Minimal padding profiles and stiff carbon rails maximize power transfer during sustained aerodynamic positioning. UCI WorldTour team specifications and Japanese keirin racing sustain premium positioning through gram-counted procurement.
- Comfort:Elastomer dampers and sprung rail suspensions absorb road irregularities for upright posture cycling. Dutch e-bike OEM integration and Danish cargo bike specifications expand category relevance beyond traditional recreational use.
- Performance:Pressure-mapping optimized channel geometries and graduated foam densities target endurance riders. Digital fit studio adoption in German and Australian markets elevates attach rates among gran fondo participants.
- Urban:Abrasion-resistant covers and integrated rear reflectors address theft-prone parking and low-light visibility. Bike-share fleet procurement in Paris and Barcelona mandates replaceable cover designs for maintenance efficiency.
Performance holds technology leadership. Urban is climbing the fastest through micromobility infrastructure expansion.
End User:
Customer type separates price-sensitive replacement purchasing from specification-driven OEM influence.
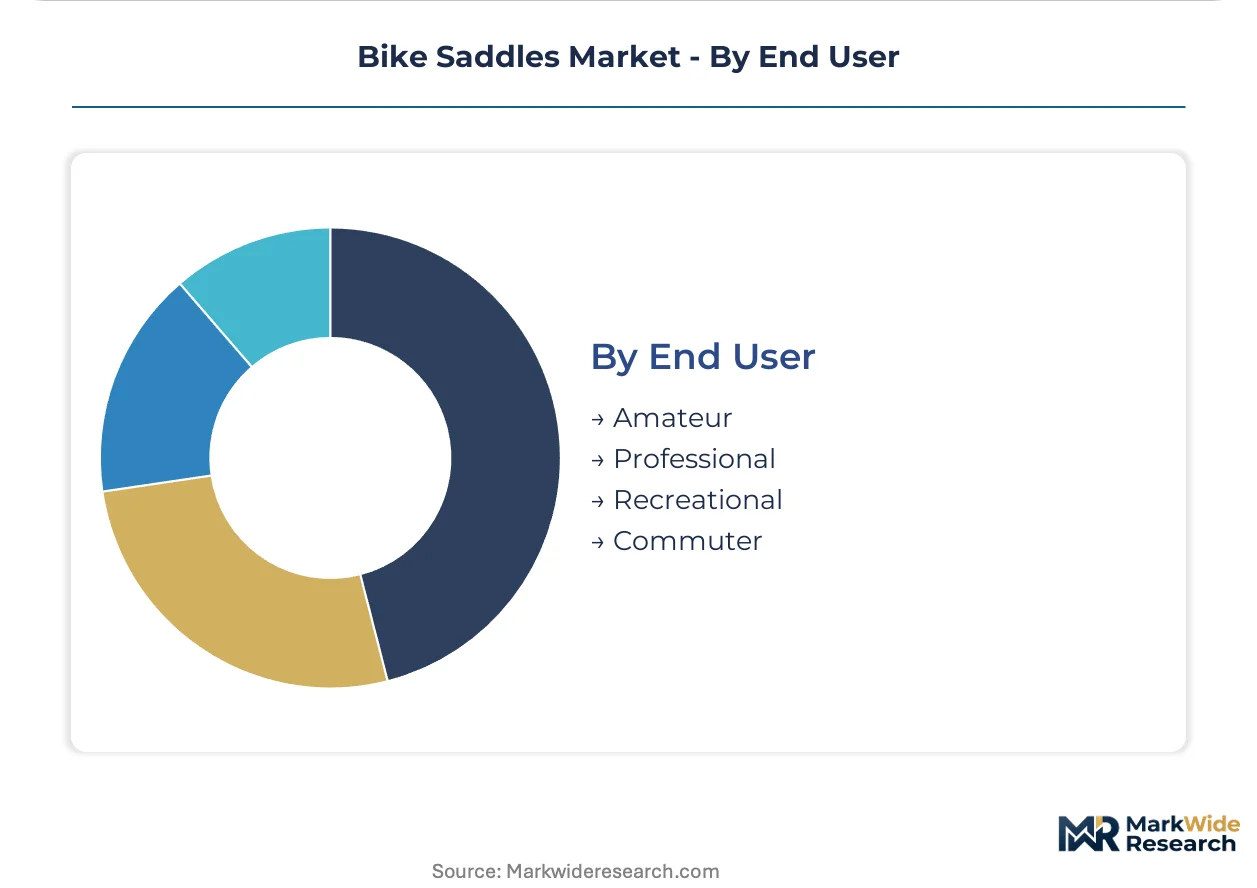
- Amateur:Club cyclists and sportive participants prioritize pressure relief and durability over weight minimization. UK cycling club demographics and Australian gran fondo entry growth sustain mid-tier volume.
- Professional:UCI-registered teams and national federation programs specify sponsor-matched equipment with sub-200-gram weight targets. Italian and Belgian racing heritage brands dominate squad procurement through technical service relationships.
- Recreational:Weekend riders and fitness cyclists respond to retail channel promotions and seasonal discounting. North American big-box sporting goods and European supermarket bicycle sales drive private-label volume.
- Commuter:Daily urban cyclists prioritize weather resistance and theft-deterrent mounting systems over performance metrics. China domestic e-bike adoption and Netherlands cargo bike integration expand category scale through OEM bundling protocols.
Amateur maintains replacement frequency. Commuter is expanding most quickly through e-bike penetration and infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across markets. Dutch and Danish commuters accept premium pricing for durability, while Indian and Southeast Asian buyers prioritize entry-level synthetic options. German and Japanese performance cyclists drive margin capture through specification-driven procurement.
Germany
E-bike commuter density in Berlin and Munich sustains replacement demand at premium price points. ECHA REACH enforcement on phthalate-based foams is accelerating bio-polyurethane transitions among Bavarian compounders. Stuttgart's automotive supplier ecosystem is repurposing precision molding capabilities for saddle rail production.
Netherlands
Urban cycling infrastructure in Amsterdam and Utrecht generates the highest per-capita saddle replacement frequency worldwide. EU Green Deal chromium VI restrictions are consolidating heritage leather tanning to compliant Limburg facilities. Eindhoven's design studios are prototyping integrated sensor arrays for fit optimization services.
China
Domestic e-bike adoption exceeding forty million units annually is compressing OEM bundling cycles. MIIT quality supervision mandates under evolving GB standards are formalizing certification requirements for foreign suppliers. Shenzhen and Tianjin manufacturing clusters are scaling synthetic cover production for export markets.
United States
Gran fondo participation growth in California and Colorado elevates pressure-mapping saddle attach rates. CPSC dynamic load testing standards for rail integrity create compliance barriers for unbranded imports. Pacific Northwest trail networks sustain mountain saddle demand through enduro racing expansion.
Japan
Keirin racing specifications and domestic road racing culture sustain gram-counted premium procurement. METI industrial standards for bicycle component safety are tightening quality disclosure requirements. Osaka-based precision manufacturers are supplying carbon fiber rail stock to regional saddle assemblers.
Bike Saddles Market Competitive Environment
Capability concentration sits with heritage European specialists; scale advantage sits with Asian component conglomerates. The market structures around three tiers: artisan leather producers with century-old positioning, performance specialists leveraging pressure-mapping technology, and diversified bicycle OEMs capturing bundling economics. Two competitive moves dominate: drivetrain ecosystem integration and direct-to-consumer fit tool deployment.
Among Italian heritage specialists, Selle Italia s.r.l. and Selle Royal S.p.A. occupy positions defined by racing pedigree and volume manufacturing respectively. SHIMANO INC. represents the ecosystem-control archetype, extending component bundling protocols into saddle specification frameworks. Brooks England exemplifies the artisan-tier positioning, anchoring premium leather demand through durability claims and break-in rituals.
| Leading Market Players |
|---|
| Specialized Bicycle Components, Inc. |
| SHIMANO INC. |
| Selle Italia s.r.l. |
| Fizik |
| Giant Bicycles |
| MERIDA BIKES |
| Selle Royal S.p.A. |
| Brooks England |
| Bontrager |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese synthetic cover manufacturing is compressing margin capture for mid-tier producers while simultaneously enabling aggressive OEM bundling economics. This utilization dynamic forces European and Japanese suppliers toward carbon rail specialization and bio-based polyurethane premium positioning to defend price architecture.
Pricing Analysis
Aftermarket service revenue from fit studio calibration and warranty-backed comfort guarantees drives lifetime value capture. Three-tier pricing structure across premium, standard, and economy levels separates carbon-rail performance specifications from gel-padded commuter models and basic synthetic OEM bundles. Cost compression in standard-tier foam formulations is intensifying because REACH-mandated bio-polyol transitions elevate compounder qualification costs. Commuter segments exhibit highest price sensitivity due to e-bike OEM volume procurement, while gran fondo participants accept premium positioning for pressure-mapped customization.
Supply Chain Analysis
Contract manufacturing concentration rests with Shenzhen and Tianjin synthetic cover specialists serving export markets, alongside Bavarian precision molders repurposing automotive capabilities for rail production. Raw material flows draw from Toray and Mitsubishi Chemical carbon fiber grades, German and Italian bio-polyol compounders, and British vegetable-tanned hides. Single-source vulnerability concentrates in aerospace-qualified carbon fiber for high-performance rails. Distribution runs through independent bike shop networks, direct-to-consumer calibration platforms, and OEM bundling protocols specified by drivetrain ecosystem integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward e-bike OEMs and direct-to-consumer fit platforms as procurement consolidates around specification-setting ecosystem controllers. This fragmentation among traditional retail channels weakens incumbent pricing leverage.
For Market Incumbents: Build certification moats around REACH-compliant bio-polyurethane formulations and ECHA-registered compounder relationships. Secure backward integration into carbon fiber rail production through partnerships with Osaka-based precision manufacturers. Channel control through exclusive fit studio technician training programs counters direct-to-consumer disintermediation threats. For New Entrants and Emerging Players: Establish a beachhead in women's-specific anatomical designs where North American fit studio adoption outpaces incumbent stocking depth. Target urban bike-share fleet procurement in micromobility expansion cities with replaceable cover architectures. Go-to-market leverage rests on smartphone-based sit-bone measurement apps capturing first-party rider data. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance arbitrage play because ECHA enforcement timelines and MIIT certification mandates create qualification barriers that favor capitalized compounders and heritage tanners. Acquisition targets center on Italian bio-polyol R&D specialists and Limburg-compliant leather processors. The signal to watch is E-bike OEM bundling protocol adoption rates as specification control indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Polyurethane Transition | REACH-compliant compounders gain first-mover certification advantages ahead of ECHA enforcement deadlines. |
| Pressure-Mapping Technology Integration | Embedded sensor arrays shift rider data ownership from retailers to saddle brands in Dutch urban markets. |
| Carbon Fiber Rail Supply Security | Partnerships with Toray and Mitsubishi Chemical qualified grades reduce aerospace input bottlenecks. |
| Direct-to-Consumer Calibration Tools | Smartphone sit-bone apps disintermediate traditional bike shop fitting services and capture proprietary data. |
| E-Bike OEM Bundling Protocols | SHIMANO and Bosch drivetrain specification frameworks embed saddle compatibility as ecosystem control mechanisms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with product managers at heritage Italian saddle specialists, procurement leads at German e-bike OEMs, technical directors at Bavarian polyurethane compounders, and fit studio owners in Netherlands urban cycling markets. Secondary validation drew from ECHA REACH substance registrations, MIIT bicycle component GB standard drafts, UCI equipment technical regulations, and customs trade data for carbon fiber rail imports. Bottom-up volume modeling triangulated against top-down OEM bundling cycle analysis.
Calibration across the analysis window employed segment-level growth rate derivation from replacement frequency data and e-bike penetration trajectories. Modeled dimensions spanned product type, material chemistry, design geometry, and end-user category. CAGRs were computed from installed base expansion and compressed replacement cycle assumptions. Industry-specific inputs included ECHA enforcement timeline phasing and MIIT certification requirement evolution.
Stress conditions across REACH reformulation cost pass-through, carbon fiber supply disruption, and e-bike subsidy withdrawal were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume continued ECHA bio-polyol transition compliance and MIIT quality supervision mandate expansion. Cross-checking against bicycle OEM production schedule disclosures and component supplier order backlog reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Sports Flooring Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Dance Equipment Market
Sports Equipment
Go Kart Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Surfboard Market
Sports Equipment
Sports Devices Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Europe Ski Gear and Equipment Market