
 Bicycle Tire Market | 2026-2036
Bicycle Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Tire Market Intelligence
Thermoplastic elastomer compounding is reconfiguring how bicycle tire casings achieve puncture resistance without the weight penalty of traditional aramid layers. Continental leverages captive rubber research facilities to anchor its tubeless road tire portfolio. Michelin competes through motorsport-derived silica tread compounds adapted for wet-weather cycling grip. Schwalbe dominates the European premium replacement channel through dealer-exclusive distribution agreements and recycling take-back programs.
A bicycle tire is a toroidal flexible structure comprising a woven fabric casing, rubber tread compound, and optional puncture-protection belt, designed to interface with a rim bed while transmitting rider power, absorbing road irregularities, and providing directional control across variable surfaces. Tubeless configurations now lead growth in mountain biking and gravel applications where lower pressures reduce pinch-flat incidence. Clincher systems retain volume leadership in road cycling due to standardized rim interfaces and established roadside repair protocols. Natural rubber formulations face margin pressure from Southeast Asian supply volatility, pushing compounders toward bio-based synthetic alternatives in touring and urban commuting grades.
REACH restrictions on polycyclic aromatic hydrocarbons in tire manufacturing reshape European compound sourcing, while China's GB standards for e-bike tire load ratings create separate certification tracks for domestic OEM supply. The US Consumer Product Safety Commission maintains bicycle tire recall authority, though enforcement intensity varies by distribution channel. Stakeholders must monitor how EU Ecodesign for Sustainable Products Regulation extends to tire durability labeling and recycled content thresholds.
Market Dynamics
Thermoplastic elastomer compounding is compressing traditional aramid-reinforced casing architectures while REACH polycyclic aromatic hydrocarbon restrictions force compound reformulation across European supply chains.
Growth Catalysts
- Last-mile fleet expansion:Urban delivery operators across India, Vietnam, and Indonesia are compressing tire replacement cycles as e-cargo bike deployment accelerates in dense metropolitan corridors.
- REACH compliance migration:ECHA restrictions on PAH content in rubber compounds are redirecting European manufacturers toward bio-sourced synthetic formulations with certified supply chain traceability.
- Tubeless system adoption:Mountain bike and gravel segments are standardizing tubeless-ready rim-tire interfaces, eliminating inner tube inventory layers from retail and OEM supply chains.
Market Restraints
- Natural rubber price volatility:Southeast Asian latex supply disruptions from climate stress and labor constraints are compressing margins for manufacturers dependent on high-natural-rubber touring compounds.
- Certification fragmentation:China's GB standards for e-bike load ratings operate on separate testing protocols from CPSC requirements in the United States, forcing dual-track product development.
- Aramid fiber cost structure:Puncture-protection belt materials remain input-cost intensive relative to thermoplastic alternatives, limiting price competitiveness in economy-tier replacement markets.
Strategic Opportunities
- EU Ecodesign extension:The EU Ecodesign for Sustainable Products Regulation's anticipated durability labeling and recycled content thresholds will reward early movers with certified circular supply chains.
- Dealer recycling integration:European premium channels are piloting take-back programs that lock in replacement demand through trade-in credit systems tied to new tire purchases.
- Silica compound convergence:Motorsport-derived wet-grip formulations adapted from automotive racing are penetrating road cycling segments where all-weather performance commands price premiums.
Industry Challenges
- Compounder talent scarcity:Formulation chemistry expertise for bio-sourced synthetic rubber development concentrates among a narrow cohort of European and Japanese research facilities.
- Tubeless roadside repair complexity:Sealant-based puncture sealing protocols require consumer education investments that legacy clincher distribution networks are structurally unprepared to deliver.
- Dual certification timelines:Parallel GB and CPSC testing tracks for e-bike tire load ratings extend product launch cycles by 8-14 months for manufacturers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Tire Market |
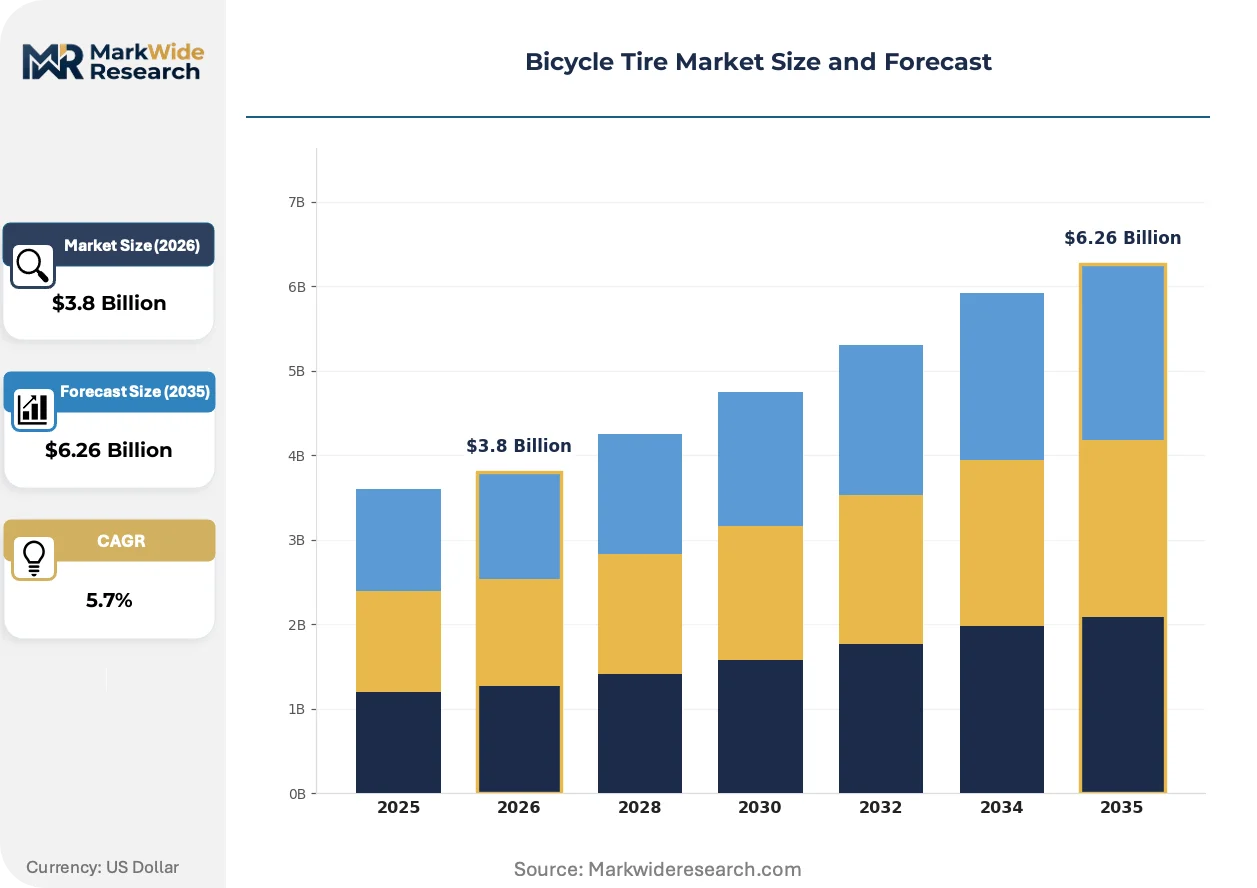
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clincher, Tubeless, Tubular, Solid Application: Road Cycling, Mountain Biking, Urban Commuting, Touring Material: Natural Rubber, Synthetic Rubber, Kevlar, Butyl End User: Sport Enthusiasts, Bicycle Retailers, Rental Services, Delivery Couriers |
| Companies Covered | Pirelli, Michelin, Continental, Panaracer, WTB, Schwalbe, Maxxis, Goodyear, Vittoria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Tire Market Strategic Shifts & Innovations
Material substitution and regulatory compliance are converging to compress traditional tire architectures while reshaping how manufacturers source, formulate, and distribute bicycle tires across divergent certification regimes.
Thermoplastic elastomer casing compounds are rendering obsolete woven aramid puncture-protection belts in premium road and gravel tire lines. Performance-oriented cyclists and OEM specifiers are adopting these lighter-weight alternatives at accelerating rates. The structural consequence is margin compression for suppliers locked into conventional fiber-reinforced supply chains.
REACH polycyclic aromatic hydrocarbon restrictions are forcing European compounders to reformulate tread and sidewall rubber away from petroleum-derived processing oils. ECHA enforcement intensity has escalated since the 2022 restriction tightening, with downstream bicycle tire manufacturers now requiring full supply chain PAH certification. The touring and urban commuting segments face the steepest transition costs due to their historical reliance on high-aromatic compounds for durability.
Direct-to-consumer channel expansion is fragmenting traditional dealer-exclusive distribution networks that historically dominated European premium replacement markets. Online retailers with fitment databases and video installation support are capturing younger urban commuters in Germany, Netherlands, and Denmark. This channel rotation is most visible in tubeless road tire categories where technical specification complexity previously favored physical retail consultation.
Bicycle Tire Market Segmentation
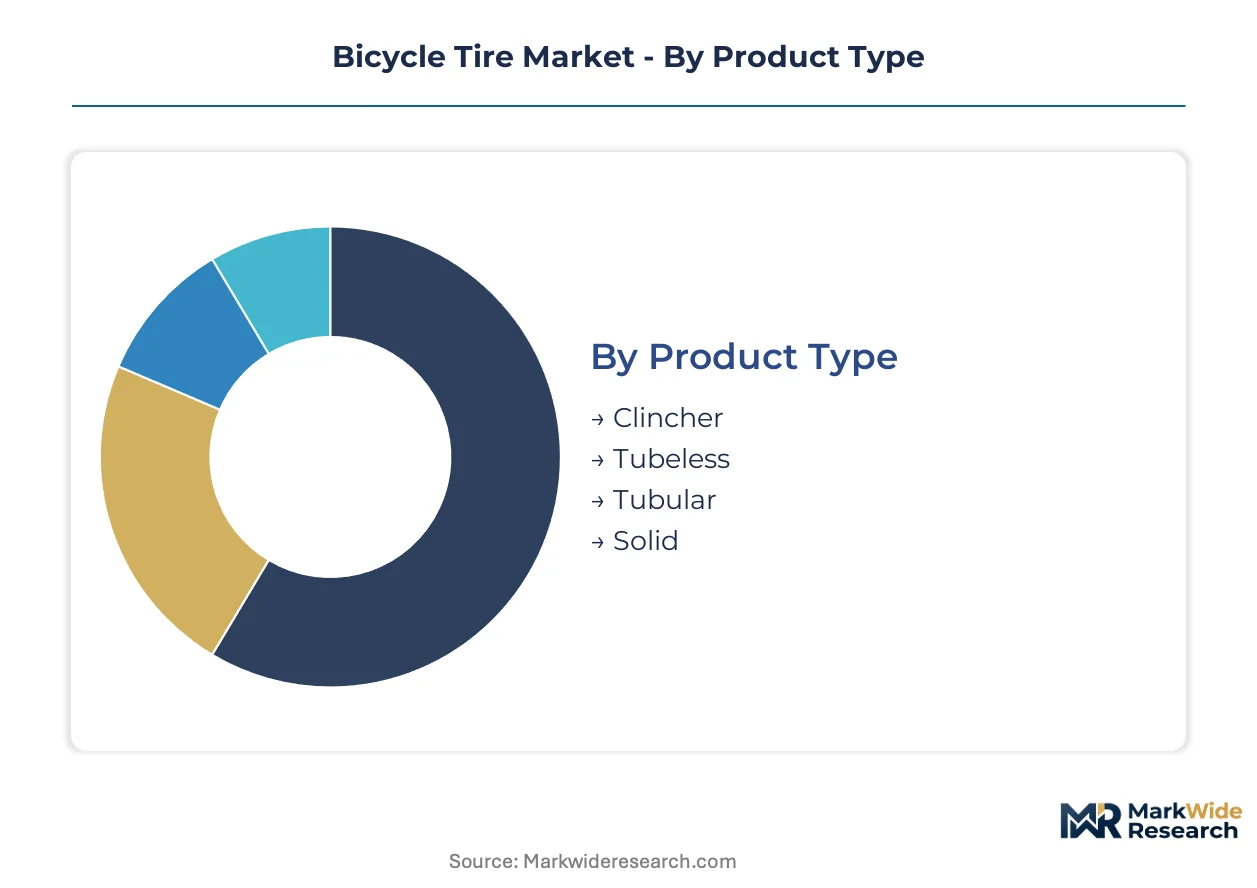
Segmentation in bicycle tires reveals how technical specifications, use environments, and procurement economics split demand across incompatible rim interfaces and compound formulations. Manufacturers configure production lines around these divides because tooling and curing processes do not transfer between clincher, tubeless, and tubular architectures.
Product Type:
Cost tier differentiation separates product types by manufacturing complexity, aftermarket service requirements, and OEM specification rates.
- Clincher:The bead hooks interface with standardized rim walls, enabling roadside repair with portable levers and spare tubes. Road cycling teams and recreational riders in Germany, Netherlands, and Belgium maintain this specification for its established service infrastructure.
- Tubeless:An airtight casing interfaces directly with the rim bed, eliminating inner tubes while requiring liquid sealant maintenance. Mountain bike and gravel applications in Colorado, British Columbia, and Scotland adopt this configuration for pinch-flat elimination at sub-30 PSI pressures.
- Tubular:The casing is sewn around an inner tube and glued to the rim, delivering weight reduction and ride quality at installation complexity cost.
- Solid:A homogeneous rubber or microcellular polyurethane structure eliminates pneumatic pressure entirely, targeting fleet maintenance reduction.
Clincher commands the established base. The steepest expansion runs through tubeless.
Application:
Use environment dictates casing construction, tread pattern, and compound hardness selection.
- Road Cycling:Smooth center treads and high-TPI casings minimize rolling resistance on paved surfaces. Competitive amateur racing circuits in France, Italy, and Spain specify these tires for criterium and gran fondo events where cornering grip at lean angles determines purchase decisions.
- Mountain Biking:Aggressive knob patterns and reinforced sidewalls withstand rock strikes and root impacts. Trail networks in Whistler, Rotorua, and Finale Ligure drive replacement demand through abrasion-intensive terrain.
- Urban Commuting:Puncture-resistant belts and reflective sidewalls address debris-strewn streets and low-light visibility.
- Touring:Durable compounds and high load ratings accommodate multi-day baggage carriage on mixed surfaces.
Road cycling anchors volume in mature markets. Urban commuting gains share fastest where last-mile fleet electrification accelerates.
Material:
Raw material selection determines elasticity, abrasion resistance, and regulatory compliance pathways.
- Natural Rubber:Hevea brasiliensis latex delivers unmatched elasticity and low heat buildup. Southeast Asian supply disruptions from Thai and Indonesian plantation constraints are compressing margin structures for touring compounders.
- Synthetic Rubber:Styrene-butadiene and polybutadiene formulations offer batch consistency and PAH compliance under REACH. European manufacturers pivot toward bio-sourced synthetic alternatives as ECHA enforcement tightens.
- Kevlar:Aramid fiber puncture belts provide cut resistance at weight and cost premiums relative to thermoplastic substitutes.
- Butyl:Isobutylene-isoprene rubber forms impermeable inner tube membranes and tubeless rim tape substrates.
Natural rubber retains the historical installed base. Synthetic formulations climb fastest on regulatory compliance requirements.
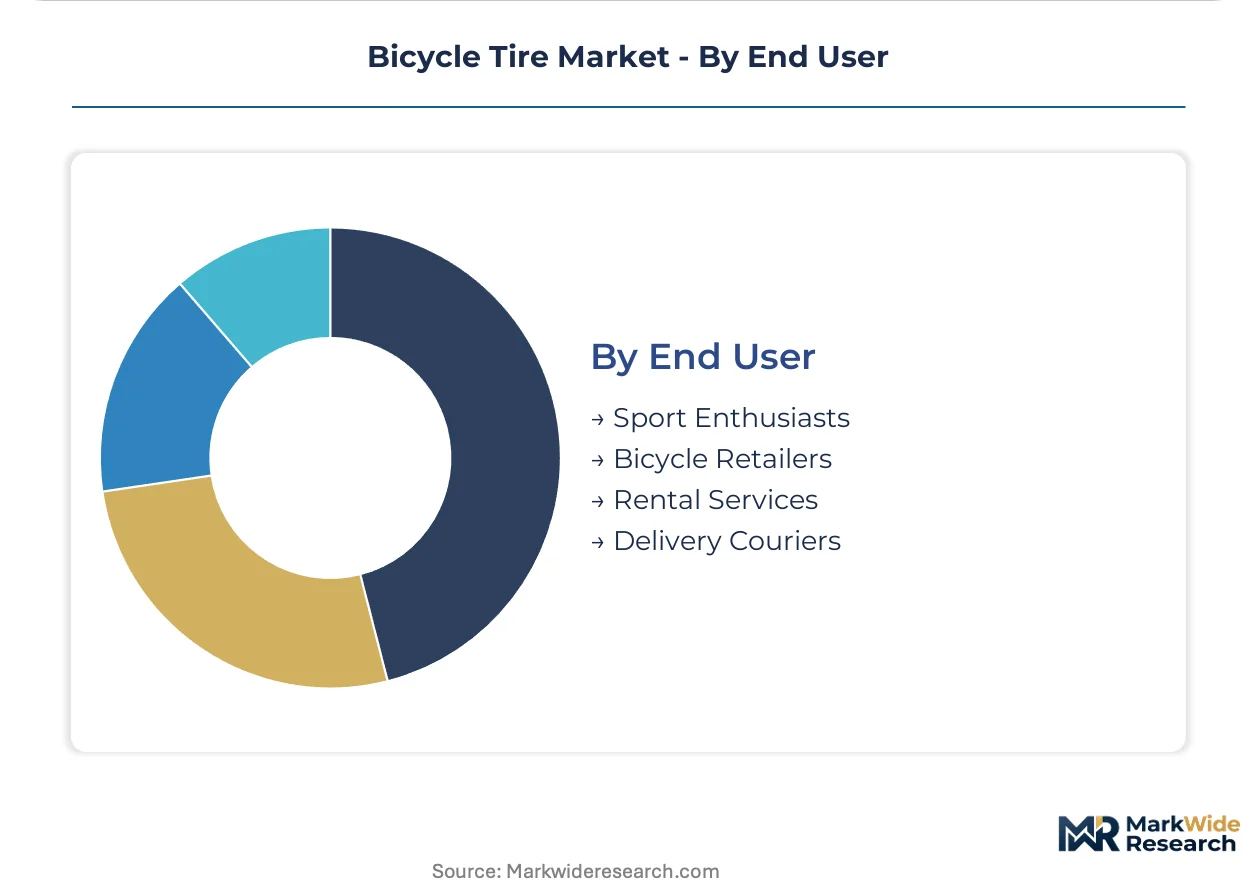
End User:
Procurement economics and technical specification authority separate end user categories.
- Sport Enthusiasts:Individual riders research TPI counts, compound durometers, and rolling resistance coefficients before purchase. Online fitment databases and forum discussions in Germany, UK, and Japan shape brand consideration sets.
- Bicycle Retailers:Independent shops and chain stores manage inventory turns across seasonal demand fluctuations. Dealer-exclusive distribution agreements lock in premium brand access for authorized service centers.
- Rental Services:Fleet operators prioritize durability and standardized maintenance protocols over performance optimization.
- Delivery Couriers:E-cargo bike fleets in Mumbai, Jakarta, and Ho Chi Minh City compress replacement cycles through high-mileage urban corridors.
Sport enthusiasts command the premium specification channel. Delivery couriers drive the steepest volume expansion through fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and sport enthusiasts concentrate demand in distinct geographic corridors, with regulatory frameworks fragmenting product specifications across major bicycle tire consumption zones.
China
E-cargo bike OEMs and export road cycling brands drive dual-track demand from manufacturing clusters in Zhejiang and Guangdong provinces. GB standards for e-bike tire load ratings mandate separate certification protocols from Western safety regimes. The Yangtze River Delta anchors domestic supply chains serving both local last-mile fleets and European premium brands.
Germany
Dealer-exclusive distribution networks and cycling club culture sustain premium replacement volume in Bavaria and North Rhine-Westphalia. ECHA REACH restrictions on polycyclic aromatic hydrocarbons force compound reformulation across rubber processing facilities. The Baden-Württemberg region hosts captive research operations developing bio-sourced synthetic alternatives.
United States
Mountain bike trail networks in Colorado and gravel racing circuits in the Pacific Northwest accelerate tubeless system adoption. CPSC maintains recall authority over bicycle tire safety, though enforcement intensity varies by distribution channel. The Midwest manufacturing belt supplies OEM specifiers with clincher systems for recreational road cycling segments.
India
Last-mile delivery operators across Mumbai, Delhi-NCR, and Bangalore compress replacement cycles through high-mileage urban corridors. Central pollution control directives increasingly scrutinize rubber compound formulations in domestic manufacturing. Tamil Nadu and Maharashtra industrial zones scale production for both domestic e-bike integration and Southeast Asian export markets.
Netherlands
Urban commuting infrastructure and cycling-as-transport policy normalize premium tire specification in Amsterdam-Rotterdam-Utrecht corridor. EU Ecodesign for Sustainable Products Regulation anticipates durability labeling requirements affecting import compliance. Randstad distribution hubs pilot dealer-integrated recycling take-back programs locking in replacement demand.
Bicycle Tire Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans vertically integrated rubber compounders, tire brand licensors, and regional fabricators serving distinct price-performance segments. Two archetypes dominate: motorsport-heritage compound developers leveraging automotive R&D spillovers, and cycling-native specialists anchoring dealer service networks. Competitive moves concentrate on exclusive distribution lock-ins and thermoplastic elastomer formulation licensing.
Within the motorsport-derived compounder tier, Pirelli and Michelin exemplify technology-transfer strategies from automotive racing into cycling wet-grip segments. Continental occupies a position bridging captive rubber research with tubeless road tire architectures. These three European-headquartered entities anchor premium-tier positioning through compound chemistry differentiation rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Pirelli |
| Michelin |
| Continental |
| Panaracer |
| WTB |
| Schwalbe |
| Maxxis |
| Goodyear |
| Vittoria |
| Others |
Cost & Logistics Intelligence
Zhejiang province's synthetic rubber compounding clusters anchor global capacity for thermoplastic elastomer bicycle tire casings, concentrating formulation expertise that translates directly into pricing power for manufacturers serving premium tubeless road and gravel segments. This geographic concentration of technical capability creates asymmetric margin structures where compound innovation commands sustained premiums while commodity-grade natural rubber formulations face persistent cost compression from Southeast Asian supply volatility.
Pricing Analysis
Cost-plus contracts indexed to styrene-butadiene rubber and polybutadiene feedstock futures dominate OEM supply agreements, insulating manufacturers from petrochemical volatility while compressing margins when spot prices diverge from contract baselines. Three-tier pricing structure across premium, standard, and economy levels separates tubeless-ready compounds with ECHA PAH certification from legacy high-aromatic touring grades and basic clincher replacements for emerging market fleet operators. Pricing pressure stems from thermoplastic elastomer substitution eroding aramid-reinforced product premiums. Delivery couriers in Indian and Vietnamese urban corridors exhibit highest price sensitivity, while German and Dutch sport enthusiasts tolerate substantial premiums for wet-grip silica compounds and dealer-integrated service bundles.
Supply Chain Analysis
Export-control restrictions on advanced aramid fiber weaving equipment limit technology transfer to Southeast Asian fabricators, preserving European and Japanese dominance in puncture-protection belt manufacturing. Thailand, Indonesia, and Vietnam supply natural rubber latex that feeds touring compound production, while Germany, China, and Japan concentrate synthetic rubber polymerization and thermoplastic elastomer compounding. Raw material dependencies center on Hevea brasiliensis latex, petroleum-derived processing oils, and silica filler grades. Single-source vulnerability concentrates in aramid fiber supply from DuPont and Teijin production networks. Distribution runs through dealer-exclusive agreements in European premium channels and direct-to-consumer platforms capturing younger urban commuters in Germany, Netherlands, and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bicycle tire demand sits in early-cycle expansion as last-mile fleet electrification and tubeless system adoption create dual penetration tailwinds across urban logistics and performance cycling segments simultaneously.
For Market Incumbents: Entrench compound chemistry differentiation through captive research facilities in Baden-Württemberg and Randstad regions, locking in ECHA PAH compliance certification ahead of Ecodesign durability labeling mandates. Secure dealer-exclusive distribution networks against direct-to-consumer erosion by integrating recycling take-back programs that trade end-of-life tire credits against replacement purchases. Vertical integration into bio-sourced synthetic rubber feedstocks defends margin position against petroleum price volatility and REACH reformulation costs. For New Entrants and Emerging Players: Establish a beachhead in Indian and Vietnamese delivery courier fleet supply, where compressed replacement cycles and limited brand loyalty create penetrable volume opportunities. Target white-space in thermoplastic elastomer tubeless gravel tires for North American and British Columbia trail networks, where technical specification complexity has slowed incumbent adaptation. Pursue direct-to-consumer fitment databases with video installation support to bypass entrenched European dealer networks. For Investors and Strategic Acquirers: Long-term, this sits as a compound-specialist consolidation play because formulation chemistry expertise concentrates among narrow European and Japanese research cohorts while regulatory compliance burdens escalate. Acquisition targets should prioritize captive rubber research operations with ECHA certification track records and established OEM specification relationships. Monitor Ecodesign durability labeling implementation timelines as the critical inflection signal for circular supply chain valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Sourced Synthetic Rubber Transition | ECHA REACH PAH restrictions force compound reformulation toward certified traceable supply chains. |
| Dealer Recycling Integration | European premium channels pilot take-back programs locking replacement demand through trade-in credits. |
| Tubeless System Standardization | Mountain bike and gravel segments eliminate inner tube inventory layers from retail supply chains. |
| Thermoplastic Elastomer Licensing | Formulation patents displace aramid-reinforced architectures in premium road tire specifications. |
| Dual Certification Streamlining | Parallel GB and CPSC testing tracks compress product launch timelines for cross-market manufacturers. |
Research Approach
Cross-validation between primary interviews with tire compound R&D directors, OEM specification engineers, and European dealer network managers anchors the qualitative findings against secondary validation from ECHA regulatory filings, customs trade data on natural rubber imports, and SEC disclosures from vertically integrated rubber compounders. Bottom-up triangulation across product-type demand modeling and top-down macroeconomic calibration ensures segmentation integrity. Stakeholder roles interviewed include plant managers at Thai latex processing facilities, procurement leads at German cycling OEMs, distribution channel partners in Dutch Randstad hubs, and technical directors at synthetic rubber polymerization plants in China and Japan.
Calibration against historical volume trajectories and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type architecture, application environment, material formulation grade, and end-user procurement economics. CAGRs derive from fitted growth curves incorporating fleet electrification penetration rates, tubeless adoption thresholds, and compliance cost pass-through elasticities. Industry-specific forecast inputs center on E-bike load rating certification volumes and thermoplastic elastomer patent filing velocities.
Sensitivities concentrate around Ecodesign durability labeling implementation schedules, Southeast Asian natural rubber supply disruptions from climate stress, and thermoplastic elastomer substitution rates in premium segments. Forecasts reflect documented assumptions on regulatory enforcement intensity and fleet operator replacement cycle compression. Material shifts in REACH restriction scope or GB-CPSC certification harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Baseball Shoes Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Global Spikeball Equipment Market
Sports Equipment
Running Gear Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Padel Balls Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Gym Bag Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Rowing Oars Market
Sports Equipment
Surface Water Sports Equipment Market