
 Middle East and Africa Sports Analytics Market | 2026-2036
Middle East and Africa Sports Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sports Analytics Market Foresight
Broadcasting networks is repositioning as the fastest-growing end user segment across the Middle East and Africa Sports Analytics landscape, overtaking traditional team-centric deployments as media rights holders pursue granular audience segmentation. Sportradar AG leverages its established data partnerships with regional football federations to control premium match data feeds. Catapult Group International Ltd anchors wearable athlete monitoring across rugby and football academies in South Africa and Australia-linked training programs. Stats Perform competes on predictive modeling tools that betting operators and broadcasters deploy for second-screen experiences.
Sports analytics encompasses the systematic capture, processing, and interpretation of athletic performance data through sensor networks, computer vision systems, and statistical algorithms to optimize competitive outcomes and commercial returns. Cloud processing architectures now handle sub-second latency for real-time tactical overlays, while edge computing nodes in stadium infrastructure reduce bandwidth costs for live video analysis. Performance Analysis commands the largest revenue share among product types, reflecting persistent investment from professional football clubs in the Gulf states seeking UEFA-standard training insights. Cloud-Based delivery models are expanding fastest, as telecommunications upgrades in Saudi Arabia and the UAE reduce latency barriers that previously favored on-premise installations.
South Africa's POPIA, the UAE's NESA compliance frameworks for critical infrastructure, and Saudi Arabia's SDAIA data governance standards collectively raise the compliance threshold for foreign analytics vendors seeking regional contracts. These regulations mandate local data residency and encrypted transmission protocols, which shapes procurement specifications for federations and broadcasters evaluating platform providers. Stakeholders must monitor how evolving national AI strategies across Gulf Cooperation Council members redefine acceptable automated decision-making in talent scouting and wagering applications.
Market Dynamics
Broadcasting networks across the Middle East and Africa are redirecting procurement budgets from team-centric performance tools toward real-time viewer engagement platforms, compressing sales cycles for cloud-native analytics vendors while elevating data residency requirements in tender specifications.
Growth Catalysts
- Cloud-Based Delivery Models:Telecommunications infrastructure upgrades in Saudi Arabia and the UAE are eliminating latency barriers that previously favored on-premise installations, enabling federations to access real-time tactical overlays without dedicated server farms.
- NESA Compliance Frameworks:The UAE's critical infrastructure data governance standards mandate encrypted transmission protocols and local data residency, which foreign vendors must satisfy to compete for broadcaster and federation contracts.
- Franchise League Expansions:Professional football and cricket league proliferation in the Gulf states is generating concentrated demand for UEFA-standard performance analysis platforms across multiple club academies simultaneously.
Market Restraints
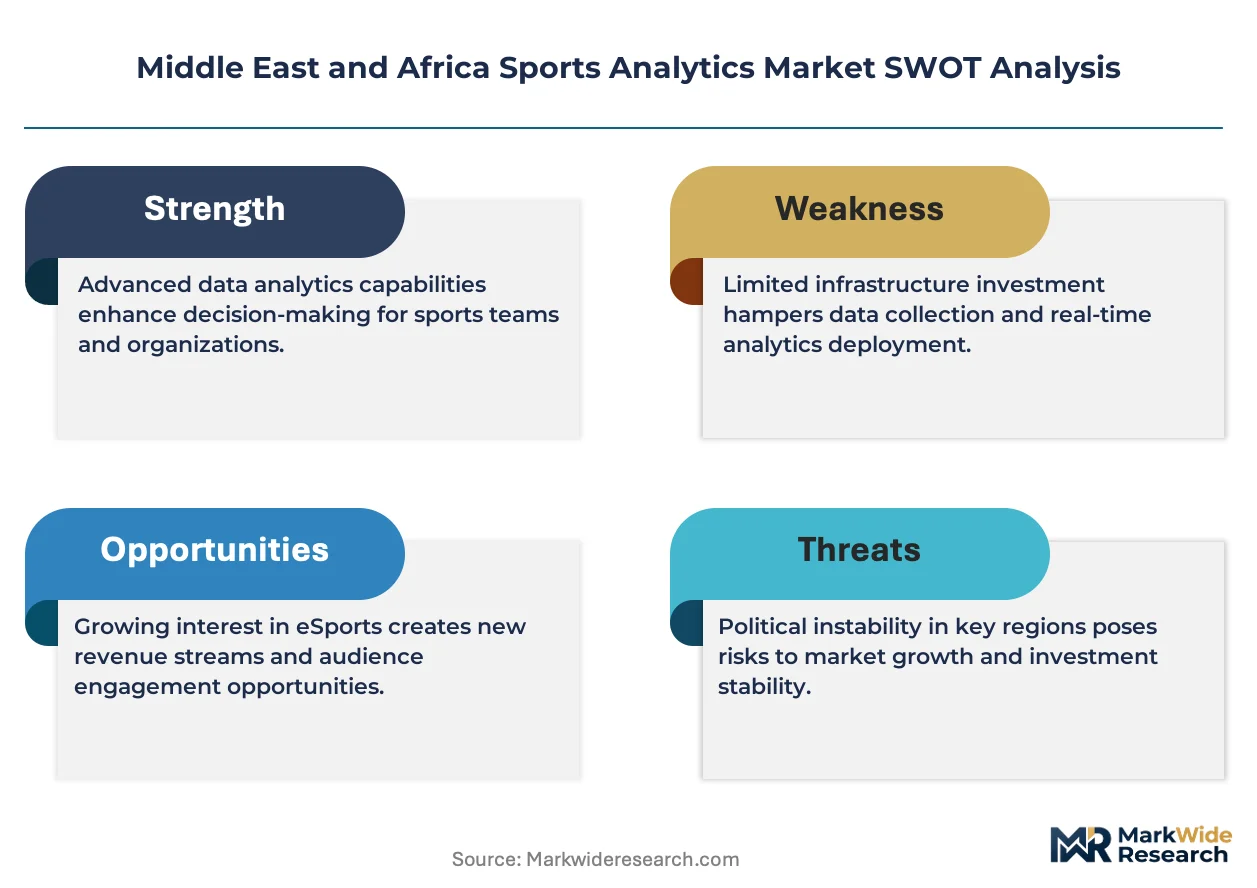
- Input Cost Volatility:Specialized edge computing hardware for stadium infrastructure faces supply concentration risk from East Asian semiconductor foundries, inflating deployment timelines for live video analysis networks.
- Regulatory Fragmentation:Divergent data governance standards between South Africa's POPIA, Saudi Arabia's SDAIA, and the UAE's NESA frameworks force vendors to maintain three parallel compliance architectures, elevating operational overhead.
- Technical Limitation:Sub-second latency requirements for real-time biometric feedback during live matches exceed current 5G network coverage in secondary African markets, restricting wearable athlete monitoring to elite urban training centers.
Strategic Opportunities
- Underpenetrated Geography:Nigeria's emerging professional basketball and football leagues lack dedicated analytics departments, creating first-mover advantage for vendors establishing localized training partnerships with Lagos-based sports academies.
- Technology Convergence:Integration of computer vision systems with sensor networks enables automated tactical pattern recognition without manual video tagging, reducing analyst staffing requirements for mid-tier clubs in Morocco and Tunisia.
- Regulatory Tailwind:Saudi Arabia's SDAIA data governance standards include provisions for AI-enabled talent scouting applications, opening procurement channels for predictive modeling platforms that automate player identification from regional youth tournaments.
Industry Challenges
- Skill Gap in Data Science:Shortage of sports-specific data analysts fluent in Arabic and familiar with regional competition structures forces vendors to import expensive technical talent or dilute platform functionality through simplified dashboards.
- Integration Complexity:Legacy on-premise video analysis systems deployed by established football clubs in Egypt and Algeria resist seamless API connection with cloud-native biometric platforms, requiring costly middleware development.
- Certification Timeline Compression:SDAIA and NESA compliance verification processes for foreign vendors extend sales cycles by 8-14 months, straining working capital for analytics startups seeking regional market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sports Analytics Market |
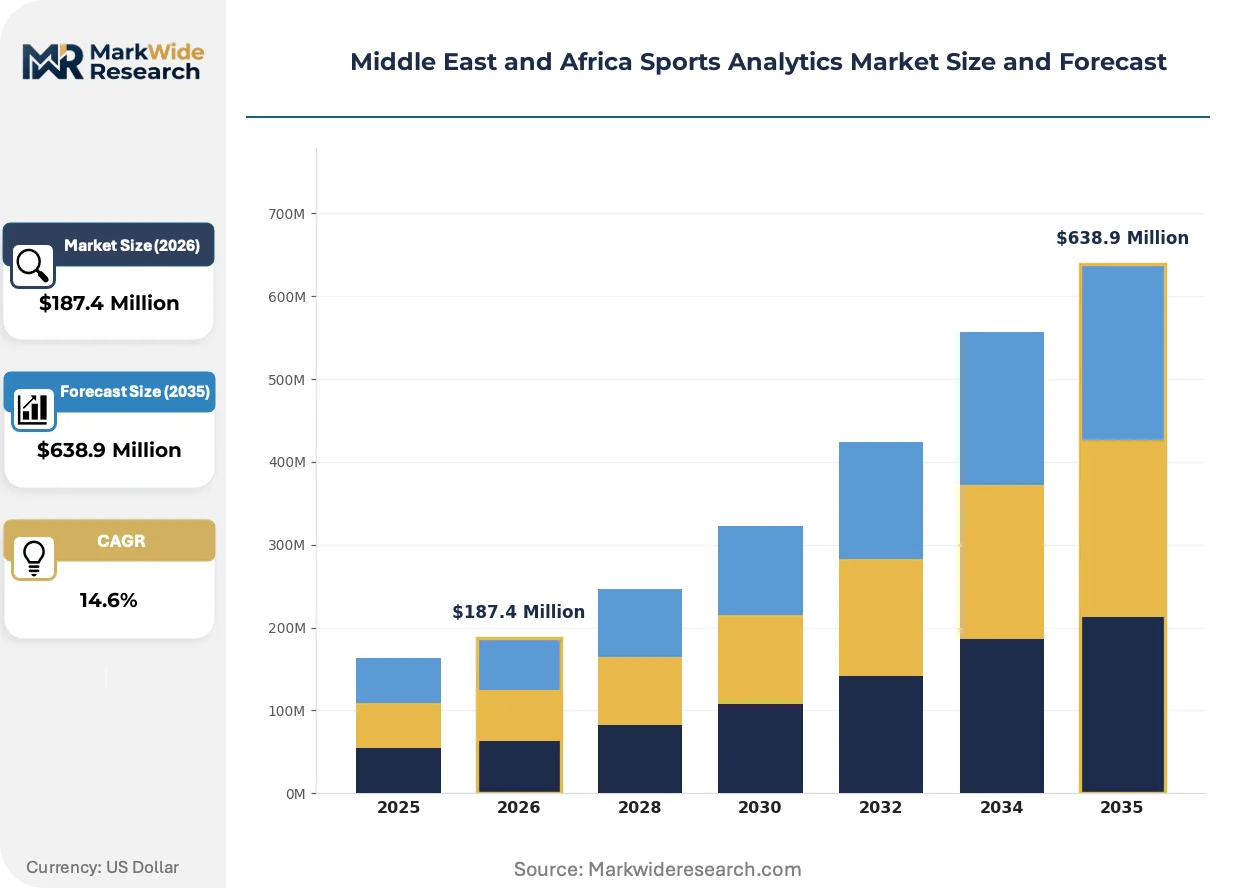
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Performance Analysis, Injury Prediction, Game Strategy, Fan Engagement End User: Sports Teams, Coaching Staff, Event Organizers, Broadcasting Networks Delivery Model: On-Premise, Cloud-Based, Hybrid, Software as a Service Market Segment: Professional Sports, Amateur Sports, Esports, College Athletics |
| Companies Covered | IBM Corporation, Sportradar AG, Catapult Group International Ltd, ChyronHego, Stats Perform, Oracle Corporation, SAS Institute Inc., Genius Sports Ltd, SAP SE, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sports Analytics Market Shifts & Advancements
Real-time processing architectures and automated decision-making systems are restructuring how performance data flows from pitch to broadcast studio, eliminating manual intervention points that previously bottlenecked tactical insight delivery.
Edge computing nodes deployed within stadium infrastructure are overtaking centralized cloud processing for live video analysis workloads. These localized processing units execute computer vision algorithms on-site, reducing bandwidth costs for high-frame-rate player tracking. Broadcasters in the UAE and Qatar are prioritizing vendors offering hybrid edge-cloud architectures that guarantee sub-500-millisecond latency for second-screen tactical overlays during premium football fixtures.
SDAIA's data governance standards in Saudi Arabia are mandating algorithmic transparency documentation for AI-driven talent scouting platforms. Vendors must now provide interpretable decision pathways for automated player ratings, shifting competitive advantage from black-box predictive accuracy toward auditable feature attribution. Football academies in Riyadh and Jeddah are inserting these explainability requirements into procurement specifications, rejecting platforms that cannot satisfy regulatory audit protocols.
Subscription-based platform access is displacing perpetual license purchases among mid-tier football clubs across the Gulf states. These organizations prefer operational expenditure models that bundle software, hardware, and analyst training into predictable monthly fees. Kenyan and Tanzanian rugby federations are piloting similar arrangements, negotiating multi-year service contracts that include dedicated technical support during international tournament windows rather than capital-intensive upfront platform acquisitions.
Middle East and Africa Sports Analytics Market Segmentation
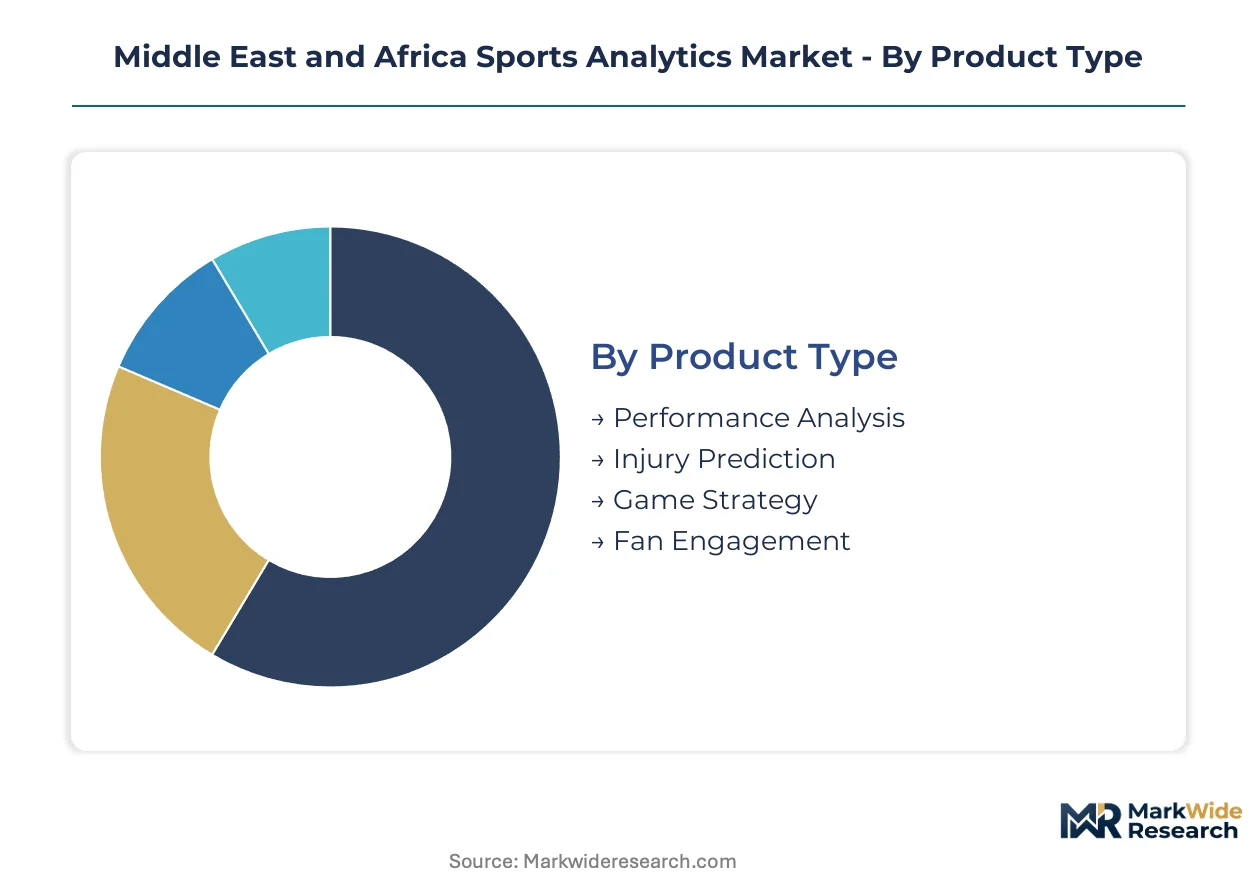
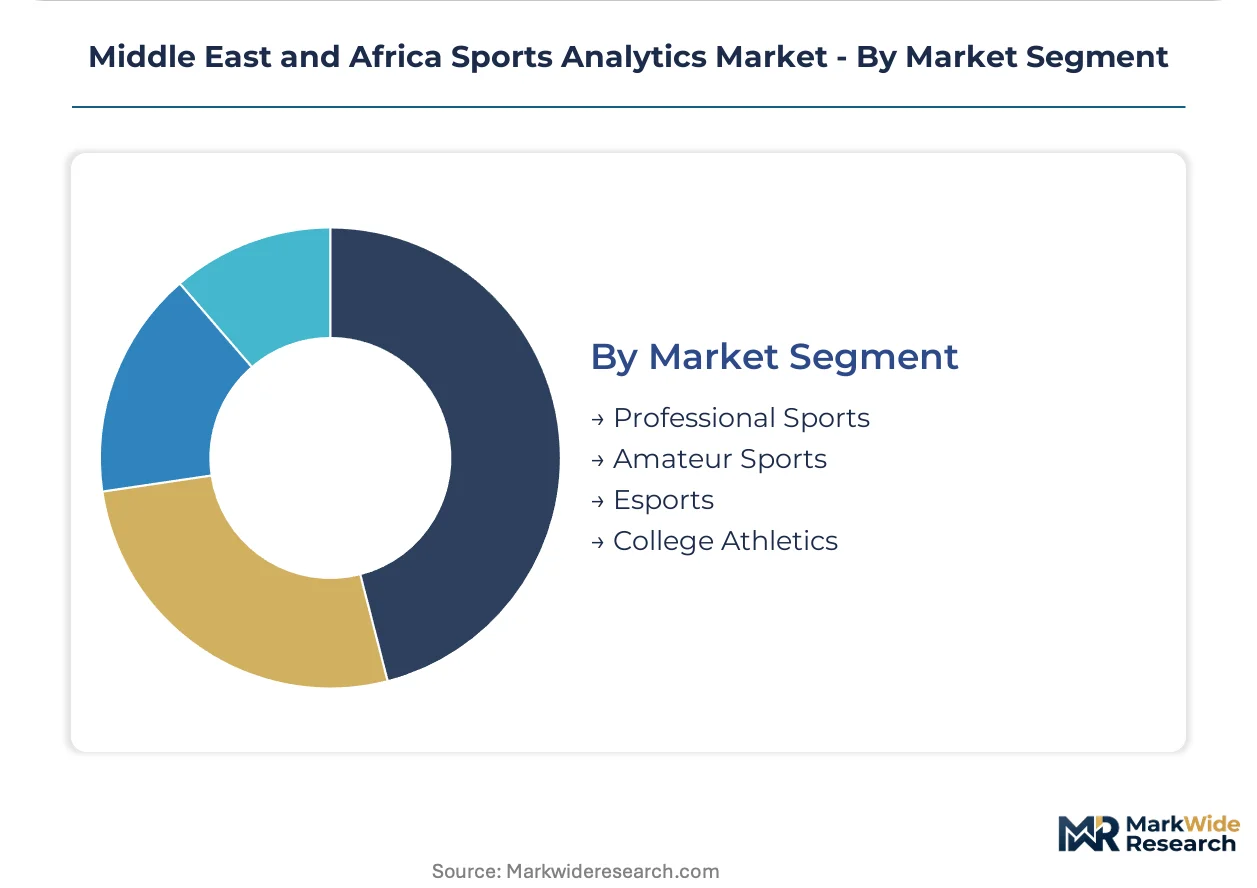
Sports analytics procurement across the Middle East and Africa fragments across four structural dimensions that determine vendor selection criteria and deployment architecture. Each segmentation axis carries distinct capital requirements, compliance obligations, and integration complexity that shape competitive positioning for platform providers.
Product Type:
Capital intensity varies sharply across product categories, with sensor hardware and edge computing infrastructure demanding the heaviest upfront investment while pure software modules require minimal physical deployment.
- Performance Analysis:Video-based tactical breakdown systems integrate computer vision algorithms with manual tagging workflows to generate UEFA-standard training insights. Gulf state football clubs in Dubai and Riyadh concentrate procurement here, driven by franchise league expansion mandates for academy certification.
- Injury Prediction:Wearable biometric platforms process accelerometer and gyroscope data through machine learning models to forecast soft-tissue injury risk. South African rugby academies and Australian-linked training programs anchor regional demand, though POPIA compliance elevates data residency costs.
- Game Strategy:Real-time decision-support tools aggregate opponent pattern recognition with simulated outcome probabilities.
- Fan Engagement:Second-screen personalization engines and predictive betting overlays serve broadcaster revenue optimization.
Performance Analysis absorbs the bulk of installed capacity; Fan Engagement is expanding most quickly.
End User:
Customer type determines pricing architecture and contract duration, with broadcasting networks favoring operational expenditure models while sports teams accept longer capital depreciation schedules.
- Broadcasting Networks:Real-time viewer engagement platforms demand sub-500-millisecond latency for tactical overlays during premium fixtures. UAE and Qatar media rights holders are redirecting analytics budgets here, compressing sales cycles for cloud-native vendors while elevating NESA data residency requirements.
- Sports Teams:Professional football and cricket clubs purchase integrated performance and injury management suites. Saudi Pro League expansion generates clustered procurement across multiple Riyadh and Jeddah academies simultaneously.
- Coaching Staff:Individual analyst tool licenses for tactical preparation and opponent scouting.
- Event Organizers:Temporary infrastructure for tournament-specific crowd flow and security analytics.
Broadcasting Networks command the steepest expansion trajectory; Sports Teams retain the largest cumulative installed base.
Delivery Model:
Deployment architecture selection hinges on telecommunications maturity and regulatory data sovereignty mandates, with hybrid configurations gaining traction as latency and compliance requirements converge.
- Cloud-Based:Federated processing architectures eliminate dedicated server farm requirements through Saudi Telecom and Etisalat infrastructure upgrades. Real-time tactical overlays now reach Gulf state federations without on-premise hardware, though SDAIA and NESA residency rules constrain vendor selection.
- Hybrid:Edge computing nodes within stadium infrastructure execute computer vision locally while pushing aggregated insights to centralized clouds. Broadcasters in Qatar prioritize this architecture for bandwidth cost reduction during high-frame-rate player tracking.
- On-Premise:Legacy installations persist among established Egyptian and Algerian clubs with legacy video analysis systems resisting API integration.
- Software as a Service:Subscription bundles combining platform access, hardware leasing, and analyst training into predictable monthly fees.
Cloud-Based configurations are gaining share fastest; On-Premise retains residual presence among North African legacy installations.
Market Segment:
Organizational maturity and revenue scale determine platform sophistication requirements, with professional tiers demanding predictive modeling while amateur segments accept simplified dashboard functionality.
- Professional Sports:Full-spectrum analytics spanning biometric monitoring, tactical analysis, and commercial optimization. UAE football franchises and Saudi Pro League clubs represent the concentrated demand center, with procurement specifications mandating UEFA-standard certification.
- Esports:Cognitive performance tracking and real-time strategic decision analysis for competitive gaming organizations.
- Amateur Sports:Cost-constrained academies in Morocco and Tunisia pilot automated tactical pattern recognition to reduce analyst staffing.
- College Athletics:Limited penetration outside South African university rugby programs with established performance departments.
Professional Sports captures the dominant revenue share; Esports is climbing the fastest among emerging categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dubai Sports City free zone concentrates analytics vendor headquarters and broadcasting technology operations, drawing procurement budgets from Gulf state federations seeking UEFA-standard certification pathways.
United Arab Emirates
NESA compliance frameworks for critical infrastructure mandate encrypted transmission protocols and local data residency for foreign vendors. Dubai's stadium infrastructure investments and franchise league expansions generate concentrated procurement of performance analysis platforms. Abu Dhabi broadcasters prioritize hybrid edge-cloud architectures guaranteeing sub-500-millisecond latency for second-screen tactical overlays.
Saudi Arabia
SDAIA data governance standards include provisions for AI-enabled talent scouting applications, opening procurement channels for predictive modeling platforms. Riyadh and Jeddah football academies insert algorithmic transparency requirements into specifications, rejecting black-box systems. The Saudi Pro League expansion generates clustered demand across multiple club academies simultaneously.
South Africa
POPIA shapes how player biometric data gets collected and stored, elevating data residency costs for wearable athlete monitoring platforms. Rugby academies and Australian-linked training programs anchor regional demand for injury prediction systems. Cape Town and Johannesburg host the primary technical talent pools for sports-specific data analysts.
Qatar
Broadcasting networks redirect analytics budgets toward real-time viewer engagement platforms, compressing sales cycles for cloud-native vendors. Doha-based media rights holders demand sub-500-millisecond latency for tactical overlays during premium football fixtures. Stadium infrastructure deployments prioritize edge computing nodes for bandwidth cost reduction during high-frame-rate player tracking.
Nigeria
Emerging professional basketball and football leagues lack dedicated analytics departments, creating first-mover advantage for vendors establishing localized training partnerships. Lagos-based sports academies represent the primary concentration for pilot automated tactical pattern recognition programs. Federal data protection guidelines remain less prescriptive than Gulf state frameworks, reducing compliance overhead for market entry.
Middle East and Africa Sports Analytics Market Competitive Landscape
Top-tier vendors anchor federation and broadcaster contracts, while mid-tier specialists compete on subscription-based platform access bundling software, hardware, and analyst training. The vendor base stratifies across three archetypes: established data partnerships controlling premium match feeds, wearable monitoring specialists serving rugby and football academies, and predictive modeling providers targeting betting operators. M&A activity concentrates on computer vision capabilities, while geographic expansion through localized training partnerships secures mid-tier club access.
Within the data partnership tier, Sportradar AG and Stats Perform exemplify contrasting approaches to match feed control and predictive tool deployment. Sportradar AG occupies a position anchored in regional football federation relationships, while Stats Perform represents the betting operator and broadcaster-facing archetype. Catapult Group International Ltd sits within the wearable monitoring specialization, serving South African rugby academies and Australian-linked training programs with athlete biometric platforms.
| Leading Market Players |
|---|
| IBM Corporation |
| Sportradar AG |
| Catapult Group International Ltd |
| ChyronHego |
| Stats Perform |
| Oracle Corporation |
| SAS Institute Inc. |
| Genius Sports Ltd |
| SAP SE |
| Others |
Supply & Pricing Matrix
Edge computing hardware costs for stadium infrastructure cascade through three distinct pricing tiers, with GPU and FPGA module expenses from East Asian foundries compressing margins for live video analysis deployments while subscription-based SaaS models absorb residual price sensitivity among mid-tier Gulf state clubs.
Pricing Analysis
Lead-time premiums dominate vendor quotations, with sub-90-day deployment guarantees commanding substantial markups from UAE broadcasters facing compressed tournament preparation windows. Three-tier pricing structure across premium, standard, and economy levels separates federation-grade platforms with NESA certification from simplified academy dashboards and basic video tagging tools. Pricing pressure stems from telecommunications infrastructure upgrades eliminating latency barriers that previously justified on-premise hardware premiums. Mid-tier Moroccan and Tunisian clubs exhibit acute price sensitivity, while Saudi Pro League franchises prioritize UEFA-standard certification over cost minimization.
Supply Chain Analysis
Refurbished sensor networks and redeployed edge computing nodes from Qatar's tournament infrastructure are entering secondary markets across Nigeria and Kenya, extending hardware lifecycles and depressing new equipment demand. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with specialized AI accelerators for computer vision drawing from TSMC and Samsung foundry capacity. Raw material dependencies span silicon wafers, rare-earth magnets for wearable gyroscopes, and high-purity copper for stadium cabling infrastructure. Single-source vulnerability in advanced GPU supply chains threatens deployment timelines for real-time biometric platforms. Distribution runs through Dubai Sports City free zone logistics hubs serving Gulf state federations and Lagos-based channel partners penetrating West African academies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa sports analytics market is consolidating around control of data pipeline infrastructure, with federation partnerships and local data residency capabilities serving as the decisive vertical-integration levers separating tier-one vendors from commoditized platform providers.
For Market Incumbents: Deploy algorithmic transparency documentation capabilities to preempt SDAIA audit requirements in Saudi Arabia and NESA compliance verification in the UAE. Secure exclusive data partnership renewals with regional football federations before franchise league expansions trigger competitive tendering. Deepen backward integration into edge computing hardware assembly through partnerships with Dubai-based system integrators, reducing exposure to East Asian semiconductor supply concentration. For New Entrants and Emerging Players: Launch via subscription-based platform access bundled with Arabic-language analyst training to bypass capital constraints at Nigerian basketball academies and Lagos-based football development programs. Target Morocco and Tunisia for automated tactical pattern recognition pilots, where mid-tier clubs lack dedicated performance departments and accept simplified dashboard functionality. Establish localized training partnerships with Riyadh and Jeddah football academies to satisfy SDAIA algorithmic interpretability mandates before predictive modeling incumbents entrench. For Investors and Strategic Acquirers: SDAIA's publication of interpretable AI scouting platform procurement specifications is the leading indicator that Saudi Arabia will mandate auditable decision pathways across talent identification applications, elevating compliant vendors above black-box competitors. Long-term viability rests on federation relationship durability and data sovereignty architecture rather than algorithmic performance alone. Target acquisition archetypes include computer vision specialists with existing NESA certification and regional federations with captive match data feeds. Monitor UAE Ministry of Interior critical infrastructure designation expansions for early signals of additional data residency requirements affecting broadcaster contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Computer Vision Acquisition | Automated tactical pattern recognition eliminates manual video tagging costs for mid-tier North African clubs. |
| Federation Data Partnership | Exclusive match feed access creates defensive moats against cloud-native challengers in Gulf state markets. |
| Local Data Residency Buildout | SDAIA and NESA compliance certification extends sales cycles but locks out non-compliant foreign competitors. |
| Edge Computing Node Deployment | Stadium infrastructure processing reduces bandwidth expenditures for high-frame-rate player tracking during premium fixtures. |
| Subscription Model Transition | Predictable operational expenditure structures align with mid-tier club budget constraints across Kenya and Tanzania. |
Research Methodology
Federation annual reports, telecommunications infrastructure disclosure filings, and sports technology trade publications formed the secondary backbone, supplemented by customs records tracking edge computing hardware imports into Dubai Sports City free zone. Primary interviews with performance analysis directors at Saudi Pro League clubs, broadcasting technology procurement officers in Abu Dhabi and Doha, and data protection compliance leads navigating POPIA implementation in South Africa validated segmentation assumptions. Bottom-up demand modeling triangulated against top-down market sizing from regional IT expenditure surveys.
Historical trendline analysis of analytics platform procurement across franchise league expansion cycles informed projection frameworks, with CAGR derivation incorporating telecommunications latency improvement trajectories and regulatory compliance timeline compression. Segmentation dimensions spanned product type, end user archetype, delivery model architecture, and market segment maturity tier. Industry-specific forecast inputs included stadium infrastructure investment pipelines from Gulf state sovereign wealth disclosures and AI governance standard evolution timelines from SDAIA and NESA regulatory publications.
The model assumes a particular technology adoption path; alternative pathways for 5G network coverage expansion in secondary African markets would alter the outlook for wearable athlete monitoring penetration outside elite urban training centers. Forecasts reflect assumptions regarding federation data partnership renewal rates and compliance verification timeline standardization across Gulf Cooperation Council members. Practitioners should monitor SDAIA algorithmic transparency audit protocol publications and NESA critical infrastructure designation expansions for early signals of procurement specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
North America Fantasy Sports Market
Sports Analytics
Player Tracking System Market
Sports Analytics
Global Player Tracking Market
Sports Analytics
India Fantasy Sports Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
Sports Analytics Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Youth Sports Software Market
Sports Analytics
Fantasy Sports Market
Sports Analytics
Daily Fantasy Sports Market