
 PE Sports Turf Market | 2026-2036
PE Sports Turf Market Size, Share, and Industry Trends Forecast 2026-2036
PE Sports Turf Market Insights
FIFA Quality Programme certification is unwinding the competitive landscape, forcing smaller installers to exit or partner with accredited manufacturers. TenCate Grass leverages its vertical integration from polymer extrusion to field installation to sustain pricing power across European stadium contracts. Shaw Sports Turf anchors its position through dedicated R&D facilities in Georgia that specialize in cooling infill technologies for high-heat climates. FieldTurf Tarkett competes aggressively on municipal bids in North America by controlling regional distribution networks and offering bundled maintenance contracts.
PE sports turf consists of polyethylene monofilament or slit-film yarns tufted into porous backings, typically incorporating UV stabilizers and anti-static agents to withstand intensive cleat traffic across seasonal cycles. Its primary purpose is to deliver consistent ball bounce, rotational resistance, and drainage performance for competitive play regardless of ambient weather. Monofilament yarns command premium positioning due to superior resilience and aesthetic uniformity, while slit-film variants dominate volume in educational and municipal segments where budget constraints override performance thresholds. Hybrid installation systems that combine natural grass root zones with polyethylene reinforcement represent the fastest-growing configuration among professional venues seeking broadcast-quality surfaces.
EPA guidelines on crumb rubber infill leachate and REACH restrictions on zinc and PAH content in synthetic turf components are reshaping material specifications and supplier qualification requirements across the United States and European Union. FIFA's ongoing revision of player-surface interaction protocols, combined with state-level procurement mandates in California and New York, will determine which manufacturers retain access to publicly funded projects. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
FIFA Quality Programme certification requirements are compressing supplier margins while consolidating procurement authority among accredited manufacturers with full polymer-to-field capabilities.
Growth Catalysts
- REACH restrictions on zinc and PAH content:European manufacturers are accelerating reformulation of infill compounds and backing adhesives to retain stadium certification eligibility.
- Hybrid reinforcement systems:Professional football venues in Germany and England are adopting polyethylene-root-zone combinations to extend broadcast-quality surface hours.
- Municipal stadium renovations:German Bundesliga venue upgrades and city-owned facility modernizations are compressing procurement cycles for full-system replacements.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene resin prices fluctuate with naphtha and ethylene spot markets, compressing margin predictability for yarn extruders.
- Crumb rubber infill substitution pressure:EPA guidelines on leachate testing and parent concerns in school districts are constraining specification options for budget-tier installations.
- Installation labor concentration:Accredited field construction crews cluster in Germany, the Netherlands, and northern Italy, creating bottlenecks for multi-site rollout schedules.
Strategic Opportunities
- Cooling infill technologies:Shaw Sports Turf's Georgia R&D facilities are commercializing temperature-mitigating compounds for high-heat climate penetration.
- Bundled maintenance contracts:North American municipal bids now favor decade-long service agreements over transactional field sales, locking in recurring revenue streams.
- State-level procurement mandates:California and New York procurement codes are disqualifying non-certified suppliers from publicly funded school and park projects.
Industry Challenges
- FIFA certification timeline compression:Laboratory testing for ball roll, rotational resistance, and drainage performance now extends 14-18 months, delaying revenue recognition.
- Legacy natural grass integration:Hybrid system installers must coordinate with living turf agronomists, doubling project management complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PE Sports Turf Market |
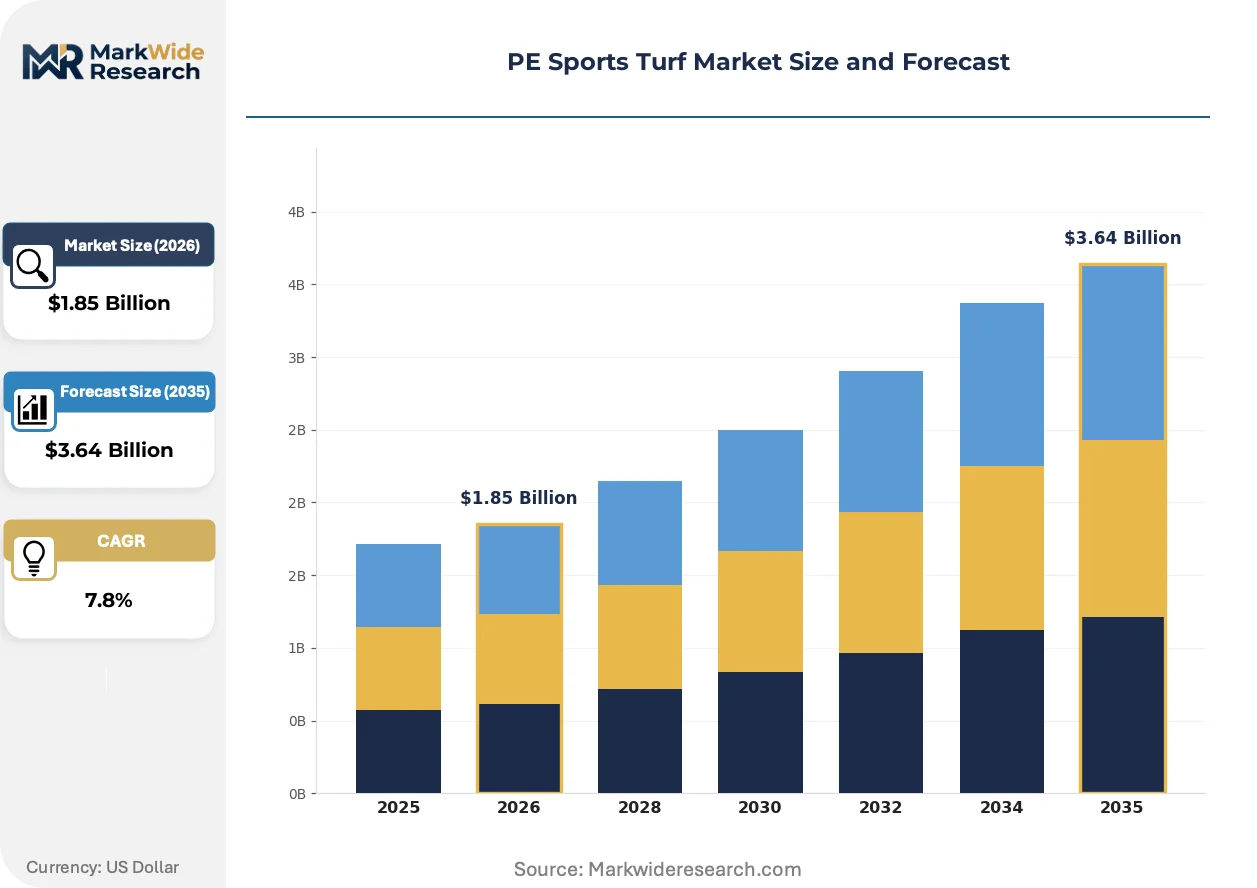
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofilament, Fibrillated, Blended, Slit Film, Texturized Application: Football Fields, Tennis Courts, Golf Courses, Athletics Tracks, Riding Arenas End User: Sports Clubs, Educational Institutions, Municipal Authorities, Recreation Centers Installation Type: Infill, Non-Infill, Hybrid, Modular Systems, Backed Systems |
| Companies Covered | TenCate Grass, Shaw Sports Turf, FieldTurf Tarkett, AstroTurf, SIS Pitches, AktivTurf, GreenFields, SYNLawn, NexGen Turf International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PE Sports Turf Market Trends and Innovations
Material science advances and regulatory tightening are fragmenting specification standards while creating tiered performance categories that reward captive supply chains.
Monofilament yarn construction is decomposing the historical dominance of slit-film variants in premium segments. Bundesliga and Premier League groundskeepers specify monofilament for rotational resistance consistency and aesthetic uniformity under broadcast lighting. This shift is compressing volume share for commodity slit-film producers without extrusion-to-installation integration.
EPA guidelines on synthetic turf infill leachate are forcing reformulation of crumb rubber compounds across the United States. Manufacturers must submit to third-party testing for heavy metal migration and polycyclic aromatic hydrocarbon content. California school districts and New York municipal parks departments now require pre-approval documentation before bid submission.
Buyer preference is migrating toward performance-guaranteed service contracts rather than capital expenditure field purchases. North American municipalities and European municipal stadium authorities now prioritize decade-long surface performance warranties with bundled maintenance. This shift is visible most acutely in German city-owned venues and California school district procurement cycles.
PE Sports Turf Market Segmentation
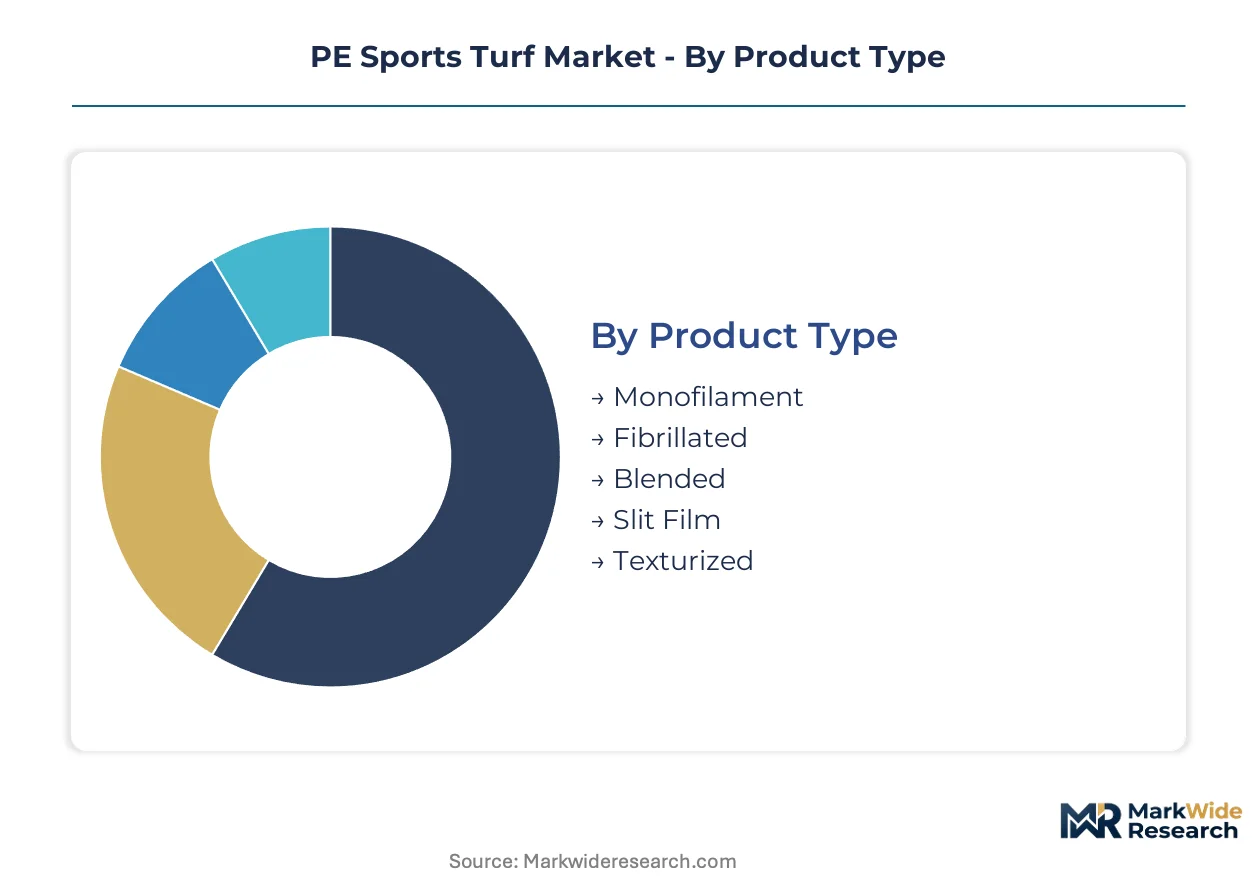
Polyethylene sports turf specifications fragment across performance tiers, installation methods, and end-user procurement authority. Understanding segment boundaries reveals where FIFA certification requirements reshape supplier access and margin structures.
Product Type:
Monofilament yarn production concentrates in Germany and the Netherlands for European stadium exports, while slit-film extrusion serves domestic educational markets across multiple countries.
- Monofilament:Individual polymer filaments deliver superior rotational resistance and aesthetic uniformity under broadcast lighting. Bundesliga and Premier League venues specify these yarns for extended playable hours, compressing procurement cycles for certified extruders.
- Slit Film:Flattened tape yarns dominate municipal and educational volume where budget constraints override performance thresholds. German city parks departments and California school districts favor these specifications for cost-controlled replacements.
- Fibrillated:Split-fiber construction creates textured surfaces for multi-use community fields requiring moderate durability.
- Blended:Hybrid yarn constructions combine monofilament resilience with slit-film economy for mid-tier athletic facilities.
- Texturized:Curled or crimped filaments enhance infill retention and surface softness for equestrian and training applications.
Slit Film holds the largest share; momentum sits with Monofilament.
Application:
Football field installations generate premium pricing through FIFA Quality Programme mandates, while tennis and golf applications follow country-specific sporting federation standards.
- Football Fields:Professional and municipal pitches require ball roll consistency, drainage performance, and rotational resistance certification. German Bundesliga venue upgrades and English Football League stadium renovations concentrate demand among accredited installers.
- Tennis Courts:Hard-court replication surfaces demand precise bounce characteristics and pace control. Club installations in France and Spain follow national federation surface guidelines.
- Golf Courses:Driving range mats and practice greens utilize specialized pile heights for club interaction simulation.
- Athletics Tracks:Surfaces prioritize spike resistance and all-weather traction for training and competition.
- Riding Arenas:Equestrian facilities require dust suppression and cushioning for hoof impact absorption.
Football Fields generate the highest revenue per square meter; Riding Arenas are climbing fastest as equestrian centers modernize.
End User:
Municipal procurement offices control the steepest volume expansion through bundled maintenance contracts, while sports clubs concentrate premium specification authority.
- Sports Clubs:Professional and semi-professional organizations demand broadcast-quality surfaces with decade-long performance warranties. German football clubs and English rugby unions specify hybrid reinforcement systems.
- Municipal Authorities:City-owned stadiums and parks departments prioritize lifecycle cost through service-contract procurement. California and New York procurement codes now disqualify non-certified suppliers.
- Educational Institutions:School districts balance budget constraints against parent safety concerns regarding infill composition.
- Recreation Centers:Multi-use community facilities favor durability and low maintenance for high-traffic programming.
Municipal Authorities command the greatest volume; Sports Clubs drive specification upgrades.
Installation Type:
Infill systems face regulatory substitution pressure in the United States, while hybrid configurations gain professional venue adoption in Europe.
- Hybrid:Polyethylene reinforcement integrated with natural grass root zones extends broadcast-quality surface hours. German and English professional football venues adopt these systems for reduced maintenance intervals.
- Infill:Sand and crumb rubber or alternative compounds provide stability, cushioning, and traction. EPA leachate guidelines and REACH restrictions force reformulation of rubber compounds.
- Non-Infill:Dense turf constructions eliminate loose material requirements for simplified maintenance.
- Modular Systems:Interlocking panels enable temporary deployment and surface reconfiguration.
- Backed Systems:Reinforced secondary layers enhance dimensional stability for intensive use patterns.
Infill retains volume leadership; Hybrid configurations are expanding most quickly among professional venues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal stadium authorities and professional football clubs concentrate procurement authority in Germany, with Bundesliga venue upgrades compressing installation timelines. REACH restrictions on zinc and PAH content are forcing reformulation across European supply chains. California school districts and New York municipal parks departments now require pre-approval documentation before bid submission.
Germany
Bundesliga venue upgrades and city-owned facility modernizations are accelerating full-system replacement cycles. ECHA REACH restrictions on zinc content in synthetic turf components are disqualifying non-compliant infill compounds from stadium certification eligibility. Industrial clusters in North Rhine-Westphalia and Bavaria host accredited extrusion-to-installation operations serving domestic and export stadium contracts.
United States
California school districts and New York municipal parks departments are tightening procurement codes around crumb rubber infill safety documentation. EPA guidelines on synthetic turf leachate testing are forcing third-party validation of heavy metal migration before contract award. Georgia-based R&D facilities are commercializing temperature-mitigating infill compounds for high-heat climate penetration.
United Kingdom
English Football League stadium renovations and rugby union venue specifications are concentrating demand for hybrid reinforcement systems. FIFA Quality Programme certification requirements are compressing supplier margins while consolidating procurement authority among accredited manufacturers. Industrial capacity clusters in the Midlands and northern England coordinate living turf agronomists with polyethylene reinforcement installers.
Netherlands
Tufting and backing operations serve as export hubs for European stadium and municipal contracts. ECHA REACH restrictions on PAH content in adhesives are accelerating reformulation of backing compounds to retain certification eligibility. The Randstad region maintains accredited field construction crews that create bottlenecks for multi-site rollout schedules across continental projects.
France
Tennis club installations and national federation surface guidelines are driving hard-court replication specifications with precise bounce characteristics. ECHA REACH compliance deadlines are forcing infill compound reformulation ahead of certification renewal cycles. Industrial operations in Île-de-France and Auvergne-Rhône-Alpes serve domestic sporting federation contracts and adjacent export markets.
PE Sports Turf Market Competitive Landscape
Player mix skews toward vertically integrated polymer-to-field specialists and regional installation contractors with FIFA accreditation. Market structure concentrates procurement authority among manufacturers with captive extrusion capabilities and certified field construction crews. Three archetypes dominate: integrated polymer-to-field operators, regional installation specialists with bundled maintenance capabilities, and commodity yarn extruders serving budget-tier educational segments. Competitive moves center on strategic partnerships for certification access and geographic expansion through regional distribution network control.
Among integrated specialists, TenCate Grass and Shaw Sports Turf occupy positions defined by upstream polymer operations and dedicated R&D facilities. FieldTurf Tarkett exemplifies the regional-contractor archetype with bundled maintenance capabilities. These three represent distinct competitive vectors: captive supply chain control, temperature-mitigation technology development, and municipal bid aggregation through service-contract bundling.
| Leading Market Players |
|---|
| TenCate Grass |
| Shaw Sports Turf |
| FieldTurf Tarkett |
| AstroTurf |
| SIS Pitches |
| AktivTurf |
| GreenFields |
| SYNLawn |
| NexGen Turf International |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month FIFA certification timelines compress inventory turns for yarn extruders and concentrate pricing power among accredited manufacturers with polymer-to-field capabilities. This lead-time band forces buyers into long-term offtake commitments that insulate integrated suppliers from spot resin volatility while squeezing margin for non-certified competitors.
Pricing Analysis
Cost-plus contracts with naphtha-indexed polyethylene resin clauses dominate procurement for municipal and professional stadium segments. Three-tier pricing structure across FIFA-certified premium, standard institutional, and economy educational levels separates monofilament yarn systems from slit-film alternatives. Cost compression in budget-tier installations intensifies because REACH-compliant infill compounds carry formulation premiums. California school districts exhibit highest price sensitivity due to crumb rubber substitution mandates, while Bundesliga clubs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Inventory compression at accredited field construction crews in Germany, the Netherlands, and northern Italy creates installation bottlenecks that extend project timelines. Polyethylene resin extrusion concentrates in Germany, the United States, and China, with tufting operations clustered in the Netherlands and England. Raw material dependencies rest on naphtha-derived ethylene, UV stabilizer additives, and ECHA-compliant backing adhesives. Single-source vulnerability sits with certified installation labor pools. Distribution runs through manufacturer-direct stadium contracts and regional distributor networks for municipal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward municipal procurement offices that aggregate decade-long bundled maintenance contracts, consolidating volume among fewer accredited suppliers and fragmenting access for non-certified manufacturers.
For Market Incumbents: Secure captive polymer extrusion capacity in North Rhine-Westphalia or Bavaria to defend against REACH reformulation cost shocks. Deepen backward integration into cooling infill compound R&D to differentiate from commodity yarn producers facing margin erosion from EPA leachate documentation requirements.
For New Entrants and Emerging Players: Lead with alternative infill technologies—cork, coconut, or thermoplastic elastomers—to penetrate California and New York school districts where crumb rubber disqualification creates specification white space. Target mid-tier European municipal stadium renovations with hybrid system expertise bypassing FIFA certification backlog through agronomist partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification barriers and bundled service contract preferences favor scaled polymer-to-field operators over fragmented installation contractors. Monitor ECHA REACH enforcement intensity as inflection signal for reformulation cost pass-through viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captive resin supply insulates TenCate Grass and Shaw Sports Turf from naphtha spot volatility. |
| Cooling Infill Technology Commercialization | Shaw's Georgia R&D facilities target high-heat climate penetration with temperature-mitigating compounds. |
| Hybrid System Certification Investment | Living turf agronomist coordination doubles project complexity but locks in Bundesliga venue access. |
| Bundled Maintenance Contract Aggregation | FieldTurf Tarkett's decade-long service agreements lock recurring revenue from North American municipalities. |
| Alternative Infill Compound Development | EPA and REACH compliance pressures force reformulation away from crumb rubber toward cork or thermoplastic elastomers. |
Research Methodology
The analysis maps monofilament yarn, slit-film, hybrid installation, and infill compound sub-sectors, each validated through interviews with FIFA-accredited field construction crews, municipal stadium procurement officers, polymer extrusion plant managers, and synthetic turf R&D directors. Secondary validation draws from ECHA REACH compliance databases, EPA synthetic turf leachate guidelines, FIFA Quality Programme certification records, and Bundesliga venue upgrade announcements. Bottom-up unit economics triangulate against top-down polyethylene resin consumption estimates.
Consistency checks against naphtha-ethylene spread indices and stadium construction permit data validate volume and value outputs across the projection horizon. Segmentation dimensions model product type, installation configuration, end-user procurement authority, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, FIFA certification throughput constraints, and REACH reformulation cost curves.
Underlying assumptions cover stable naphtha feedstock availability and ECHA enforcement continuity, with deviation risk concentrated in EPA guideline expansion to additional states and hybrid system agronomist labor shortages. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Golf Club Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
Rowing Machine Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Portable Basketball Hoops Market
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Cycling Sunglasses Market