
 Sports and Athletic Insoles Market | 2026-2036
Sports and Athletic Insoles Market Size, Share, and Industry Trends Forecast 2026-2036
Sports and Athletic Insoles Market Analytics
Podiatric technician availability is collapsing across North American and European manufacturing hubs, forcing brands to automate production or relocate mold-making operations. Superfeet leverages its proprietary carbon fiber stabilization plate technology to sustain premium positioning in specialty running channels. Bauerfeind anchors its European manufacturing base while competing aggressively in Asian markets through medical-grade orthotic certifications.
Sports and athletic insoles are biomechanical inserts engineered from multi-density foams, thermoplastic polymers, or carbon fiber composites, manufactured through heat-moldable, CAD-milled, or 3D-printed processes to redistribute plantar pressure and correct gait abnormalities during high-impact activity. Their primary commercial purpose is to reduce repetitive stress injuries in competitive and recreational athletes while extending footwear functional lifespan. Orthotic insoles command the highest margin pools due to prescription-grade customization requirements, while gel insoles dominate volume through pharmacy chain and mass retail penetration. Carbon fiber materials represent the fastest-growing material segment as elite athletes prioritize stiffness-to-weight ratios for explosive performance.
FDA oversight of medical device classifications, REACH chemical compliance for polyurethane and thermoplastic formulations, and ISO 9001 quality management standards collectively shape product liability exposure and export market access for manufacturers. The EU Green Deal's evolving restrictions on petroleum-based foam feedstocks are forcing material suppliers to certify bio-based alternatives or risk exclusion from European distribution channels. Stakeholders must monitor regulatory divergence between medical-grade and consumer-grade classification thresholds to anticipate where compliance costs will concentrate.
Market Dynamics
3D-printed lattice midsole structures are bifurcating production economics between automated high-volume hubs and artisan mold-making operations, compressing lead times from weeks to hours while eliminating podiatric technician bottlenecks across Germany and the United States manufacturing clusters.
Growth Catalysts
- Marathon participation surge:China's domestic race calendar and government fitness campaigns are accelerating consumer spending on performance footwear accessories in tier-one cities.
- REACH chemical compliance:European bio-based polyurethane certification requirements are forcing material suppliers to innovate sustainable foam feedstocks ahead of EU Green Deal enforcement timelines.
- Carbon fiber stiffness-to-weight ratios:Elite track and field programs are specifying composite stabilization plates for explosive power transfer in sprint disciplines.
Market Restraints
- Petroleum-based foam feedstock volatility:Polyurethane precursor costs fluctuate with crude oil indices, squeezing margin pools for mid-tier gel insole manufacturers.
- Podiatric technician scarcity:North American and European mold-making labor pools are contracting, constraining custom orthotic throughput regardless of automation investments.
- FDA medical device classification friction:Prescription-grade insoles face extended 510(k) review timelines that delay commercialization of next-generation pressure-mapping technologies.
Strategic Opportunities
- Underpenetrated Southeast Asian fitness markets:Indonesia and Vietnam marathon participation rates trail China by a factor of five, creating whitespace for entry-level performance insole distribution.
- Dual carbon goals alignment:China's MEE bio-based material incentives reward manufacturers certifying plant-derived thermoplastic formulations for domestic consumption.
- Direct-to-athlete digital channels:CAD-scanning smartphone applications are displacing brick-and-mortar gait analysis, enabling remote custom insole ordering from training facilities.
Industry Challenges
- ISO 9001 quality management certification timelines:New production facilities face 18-month accreditation periods that delay export market entry to European Union distribution channels.
- Legacy heat-moldable process integration:Hybrid manufacturing lines must reconcile traditional foam casting equipment with additive manufacturing cells, creating workflow friction and scrap rate volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports and Athletic Insoles Market |
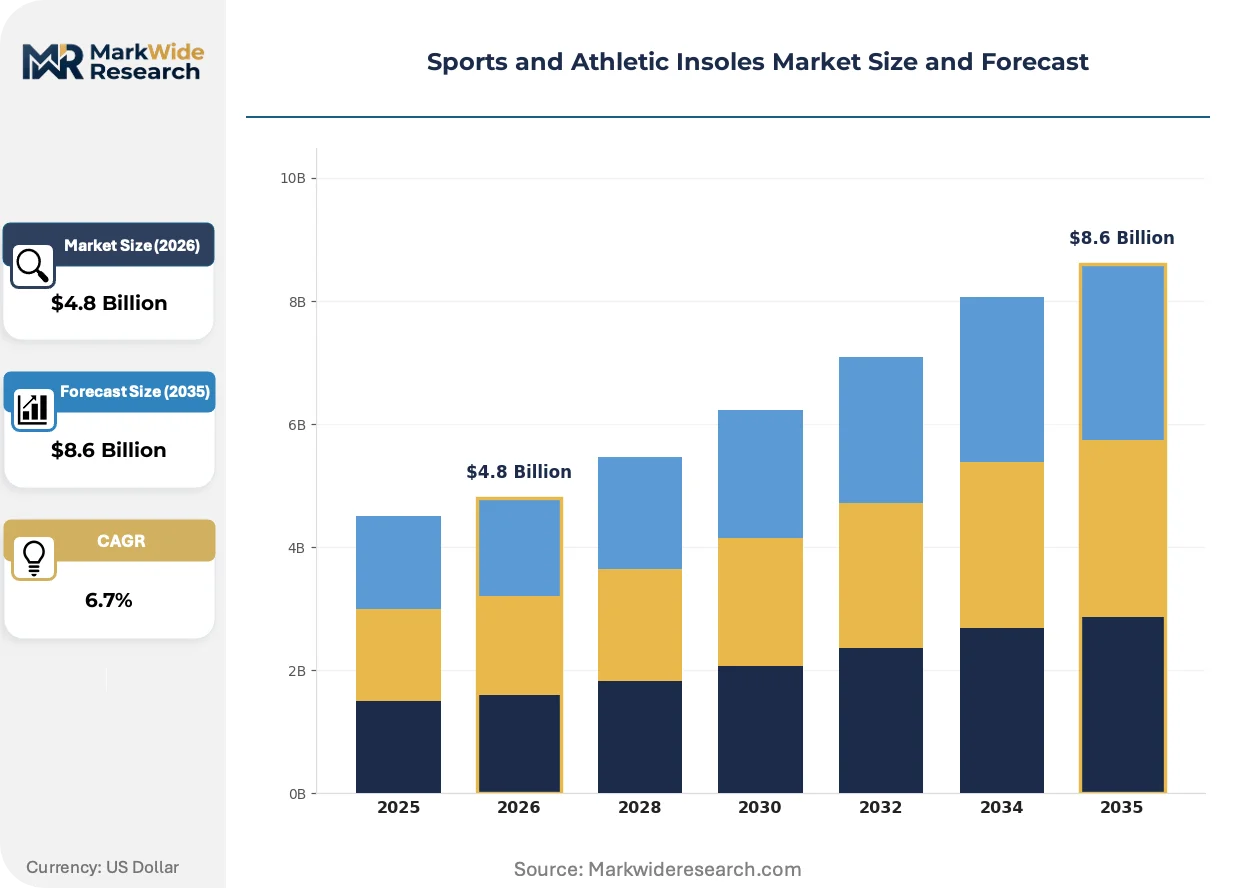
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Insoles, Cushioned Insoles, Gel Insoles, Arch Support Insoles End User: Professional Athletes, Recreational Users, Coaches, Trainers Material: Foam, Thermoplastic, Carbon Fiber, Leather Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Pharmacy Chains |
| Companies Covered | Dr. Scholl's, Superfeet, Spenco, PowerStep, Protalus, Aetrex Worldwide, Bauerfeind, Foot Science International, Currex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports and Athletic Insoles Market Evolving Landscape
Biomechanical personalization is migrating from clinical settings to consumer-controlled platforms, compressing the customization cycle while fragmenting authority between podiatrists, athletic trainers, and self-service algorithms.
Multi-density foam formulations are bifurcating the market between pharmacy-chain commodity gel insoles and prescription-grade orthotic systems. Recreational runners now access entry-level plantar pressure redistribution through mass retail, while competitive athletes demand CAD-milled or 3D-printed lattice structures calibrated to individual gait signatures. This split is compressing mid-tier brand positioning and forcing portfolio stratification across premium and economy tiers.
EU Green Deal evolving restrictions on petroleum-based foam feedstocks are accelerating bio-based alternative certification among European material suppliers. Manufacturers failing to secure REACH-compliant polyurethane or thermoplastic formulations risk exclusion from continental distribution channels. Orthotic insole producers with medical-grade certifications are absorbing compliance costs fastest, while consumer-grade gel insole brands face margin compression from reformulation expenses.
After-sales service unbundling is disrupting traditional specialty running store value propositions. Athletes increasingly purchase insoles through direct digital channels, then seek independent gait analysis or self-calibrate via smartphone pressure-mapping applications. This pattern concentrates in China's tier-one cities where domestic e-commerce platforms integrate fitness tracking data with personalized product recommendations, bypassing conventional brick-and-mortar fitting consultations.
Sports and Athletic Insoles Market Segmentation
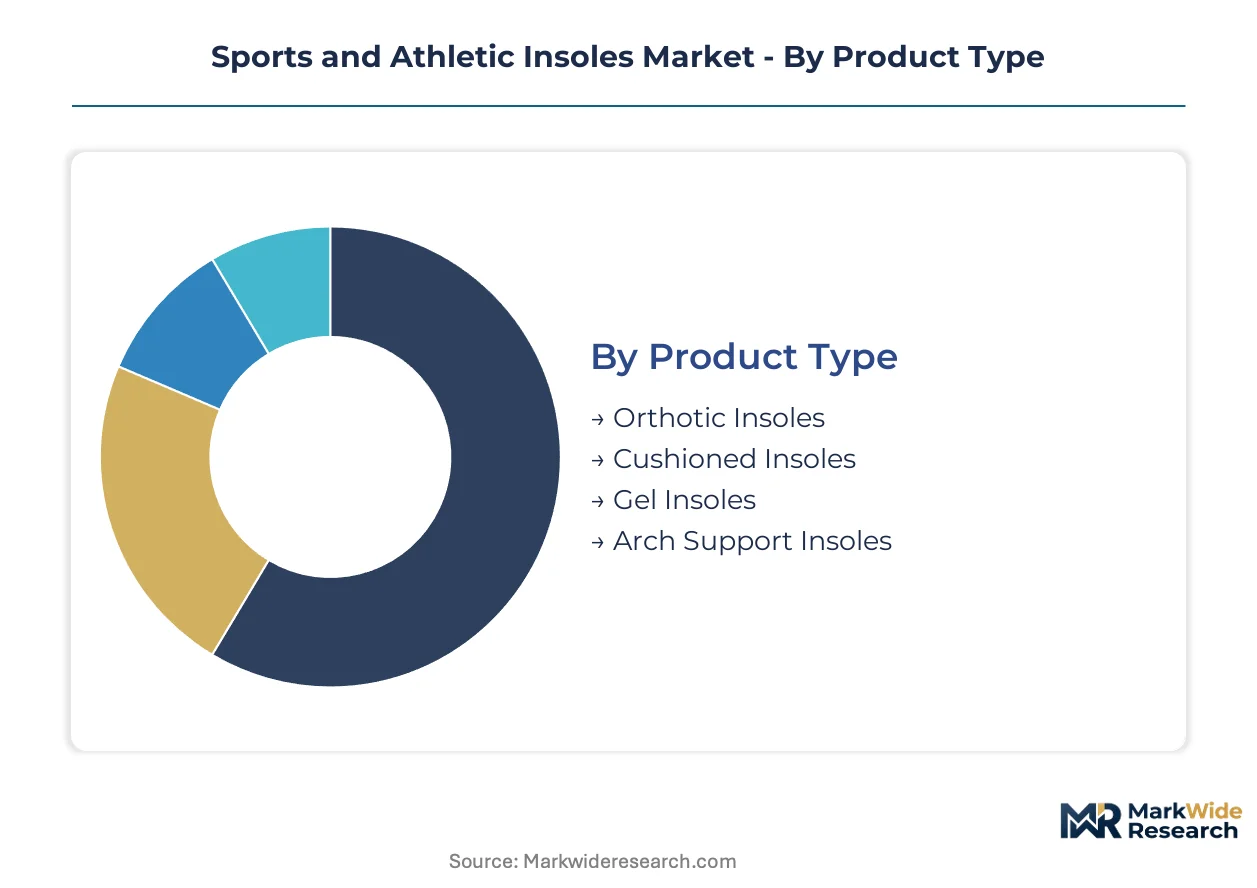
Segmentation in sports and athletic insoles reveals how regulatory thresholds, material specifications, and channel economics partition commercial opportunity. Manufacturers must align certification grade with distribution strategy to capture margin pools effectively.
Product Type:
FDA medical device classifications and EU MDR compliance requirements create divergent margin structures across prescription versus consumer-grade categories.
- Orthotic Insoles:Engineered from multi-density thermoplastics and CAD-milled or 3D-printed substrates to correct biomechanical gait abnormalities under clinical supervision. Prescription-grade demand concentrates in Germany and the United States where podiatric referral networks and insurance reimbursement codes sustain premium pricing.
- Cushioned Insoles:Multi-layer EVA or polyurethane foam constructions absorb repetitive impact forces during high-mileage training. Marathon participation surges in China's tier-one cities are accelerating retail uptake among recreational runners seeking entry-level plantar protection.
- Gel Insoles:Viscous silicone or thermoplastic elastomer pads distribute pressure across high-friction zones.
- Arch Support Insoles:Semi-rigid polymer frames with contoured medial posting for flat-foot correction.
Orthotic Insoles handles the majority of throughput; Cushioned Insoles is the fastest mover on share.
End User:
Procurement authority and volume scale separate institutional buyers from individual consumers across this dimension.
- Professional Athletes:Elite competitors specify carbon fiber composite stabilization plates and custom-molded lattice structures calibrated to individual biomechanical signatures. Track and field programs in the United States and Germany are expanding 3D-printed insole procurement for explosive power transfer optimization.
- Recreational Users:Weekend runners and fitness enthusiasts purchase mass-market gel or foam inserts through pharmacy chains and e-commerce platforms. China's government fitness campaigns are swelling this segment fastest as domestic marathon participation multiplies.
- Coaches:Team-level buyers sourcing standardized insole inventories for athletic programs.
- Trainers:Independent fitness professionals recommending specific support levels to individual clients.
Recreational Users dominates volume throughput; Professional Athletes commands the steepest expansion trajectory in absolute spend per capita.
Material:
REACH chemical compliance and China's MEE bio-based certification programs are reshaping supplier qualification requirements across feedstock categories.
- Carbon Fiber:Woven composite sheets and unidirectional tapes deliver maximum stiffness-to-weight ratios for sprint disciplines and jumping events. Elite athletic programs in Germany and the United States are specifying these materials for custom orthotic fabrication despite premium cost positions.
- Thermoplastic:Heat-moldable polymers including polypropylene and polyethylene variants enable podiatric technicians to customize fit through vacuum-forming processes. European manufacturers are accelerating bio-based polyurethane certification to satisfy EU Green Deal enforcement timelines.
- Foam:Open-cell polyurethane and closed-cell EVA formulations provide cost-effective cushioning.
- Leather:Natural hide substrates for dress shoe compatibility and moisture management.
Foam handles the majority of throughput; Carbon Fiber is expanding most quickly on share.
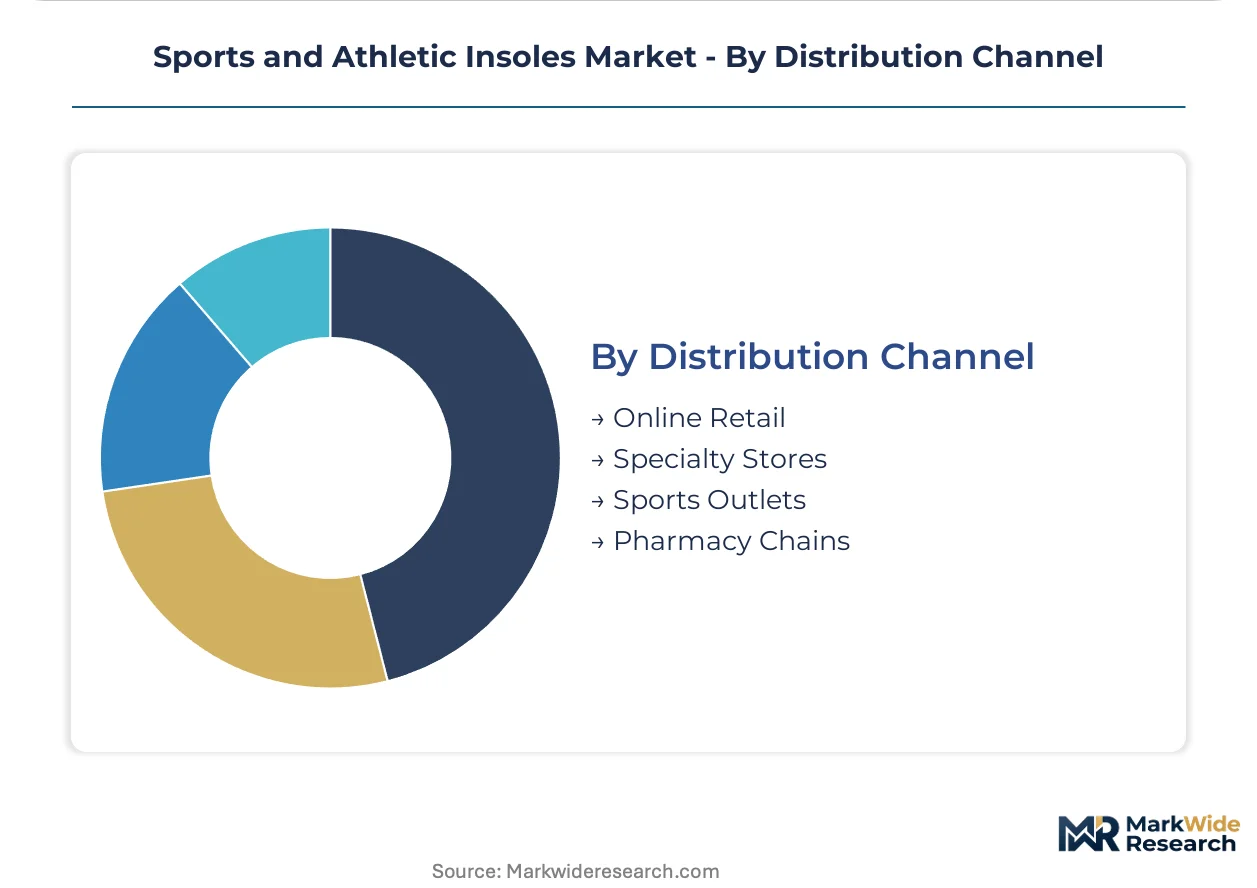
Distribution Channel:
After-sales service unbundling and digital gait analysis tools are compressing traditional specialty retail value propositions.
- Online Retail:Direct-to-athlete platforms integrate smartphone CAD-scanning applications with automated manufacturing workflows. China's domestic e-commerce ecosystems are concentrating demand here through fitness data integration and personalized recommendation engines.
- Specialty Stores:Brick-and-mortar running shops provide in-person gait analysis and custom fitting consultations. These outlets retain importance in Germany and the United States where podiatric technician availability supports high-touch service models.
- Sports Outlets:Big-box retailers and brand flagship stores moving standardized insole inventories.
- Pharmacy Chains:Mass-market gel and foam insoles distributed through healthcare-adjacent retail networks.
Pharmacy Chains handles the majority of throughput; Online Retail is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA medical device classifications anchor the United States market structure, while China's MEE bio-based material incentives and Germany's REACH enforcement timelines create divergent compliance pathways across the three dominant manufacturing clusters.
United States
Elite track and field programs in Eugene, Oregon and Austin, Texas are expanding procurement of carbon fiber composite stabilization plates. FDA 510(k) review timelines for prescription-grade pressure-mapping technologies constrain commercialization velocity for next-generation orthotic systems. Boston and Denver manufacturing hubs concentrate automated 3D-printed lattice production, displacing traditional podiatric technician workflows.
Germany
Bavarian and North Rhine-Westphalian orthotic laboratories sustain Europe's densest podiatric referral networks. EU Green Deal enforcement timelines for petroleum-based foam feedstocks are accelerating bio-based polyurethane certification among Stuttgart-area material suppliers. Freiburg and Munich clusters anchor medical-grade thermoplastic manufacturing for export markets.
China
Shanghai and Beijing tier-one city marathon participation is multiplying recreational user demand for entry-level cushioned insoles. MEE dual carbon goals reward domestic manufacturers certifying plant-derived thermoplastic formulations for local consumption. Shenzhen e-commerce platforms integrate fitness tracking data with personalized insole recommendations, bypassing specialty retail channels.
Japan
Tokyo and Osaka metropolitan running clubs are adopting CAD-scanning smartphone applications for remote custom ordering. METI standards for pressure-distribution footwear accessories shape product liability frameworks for domestic manufacturers. Nagoya industrial clusters supply precision-milled orthotic substrates to regional medical device distributors.
Australia
Sydney and Melbourne recreational running participation is driving pharmacy-chain penetration of gel insole volumes. TGA medical device classifications create compliance thresholds for prescription-grade imports from German and US suppliers. Brisbane manufacturing facilities face 18-month ISO 9001 accreditation periods that delay export market entry to European distribution channels.
Sports and Athletic Insoles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where premium orthotic specialists compete on biomechanical customization while mass-market gel insole producers compete on pharmacy-chain shelf presence and e-commerce logistics scale. The vendor base stratifies across three tiers: medical-grade certified orthotic laboratories with podiatric referral networks, mid-tier performance brands with specialty running store distribution, and commodity gel insole manufacturers with mass retail penetration. Dominant competitive moves include geographic expansion into underpenetrated Southeast Asian fitness markets and portfolio diversification across carbon fiber, thermoplastic, and bio-based foam material certifications.
Within the medical-grade orthotic tier, Bauerfeind and Superfeet occupy positions exemplifying divergent geographic anchoring strategies, with the former representing European manufacturing base consolidation and the latter representing North American carbon fiber technology specialization. Among mass-market accessibility providers, Dr. Scholl's exemplifies pharmacy-chain volume leadership. These three companies represent the archetype spectrum spanning prescription-grade clinical certification, performance-oriented composite engineering, and consumer-grade retail scale.
| Leading Market Players |
|---|
| Dr. Scholl's |
| Superfeet |
| Spenco |
| PowerStep |
| Protalus |
| Aetrex Worldwide |
| Bauerfeind |
| Foot Science International |
| Currex |
| Others |
Value Network & Pricing Analysis
Three-week lead times for custom-molded orthotic substrates compress pricing power at German and US manufacturing clusters while extending margin capture for automated 3D-printed lattice producers. Inventory cycles for petroleum-based polyurethane feedstocks amplify cost volatility across mid-tier gel insole producers, forcing portfolio stratification between premium certification tiers and mass-market pharmacy penetration.
Pricing Analysis
Geographic price spreads between Bavarian medical-grade laboratories and Shenzhen mass-manufacturing facilities exceed fourfold for equivalent biomechanical specifications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared prescription orthotics from REACH-compliant consumer gel insoles and uncertified commodity inserts. Cost compression in the mid-tier foam segment intensifies because petroleum-based feedstock volatility squeezes manufacturers lacking bio-based certification. Recreational runners through pharmacy chains exhibit highest price sensitivity, while elite track programs demonstrate lowest sensitivity due to performance-optimized procurement authority.
Supply Chain Analysis
Podiatric technician availability chokepoints across North Rhine-Westphalian and Massachusetts manufacturing clusters constrain custom orthotic throughput regardless of automation investments. Raw material supply concentrates in Germany, China, and the United States for thermoplastic polymers, carbon fiber composites, and bio-based polyurethane formulations. Feedstock dependency on crude oil-indexed precursors and medical-grade resin certifications creates single-source vulnerability for European REACH compliance. Distribution runs through direct-to-athlete digital channels in Chinese tier-one cities and specialty running stores in German urban centers, with pharmacy chains anchoring mass-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against smartphone-integrated pressure-mapping applications that displace traditional gait analysis consultations. Incumbents must navigate algorithmic self-service platforms eroding brick-and-mortar fitting value propositions.
For Market Incumbents: Compound defensive positioning through backward integration into bio-based polyurethane feedstock production and captive certification of REACH-compliant thermoplastic formulations. Secure podiatric technician capacity through apprenticeship pipelines in Bavaria and Massachusetts manufacturing clusters. Counter smartphone CAD-scanning substitutes by bundling clinical gait analysis with premium orthotic subscriptions.
For New Entrants and Emerging Players: Differentiate on bio-based material certification aligned with China's MEE dual carbon incentives and EU Green Deal enforcement timelines. Target underpenetrated Indonesian and Vietnamese marathon participation markets with entry-level cushioned insoles distributed through regional e-commerce platforms. Pursue direct-to-athlete digital channels integrating fitness tracking data with automated manufacturing workflows.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant orthotic laboratory assets and legacy thermoplastic molding capabilities. Long-term viability hinges on portfolio exposure to medical-grade certification tiers rather than commodity gel insole volume. Monitor FDA 510(k) review timeline compression as signal for next-generation pressure-mapping technology commercialization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Material Certification | REACH-compliant polyurethane formulations from Stuttgart suppliers unlock EU distribution access against petroleum-based competitors. |
| Automated Lattice Production Scale-Up | Boston and Denver 3D-printing hubs displace traditional podiatric technician bottlenecks through compressed custom manufacturing cycles. |
| Direct-to-Athlete Digital Channel Launch | Shenzhen e-commerce platforms integrate fitness tracking with personalized recommendations, bypassing specialty retail gatekeepers. |
| Podiatric Technician Apprenticeship Pipeline | Bavarian and Massachusetts training programs secure mold-making labor pools constraining custom orthotic throughput expansion. |
| Southeast Asian Distribution Partnership | Jakarta and Ho Chi Minh City entry-level positioning captures marathon participation growth trailing Chinese tier-one adoption curves. |
Research Methodology
Operator-level perspectives from podiatric laboratory directors, running specialty store buyers, thermoplastic procurement managers, and athletic program equipment coordinators anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, ECHA REACH substance registrations, Chinese MEE bio-based certification databases, and ISO 9001 accreditation records. Bottom-up volume modeling across product type, end user, material, and distribution channel dimensions triangulated with top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across petroleum price volatility bands, regulatory enforcement timeline scenarios, and marathon participation growth trajectories throughout the forecast period. Segmentation dimensions modeled include prescription versus consumer-grade certification tiers, elite versus recreational user procurement authority, carbon fiber versus foam versus thermoplastic material specifications, and digital versus brick-and-mortar channel economics. CAGRs derived from regression analysis against historical marathon participation rates, fitness equipment expenditure indices, and medical device reimbursement code expansions.
Material uncertainties — FDA medical device reclassification, EU Green Deal feedstock restriction acceleration, and podiatric technician labor pool contraction — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding bio-based material substitution timelines and REACH compliance cost absorption rates. Practitioners should keep alternative scenarios live as regulatory divergence between medical-grade and consumer-grade classification thresholds evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Tennis Equipment Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Bicycle Pumps Market