
 Fitness and Recreational Sports Centers Market | 2026-2036
Fitness and Recreational Sports Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Fitness and Recreational Sports Centers Market Intelligence
Capital-intensity divergence between premium full-service operators and budget franchise networks is rotating competitive dynamics across the sector. Life Time Fitness leverages its integrated resort-style amenities to sustain higher per-member revenue in affluent suburbs. Planet Fitness anchors its position through aggressive franchise expansion and standardized low-cost equipment packages. Equinox differentiates via boutique studio concepts and elevated service tiers that occupy the luxury segment.
Fitness and recreational sports centers encompass commercial facilities providing structured physical activity spaces, exercise equipment, instructor-led programming, and ancillary wellness services to individual and institutional subscribers. Facilities typically range from 15,000 to 150,000 square feet, incorporating climate-controlled training floors, aquatic installations, and recovery zones designed for repetitive biomechanical stress. Gyms and yoga studios within the facility-type segment capture the dominant share of membership volume, while climbing walls represent the fastest-growing subcategory driven by adventure-sport crossover appeal. Corporate membership models within the membership-model segment are expanding fastest as employers integrate preventive health benefits, though annual memberships retain the largest revenue pool due to upfront cash flow and retention lock-in.
FDA oversight of medical-grade recovery devices, EPA guidelines for indoor air quality in athletic facilities, and OSHA workplace safety standards for employee trainers collectively elevate operational compliance costs while creating barriers to informal market entry. The EU Green Deal and REACH chemical regulations on flooring and equipment materials are reshaping procurement specifications for facility build-outs across European markets. Stakeholders must monitor how municipal zoning boards and health departments tighten spatial and ventilation requirements before committing to long-term lease structures or expansion pipelines.
Market Dynamics
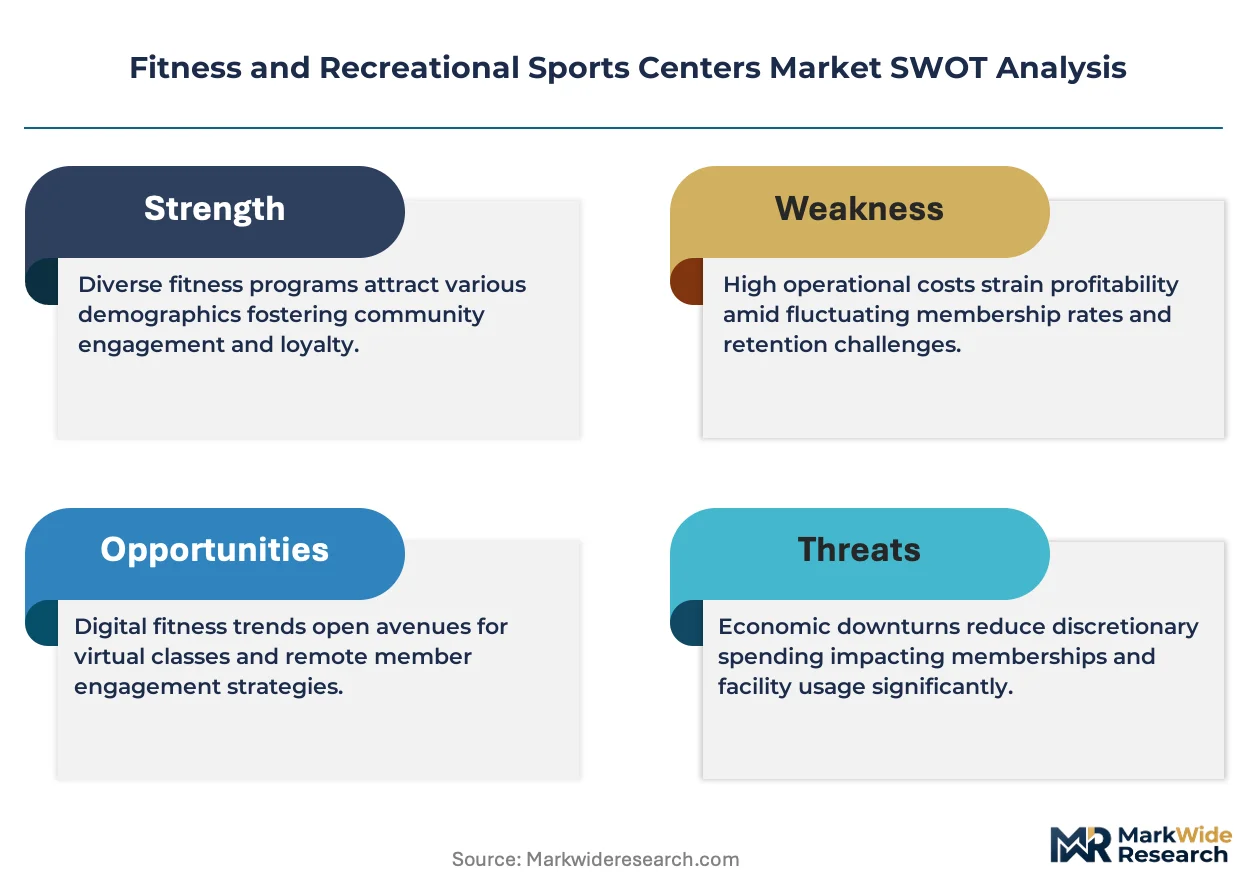
Corporate wellness mandates and wearable technology convergence are compressing member acquisition cycles while fragmenting loyalty patterns across facility operators. Employers now subsidize memberships as preventive health infrastructure, forcing centers to reconfigure pricing architectures around institutional contracts rather than individual subscriptions.
Growth Catalysts
- OSHA workplace safety standards:Mandatory trainer certification protocols elevate service quality thresholds, filtering informal competitors from formal market participation.
- Metropolitan cluster density:Urban agglomerations in the United States, Germany, and Australia concentrate disposable income and time-constrained professionals seeking structured fitness access.
- Wearable fitness technology:Biometric integration enables personalized programming at scale, reducing churn through data-driven engagement retention.
Market Restraints
- Real estate cost volatility:Prime urban retail and suburban anchor tenancy rates compress operating margins for full-service operators.
- REACH chemical compliance:Flooring and equipment material specifications add procurement complexity and extend facility build-out timelines.
- Home fitness substitution:Connected equipment and streaming platforms capture time-constrained segments previously requiring physical facility access.
Strategic Opportunities
- Adventure-sport crossover:Climbing wall installations attract outdoor recreation enthusiasts seeking climate-controlled training environments.
- Recovery zone expansion:Cryotherapy and hydrotherapy services capture ancillary revenue from performance-oriented members.
- EU Green Deal procurement incentives:Sustainable facility certifications unlock municipal partnership opportunities and preferential lease terms.
Industry Challenges
- Biomechanical specialist scarcity:Certified corrective exercise practitioners command premium wages, constraining service expansion.
- Legacy membership system migration:API integration between proprietary CRM platforms and wearable data ecosystems requires substantial IT investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fitness and Recreational Sports Centers Market |
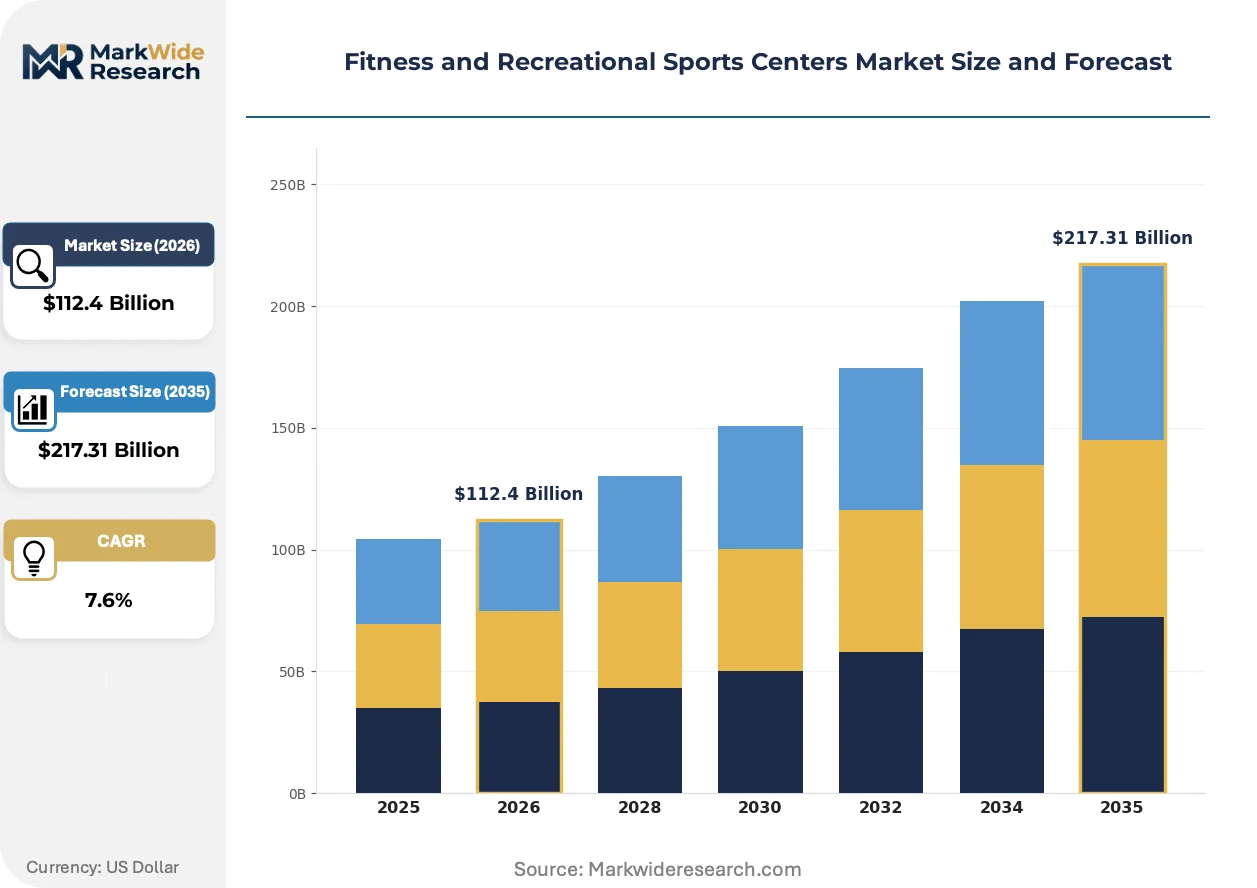
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $217.31 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Group Classes, Personal Training, Locker Services, Nutrition Counseling Facility Type: Gyms, Yoga Studios, Pools, Climbing Walls Membership Model: Annual Membership, Monthly Subscription, Pay-Per-Visit, Corporate Membership Target Demographic: Families, Seniors, Students, Professionals |
| Companies Covered | Life Time Fitness, LA Fitness, Planet Fitness, Crunch Fitness, Equinox, Anytime Fitness, Gold’s Gym, Snap Fitness, 24 Hour Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fitness and Recreational Sports Centers Market Strategic Shifts & Innovations
Wearable biometric sensors and AI-driven coaching algorithms are compressing the personalization cost curve, enabling mass-market facilities to deliver previously boutique-level programming. Facility design is pivoting toward modular recovery infrastructure.
Sensor-embedded strength equipment is miniaturizing. Budget franchise networks deploy compact connected racks that transmit form feedback to member smartphones. This hardware footprint reduction enables profitable operations in secondary retail locations previously excluded by square-footage minimums. Traditional floor space allocation for free weights is compressing accordingly.
EPA indoor air quality guidelines are tightening ventilation requirements for athletic facilities. Operators must upgrade HVAC specifications and increase filtration maintenance frequencies. Aquatic installations and high-intensity studio zones face the most stringent compliance timelines and capital retrofit obligations.
Employer-sponsored wellness subsidies are displacing individual membership decisions. Human resources departments now negotiate corporate rates directly with facility networks, consolidating purchasing power. This procurement concentration is most visible in United States metropolitan corridors where self-insured employers dominate health benefit administration.
Fitness and Recreational Sports Centers Market Segmentation
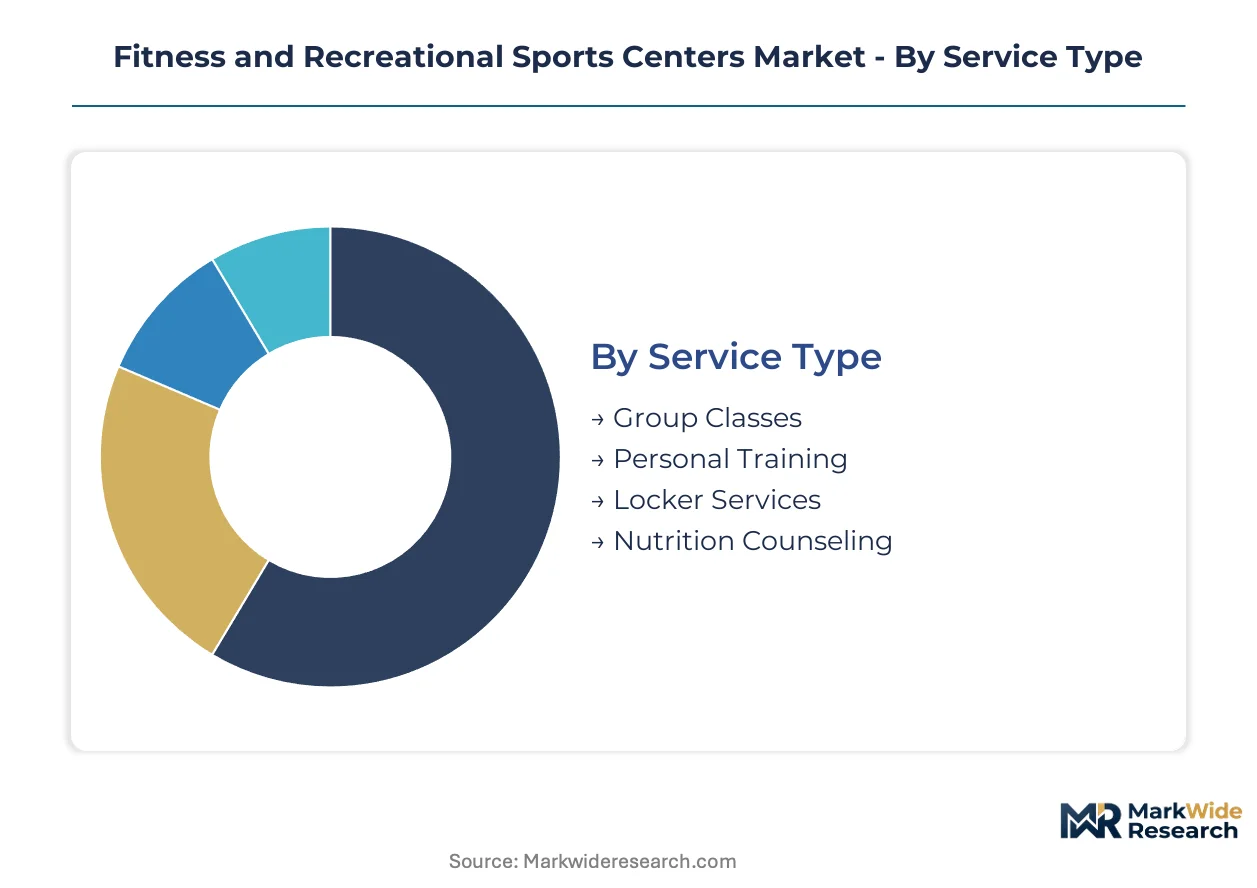
Segmentation in fitness and recreational sports centers reveals how distinct member needs and facility economics create parallel revenue architectures. Operators must align service depth, space allocation, and pricing mechanics to specific subscriber profiles rather than pursuing undifferentiated scale.
Service Type:
Group classes and personal training concentrate demand in urban metropolitan clusters across the United States, Germany, and Australia, while locker services and nutrition counseling follow facility-type distribution patterns.
- Group Classes:Instructor-led programming delivered in dedicated studio spaces with scheduled timetables spanning HIIT, cycling, and dance formats. Demand concentrates in time-constrained professional segments within urban United States corridors where employer wellness subsidies reduce individual price sensitivity.
- Personal Training:One-on-one biomechanical coaching and corrective exercise protocols delivered by certified practitioners. Metropolitan Australia clusters exhibit the highest penetration rates as disposable income thresholds support premium service tiers.
- Locker Services:Secure storage infrastructure with towel service and amenity provisioning tied to membership tier.
- Nutrition Counseling:Registered dietitian consultations and meal planning integrated into holistic wellness programming.
Group classes command the established base. The steepest expansion runs through personal training.
Facility Type:
Capital deployment intensity varies sharply across facility categories, with aquatic installations and climbing walls requiring specialized structural specifications that constrain geographic deployment flexibility.
- Gyms:General-purpose training floors incorporating cardiovascular equipment, resistance machines, and free-weight zones across 15,000 to 150,000 square feet. Budget franchise networks in the United States deploy standardized equipment packages that compress build-out costs and accelerate suburban expansion timelines.
- Climbing Walls:Engineered vertical surfaces with automated belay systems and bouldering zones designed for repetitive biomechanical stress. Demand from outdoor recreation enthusiasts seeking climate-controlled training environments drives fastest-growing installation rates across German urban centers.
- Yoga Studios:Climate-controlled spaces optimized for flexibility training and mindfulness programming with minimal equipment overhead.
- Pools:Aquatic installations facing stringent EPA ventilation compliance timelines and elevated HVAC retrofit obligations.
Gyms retain the dominant membership volume position. Climbing walls are gaining share fastest.
Membership Model:
Pricing architecture directly shapes cash flow predictability and member lifetime value calculations across operator business models.
- Annual Membership:Upfront payment structures generating immediate cash flow and creating retention lock-in through sunk-cost psychology. Full-service operators in affluent United States suburbs leverage annual commitments to fund capital-intensive recovery zone expansions.
- Corporate Membership:Institutional contracts negotiated directly with human resources departments as preventive health infrastructure. Self-insured employers in United States metropolitan corridors consolidate purchasing power and displace individual subscription decisions.
- Monthly Subscription:Recurring billing with cancellation flexibility attracting price-sensitive segments.
- Pay-Per-Visit:Transactional access for occasional users without long-term commitment requirements.
Annual memberships anchor the revenue pool. Corporate contracts are expanding most quickly.
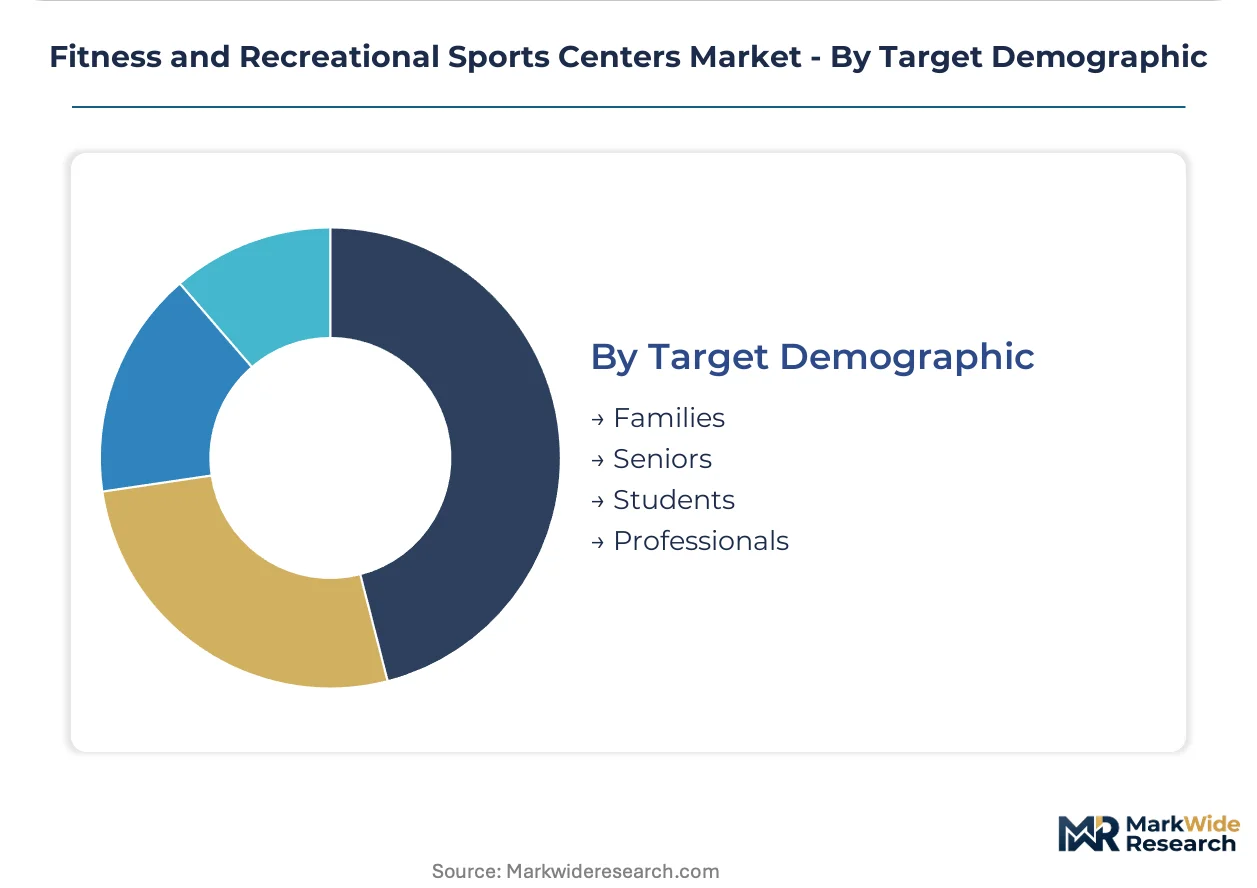
Target Demographic:
Age and household composition determine programming mix, facility design priorities, and optimal location selection criteria.
- Professionals:Time-constrained subscribers aged 25-45 seeking efficient training protocols and digital integration. Concentrated in urban agglomerations across the United States, Germany, and Australia where disposable income and schedule compression create demand for structured fitness access.
- Families:Multi-generational households requiring childcare infrastructure and varied programming depth. Australian suburban markets exhibit highest family membership penetration as facility operators bundle youth sports and adult training under single household contracts.
- Seniors:Age-qualified programming emphasizing low-impact movement and social engagement.
- Students:Price-sensitive segments accessing discounted rates through university partnerships.
Professionals command the established base. Family segments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan clusters in the United States command premium pricing power that outstrips comparable facilities in Germany by roughly one-third, reflecting divergent disposable income thresholds and employer wellness subsidy penetration. Australian operators occupy a mid-tier position with pricing elasticity tied to coastal urban density.
United States
Self-insured employers in metropolitan corridors now negotiate corporate membership rates directly with facility networks, consolidating purchasing power that individual subscriptions cannot match. OSHA workplace safety standards for trainer certification filter informal competitors from formal market participation. Life Time Fitness anchors affluent suburban clusters with integrated resort-style amenities that sustain elevated per-member revenue.
Germany
REACH chemical regulations on flooring and equipment materials reshape procurement specifications for facility build-outs, extending construction timelines. EU Green Deal procurement incentives unlock municipal partnership opportunities for operators achieving sustainable certifications. Berlin and Munich urban centers concentrate climbing wall installations driven by outdoor recreation enthusiasts seeking climate-controlled training environments.
Australia
Family membership penetration peaks in suburban markets where operators bundle youth sports and adult training under single household contracts. TGA oversight of medical-grade recovery devices elevates operational compliance costs for cryotherapy and hydrotherapy service expansions. Sydney and Melbourne metropolitan clusters exhibit the highest personal training penetration rates as disposable income thresholds support premium service tiers.
United Kingdom
Corporate wellness mandates from London-based financial services employers compress member acquisition cycles while fragmenting loyalty patterns across facility operators. GDPR compliance requirements constrain biometric data integration from wearable fitness technology. Greater London and Manchester urban agglomerations concentrate demand for time-efficient training protocols among professional segments aged 25-45.
Canada
Health Canada guidelines for indoor air quality in athletic facilities tighten ventilation requirements, particularly for aquatic installations and high-intensity studio zones. Municipal zoning boards in Toronto and Vancouver metropolitan areas impose spatial requirements that constrain rapid expansion pipelines. Budget franchise networks deploy standardized equipment packages to accelerate suburban penetration in secondary retail locations.
Fitness and Recreational Sports Centers Market Key Industry Players
Concentration sits with premium full-service operators and budget franchise networks that occupy opposing ends of the capital-intensity spectrum. The sector exhibits tiered structure rather than consolidated dominance, with resort-style amenities competing against stripped-down value propositions for distinct subscriber psychographics. Three archetypes define competitive positioning: integrated wellness resorts, standardized low-cost franchises, and boutique studio concepts. M&A activity targets regional chains for geographic fill-in, while technology licensing agreements accelerate wearable data ecosystem integration.
Within the premium resort archetype, Life Time Fitness exemplifies integrated amenity depth that commands sustained pricing power in affluent suburbs. Planet Fitness anchors the budget-tier vector with aggressive franchise expansion and standardized equipment packages that compress build-out costs. Equinox occupies the luxury segment through boutique studio concepts and elevated service tiers that differentiate via exclusivity positioning. These three operators collectively illustrate how capital deployment intensity determines viable geographic and demographic targeting across the sector.
| Leading Market Players |
|---|
| Life Time Fitness |
| LA Fitness |
| Planet Fitness |
| Crunch Fitness |
| Equinox |
| Anytime Fitness |
| Gold's Gym |
| Snap Fitness |
| 24 Hour Fitness |
| Others |
Cost & Logistics Intelligence
Corporate membership contracts lock in multi-year institutional commitments that secure supply access for facility operators while stabilizing price visibility against individual subscription volatility. These negotiated rate structures concentrate purchasing power with self-insured employers across United States metropolitan corridors, compressing margin flexibility for operators dependent on upfront annual cash flow.
Pricing Analysis
The customization-premium spread separates configured corporate wellness packages from standardized individual memberships. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with resort-style amenities commanding quality-grade premiums and budget franchise networks competing on volume scale. Price erosion runs through the economy tier as home fitness substitution intensifies competitive pressure. Corporate subscribers exhibit the lowest price sensitivity due to employer subsidy structures, while students and pay-per-visit users face the highest elasticity.
Supply Chain Analysis
Just-in-time equipment procurement dominates budget franchise networks, while full-service operators maintain strategic stockpiles of specialized recovery infrastructure to minimize installation downtime. Manufacturing concentration centers on China for connected fitness hardware, Taiwan for sensor components, and Germany for precision-engineered strength equipment. Supply chains draw from steel alloys, polyurethane flooring compounds, and semiconductor chips for embedded biometric systems. Single-source vulnerability in medical-grade cryotherapy unit production elevates risk exposure. Distribution runs through regional equipment distributors with direct-to-operator installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through corporate wellness procurement consolidation, as human resources departments displace individual subscription decisions with institutional rate negotiations.
For Market Incumbents: Shield margin position by deepening backward integration into recovery service infrastructure and securing exclusive municipal partnerships under EU Green Deal certification pathways. Home fitness substitution and biomechanical specialist scarcity represent immediate threats requiring defensive certification investment and channel control through employer-direct sales teams. For New Entrants and Emerging Players: OSHA fast-track certification for corrective exercise practitioners unlocks white-space penetration in Australian metropolitan clusters where personal training demand outstrips certified supply. Target family membership bundles in suburban markets with bundled youth sports programming as the most penetrable segment, deploying direct corporate sales to human resources departments as the primary go-to-market angle. For Investors and Strategic Acquirers: Regional climbing wall specialists with adventure-sport crossover positioning offer acquisition exposure to the fastest-growing facility subcategory. Long-term viability across the analysis window hinges on biometric data integration capabilities and sustainable facility certification portfolios. Watch corporate wellness subsidy expansion rates as the critical inflection signal for institutional contract volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Data Platform Integration | API connectivity between proprietary CRM systems and wearable ecosystems reduces churn through personalized engagement protocols. |
| Recovery Zone Capacity Expansion | Cryotherapy and hydrotherapy installations capture ancillary revenue from performance-oriented members in affluent suburbs. |
| Corporate Wellness Direct Sales | Human resources department partnerships displace individual subscription decisions with institutional rate structures. |
| Sustainable Facility Certification | EU Green Deal compliance unlocks municipal partnerships and preferential lease terms across European urban centers. |
| Climbing Wall Installation Program | Adventure-sport crossover appeal drives fastest-growing membership acquisition in German and Australian metropolitan clusters. |
Research Approach
Desk research of SEC filings, municipal zoning records, and EPA ventilation compliance databases preceded structured interviews with facility operations directors, corporate wellness benefits managers, and fitness equipment procurement specialists. Primary fieldwork with franchise development executives and regional chain owners was cross-validated against trade association membership data and OSHA trainer certification registries. Bottom-up facility count enumeration triangulated against top-down revenue estimates from annual membership and corporate contract disclosures.
Variance decomposition across facility type, membership model, service tier, and target demographic dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion trajectories throughout the forecast period. Modeled inputs incorporated employer wellness subsidy penetration curves, wearable technology adoption rates, and metropolitan cluster disposable income thresholds specific to United States, German, and Australian urban agglomerations.
Decision-makers should treat outputs as directional under sustained corporate wellness subsidy expansion and stable real estate cost environments; material deviation would warrant model refresh. Forecasts assume continued EPA and OSHA regulatory enforcement without structural relaxation. Revision becomes warranted when home fitness substitution rates or biomechanical specialist wage inflation cross thresholds that alter facility economics materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
Europe Pilates & Yoga Studios Market
Gyms and Fitness Centers
Global Climbing Gym Market
Gyms and Fitness Centers
Boutique Fitness Studio Market
Gyms and Fitness Centers
Health and Fitness Club Market
Gyms and Fitness Centers
Europe Climbing Gym Market
Gyms and Fitness Centers
Global Pilates and Yoga Studios Market
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market
Gyms and Fitness Centers
South Korea Health and Fitness Club Market
Gyms and Fitness Centers
South America Health and Fitness Club Market
Gyms and Fitness Centers
Saudi Arabia Health and Fitness Club Market