
 Speed Hurdle Market | 2026-2036
Speed Hurdle Market Size, Share, and Industry Trends Forecast 2026-2036
Speed Hurdle Market Analytics
China is rewriting the competitive map for speed hurdle manufacturing through expanded thermoplastic molding capacity in Zhejiang province. Gill Athletics leverages vertical integration across aluminum extrusion and powder-coating operations to sustain margin control. Blazer Athletic Equipment anchors its position through R&D intensity in adjustable-height mechanisms. Kwik Goal Ltd. competes via channel dominance in institutional procurement across the collegiate sports segment.
Speed hurdles are collapsible or fixed barriers used in sprint agility training, typically constructed from aluminum tubing or high-impact polymer with heights ranging from six to twelve inches to enforce stride frequency discipline. The equipment serves coaches and athletes seeking to improve foot speed, hip mobility, and neuromuscular coordination without the full clearance demands of competition hurdles. Adjustable hurdles command premium positioning due to customization demands from multi-sport training facilities, while portable variants lead volume through recreational and youth league penetration. Aluminum construction dominates competitive and institutional channels for durability, though composite materials represent the fastest-growing material category as carbon-fiber-reinforced polymers reduce transport weight.
ASTM International governs sports equipment safety specifications in the United States, while the European Committee for Standardization oversees CE marking requirements for fitness equipment sold across EU member states. China's GB standards for sports goods mandate impact resistance testing that shapes export qualification timelines for domestic manufacturers. Stakeholders must monitor evolving school district procurement policies and federated sports body equipment mandates to anticipate demand shifts.
Market Dynamics
ASTM F2656 certification requirements are compressing vendor qualification timelines while thermoplastic molding advances in Zhejiang province are redrawing supply-side economics for speed hurdle manufacturers.
Growth Catalysts
- NCAA Division I procurement expansion:Track and field programs are elevating equipment budgets for sprint agility infrastructure. Collegiate athletic departments now mandate adjustable-height systems for multi-sport training facilities.
- REACH-compliant polymer adoption:European fitness equipment standards are accelerating material transitions toward recyclable high-impact polymers. CE marking requirements for fitness equipment sold across EU member states are pulling manufacturers toward certified supply chains.
- Southern United States climate advantage:Year-round outdoor training conditions in Texas, Florida, and Georgia are sustaining higher hurdle utilization rates than seasonal northern markets. Regional school districts are consolidating purchases around portable aluminum systems.
Market Restraints
- Aluminum price volatility:Extrusion-grade aluminum input costs fluctuate with energy-intensive smelting economics. Margin compression hits mid-tier manufacturers lacking captive powder-coating operations.
- GB standards compliance burden:China's sports goods impact resistance testing mandates extend export qualification timelines for domestic manufacturers. Certification delays constrain speed-to-market for new product variants.
- Fixed-height substitution threat:Basic PVC pipe constructions from recreational suppliers undercut institutional-grade systems in youth league segments. Price-sensitive buyers trade durability for upfront cost savings.
Strategic Opportunities
- Carbon-fiber-reinforced polymer convergence:Composite materials are hybridizing with traditional aluminum frames to reduce transport weight. Multi-sport training facilities are adopting these hybrid systems for field mobility.
- Adjustable-height mechanism innovation:R&D-intensive quick-release pin systems are opening premium positioning in physical therapy and rehabilitation centers. Customization demands from cross-functional training facilities support margin expansion.
- Institutional procurement channel consolidation:Direct vendor relationships with school district cooperatives are displacing traditional distributor networks. Volume aggregation through regional purchasing alliances is compressing sales cycle duration.
Industry Challenges
- ASTM F2656 testing backlog:Third-party certification laboratory capacity constraints are extending product launch timelines. Manufacturers face working capital pressure from inventory held in qualification queues.
- Multi-material welding expertise scarcity:Aluminum-to-composite joint engineering requires specialized technician training. Workforce development lags behind product architecture complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speed Hurdle Market |
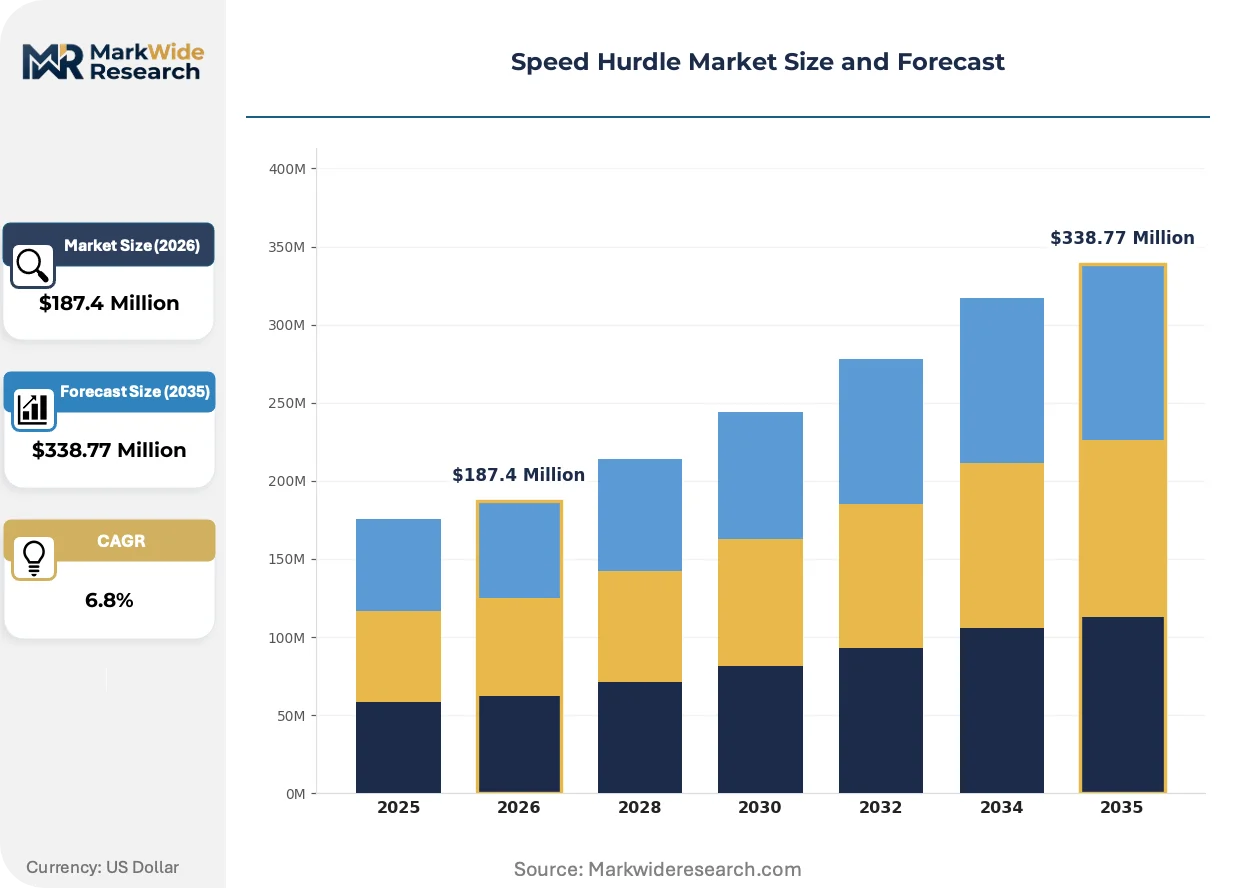
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Hurdles, Adjustable Hurdles, Portable Hurdles, Olympic Hurdles Material: Plastic, Aluminum, Wood, Composite End User: Athletes, Coaches, Schools, Training Facilities Usage Type: Competitive Events, Training Sessions, Sports Academies, Recreational Use |
| Companies Covered | Gill Athletics, Blazer Athletic Equipment, Kwik Goal Ltd., Trademark Innovation Inc., Epic Sports Inc., Olympia Sports Ltd., Champion Sports, Fisher Athletic, Artimex Sport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speed Hurdle Market Evolving Landscape
Material science advances and procurement digitization are restructuring how speed hurdles are specified, certified, and deployed across training environments.
Carbon-fiber-reinforced polymer is hybridizing with aluminum extrusion to produce sub-five-pound hurdle assemblies without sacrificing impact resistance. Collegiate strength and conditioning programs are adopting these hybrid systems for travel squad equipment. The technology is hybridizing competitive and portable product categories that previously operated as distinct market tiers.
ASTM International's F2656 standard revision cycle is tightening tip-over stability requirements for collapsible training barriers. North American manufacturers are redesigning base geometry and adding ballast-compatible footings to maintain certification. Institutional buyers in the United States are now requiring current-standard documentation in RFP specifications, filtering uncertified suppliers from bid pools.
Aggregated purchasing through regional school district cooperatives is consolidating buying power previously fragmented across individual athletic directors. Traditional sporting goods distributors are losing position to direct manufacturer relationships with procurement officers. This consolidation is most visible in Texas and Florida, where state-level interscholastic athletic associations are standardizing equipment specifications to simplify compliance auditing.
Speed Hurdle Market Segmentation
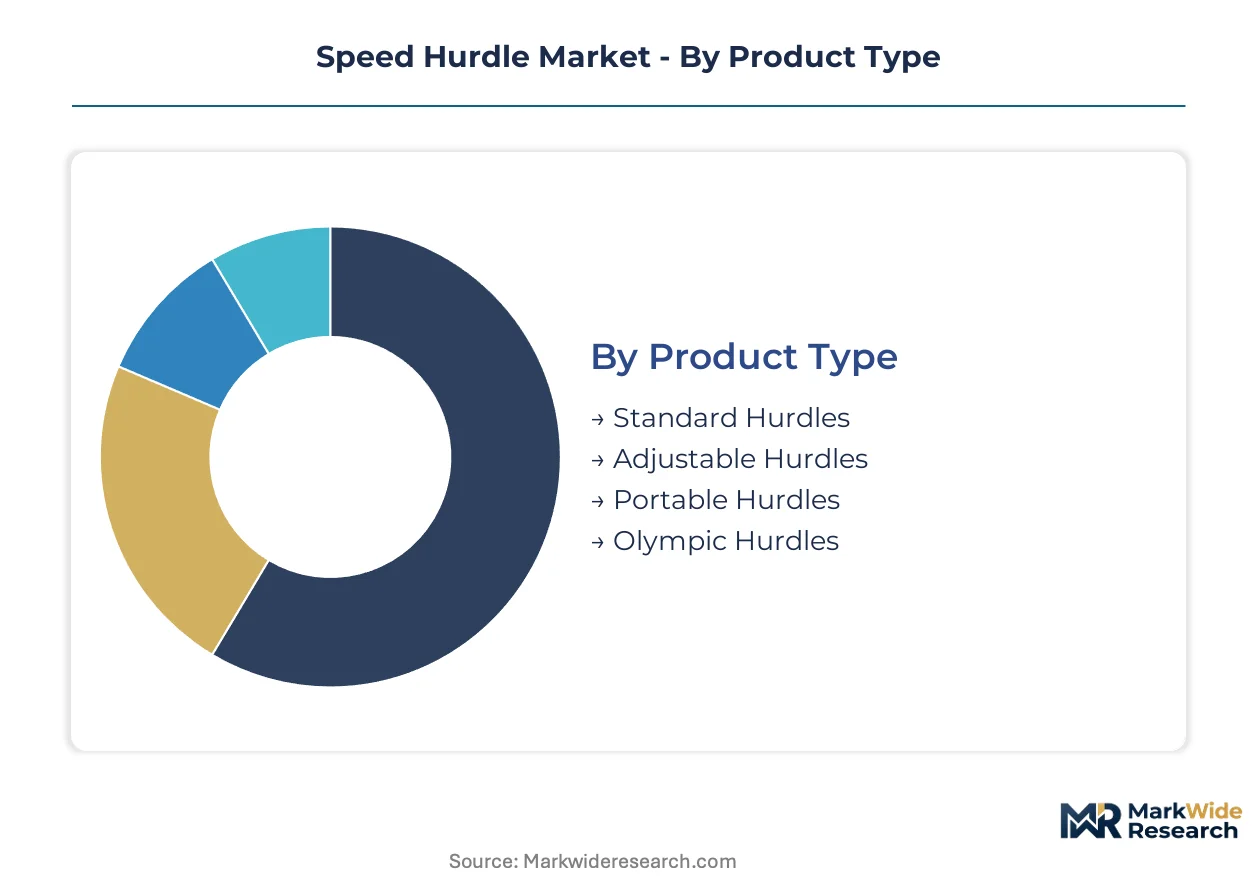
Speed hurdle manufacturers must align product architectures with distinct performance demands across institutional procurement channels. Segmentation reveals where margin concentration diverges from volume concentration, guiding resource allocation for R&D and certification investments.
Product Type:
After-sales-service intensity varies sharply across hurdle categories, with adjustable mechanisms requiring calibration support while fixed systems demand minimal field intervention.
- Adjustable Hurdles:Quick-release pin systems enable height modification from six to twelve inches for multi-sport training protocols. NCAA Division I athletic departments in Texas and Florida specify these systems for year-round agility programming, absorbing premium pricing in exchange for customization flexibility.
- Portable Hurdles:Collapsible aluminum or polymer frames under five pounds support travel squad logistics and recreational league deployment. Southern United States school districts consolidate purchases around these systems for field mobility, though PVC pipe substitutes undercut institutional-grade alternatives in youth segments.
- Standard Hurdles:Fixed-height aluminum constructions dominate high school track programs seeking durability without complexity.
- Olympic Hurdles:Competition-grade specifications with precise weight and tip-over stability requirements serve sanctioned meet operations.
Adjustable Hurdles holds the largest share; momentum sits with Portable Hurdles.
Material:
Cost tier stratification separates aerospace-grade aluminum systems from injection-molded polymer alternatives, with composite hybrids capturing premium positioning in collegiate channels.
- Aluminum:Extrusion-grade tubing with powder-coated finishes delivers impact resistance for institutional procurement. ASTM F2656 certification requirements favor established aluminum fabricators with captive coating operations, compressing qualification timelines for integrated manufacturers.
- Composite:Carbon-fiber-reinforced polymers hybridized with aluminum frames reduce transport weight below five pounds. Collegiate strength and conditioning programs in Georgia adopt these systems for travel equipment, accepting price premiums for field mobility gains.
- Plastic:High-impact polymers serve recreational and youth league penetration with REACH-compliant formulations for European export qualification.
- Wood:Traditional constructions persist in legacy training facilities with established equipment inventories.
Aluminum dominates procurement volume; Composite claims the steepest expansion trajectory.
End User:
Customer type determines specification stringency, with institutional buyers mandating certification documentation while individual purchasers prioritize upfront cost minimization.
- Schools:Regional purchasing alliances in Texas and Florida aggregate demand through district cooperatives, displacing traditional distributor relationships. State interscholastic athletic associations standardize equipment specifications to simplify compliance auditing.
- Training Facilities:Multi-sport complexes require adjustable-height systems for cross-functional programming, supporting premium positioning for mechanism innovation.
- Coaches:Individual procurement emphasizes portability and rapid deployment for practice session flexibility.
- Athletes:Personal equipment purchases concentrate in competitive segments seeking travel-compatible systems.
Schools command the greatest procurement volume; Training Facilities drive specification upgrades fastest.
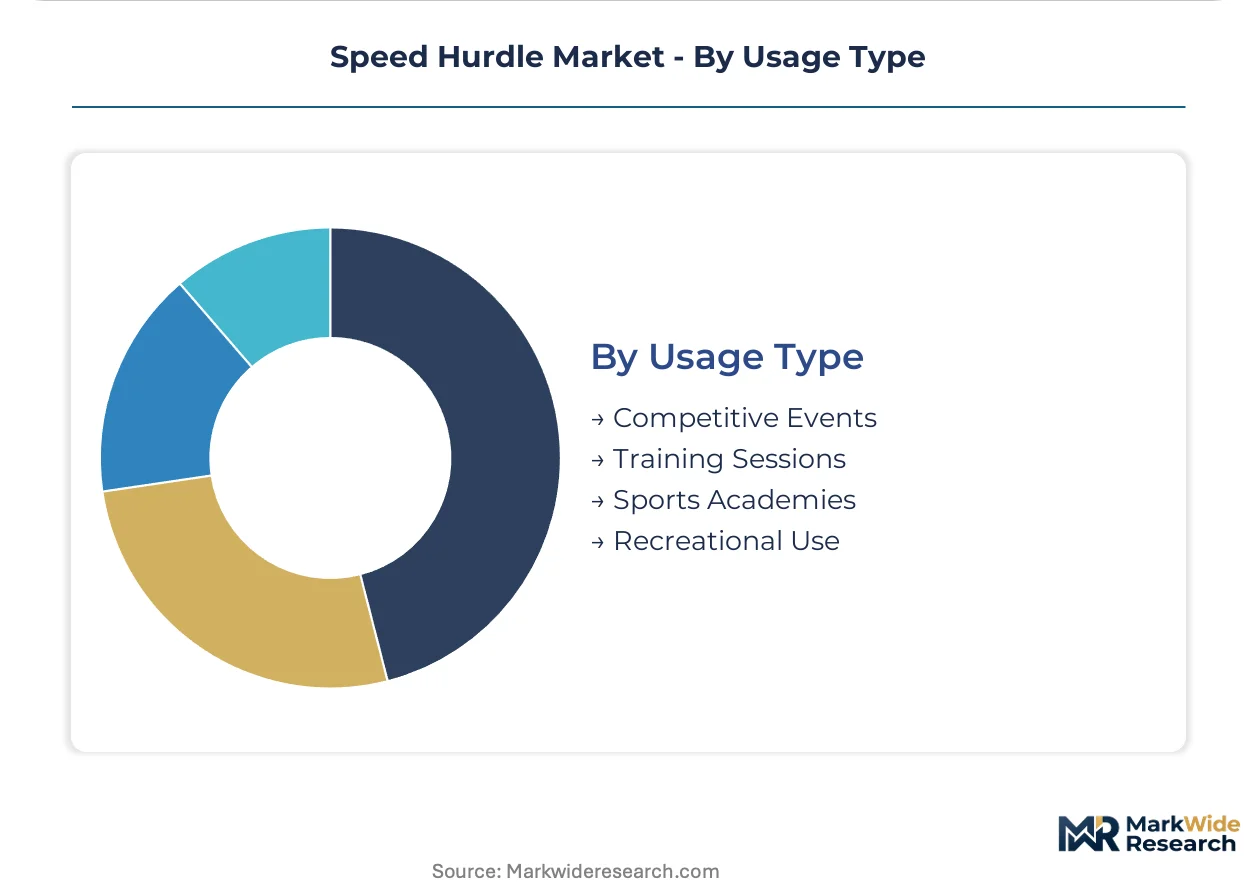
Usage Type:
Application context dictates durability requirements and replacement cycles, with competitive events demanding certified systems while recreational use tolerates lower-grade alternatives.
- Training Sessions:Daily agility programming in collegiate and professional environments sustains highest utilization rates. Southern United States climate advantages support year-round outdoor deployment, accelerating wear-cycle replacement demand.
- Competitive Events:Sanctioned meets require current-standard ASTM F2656 documentation, filtering uncertified suppliers from bid pools. Institutional buyers now mandate certification in RFP specifications.
- Sports Academies:Specialized coaching facilities combine competitive and training specifications for athlete development pipelines.
- Recreational Use:Price-sensitive youth leagues trade durability for upfront cost savings, accepting PVC pipe constructions.
Training Sessions generates the highest replacement revenue; Competitive Events enforces the tightest certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach logistics corridor underwrites California's distribution dominance for sports equipment imports serving collegiate athletic programs across the western United States.
United States
NCAA Division I track and field programs in Texas and Florida drive institutional procurement volume with year-round outdoor training infrastructure. ASTM F2656 certification requirements filter uncertified suppliers from bid pools, compressing vendor qualification timelines. The Dallas-Fort Worth metroplex anchors regional distribution networks serving southern school district cooperatives.
China
Thermoplastic molding capacity expansion in Zhejiang province redraws supply-side economics for polymer hurdle production. GB standards for sports goods mandate impact resistance testing that shapes export qualification timelines for domestic manufacturers. Ningbo port infrastructure supports consolidated shipment consolidation to North American collegiate procurement channels.
Germany
REACH-compliant polymer adoption accelerates material transitions toward recyclable high-impact formulations for fitness equipment. CE marking requirements pull manufacturers toward certified supply chains serving institutional buyers across EU member states. The Rhine-Ruhr industrial corridor concentrates powder-coating operations for aluminum extrusion finishing.
United Kingdom
Multi-sport training facilities in Greater London specify adjustable-height systems for cross-functional programming. The country's national sports equipment regulator enforces safety documentation requirements that parallel ASTM specifications. Manchester's logistics infrastructure supports distribution consolidation for northern England school district alliances.
Japan
JIS standards for sports equipment shape domestic procurement specifications for track and field infrastructure. METI industrial policy supports lightweight composite material R&D for transport-efficient training equipment. The Kansai region's manufacturing base supplies carbon-fiber-reinforced polymer components for hybrid hurdle assemblies.
Speed Hurdle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying extrusion, molding, and coating inputs. The vendor base organizes around three tiers: vertically integrated manufacturers with captive powder-coating operations, regional fabricators serving district cooperatives, and recreational suppliers competing on upfront cost. Strategic moves concentrate on direct procurement relationships with institutional buyers and composite material hybridization for weight reduction.
Among North American athletic equipment specialists, Gill Athletics exemplifies vertical integration across aluminum extrusion and finishing operations. Blazer Athletic Equipment occupies a position within the R&D-intensive tier focused on adjustable-height mechanism innovation. Kwik Goal Ltd. represents channel dominance archetypes in institutional procurement across collegiate segments. These three anchors illustrate how competitive positioning diverges between manufacturing control, product engineering, and distribution scale.
| Leading Market Players |
|---|
| Gill Athletics |
| Blazer Athletic Equipment |
| Kwik Goal Ltd. |
| Trademark Innovation Inc. |
| Epic Sports Inc. |
| Olympia Sports Ltd. |
| Champion Sports |
| Fisher Athletic |
| Artimex Sport |
| Others |
Value Network & Pricing Analysis
Thermoplastic molding capacity in Zhejiang province anchors upstream supply concentration, compressing input costs for polymer hurdle variants while diverting margin pools toward ASTM F2656-certified aluminum fabricators with captive finishing operations. The divergence between commodity-grade recreational imports and institutional-grade domestic production defines where pricing power concentrates downstream.
Pricing Analysis
ASTM F2656 dictates the pricing tier structure across the speed hurdle market, separating certified institutional systems from uncertified recreational alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because PVC pipe substitutes from recreational suppliers undercut aluminum constructions. School district cooperatives exhibit highest price sensitivity through aggregated volume bidding, while NCAA Division I athletic departments absorb premium positioning for adjustable-height mechanisms.
Supply Chain Analysis
Contract manufacturers in Zhejiang province hold dominant thermoplastic molding capacity for polymer hurdle production. Supply draws from China for injection-molded components, the United States for aluminum extrusion and powder-coating, and Germany for REACH-compliant polymer formulations. Raw material dependencies include extrusion-grade aluminum, carbon-fiber-reinforced polymer resin, and high-impact thermoplastic compounds. Single-source vulnerability concentrates in Zhejiang molding capacity for polymer variants. Distribution runs through regional school district cooperatives in Texas and Florida, displacing traditional sporting goods distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The speed hurdle market sits in early-cycle expansion, with carbon-fiber-reinforced polymer hybridization opening premium positioning in collegiate travel equipment as the clearest adoption tailwind.
For Market Incumbents: Build certification moats around ASTM F2656 documentation and captive powder-coating operations to defend against Zhejiang-based polymer imports. Invest in quick-release pin mechanism R&D to deepen differentiation in physical therapy channels. Consolidate direct procurement relationships with Texas and Florida school district cooperatives before distributor displacement completes.
For New Entrants and Emerging Players: Mid-market training facilities in the southern United States represent the most penetrable entry point, as these buyers seek adjustable-height systems without incumbent brand loyalty. European rehabilitation centers underserved by REACH-certified suppliers offer secondary white-space. Enter through private-label partnerships with Zhejiang molders to bypass capital-intensive extrusion infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators serving district cooperatives but lacking composite material capabilities. Five-to-ten year viability hinges on aluminum-to-polymer transition timing. Monitor ASTM F2656 testing laboratory capacity utilization as an early signal of vendor qualification bottlenecks that favor integrated manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Fiber Hybridization | Reduces travel squad equipment weight below five pounds for collegiate programs. |
| Direct Procurement Relationships | Bypasses distributor networks through school district cooperative contracts in Texas. |
| ASTM F2656 Certification Investment | Filters uncertified competitors from institutional bid pools across NCAA Division I. |
| Quick-Release Mechanism R&D | Opens premium positioning in physical therapy and rehabilitation center channels. |
| REACH-Compliant Polymer Transition | Enables European market access through certified supply chain documentation. |
Research Methodology
A standing panel of collegiate strength and conditioning coaches, athletic department procurement officers, and sports equipment distributors provided ongoing calibration across the study period. Primary interviews with track and field program directors, school district cooperative administrators, and aluminum extrusion plant managers combined with secondary validation from ASTM International documentation, NCAA equipment budget disclosures, and Zhejiang provincial industrial statistics. Bottom-up triangulation against top-down market sizing anchored volume and value estimates.
Scenario-bracketing around aluminum price volatility, certification timeline compression, and polymer substitution rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material composition, end-user category, and geographic procurement cluster. CAGRs derived from historical utilization rate patterns in southern United States climates and collegiate equipment replacement cycles. Forecast inputs incorporated GB standards compliance timelines for Chinese manufacturers and REACH adoption curves in European fitness equipment.
Practitioners should monitor aluminum smelting energy costs, third-party laboratory certification backlogs, and school district cooperative consolidation pace for early signals of forecast revision. Quarterly review of ASTM F2656 documentation requirements in institutional RFPs and Zhejiang thermoplastic molding capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
France Artificial Turf Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Golf Club Market
Sports Equipment
Global Darts Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Golf Gloves Market
Sports Equipment
United States Archery Equipment Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
North America Stand-Up Paddleboard Market