
 Sorbitol Production Equipment Market | 2026-2036
Sorbitol Production Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sorbitol Production Equipment Market Analysis
Pharmaceutical-grade stainless steel specifications are rotating toward higher purity thresholds across sorbitol production lines. Dipesh Engineering Works leverages its fabrication expertise in Gujarat to anchor regional supply for Indian pharmaceutical clients. Beijing MecKey Engineering dominates turnkey crystallization systems across East Asian markets. Raj Process Equipment and Systems specializes in custom batch reactor configurations for mid-scale sweetener manufacturers.
Sorbitol production equipment encompasses the engineered systems that catalytically hydrogenate glucose feedstock under controlled temperature and pressure to yield sorbitol syrup or crystalline powder for industrial use. Continuous reactor systems are maturing as the dominant installed base, while enzymatic process technology represents the fastest-growing segment as bio-based conversion gains traction among European personal care formulators. Turnkey installation projects command the deepest margin pools due to engineering complexity and long-term service contracts.
FDA pharmaceutical cGMP standards and EMA's Good Manufacturing Practice guidelines shape equipment validation protocols for sorbitol destined for drug excipient applications. India's CDSCO aligns with ICH Q7 guidelines for active pharmaceutical ingredient equipment, tightening weld inspection and surface finish requirements. China's NMPA enforces GB standards for food-contact equipment that constrain alloy selection and cleaning system design. Stakeholders must monitor evolving dual-use regulatory convergence between food-grade and pharmaceutical-grade equipment specifications.
Market Dynamics
Catalytic hydrogenation reactor technology is tightening purity thresholds across sorbitol production lines, forcing equipment fabricators to redesign heat transfer surfaces and pressure vessel specifications for pharmaceutical-grade compliance.
Growth Catalysts
- EMA cGMP alignment:European pharmaceutical excipient standards are pulling stainless steel surface finish requirements from Ra 0.8 to Ra 0.4 micrometers, mandating equipment upgrades across contract manufacturing organizations.
- Reduced-calorie formulation expansion:Food and beverage manufacturers in India are scaling crystallization capacity to replace sucrose in functional beverages and sugar-free confectionery.
- Enzymatic conversion:Bio-based glucose-to-sorbitol pathways are gaining traction among personal care formulators seeking lower-temperature processing with reduced hydrogen consumption.
Market Restraints
- High-purity nickel alloy costs:Hastelloy and Inconel price volatility for hydrogenation reactor linings compresses margin pools for mid-scale equipment fabricators.
- East Asian supply concentration:Turnkey crystallization system engineering gravitates toward Chinese and South Korean vendors, limiting second-source options for Indian and European buyers.
- Batch-to-continuous transition friction:Legacy batch reactor installations face stranded asset risk as continuous systems tighten unit economics.
Strategic Opportunities
- CDSCO pharmaceutical alignment:India's ICH Q7 equipment guidelines create certified vendor status for domestic fabricators serving active pharmaceutical ingredient producers.
- Personal care enzymatic demand:European cosmetic formulators are requesting modular skid-mounted systems for small-volume sorbitol production with rapid product changeover.
- Service contract unbundling:Aftermarket validation documentation and weld inspection services are separating from capital equipment sales as standalone revenue streams.
Industry Challenges
- Orbital welding certification scarcity:ASME Section IX qualified welders for pharmaceutical-grade autogenous joints command premium labor rates and extended project timelines.
- FDA 21 CFR Part 11 integration:Electronic batch record systems for continuous reactors require legacy control architecture replacement with validated software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorbitol Production Equipment Market |
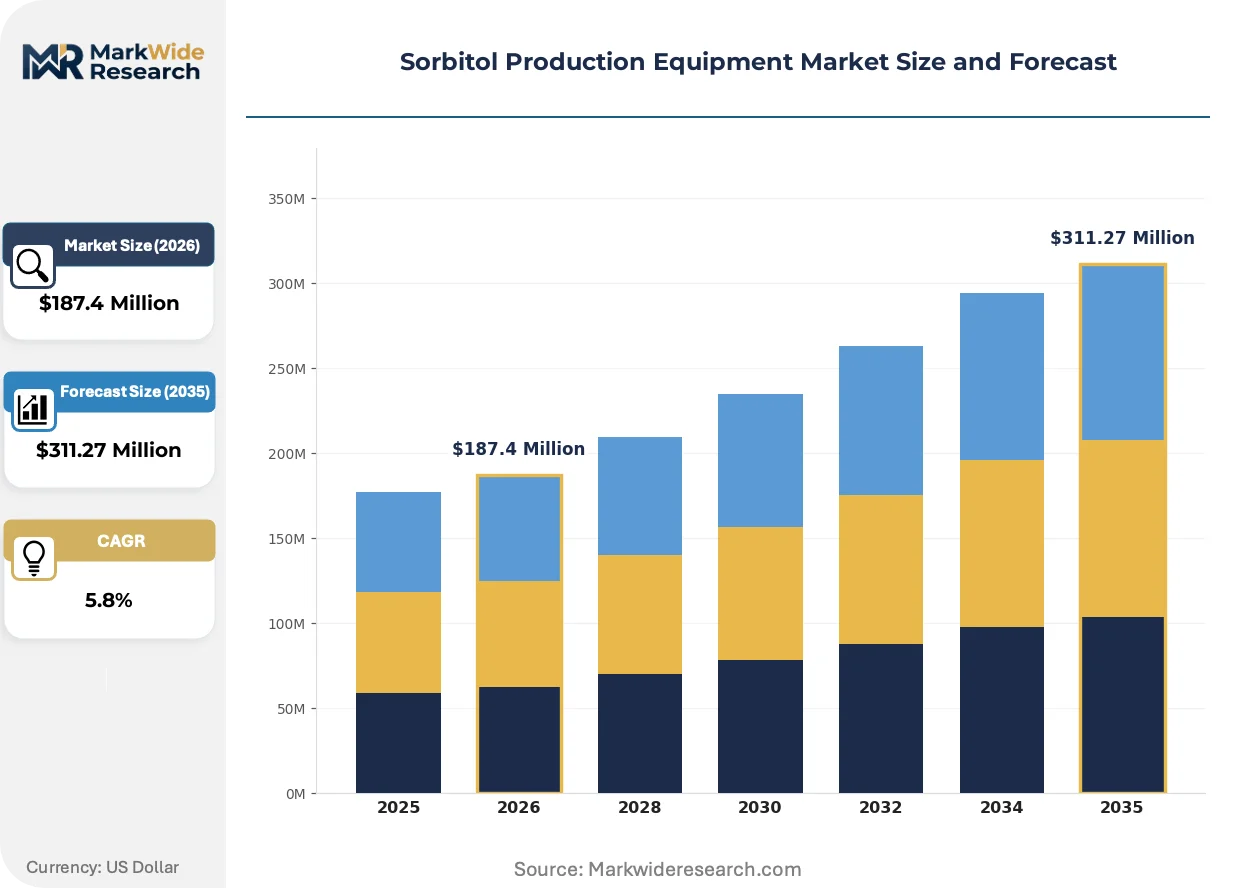
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Reactors, Continuous Reactors, Mixing Tanks, Storage Tanks Technology: Catalytic Process, Chemical Process, Fermentation Technology, Enzymatic Process End User: Food & Beverage Industry, Pharmaceutical Industry, Personal Care Sector, Chemical Manufacturing Installation: On-site Installation, Off-site Installation, Modular Systems, Turnkey Projects |
| Companies Covered | Dipesh Engineering Works, Raj Process Equipment and Systems, Bosida Machinery, Beijing MecKey Engineering, Sri Ram Engineering & Fabrication Works, Mukul Engineering Works, DSSE, Ilshin Autoclave, Universal Process Engineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorbitol Production Equipment Market Emerging Trajectories
Process intensification and modular system architecture are compressing project delivery timelines while elevating validation complexity for multi-product facilities.
Membrane-assisted catalytic hydrogenation is supplanting conventional slurry-phase reactors in high-purity sorbitol applications. Pharmaceutical excipient manufacturers in Germany and Switzerland are piloting ceramic membrane modules for inline glucose conversion. This technology is supplanting traditional stirred-tank designs by enabling continuous operation with tighter molecular weight distribution control.
REACH substance restrictions on nickel catalyst leaching are tightening effluent treatment requirements for hydrogenation facilities. ECHA's updated guidance on metal catalyst residues in food-contact applications is forcing equipment redesigns with closed-loop catalyst recovery systems. Sorbitol destined for European nutraceutical applications now requires documented catalyst retention below 0.1 parts per million, driving membrane filtration retrofit demand.
Buyer concentration among multinational sweetener producers is compressing vendor negotiation leverage for regional equipment fabricators. Tier-one food ingredient conglomerates are consolidating procurement through framework agreements with turnkey engineering houses, sidelining mid-scale batch reactor specialists. This pattern is most visible in India, where domestic sugar processors are scaling sorbitol capacity through single-source EPC contracts rather than fragmented equipment purchases.
Sorbitol Production Equipment Market Segmentation
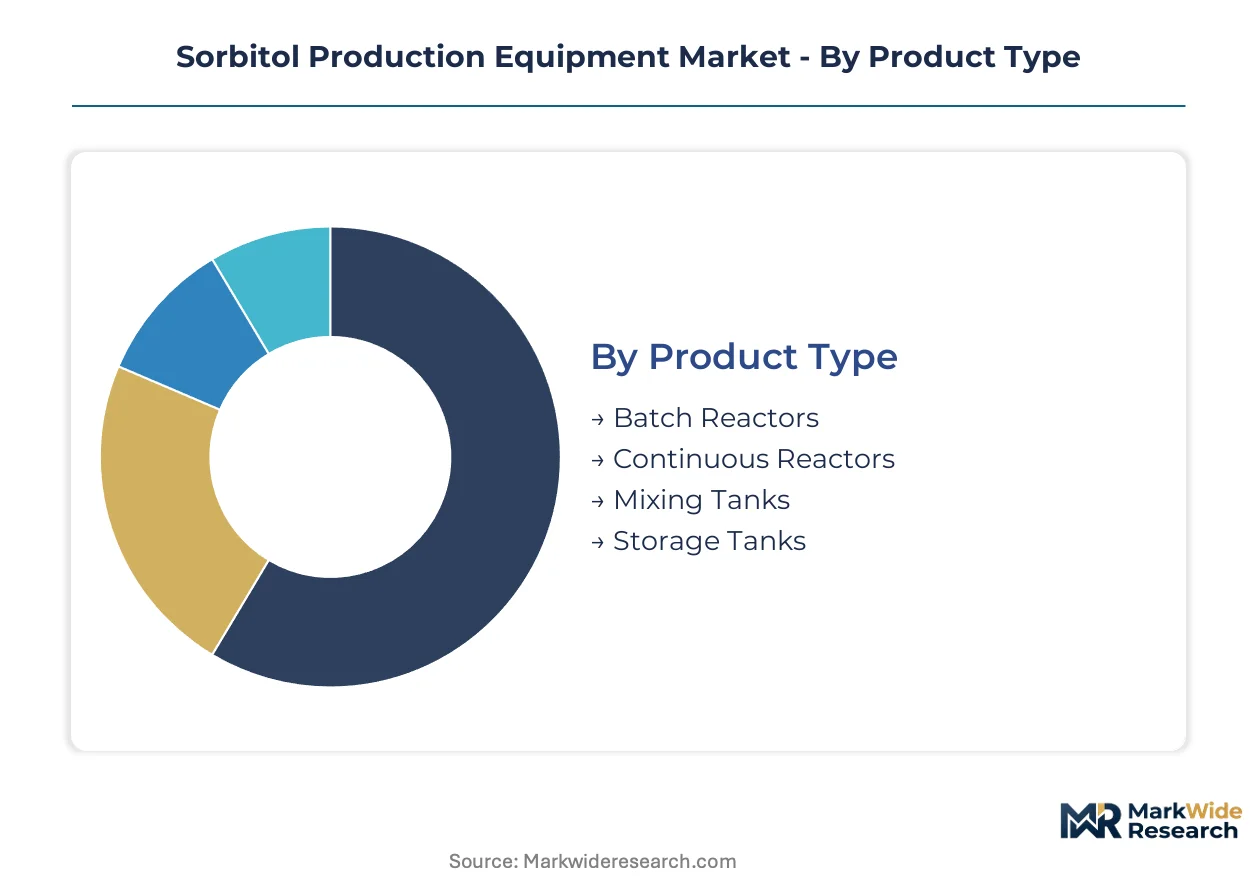
Sorbitol production equipment segments diverge sharply in margin capture, with pharmaceutical-grade continuous systems commanding premium pricing against commoditized batch configurations. Equipment fabricators align R&D spending with end-use purity thresholds rather than unit volume.
Product Type:
Margin pools concentrate in reactor systems where pressure vessel certification and surface finish specifications create vendor stickiness.
- Batch Reactors:Stirred-tank vessels with jacketed heat transfer surfaces accommodate multi-product flexibility for contract manufacturers serving nutraceutical and food-grade clients. Mid-scale Indian sweetener producers favor these systems for their lower capital intensity despite higher per-unit operating costs.
- Continuous Reactors:Fixed-bed catalytic hydrogenation systems with automated temperature-pressure control deliver pharmaceutical-grade sorbitol with tighter molecular weight distribution. German and Swiss excipient manufacturers are retrofitting facilities with these systems to meet EMA cGMP surface finish requirements.
- Mixing Tanks:Stainless steel agitated vessels with sanitary fittings handle intermediate syrup blending and catalyst slurry preparation.
- Storage Tanks:Atmospheric and pressure-rated vessels with nitrogen blanketing preserve sorbitol syrup integrity against oxidation.
The dominant share belongs to Continuous Reactors, while Batch Reactors retain relevance in emerging market capacity expansions.
Technology:
Process chemistry selection determines hydrogen consumption rates, catalyst loading costs, and effluent treatment complexity.
- Catalytic Process:Raney nickel or ruthenium-catalyzed glucose hydrogenation under 40-100 bar pressure remains the installed base standard for industrial-scale sorbitol production. REACH compliance on nickel leaching is forcing closed-loop catalyst recovery retrofits across European facilities.
- Enzymatic Process:Glucose oxidoreductase biocatalysis operates at ambient pressure with reduced energy input, attracting personal care formulators seeking bio-based processing claims. European cosmetic manufacturers are piloting modular skid-mounted enzymatic systems for rapid product changeover.
- Chemical Process:Electrochemical reduction pathways without molecular hydrogen are gaining research attention for carbon footprint reduction.
- Fermentation Technology:Microbial conversion of glucose by engineered yeast strains produces sorbitol alongside mannitol co-products.
Catalytic Process retains the deepest installed base, though Enzymatic Process is climbing the fastest among sustainability-focused formulators.
End User:
Customer concentration and certification requirements fragment pricing power across buyer categories.
- Pharmaceutical Industry:FDA 21 CFR Part 11 and EMA cGMP compliance mandate validated continuous reactor systems with electronic batch records and orbital-welded autogenous joints. CDSCO alignment with ICH Q7 guidelines is creating certified vendor opportunities for Indian fabricators serving API producers.
- Food & Beverage Industry:Sugar-free confectionery and functional beverage manufacturers in India are scaling crystallization capacity to replace sucrose in reduced-calorie formulations. FSSAI food-contact equipment standards constrain alloy selection for domestic processors.
- Personal Care Sector:Cosmetic formulators prioritize enzymatic process equipment for milder processing claims in humectant applications.
- Chemical Manufacturing:Industrial polyol producers utilize sorbitol as feedstock for surfactant and resin synthesis with lower purity requirements.
Pharmaceutical Industry specifications pull the highest equipment margins, while Food & Beverage Industry volume is expanding most quickly in India.
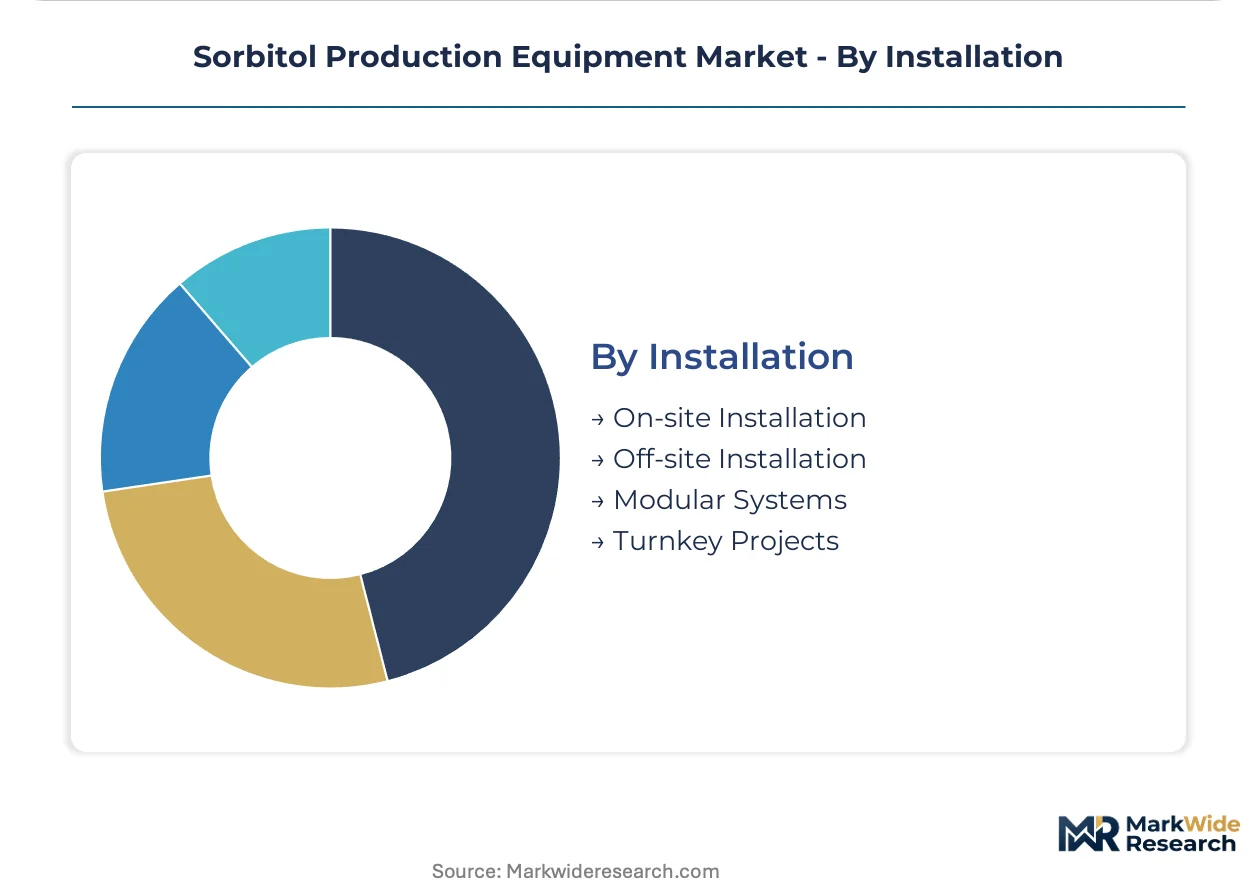
Installation:
Project delivery modality shapes revenue recognition timing and long-term service attachment rates.
- Turnkey Projects:Engineering-procurement-construction contracts bundle process design, equipment fabrication, installation, and commissioning with multi-year validation support agreements. Tier-one food ingredient conglomerates in India are consolidating procurement through single-source EPC contracts rather than fragmented equipment purchases.
- Modular Systems:Pre-fabricated skid-mounted units with plug-and-process architecture compress site installation timelines for brownfield facility upgrades. European personal care formulators favor these configurations for rapid product changeover and relocation flexibility.
- On-site Installation:Field-erected equipment with localized welding and inspection accommodates non-standard facility footprints.
- Off-site Installation:Remote fabrication with final module delivery minimizes production disruption at operating facilities.
Turnkey Projects command the steepest expansion trajectory as buyer concentration favors consolidated procurement, while Modular Systems are gaining share fastest among agile manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian turnkey engineering houses export crystallization systems to Southeast Asian sweetener processors while European pharmaceutical fabricators supply hydrogenation reactors to German and Swiss excipient manufacturers.
India
Domestic sugar processors in Gujarat and Maharashtra are scaling sorbitol capacity to serve functional beverage and sugar-free confectionery demand. CDSCO alignment with ICH Q7 guidelines tightens weld inspection and surface finish requirements for equipment serving API producers. Ahmedabad and Vadodara host fabrication clusters where stainless steel pressure vessel specialists serve both pharmaceutical and food-grade clients.
Germany
Pharmaceutical excipient manufacturers in the Rhine-Ruhr region pilot membrane-assisted catalytic hydrogenation systems for tighter molecular weight distribution control. EMA cGMP standards mandate Ra 0.4 micrometer surface finishes, forcing equipment upgrades across contract manufacturing organizations. Bavarian engineering firms supply validated continuous reactor systems with electronic batch record integration to Swiss and Austrian drug producers.
China
East Asian turnkey crystallization system engineering concentrates in Shandong and Jiangsu provinces serving domestic and export sweetener markets. NMPA enforces GB standards for food-contact equipment that constrain alloy selection and cleaning system design. Qingdao and Nanjing host integrated EPC providers bundling process design with multi-year validation support agreements.
Switzerland
Swissmedic pharmaceutical-grade requirements pull premium equipment specifications for sorbitol destined for drug excipient applications. Basel-area chemical producers retrofit facilities with continuous hydrogenation systems to meet REACH substance restrictions on nickel catalyst leaching. Swiss engineering consultancies specify ceramic membrane modules for inline glucose conversion pilot programs.
United States
FDA 21 CFR Part 11 compliance mandates validated software platforms for electronic batch records in continuous reactor installations. Houston and Bay Area industrial clusters import high-purity nickel alloy components for hydrogenation reactor linings despite Hastelloy price volatility. Personal care formulators in New Jersey request modular skid-mounted enzymatic systems for rapid product changeover.
Sorbitol Production Equipment Market Vendor Landscape
Listed leaders compete with private specialists across fabrication scale and certification depth. The vendor base stratifies between multinational turnkey engineering houses and regional stainless steel pressure vessel fabricators. Three archetypes dominate: scale-driven EPC integrators, purity-focused pharmaceutical specialists, and agile batch reactor customizers. Competitive moves concentrate on single-source procurement consolidation and aftermarket service unbundling.
Among Indian fabricators, Dipesh Engineering Works and Raj Process Equipment and Systems exemplify the regional specialist archetype serving domestic pharmaceutical and sweetener clients. Beijing MecKey Engineering occupies a position representing East Asian turnkey crystallization system engineering. These three anchors illustrate how geographic concentration in fabrication expertise shapes competitive positioning across pharmaceutical-grade and food-grade equipment tiers.
| Leading Market Players |
|---|
| Dipesh Engineering Works |
| Raj Process Equipment and Systems |
| Bosida Machinery |
| Beijing MecKey Engineering |
| Sri Ram Engineering & Fabrication Works |
| Mukul Engineering Works |
| DSSE |
| Ilshin Autoclave |
| Universal Process Engineers |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-month lead times for pharmaceutical-grade hydrogenation reactors concentrate pricing power among certified fabricators in Gujarat and Shandong, compressing margins for buyers locked into EMA cGMP upgrade cycles. Inventory scarcity for ASME Section IX qualified welders extends project timelines and amplifies cost premiums for surface-finish specifications below Ra 0.4 micrometers.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures for turnkey crystallization systems, with pharmaceutical-grade continuous reactors commanding substantial premiums over food-grade batch configurations. Price differentiation rests on certification tier—FDA 21 CFR Part 11 validation versus FSSAI food-contact compliance—and the inclusion of multi-year aftermarket service contracts. Cost compression in mid-scale batch reactor segments is intensifying because Indian sugar processors are consolidating procurement through single-source EPC agreements, squeezing standalone equipment vendors. Contract manufacturing organizations exhibit highest price sensitivity due to capital constraints, while multinational excipient producers absorb premiums for validated electronic batch record integration.
Supply Chain Analysis
Inventory scarcity for high-purity nickel alloys stretches lead times and forces buyers into long-term offtake arrangements with Hastelloy and Inconel distributors. Fabrication capacity concentrates in India, China, and South Korea, with turnkey engineering houses in Shandong and Jiangsu dominating crystallization system exports. Raw material dependencies draw from specialty steel mills in Japan and Germany, precision catalyst suppliers in Belgium, and orbital welding equipment manufacturers in the United States. Single-source vulnerability pervades ASME-certified pressure vessel fabrication, where qualified welder pools are thin across all three supply hubs. Distribution runs through direct EPC contracting for large sweetener producers and regional equipment distributors serving mid-scale pharmaceutical clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from validation documentation and weld inspection contracts is expanding faster than hardware sales, creating durable margin pools for vendors unbundling aftermarket support from capital equipment.
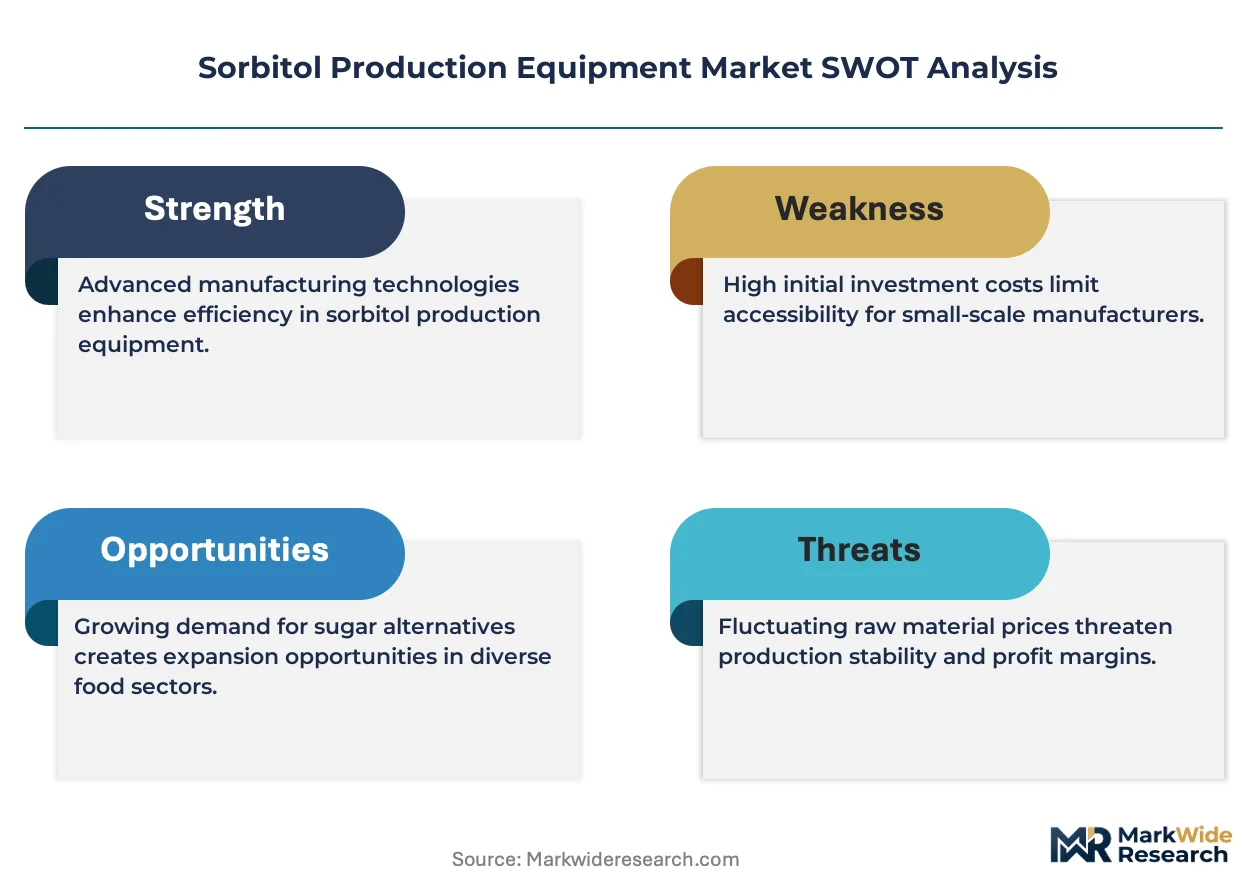
For Market Incumbents: Compound certification depth to defend against modular enzymatic system entrants targeting personal care formulators. Invest in backward integration into specialty alloy distribution to buffer Hastelloy price volatility. Lock in multi-year validation service contracts with CDSCO-aligned Indian API producers before regional competitors achieve ICH Q7 certified vendor status. For New Entrants and Emerging Players: Lead with skid-mounted enzymatic systems for European cosmetic manufacturers seeking rapid product changeover and bio-based processing claims. Target underpenetrated mid-scale Indian sweetener processors in Maharashtra bypassing single-source EPC consolidation through modular equipment financing. Position through equipment-as-a-service models lowering upfront capital barriers for contract manufacturing organizations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned pharmaceutical equipment divisions lacking cGMP certification investment. Five-to-ten-year viability hinges on regulatory alignment density rather than unit volume scale. Watch for CDSCO enforcement tightening on ICH Q7 weld inspection standards as the inflection signal for certified vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive sourcing of Hastelloy linings insulates margins from nickel price volatility affecting reactor fabrication. |
| Modular Skid-Mounted System Launch | Pre-fabricated enzymatic units compress delivery timelines for European personal care formulators seeking relocation flexibility. |
| CDSCO Certification Investment | ICH Q7 aligned weld inspection capabilities unlock certified vendor status serving Indian API producers. |
| Aftermarket Service Unbundling | Standalone validation documentation contracts create recurring revenue streams detached from capital equipment cycles. |
| Membrane-Assisted Hydrogenation Partnership | Ceramic membrane module integration with German engineering consultancies advances continuous reactor purity thresholds. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA inspection databases, and CDSCO manufacturing facility registrations. Interviews with plant engineers at Indian sweetener processors, procurement leads at German excipient manufacturers, aftermarket service heads at pressure vessel fabricators, and regulatory affairs specialists at personal care formulators informed demand-side assumptions. Secondary validation drew from customs trade data for hydrogenation reactor imports, SEC filings of diversified industrial conglomerates with equipment divisions, and ICH Q7 guidance documents. Bottom-up equipment unit estimates triangulated against top-down sweetener industry capacity expansion announcements.
Segmentation dimensions modeled span reactor type, process technology, end-use industry, installation modality, and regional regulatory cluster across the projection horizon. CAGRs derive from fitted growth curves against historical capacity installation patterns and forward-looking regulatory enforcement schedules. Industry-specific inputs include CDSCO alignment timelines for ICH Q7 equipment guidelines, REACH substance restriction implementation phases for nickel catalyst leaching, and FSSAI food-contact equipment standard revision cycles.
The analysis sits within stated boundaries; outcomes outside sustained EMA cGMP enforcement intensity or abrupt Hastelloy supply disruption would require recalibration. Forecasts reflect documented assumptions on regulatory convergence between food-grade and pharmaceutical-grade equipment specifications. Nickel alloy price volatility, orbital welding certification scarcity, and batch-to-continuous transition acceleration represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Global Food Deaerators Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Spray Dried Food Market