
 Wine Bottling Machine Market | 2026-2036
Wine Bottling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Bottling Machine Market Outlook
Italy is rewriting competitive dynamics in wine bottling machinery through its dense cluster of equipment manufacturers in the Veneto and Piedmont regions. Krones AG leverages extensive R&D spending to dominate high-speed rotary systems for sparkling wine. Gai S.p.A. specializes in monoblock rinsing-filling-corking units tailored to mid-size Italian wineries. Sidel Group extends its technology leadership into aseptic bottling lines that preserve wine integrity without preservatives.
A wine bottling machine is an integrated packaging system that rinses, fills, corks or caps, labels, and cases wine bottles at speeds ranging from 1,000 to 60,000 bottles per hour depending on configuration. These machines employ pneumatic, electronic, mechanical, or vacuum technologies to maintain precise fill levels and prevent oxidation during the bottling process. Automatic systems command the largest installed base due to labor cost pressures and throughput requirements at major wineries, while electronic control technology represents the fastest-growing segment as producers replace mechanical timers with servo-driven precision. Vacuum technology occupies a specialized niche for oxygen-sensitive varietals where spoilage risks justify premium equipment pricing.
EU Machinery Directive 2006/42/EC and CE marking requirements shape equipment design standards across European manufacturing, while FDA regulations govern material contact surfaces and sanitization protocols for US-bound wine exports. ISO 22000 food safety management standards increasingly appear in procurement specifications from large beverage manufacturers seeking supply chain certification. Stakeholders must monitor how evolving energy efficiency regulations and carbon footprint disclosure rules reshape capital equipment purchasing criteria across major wine-producing regions.
Market Dynamics
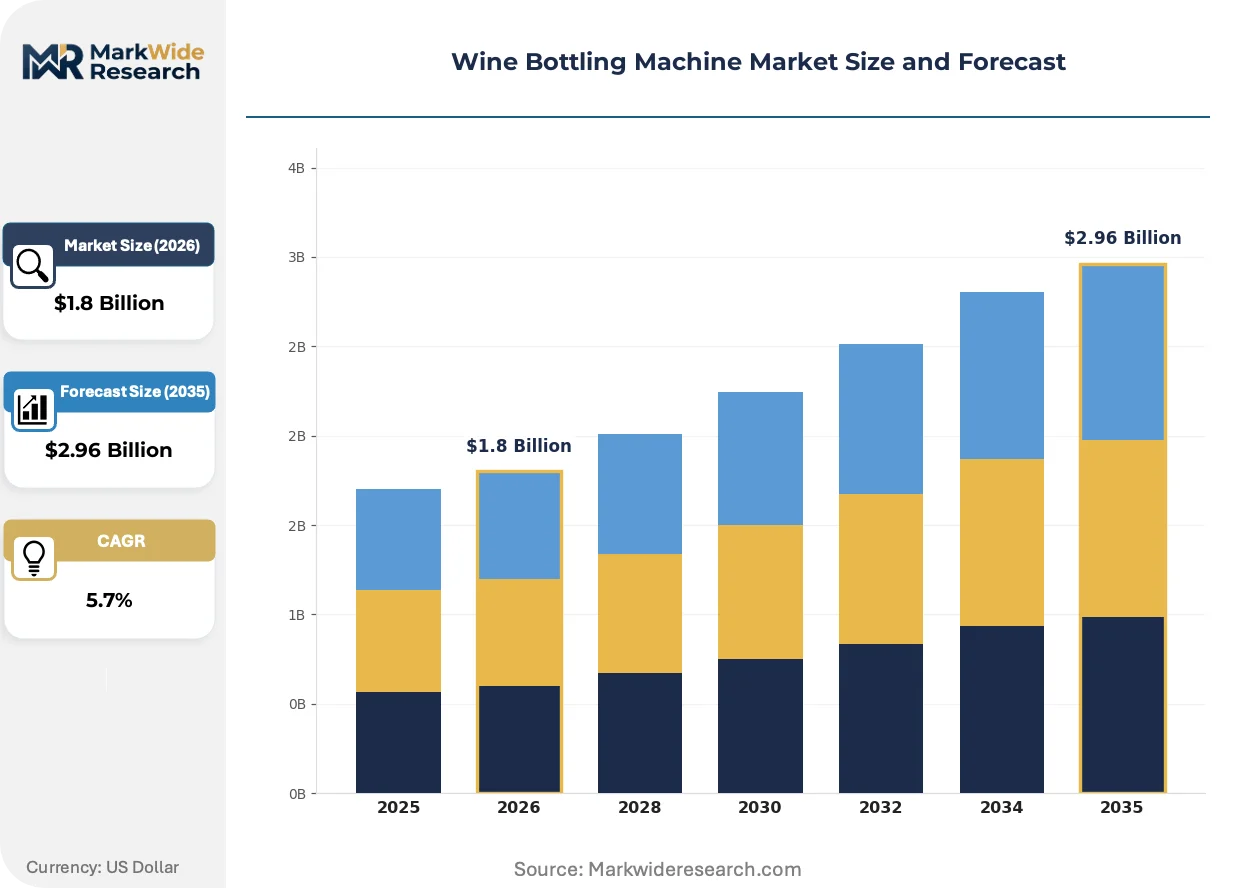
Electronic control systems are displacing mechanical timers across wine bottling installations, driven by CE marking requirements under EU Machinery Directive 2006/42/EC and labor cost pressures at mid-size wineries. This technology transition concentrates investment in Italy, France, and Germany where equipment replacement cycles accelerate.
Growth Catalysts
- EU Machinery Directive compliance:CE marking mandates are forcing mechanical equipment upgrades across European wineries, creating replacement demand for servo-driven bottling lines with integrated safety systems.
- Prosecco export surge:Sparkling wine production in Italy's Veneto region requires high-speed rotary fillers capable of 40,000+ bottles per hour to meet Asian and North American export commitments.
- Vacuum filling technology:Oxygen-sensitive Pinot Noir and Nebbiolo producers in Burgundy and Barolo are specifying vacuum-assisted bottling systems to prevent oxidation and preserve terroir expression.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316L stainless steel price swings compress equipment margins, particularly for Italian manufacturers sourcing from European mills.
- Electronic component concentration:Servo motors and PLCs depend on German and Japanese suppliers, exposing bottling OEMs to extended lead times during semiconductor allocation cycles.
- Skilled technician scarcity:Mechatronics specialists capable of programming servo-driven filling systems command wage premiums that inflate installation and commissioning costs.
Strategic Opportunities
- Aseptic bottling convergence:Sidel Group's extension of aseptic technology into wine applications eliminates preservative use, opening organic and natural wine segments previously blocked by microbial stability requirements.
- Indian wine market emergence:Nascent vineyard development in Maharashtra and Karnataka creates first-mover positioning for compact monoblock systems suited to tropical climates and limited infrastructure.
- Carbon footprint disclosure rules:EU Green Deal reporting requirements favor equipment vendors offering energy consumption certifications and lifecycle carbon assessments as procurement differentiators.
Industry Challenges
- ISO 22000 certification timelines:Food safety management system audits delay equipment delivery to large beverage manufacturers, compressing project margins and extending working capital cycles.
- Legacy mechanical integration:Retrofitting electronic controls onto existing pneumatic bottling lines requires custom engineering that fragments production schedules and strains technical support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Bottling Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Portable Technology: Pneumatic, Electronic, Mechanical, Vacuum End User: Winery, Bottling Plant, Distillery, Beverage Manufacturer Capacity: Small Scale, Medium Scale, Large Scale, Custom |
| Companies Covered | KHS GmbH, CME s.r.l., Krones AG, Bucher Vaslin, Boema S.p.A., Gai S.p.A., GAIotto srl, Enoveneta S.p.A., Sidel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Bottling Machine Market Strategic Shifts
Digital twin technology and predictive maintenance platforms are restructuring how wineries manage bottling line uptime and capital planning. Equipment vendors now bundle software subscriptions with hardware sales, shifting revenue models toward recurring service streams.
Digital twin simulation is virtualizing commissioning workflows for complex rotary filling systems. Italian equipment manufacturers deploy virtual environments to test bottle handling, fill accuracy, and changeover sequences before physical installation. This compression of commissioning timelines reduces winery downtime from weeks to days, particularly critical during harvest season bottling windows.
REACH chemical restrictions on lubricants and seal materials are forcing reformulation of food-grade contact substances used in bottling machinery. Equipment manufacturers must recertify materials compliance across their component supply chains, with sparkling wine applications facing heightened scrutiny due to pressure vessel safety requirements. German regulators are enforcing these standards most aggressively, creating competitive friction for non-EU equipment imports.
After-sales service unbundling is fragmenting traditional equipment procurement relationships. Large wineries in Napa Valley and Bordeaux now contract maintenance separately from capital purchases, favoring specialized service providers with 24-hour response commitments over OEM service departments. This shift pressures equipment margins and forces manufacturers to develop subscription-based diagnostics platforms to retain customer attachment.
Wine Bottling Machine Market Segmentation
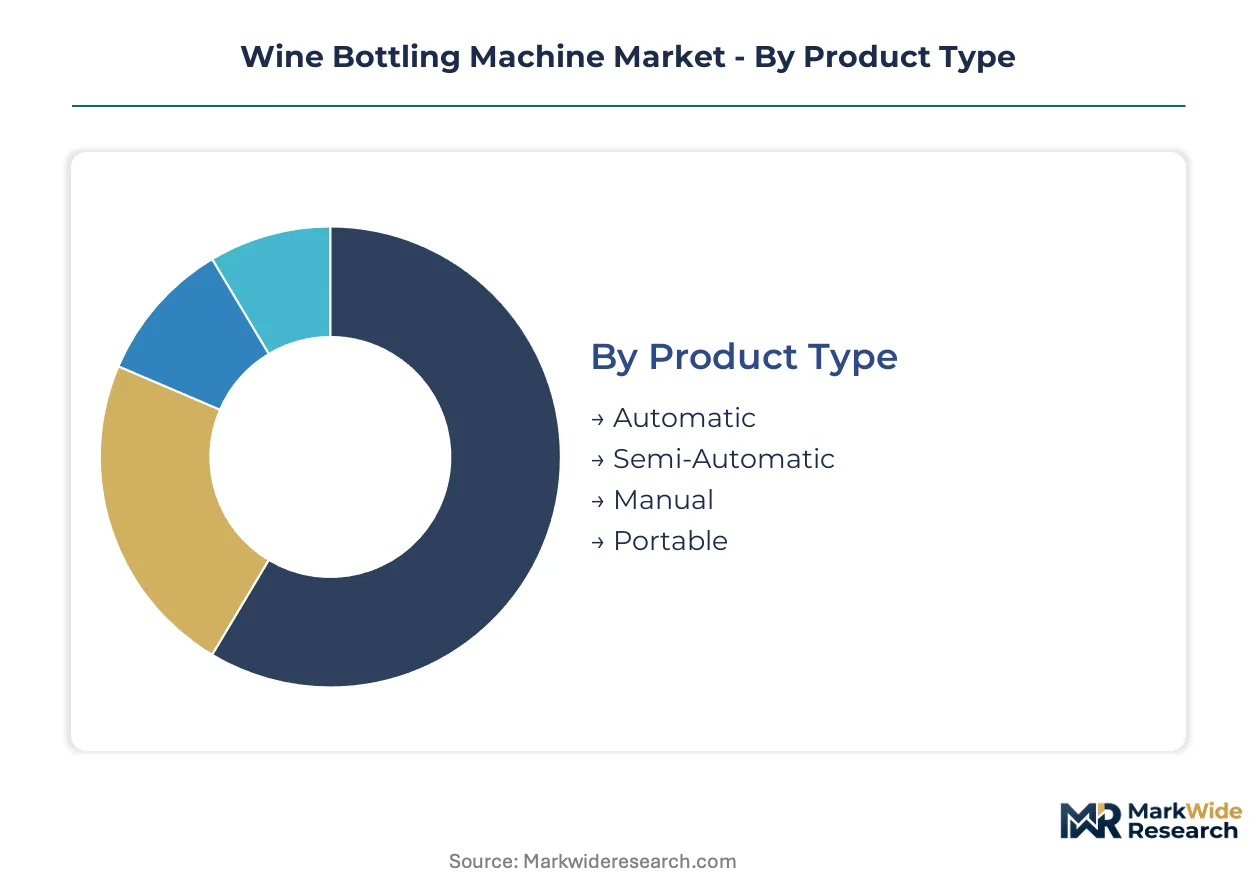
Wine bottling machinery segments reflect divergent capital intensity, labor substitution economics, and regulatory compliance burdens across producer scales. Equipment specification varies dramatically between boutique terroir-focused operations and high-volume export-oriented facilities.
Product Type:
Automation levels span from hand-fed units requiring operator presence at every station to fully integrated lines with robotic palletizing and autonomous changeover sequences.
- Automatic:Integrated rinsing-filling-corking-labeling systems operate at 1,000 to 60,000 bottles per hour with minimal operator intervention. Major wineries in Napa Valley and Bordeaux deploy these lines to compress harvest-season bottling windows and reduce per-unit labor costs.
- Semi-Automatic:Modular stations require manual bottle loading and transfer between functions while automating fill precision and cork insertion. Mid-size Italian wineries in Piedmont favor this tier for flexibility across multiple varietals and bottle formats.
- Manual:Bench-top units suit micro-wineries producing under 10,000 cases annually, where capital constraints outweigh throughput requirements.
- Portable:Trailer-mounted systems enable mobile bottling services serving vineyard estates without permanent production infrastructure.
Established volume favors Automatic; emerging adoption favors Semi-Automatic.
Technology:
Control architectures determine fill accuracy, changeover speed, and integration complexity with upstream tankage and downstream packaging.
- Electronic:Servo-driven actuators and PLC-based controls deliver fill-level precision within millimeters and real-time production analytics. CE marking requirements under EU Machinery Directive 2006/42/EC accelerate displacement of mechanical timers across German and French installations.
- Pneumatic:Compressed-air actuation dominates legacy installations in Spain and Portugal, where equipment replacement cycles lag Northern European adoption curves.
- Mechanical:Cam-driven timing systems persist in developing wine regions where technician scarcity and import tariffs constrain electronic upgrades.
- Vacuum:Oxygen-exclusion filling preserves aromatic compounds in oxygen-sensitive Pinot Noir and Nebbiolo production; Burgundy and Barolo producers specify these systems despite premium pricing.
Electronic systems are climbing the fastest as regulatory mandates and labor costs converge; Vacuum maintains niche premium positioning.
End User:
Customer archetypes differ in batch size variability, contract packaging exposure, and integration with fermentation or distillation operations.
- Winery:Estate-based producers prioritize gentle handling for terroir expression and seasonal surge capacity during harvest. Veneto Prosecco houses drive demand for high-speed rotary fillers capable of 40,000+ bottles per hour.
- Bottling Plant:Contract packagers serving multiple labels require rapid changeover between bottle formats and closure types.
- Distillery:Spirit producers specify explosion-proof configurations and higher fill-temperature tolerance for fortified wine production.
- Beverage Manufacturer:Diversified producers integrate wine lines with existing aseptic juice or ready-to-drink cocktail infrastructure.
Winery direct investment dominates current installations; Beverage Manufacturer diversification offers steepest expansion trajectory.
Capacity:
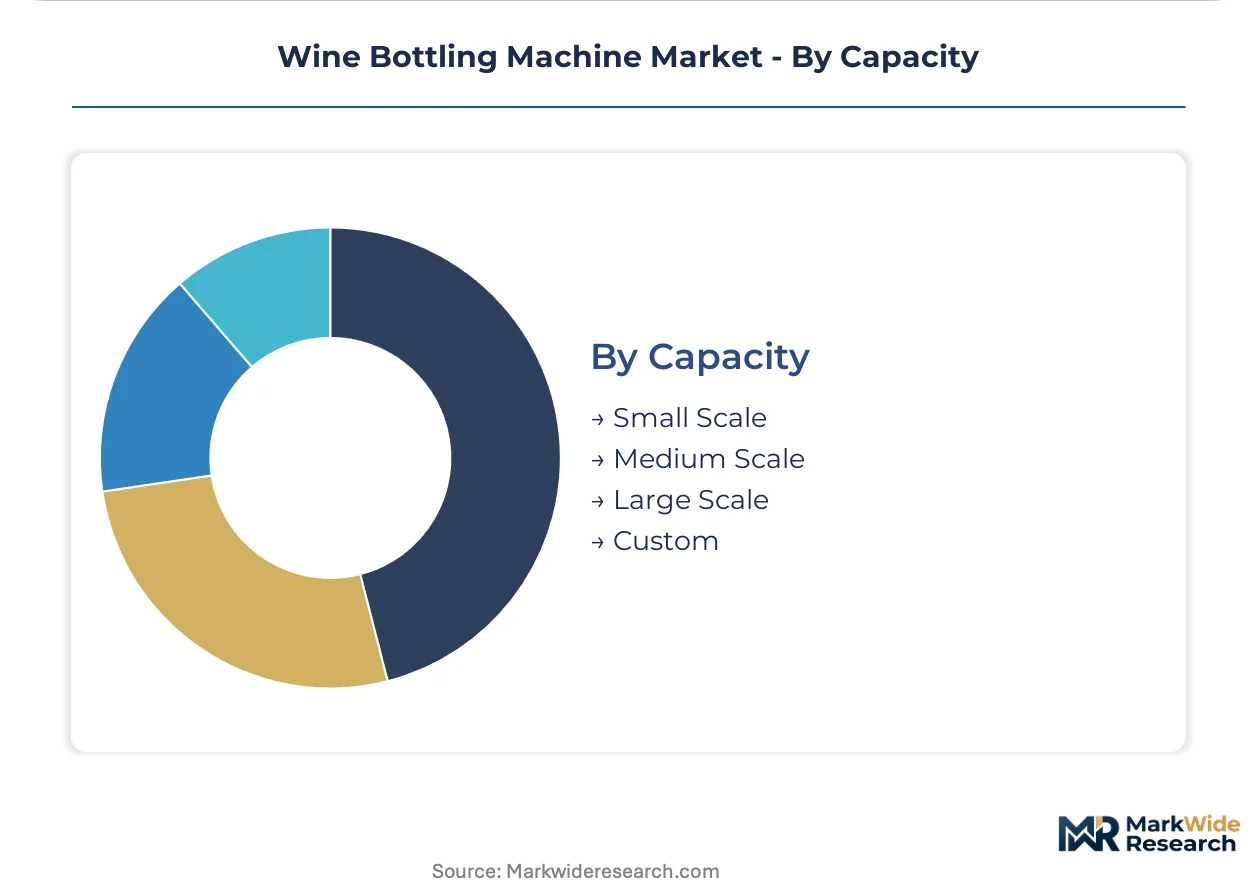
Scale tiers align with harvest logistics, storage economics, and export contract minimums.
- Large Scale:Continuous rotary systems with 50+ filling valves serve export-focused houses with annual production exceeding one million cases.
- Medium Scale:Linear or small rotary configurations suit regional distributors and cooperative wineries with seasonal volume spikes.
- Small Scale:Monoblock units handle 1,000 to 5,000 bottles per hour for estate-bottled operations and emerging vineyards in Maharashtra.
- Custom:Engineered solutions address atypical bottle geometries, alternative closures, or integration with historic facility constraints.
Large Scale commands capital deployment volume; Small Scale gains share fastest as vineyard development accelerates in non-traditional wine regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian equipment manufacturers in Veneto and Piedmont command the densest concentration of wine bottling machinery production, with German and French engineering centers anchoring precision control system development.
Italy
Prosecco export commitments to Asian and North American markets drive installations of high-speed rotary fillers exceeding 40,000 bottles per hour. CE marking requirements under EU Machinery Directive 2006/42/EC accelerate electronic control upgrades across Veneto sparkling wine houses. Equipment fabricators cluster around Conegliano and Valdobbiadene, where proximity to Prosecco production enables rapid commissioning cycles during harvest bottling windows.
Germany
REACH chemical restrictions on lubricants and seal materials force reformulation of food-grade contact substances in bottling machinery components. German regulators enforce these standards most aggressively, creating competitive friction for non-EU equipment imports. Engineering centers in Bavaria and Baden-Württemberg specialize in servo motor and PLC integration for precision filling systems.
France
Oxygen-sensitive Pinot Noir and Nebbiolo producers in Burgundy specify vacuum-assisted bottling systems to prevent oxidation and preserve terroir expression. ANSM and CNIL oversight extends to digital maintenance platforms deployed in winery operations. Equipment demand concentrates in Beaune and Dijon, where contract packagers serving multiple Grand Cru labels require rapid changeover capabilities.
United States
FDA regulations govern material contact surfaces and sanitization protocols for wine exports bound for international markets. Boutique wineries in Napa Valley expand automated bottling lines to meet surging export demand from Asian markets. California's Central Coast and Sonoma County clusters see rising adoption of electronic control retrofits on legacy pneumatic installations.
India
Nascent vineyard development in Maharashtra and Karnataka creates first-mover positioning for compact monoblock systems suited to tropical climates and limited infrastructure. BIS certification requirements for imported industrial machinery extend equipment delivery timelines. Nashik district anchors domestic wine production growth, with local producers specifying small-scale linear fillers for seasonal volume spikes.
Wine Bottling Machine Market Competitive Environment
Integrated multinational systems builders and specialized Italian monoblock fabricators split the market into distinct capability tiers. Consolidation pressure concentrates around electronic control integration and aseptic technology licensing. Three archetypes dominate: high-speed rotary specialists serving export houses, monoblock integrators targeting mid-size estates, and aseptic technology licensors penetrating organic wine segments. Competitive moves center on strategic partnerships for semiconductor supply security and geographic expansion into emerging vineyard regions.
Among German-based engineering groups, KHS GmbH and Krones AG occupy positions as scale-driven rotary system anchors. Italian specialists including Gai S.p.A., Boema S.p.A., and Enoveneta S.p.A. exemplify the mid-tier monoblock archetype with concentrated fabrication in Veneto and Piedmont. Sidel Group represents the aseptic technology vector extending beverage packaging expertise into wine applications.
| Leading Market Players |
|---|
| KHS GmbH |
| CME s.r.l. |
| Krones AG |
| Bucher Vaslin |
| Boema S.p.A. |
| Gai S.p.A. |
| GAIotto srl |
| Enoveneta S.p.A. |
| Sidel Group |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors absorb stainless steel volatility that compresses margins for Veneto fabricators while amplifying price spreads between electronic and pneumatic system tiers. This logistics chokepoint concentrates supply-side leverage among German servo motor suppliers and Japanese PLC vendors, forcing Italian OEMs to pass input costs differentially across buyer segments.
Pricing Analysis
CE marking under EU Machinery Directive 2006/42/EC dictates the pricing tier structure across European wine bottling equipment. Three-tier pricing structure across premium electronic servo systems, standard pneumatic retrofits, and economy mechanical timers separates buyers by certification burden and precision requirements. Price differentiation hinges on ISO 22000 compliance grade and after-sales service bundling. Margins are tightening in the pneumatic tier due to semiconductor allocation cycles extending component lead times. Boutique wineries in Napa Valley exhibit highest price sensitivity, while export-focused Prosecco houses prioritize throughput over capital cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now anchor supplier-finance relationships across Italian equipment fabricators sourcing Grade 304 and 316L stainless steel. Manufacturing concentrates in Italy, Germany, and Japan, with servo motors and PLCs drawing from Bavarian engineering centers and Japanese automation specialists. Raw material dependencies include European mill stainless steel, German precision actuators, and Japanese control electronics. Single-source vulnerability in semiconductor supply creates bottlenecks during allocation cycles. Distribution runs through regional equipment dealers with localized commissioning capabilities and spare parts inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription layers for predictive maintenance and digital twin platforms now expand faster than hardware sales, repositioning capital equipment markets as recurring-revenue service businesses. This attach-rate acceleration favors vendors who bundle diagnostics subscriptions with initial system procurement.
For Market Incumbents: Harden semiconductor supply security through backward integration into servo motor sourcing or exclusive partnerships with German and Japanese component suppliers. Invest in ISO 22000 certification infrastructure to compress audit timelines that currently delay large beverage manufacturer deliveries. CE marking compliance costs threaten margin compression for unprepared competitors.
For New Entrants and Emerging Players: Build out compact monoblock system portfolios targeting Maharashtra and Karnataka vineyard development, where tropical climate adaptations and limited infrastructure favor small-scale linear fillers over rotary systems. Target contract packaging services in France's Beaune-Dijon corridor with rapid-changeover configurations. Go-to-market through mobile bottling service partnerships reduces customer capital burden.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beverage packaging conglomerates seeking to divest wine-specific equipment divisions amid portfolio streamlining. Long-term viability centers on electronic control integration capabilities and aseptic technology licensing positions. Watch for inflection when carbon footprint disclosure rules trigger procurement preference shifts toward certified low-energy systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Launch | Virtual commissioning compresses harvest-season downtime from weeks to days for Prosecco producers. |
| Aseptic Technology Licensing | Sidel Group's beverage expertise opens organic wine segments blocked by preservative restrictions. |
| Backward Integration into Servo Motors | Bavarian engineering centers reduce lead time exposure during Japanese semiconductor allocation cycles. |
| Mobile Bottling Service Partnership | Trailer-mounted systems penetrate Maharashtra estates lacking permanent production infrastructure. |
| Carbon Certification Program | EU Green Deal reporting requirements favor vendors with lifecycle energy assessments. |
Study Parameters
The analysis maps automatic, semi-automatic, and manual bottling system sub-sectors, each validated through equipment procurement directors at major wineries, aftermarket service heads at Italian OEMs, and plant engineers at contract packaging facilities. Primary interviews with these stakeholders combined with secondary validation from EU Machinery Directive compliance databases, FDA material contact surface regulations, and stainless steel trade flow records. Bottom-up equipment shipment tallies triangulate against top-down winery capital expenditure surveys across the analysis window.
Assumptions held fixed include CE marking enforcement intensity, REACH chemical restriction timelines, and semiconductor allocation cycle patterns, while varying Prosecco export demand trajectories and Indian vineyard development rates. The analytical framework models automation level, technology type, end-user archetype, and capacity tier across the projection horizon. CAGRs derive from segment-level volume buildups calibrated to harvest logistics and replacement cycle data. Forecast inputs include stainless steel price indices and skilled technician wage premiums.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese automation suppliers or accelerated Indian domestic manufacturing would shift outcomes. Macroeconomic deviation, regulatory enforcement changes, or breakthrough aseptic technology adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Food Preservation Equipment Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Contact and Convective Dryers Market