
 Beverage Processing Equipment Market | 2026-2036
Beverage Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Processing Equipment Market Analysis
Multi-source equipment procurement is pivoting toward integrated single-vendor partnerships as beverage makers consolidate supplier relationships. Krones AG leverages its turnkey line engineering to dominate high-speed bottling installations worldwide. Alfa Laval Corporate AB specializes in heat exchange and separation technologies that anchor thermal processing workflows for dairy and juice applications. Tetra Pak Inc. controls aseptic carton filling channels and extends its reach through packaging-processing integration.
Beverage processing equipment encompasses mechanical systems engineered to transform raw liquid inputs into packaged, shelf-stable finished drinks through controlled unit operations including filtration, thermal treatment, carbonation, and precision filling at throughputs ranging from artisanal batch scales to 100,000-plus bottles per hour. Filtration systems and pasteurizers represent mature margin pools where aftermarket service contracts generate recurring revenue, while membrane filtration technology within the automation segment is displacing conventional separation methods in craft and functional beverage plants. Mixing equipment competes for capital allocation as ready-to-drink formulations proliferate across soft drinks and alcoholic beverage applications.
The FDA enforces sanitary design standards under FSMA that compel equipment redesign for clean-in-place compatibility, while the EPA regulates wastewater discharge from rinsing and CIP operations. ISO 22000 and 3-A Sanitary Standards shape export market access by certifying hygienic construction protocols. Stakeholders must monitor how the EU Green Deal's packaging waste directives and emerging state-level extended producer responsibility frameworks in California and New York reshape equipment specifications for recyclability and material recovery.
Market Dynamics
Consolidation of supplier relationships into turnkey partnerships is compressing procurement cycles and locking in long-term service revenues for integrated line engineers. Craft beverage makers now demand modular systems that scale from pilot batches to commercial volumes without full line replacement.
Growth Catalysts
- FSMA sanitary mandates:FDA clean-in-place requirements force equipment upgrades across US dairy and juice facilities, creating replacement demand for legacy pasteurizers and filling systems.
- Functional beverage proliferation:Ready-to-drink protein, probiotic, and adaptogenic formulations require precision mixing and aseptic processing capabilities absent in conventional soft drink lines.
- German precision engineering clusters:Concentrated supplier ecosystems around Munich and Hamburg accelerate innovation cycles for high-speed filling systems serving export markets.
Market Restraints
- Stainless steel input volatility:Grade 316L and 304 price swings compress margins for tank and piping fabricators, forcing hedging costs onto equipment purchasers.
- European supplier concentration:Dominance of turnkey line engineers in Germany and Denmark creates bottleneck risk for North American and Asian beverage makers seeking rapid installation.
- Membrane fouling limitations:Polymeric filtration membranes require frequent replacement in high-TDS applications, limiting adoption in mineral-heavy functional waters.
Strategic Opportunities
- India packaged beverage expansion:FSSAI enforcement of hygienic processing standards and rising middle-class consumption create first-mover advantage for aseptic carton filling installations.
- EU Green Deal packaging directives:Recyclability mandates and extended producer responsibility frameworks favor equipment designed for lightweight, mono-material containers.
- AI-driven predictive maintenance:Convergence of IoT sensors and machine learning algorithms enables outcome-based service contracts that lock in decade-long aftermarket revenue streams.
Industry Challenges
- Automation engineering talent scarcity:Shortage of PLC programmers and sanitary welding specialists delays commissioning timelines for complex multi-vendor lines.
- Legacy system integration friction:Retrofitting 1990s-era batch control systems with modern SCADA architectures requires custom middleware that inflates project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Processing Equipment Market |
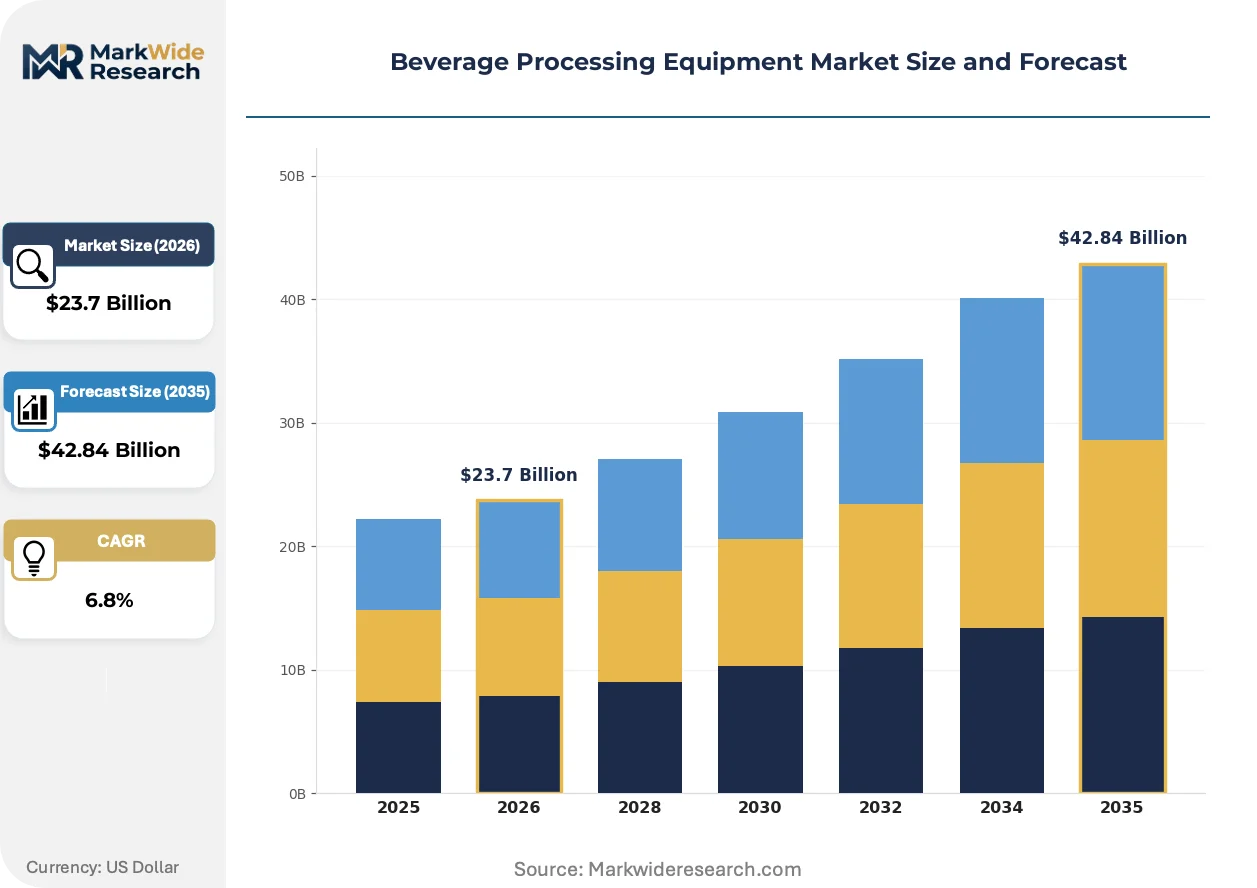
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottling Machines, Filtration Systems, Mixing Equipment, Pasteurizers Application: Soft Drinks, Alcoholic Beverages, Dairy Products, Juices End User: Breweries, Distilleries, Beverage Manufacturers, Hospitals Technology: Automation, Membrane Filtration, Heat Exchange, Vacuum Technology |
| Companies Covered | Krones AG, Tetra Pak Inc., Alfa Laval Corporate AB, GEA Group Aktiengesellschaft, SPX FLOW Inc., Bucher Industries AG, John Bean Technologies Corporation, KHS GmbH, Bühler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Processing Equipment Market Emerging Trajectories
Digitalization of processing workflows and modular equipment architectures are compressing the traditional seven-year replacement cycle for beverage lines. Manufacturers now prioritize flexibility over maximum throughput.
Membrane filtration technology is decentralizing separation operations previously concentrated in centralized utilities. Craft breweries and functional beverage startups in Colorado and Oregon adopt skid-mounted nanofiltration units that bypass regional water treatment infrastructure. This distributed model reduces dependency on municipal supply quality while enabling on-site mineral profile customization.
REACH chemical restrictions and F-Gas Regulation phase-downs in Europe are accelerating adoption of ammonia and CO2-based refrigeration in thermal processing. German equipment engineers now design pasteurizers around natural refrigerant architectures that eliminate HFC dependency. Dairy processors in Bavaria and Baden-Württemberg lead this transition, driven by compliance deadlines and carbon accounting requirements.
Service contract unbundling is fragmenting the traditional bundled maintenance model. Large beverage conglomerates in Brazil and Mexico now separate spare parts procurement from technical support, using third-party logistics providers for inventory management while retaining OEM expertise for critical overhauls. This bifurcation pressures equipment makers to defend margin on consumables and wear components.
Beverage Processing Equipment Market Segmentation
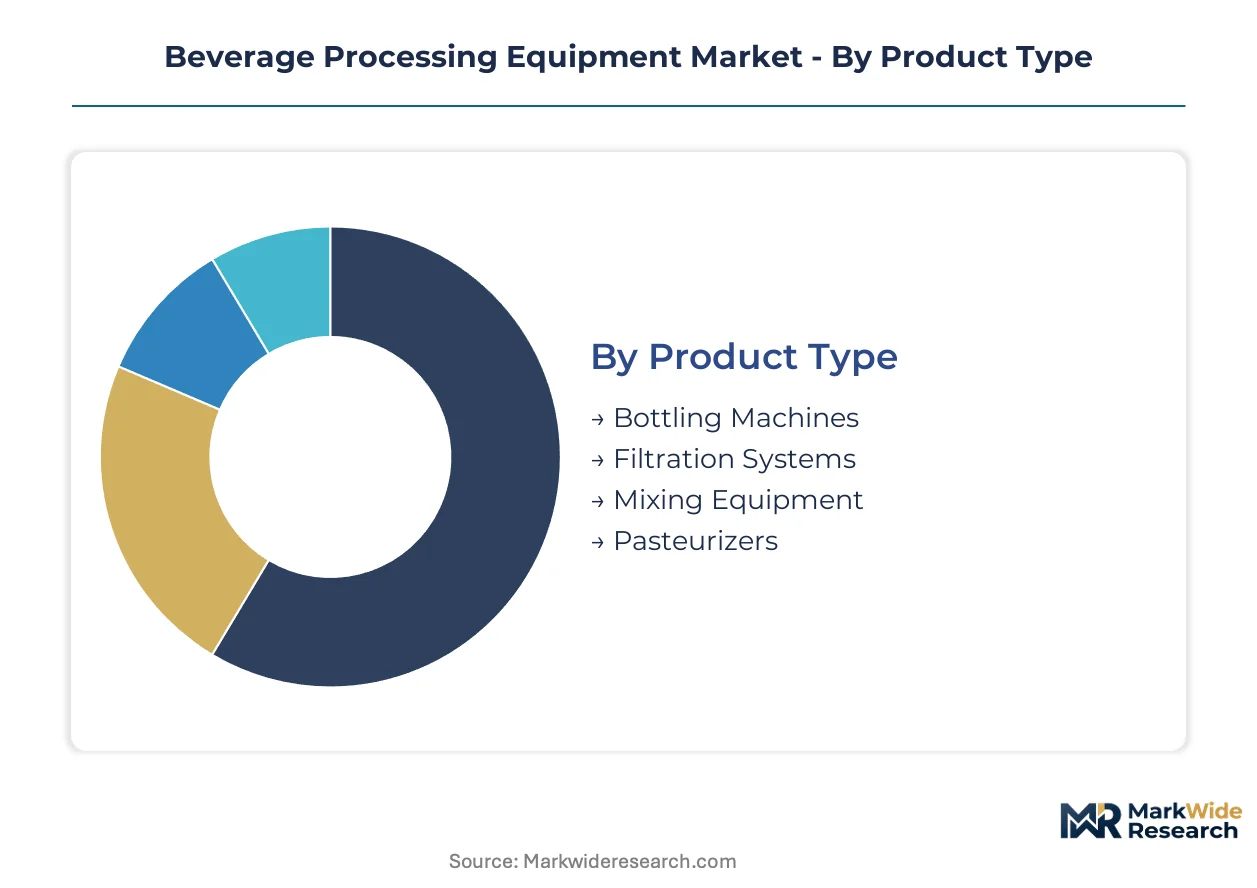
Beverage processing equipment segmentation reveals how regulatory burdens and application requirements fragment procurement decisions across distinct technical specifications. Equipment buyers prioritize certification compatibility and line integration over standalone performance metrics when allocating capital across these categories.
Product Type:
3-A Sanitary Standards and FDA FSMA clean-in-place mandates impose divergent certification loads across equipment categories, with thermal and filling systems facing the most stringent validation protocols.
- Bottling Machines:High-speed rotary fillers and counter-pressure systems engineered for carbonated and still liquid containment at throughputs exceeding 100,000 units hourly. Demand concentrates in German precision engineering clusters serving export markets, driven by craft brewery automation upgrades and aseptic dairy line expansions requiring validated sterile filling environments.
- Filtration Systems:Cross-flow membrane arrays and depth filtration skids removing particulates, microorganisms, and dissolved solids from liquid streams. European craft beverage producers in Denmark and Bavaria adopt decentralized nanofiltration units to bypass municipal water infrastructure while customizing mineral profiles for functional drinks.
- Mixing Equipment:Batch and continuous blending systems achieving homogeneity in multi-component formulations. Ready-to-drink protein and adaptogenic beverage startups in Colorado and Oregon drive specification changes for precision ingredient dosing.
- Pasteurizers:Tunnel, flash, and batch thermal treatment systems ensuring pathogen elimination and shelf stability. EU F-Gas Regulation compliance deadlines accelerate ammonia-based refrigeration retrofits in Bavarian dairy operations.
Leading the category by volume: Bottling Machines. Growing fastest: Filtration Systems.
Application:
End-use liquid chemistry and packaging format dictate equipment material specifications and sanitary design intensity, with dairy and functional beverages imposing the most exacting surface finish and cleanability standards.
- Soft Drinks:Carbonated and still formulations requiring syrup blending, deaeration, and high-speed filling at massive scale. Coca-Cola and PepsiCo bottling networks in Mexico and Brazil consolidate procurement around single-vendor turnkey partnerships to compress commissioning timelines.
- Alcoholic Beverages:Fermentation-derived products spanning beer, wine, and spirits with variable alcohol content and CO2 loading. Craft breweries across North America expand automated bottling lines while demanding modular scaling from pilot to commercial volumes.
- Dairy Products:Heat-sensitive protein matrices requiring gentle thermal processing and aseptic packaging integration. FSSAI enforcement in India creates first-mover advantage for aseptic carton filling installations as middle-class consumption expands.
- Juices:Acidic, pulp-laden, and enzyme-active liquids demanding specialized filtration and pasteurization profiles. California and Florida processors navigate EPA wastewater discharge regulations from rinsing and CIP operations.
Dairy Products command the highest equipment margins per liter processed. Juices exhibit the steepest expansion trajectory as cold-pressed and functional variants proliferate.
End User:
Operational scale and technical staffing depth determine automation architecture preferences, with large beverage conglomerates favoring integrated SCADA systems while smaller producers prioritize operator-friendly interfaces.
- Breweries:Fermentation-based operations spanning craft microbreweries to multinational lager producers. Modular system demand from Colorado and Oregon craft producers enables scaling without full line replacement.
- Distilleries:High-proof alcohol production facilities requiring explosion-rated electrical systems and specialized heat exchange. Kentucky and Tennessee whiskey producers invest in heritage-compatible automation preserving traditional mash bills.
- Beverage Manufacturers:Integrated soft drink, water, and functional drink producers operating at industrial scale. Brazilian and Mexican conglomerates unbundle service contracts, separating spare parts logistics from OEM technical support.
- Hospitals:Institutional foodservice operations requiring compact, validated equipment for patient nutrition and therapeutic beverages. US healthcare facilities navigate FDA medical food regulations alongside standard food safety protocols.
Beverage Manufacturers dominate capital deployment. Breweries show the fastest automation adoption curve among end-user categories.
Technology:
Digital integration intensity varies sharply across technical platforms, with automation and membrane systems enabling predictive maintenance revenue models while mature thermal technologies compete on equipment margin alone.
- Automation:PLC-controlled line integration, robotic handling, and SCADA-enabled process visibility. AI-driven predictive maintenance converges with IoT sensors to enable decade-long outcome-based service contracts for large beverage conglomerates.
- Membrane Filtration:Polymeric and ceramic barrier technologies displacing conventional separation in craft and functional beverage plants. Fouling limitations in high-TDS mineral waters constrain adoption despite superior separation precision.
- Heat Exchange:Plate, tubular, and scraped-surface thermal transfer systems anchoring pasteurization and cooling operations. Natural refrigerant architectures eliminate HFC dependency in German-engineered dairy pasteurizers.
- Vacuum Technology:Deaeration, degassing, and concentration systems preserving flavor compounds and extending shelf life. Soft drink producers leverage vacuum deaeration to reduce dissolved oxygen and inhibit oxidative degradation.
Automation commands the largest installed base. Membrane Filtration is expanding most quickly as distributed processing models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock availability from German mills anchors European equipment fabrication, while precision engineering clusters in Bavaria and Hamburg export turnkey bottling systems worldwide. Demand fragmentation across regulatory jurisdictions shapes regional procurement priorities.
United States
Craft brewery automation upgrades and FSMA-mandated pasteurizer replacements drive capital deployment. FDA clean-in-place requirements compel equipment redesigns across dairy and juice facilities in Wisconsin and California. Denver and Portland anchor functional beverage startup ecosystems adopting modular nanofiltration skids.
Germany
Krones AG and KHS GmbH anchor Munich and Hamburg precision engineering clusters serving export markets for high-speed filling systems. EU F-Gas Regulation deadlines accelerate ammonia-based refrigeration retrofits in Bavarian dairy pasteurizers. Baden-Württemberg processors lead natural refrigerant adoption for carbon accounting compliance.
India
FSSAI enforcement of hygienic processing standards and rising middle-class consumption create first-mover opportunities for aseptic carton filling installations. Maharashtra and Karnataka beverage manufacturers expand capacity to serve urban demand growth. Mumbai and Bangalore anchor procurement decision-making for integrated line engineering.
Brazil
Large beverage conglomerates unbundle service contracts, separating spare parts logistics from OEM technical support. ANVISA sanitary regulations align with FDA frameworks for multinational equipment standards. São Paulo state concentrates bottling network investments from Coca-Cola and PepsiCo bottlers.
China
Domestic dairy processors expand aseptic filling capacity under GB food safety standards tightening cleanability requirements. Yangtze River Delta manufacturers source membrane filtration components for functional water production. Shanghai and Jiangsu province anchor equipment procurement for ready-to-drink formulation lines.
Beverage Processing Equipment Market Vendor Landscape
Strategic partnerships dominate the current landscape as beverage makers consolidate supplier relationships into turnkey line engineering contracts. The vendor base concentrates around integrated line engineers, component specialists, and regional fabricators serving distinct automation tiers. Three archetypes prevail: German precision engineering conglomerates, Scandinavian thermal processing specialists, and Swiss-American diversified industrials. M&A activity and geographic licensing agreements represent the primary competitive vectors reshaping market share distribution.
Within the precision engineering tier, Krones AG exemplifies turnkey line integration capabilities, while KHS GmbH occupies a comparable position in high-speed filling systems. Alfa Laval Corporate AB represents the thermal processing specialist archetype, anchoring heat exchange and separation technology supply for dairy and juice applications. Tetra Pak Inc. sits within the packaging-processing integration segment, controlling aseptic carton filling channels through combined equipment and material supply arrangements.
| Leading Market Players |
|---|
| Krones AG |
| Tetra Pak Inc. |
| Alfa Laval Corporate AB |
| GEA Group Aktiengesellschaft |
| SPX FLOW Inc. |
| Bucher Industries AG |
| John Bean Technologies Corporation |
| KHS GmbH |
| Bühler Group |
| Others |
Supply Flow & Price Mechanics
Grade 316L stainless steel price volatility cascades through fabrication tiers into equipment pricing stratification, compressing margins for tank and piping fabricators while forcing hedging costs onto beverage manufacturers procuring turnkey bottling lines.
Pricing Analysis
Warranty and service bundling unbundling now defines pricing architecture across the market. Three-tier pricing structure across premium, standard, and economy levels separates validated aseptic systems from modular craft-scale units and refurbished legacy equipment, with FSMA certification tier and aftermarket service depth as primary differentiation drivers. Cost compression in standard-tier membrane filtration skids is intensifying because Brazilian and Mexican conglomerates now separate spare parts logistics from OEM technical support. Craft breweries in Colorado and Oregon exhibit highest price sensitivity, while multinational dairy processors in Bavaria show lowest sensitivity due to carbon accounting compliance deadlines.
Supply Chain Analysis
India's phased manufacturing program and local-content mandates for food processing equipment are reshaping sourcing patterns for multinational suppliers. German precision engineering clusters around Munich and Hamburg, Italian stainless steel fabricators in Lombardy, and Chinese component manufacturers in Jiangsu province anchor global supply. Production draws from Grade 316L and 304 stainless steel mills, polymeric membrane substrates, and precision servo motors. Single-source vulnerability concentrates in German high-speed filling system engineering. Distribution runs through OEM-direct turnkey contracts for large beverage conglomerates and regional distributor networks for craft-scale modular systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as FSMA sanitary mandates and stainless steel input volatility force sub-scale fabricators into distress, compressing the vendor base toward integrated line engineers with captive service revenue streams.
For Market Incumbents: Cement turnkey line engineering dominance by acquiring distressed regional fabricators in India and Brazil to secure FSSAI and ANVISA certification capabilities in-house. Deepen backward integration into stainless steel fabrication through captive supply agreements with Baden-Württemberg mills, insulating margin from commodity swings while locking in delivery priority for ammonia-based refrigeration pasteurizer retrofits.
For New Entrants and Emerging Players: Enter via distributed nanofiltration skids for functional beverage startups in Denver and Portland, where municipal water bypass demand outstrips incumbent supply capacity. Target India's Maharashtra and Karnataka beverage manufacturers with modular aseptic carton filling systems priced below Tetra Pak's integrated material-plus-equipment bundles, leveraging local fabrication partnerships to satisfy phased manufacturing content rules.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap thermal processing specialists with ammonia refrigeration retrofit expertise in Bavaria and Baden-Württemberg, where EU F-Gas Regulation compliance deadlines create forced-upgrade demand visibility. Long-term viability hinges on aftermarket service contract attach rates above sixty percent. Watch for inflection when Brazilian conglomerates reverse service contract unbundling and return to bundled OEM maintenance.
| Strategic Initiative | Industry Significance |
|---|---|
| Turnkey Line Integration | Compresses procurement cycles for Coca-Cola and PepsiCo bottlers in São Paulo state. |
| Ammonia Refrigeration Retrofit | Eliminates HFC dependency for Bavarian dairy processors facing F-Gas deadlines. |
| Modular System Architecture | Enables Colorado craft breweries to scale without full line replacement. |
| Predictive Maintenance Platform | Locks decade-long revenue through IoT-enabled outcome-based service contracts. |
| Local Content Partnership | Satisfies India's phased manufacturing program for aseptic filling installations. |
Methodological Framework
Multi-period observation of stainless steel price indices, FSMA enforcement timelines, and aseptic filling installation backlogs anchored the trend analysis, supplemented by interviews with plant engineers at multinational beverage conglomerates, procurement directors at Brazilian and Mexican bottlers, aftermarket service heads at German precision engineering firms, and regulatory affairs leads navigating FSSAI certification. Secondary validation drew from FDA warning letter databases, EU F-Gas Regulation implementation notices, SEC 10-K filings of listed equipment manufacturers, and customs records of stainless steel imports into Germany and India. Bottom-up project pipeline enumeration triangulated against top-down macroeconomic demand modeling.
Segment-weighting across product type, application, end user, and technology dimensions structured the analytical framework, with additional weighting for regulatory compliance tier. CAGRs derived from installed base replacement cycles, capacity expansion announcements, and functional beverage formulation proliferation rates across the projection horizon. Forecast inputs incorporated clean-in-place retrofit demand curves, natural refrigerant adoption S-curves, and service contract unbundling patterns in Latin American markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt stainless steel price spikes or accelerated EU Green Deal packaging waste directive implementation. Forecasts reflect documented assumptions regarding FSMA enforcement intensity and FSSAI inspectorate staffing expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Global Nutating Mixers Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market