
 Automatic Grilling Machine Market | 2026-2036
Automatic Grilling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Grilling Machine Market Outlook
Stainless steel is rebalancing cost structures across the automatic grilling machine supply chain as manufacturers substitute thicker-grade alloys for coated carbon steel in firebox assemblies. Weber leverages its foundry partnerships to sustain vertical integration over burner component supply. Traeger anchors its position through pellet-feed automation R&D intensity in Utah manufacturing facilities. The Middleby Corporation dominates commercial installation channels through broad foodservice equipment portfolios.
An automatic grilling machine integrates electric, gas, or pellet combustion systems with automated temperature modulation, conveyor mechanisms, or programmable cooking cycles to execute consistent grilling operations without continuous operator intervention. Commercial units typically achieve surface temperatures between 300°F and 700°F through infrared or convective heat distribution, with belt speeds adjustable to 0.5–3.0 inches per second for protein throughput standardization. Electric grills lead the product type category in home user penetration due to apartment fire-code compatibility, while smart grilling technology commands the fastest expansion trajectory as Wi-Fi-enabled temperature logging becomes standard in restaurant chains. Gas grills retain the largest margin pool in commercial catering services where BTU output and recovery speed determine equipment selection.
The U.S. FDA Food Code governs automated cooking equipment validation requirements, while NSF International standards certify sanitation design for commercial grilling surfaces; both frameworks elevate replacement demand as operators face inspection compliance deadlines. The EPA ENERGY STAR program for commercial kitchen equipment shapes electric grill efficiency benchmarks, restricting market access for non-certified imports. Stakeholders must monitor evolving municipal fire ordinances and energy efficiency thresholds as these dual regulatory tracks increasingly dictate equipment specification sheets and capital expenditure approval processes.
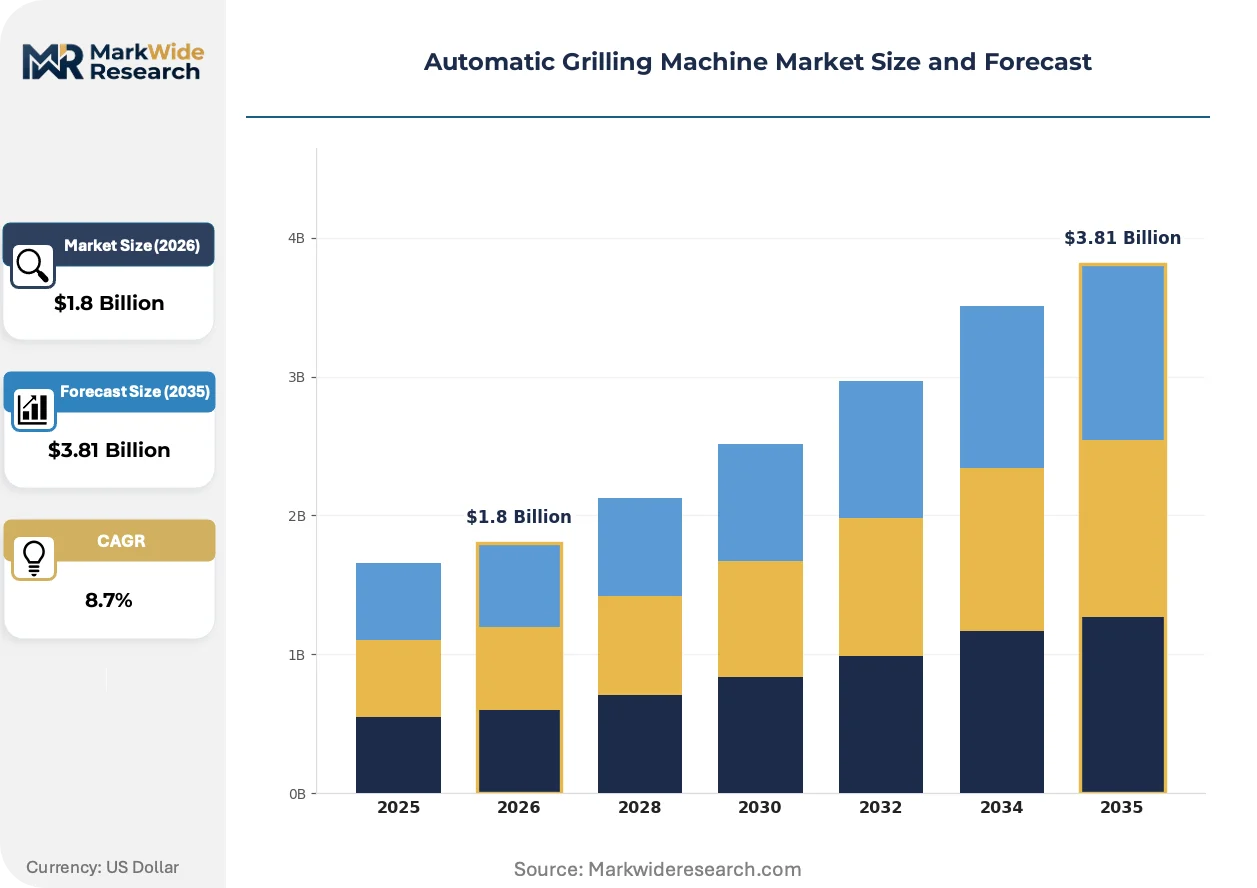
Market Dynamics
Commercial kitchen automation is accelerating equipment replacement cycles as operators face simultaneous pressure from labor shortages and inspection compliance deadlines under the U.S. FDA Food Code. The structural force compressing decision timelines is the intersection of regulatory certification requirements with throughput standardization mandates in quick-service restaurant chains.
Growth Catalysts
- NSF International Sanitation Standards:Certification requirements for commercial grilling surfaces are forcing non-compliant legacy equipment out of service, creating replacement pull across foodservice operations.
- Pellet-Feed Automation:Precision fuel delivery systems are reducing operator intervention while improving temperature consistency in high-volume protein processing environments.
- Texas Food Truck Density:Mobile foodservice expansion in high-temperature climates is driving demand for compact, high-BTU automated grilling units with rapid recovery cycles.
Market Restraints
- Stainless Steel Alloy Volatility:Firebox assembly costs fluctuate with nickel and chromium spot prices, squeezing margin structures for mid-tier equipment manufacturers.
- Foundry Supply Concentration:Burner component casting capacity clusters in specific industrial regions, creating single-source vulnerability for non-vertically integrated assemblers.
- Apartment Fire Code Restrictions:Gas combustion prohibitions in multi-unit residential buildings limit addressable market for non-electric home-use configurations.
Strategic Opportunities
- EPA ENERGY STAR Certification:Efficiency benchmarking programs are restricting market access for non-certified imports, creating protected terrain for compliant domestic manufacturers.
- Wi-Fi Temperature Logging:Connected monitoring integration with restaurant chain back-of-house systems is opening specification opportunities in enterprise procurement channels.
- Conveyor Mechanism Retrofit Kits:Automation add-ons for existing grill infrastructure represent untapped aftermarket revenue in cost-constrained independent restaurants.
Industry Challenges
- Automated Cooking Equipment Validation:FDA Food Code compliance documentation requires specialized regulatory affairs expertise that smaller equipment vendors struggle to staff.
- Infrared Heat Distribution Calibration:Precision engineering talent for 300°F–700°F surface temperature standardization is scarce in regional manufacturing labor pools.
- Legacy Kitchen System Integration:New automated grilling lines must interface with existing ventilation and fire suppression infrastructure, complicating installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Grilling Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grills, Induction Grills, Charcoal Grills, Gas Grills End User: Restaurants, Food Trucks, Home Users, Catering Services Technology: Smart Grilling, Infrared Technology, Temperature Control, Automatic Shutdown Size: Compact, Medium, Large, Extra Large |
| Companies Covered | Weber, Char-Broil, Traeger, George Foreman, The Middleby Corporation, Masterbuilt, Philips, Blackstone, Zojirushi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Grilling Machine Market Strategic Shifts
Smart connectivity and precision thermal management are converging to transform equipment specification criteria across both commercial and residential buyer segments. The pace of change is compressing product development cycles while elevating software competency requirements for traditional hardware manufacturers.
Infrared sensing arrays paired with machine-learning temperature modulation are electrifying heat distribution precision in commercial installations. High-volume steakhouse chains are deploying these systems to eliminate protein inconsistency during peak service windows. The technology is electrifying competitive positioning by enabling guaranteed cook-time contracts that manual grilling cannot match.
The U.S. FDA Food Code updates on automated cooking equipment certification are accelerating capital expenditure timelines among foodservice operators. Inspection compliance deadlines now fall within typical equipment depreciation schedules, forcing earlier replacement decisions. Full-service restaurants in Florida and California are responding by pre-emptively upgrading to NSF-certified units before mandated phase-out dates.
Enterprise procurement teams are consolidating vendor relationships around equipment-as-a-service models that unbundle upfront capital from maintenance obligations. Restaurant chains are displacing traditional distributor channels with direct manufacturer partnerships spanning installation, training, and predictive maintenance. This pattern is most visible in Texas, where quick-service expansion is concentrating buying power among regional franchise operators.
Automatic Grilling Machine Market Segmentation
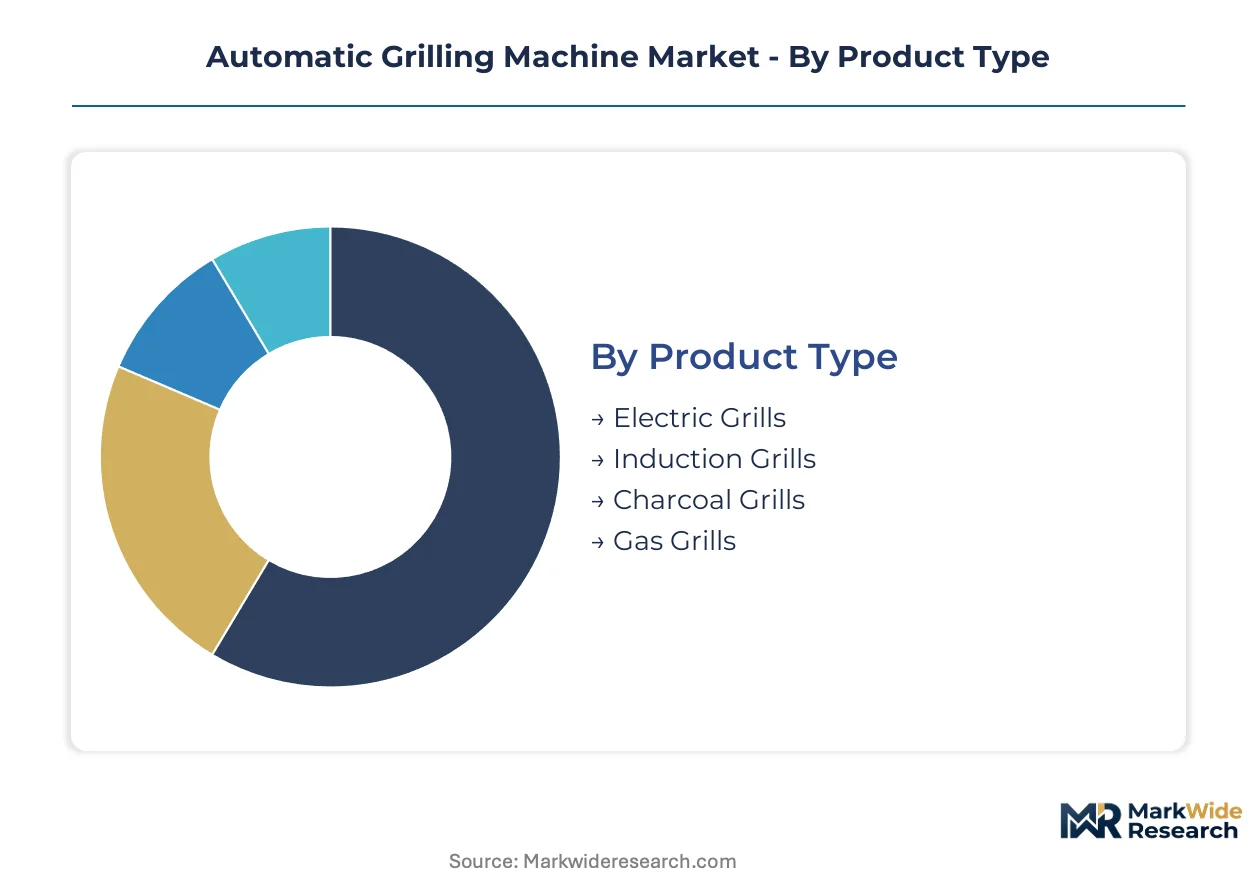
Segmentation in the automatic grilling machine market reveals divergent engineering priorities between residential convenience and commercial throughput. Equipment specifications, certification requirements, and connectivity features vary sharply across buyer categories, forcing manufacturers to maintain parallel product architectures.
Product Type:
The customization-standardization spectrum spans from plug-and-play electric units to precision-engineered gas systems requiring professional installation and ventilation integration.
- Electric Grills:Resistance-element heating systems deliver 300°F–500°F surface temperatures through ceramic or cast-iron grates. Apartment complexes in California and New York drive penetration where municipal fire codes prohibit gas combustion. The segment dominates home-user revenue due to lease-friendly portability and zero ventilation requirements.
- Gas Grills:Propane or natural gas burners achieve 700°F+ recovery speeds through 40,000–100,000 BTU outputs. Steakhouse chains in Texas concentrate procurement here for searing performance that electric elements cannot replicate. The segment commands the widest commercial margin pool despite higher installation complexity.
- Induction Grills:Electromagnetic coil systems generate rapid, precise heat without open flame. Commercial kitchens seeking energy efficiency benchmarks favor these for EPA ENERGY STAR compliance.
- Charcoal Grills:Automated auger-fed briquette systems replicate traditional flavor profiles with reduced operator attention. Specialty barbecue restaurants in the American South maintain niche demand.
Most installed capacity flows through Gas Grills. Expansion is steepest in Electric Grills.
End User:
Volume concentration tilts toward high-frequency commercial operators, though home-user unit economics improve with smart-feature bundling.
- Restaurants:Full-service and quick-service chains deploy conveyor and programmable-cycle units for protein throughput standardization. The U.S. FDA Food Code validation requirements force NSF-certified equipment replacement across Florida and California inspection jurisdictions.
- Food Trucks:Compact, high-BTU automated units with rapid recovery cycles dominate mobile foodservice in Texas heat conditions. Space constraints and generator compatibility shape specification sheets.
- Home Users:Electric and pellet configurations lead penetration where apartment fire codes restrict gas. Wi-Fi temperature logging is becoming standard expectation.
- Catering Services:Portable medium-format units with quick-setup requirements serve off-premise event volume. Rental and lease models reduce capital friction.
Revenue concentrates in Restaurants. Food Trucks are climbing the fastest.
Technology:
Margin structures diverge between commodity thermal management and proprietary algorithmic control systems.
- Smart Grilling:Wi-Fi-enabled temperature logging and mobile-app integration enable remote monitoring and recipe automation. Enterprise restaurant chains in Texas specify these for back-of-house system integration.
- Infrared Technology:Ceramic or quartz radiant elements deliver intense, direct heat for searing without convective drying. High-volume steakhouse deployment eliminates protein inconsistency during peak windows.
- Temperature Control:PID or thermocouple-feedback systems maintain surface consistency within ±5°F. Baseline expectation in commercial certification standards.
- Automatic Shutdown:Timer-based or sensor-triggered safety systems reduce fire risk and energy waste. Regulatory preference under municipal fire ordinances.
Deployment volume runs through Temperature Control. Smart Grilling shows the steepest expansion trajectory.
Size:
Footprint requirements map directly to throughput specifications and installation site constraints.
- Compact:Under 24-inch widths serve food trucks and apartment balconies. Texas mobile operators prioritize these for generator load compatibility.
- Medium:24–36 inch formats balance residential entertainment use and small commercial kitchens. Largest addressable unit volume.
- Large:36–48 inch widths target independent restaurants and catering operations. Ventilation hood integration dominates specification.
- Extra Large:48-inch+ conveyor systems serve high-throughput quick-service chains. Custom installation and fire suppression integration required.
Shipment volume concentrates in Medium. Extra Large is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas anchors the automatic grilling machine demand landscape through concentrated food truck density and quick-service restaurant expansion corridors. Commercial kitchen automation investments cluster in Dallas-Fort Worth and Houston metro areas where labor shortages intersect with high-volume protein processing requirements. The regional concentration reflects broader North American patterns where equipment replacement cycles accelerate under regulatory compliance pressures.
United States
Quick-service restaurant chains in Texas, California, and Florida drive commercial procurement volume for conveyor and programmable-cycle grilling systems. The U.S. FDA Food Code validation requirements for automated cooking equipment force NSF-certified replacements across inspection jurisdictions. Dallas-Fort Worth metro foodservice operators are pre-emptively upgrading equipment before mandated phase-out dates compress capital expenditure timelines.
Germany
Commercial catering services and industrial food processing facilities sustain demand for precision-engineered gas and induction grilling systems. The country's national food safety regulator enforces strict equipment certification protocols that elevate specification standards for imported machinery. Bavaria's manufacturing belt hosts specialized component fabricators supplying burner assemblies to European equipment assemblers.
China
Export-oriented manufacturing clusters in Guangdong and Zhejiang provinces dominate mid-tier equipment production for international foodservice markets. The State Administration for Market Regulation implements product quality standards that shape factory certification requirements for automated kitchen equipment. Shenzhen-based electronics integrators supply Wi-Fi temperature logging modules to global grilling equipment brands.
Japan
Compact electric grilling systems penetrate dense urban residential markets where apartment fire codes restrict gas combustion. The Ministry of Economy, Trade and Industry promotes energy efficiency benchmarks through commercial kitchen equipment labeling programs. Osaka-Kobe industrial corridor manufacturers specialize in infrared heat distribution components for premium residential and small commercial segments.
United Kingdom
Pub chain modernization and ghost kitchen expansion sustain commercial equipment demand across Greater London and Midlands conurbations. The Food Standards Agency coordinates with local authorities on automated cooking equipment inspection protocols that accelerate legacy system replacement. Manchester-Leeds corridor foodservice distributors are consolidating procurement relationships around equipment-as-a-service financing models.
Automatic Grilling Machine Market Competitive Environment
Global majors compete with regional champions across technology integration and distribution channel control. The vendor base clusters around three strategic tiers: vertically integrated foundry operators controlling burner component supply, pellet-feed automation specialists concentrating R&D investment, and broad foodservice equipment conglomerates dominating commercial installation channels. Competitive moves center on backward integration into alloy supply and predictive maintenance service bundling.
Within the premium residential tier, Weber and Traeger occupy positions anchored by foundry partnerships and Utah-based automation R&D respectively. The Middleby Corporation sits within the commercial equipment conglomerate archetype, leveraging broad foodservice portfolios to capture enterprise procurement consolidation. These three exemplify divergent strategic postures: captive supply control, precision fuel delivery innovation, and channel breadth dominance.
| Leading Market Players |
|---|
| Weber |
| Char-Broil |
| Traeger |
| George Foreman |
| The Middleby Corporation |
| Masterbuilt |
| Philips |
| Blackstone |
| Zojirushi |
| Others |
Value Chain & Pricing Dynamics
NSF certification tiering splits the market into premium validated equipment and economy-grade alternatives, with this bifurcation locking in divergent margin structures and sourcing strategies across manufacturer tiers. Premium NSF-certified units command sustained pricing power through FDA Food Code compliance mandates, while economy producers absorb nickel and chromium volatility in thinner firebox assemblies.
Pricing Analysis
Input-cost pass-through from stainless steel alloy markets governs manufacturer margin compression, with nickel spot volatility squeezing mid-tier assemblers who lack foundry partnerships. Three-tier pricing structure across premium NSF-validated, standard commercial-grade, and economy residential levels separates buyers by inspection jurisdiction and throughput requirements. Pricing pressure stems from EPA ENERGY STAR efficiency benchmarks that disqualify non-certified imports. Quick-service restaurant chains show least price sensitivity due to compliance-driven replacement cycles, while independent food trucks face acute budget constraints.
Supply Chain Analysis
Workforce availability in Guangdong casting clusters, Utah automation engineering pools, and Bavaria precision component hubs shapes production capacity allocation across equipment tiers. Burner assembly supply draws from Chinese foundry concentration and German specialty fabricators, with firebox manufacturing resting on nickel-chromium alloy sourcing. Single-source vulnerability clusters in pellet-feed automation componentry from Utah R&D facilities. Distribution runs through commercial foodservice equipment distributors in Texas, California, and Florida, with direct manufacturer partnerships displacing traditional channels in enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic grilling machine market functions as a regulatory compounder where FDA Food Code validation deadlines accelerate equipment replacement irrespective of economic cycle position. This structural demand floor creates defensive revenue visibility for positioned suppliers.
For Market Incumbents: Anticipate margin compression from pellet-feed automation specialists by deepening captive supply control over burner component foundries and accelerating Wi-Fi temperature logging integration to lock in enterprise restaurant chain specifications. The Middleby Corporation's channel breadth model demonstrates how broad foodservice portfolios capture procurement consolidation.
For New Entrants and Emerging Players: Capture the conveyor mechanism retrofit kit aftermarket in cost-constrained independent restaurants across Texas and Florida where legacy equipment outnumbers NSF-compliant replacements. Food truck density in high-temperature climates offers penetrable volume for compact high-BTU configurations with generator compatibility as the decisive specification wedge.
For Investors and Strategic Acquirers: Consolidation pressure builds where foundry supply concentration meets regulatory compliance expertise scarcity, favoring acquisition of vertically integrated mid-tier manufacturers with FDA validation documentation capabilities and established NSF certification pathways. Equipment-as-a-service financing model adoption in Manchester-Leeds corridor distribution channels signals inflection toward recurring revenue architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Supply | Captive burner component production insulates margin structures from nickel volatility and single-source risk. |
| Wi-Fi Temperature Logging Platform Launch | Enterprise restaurant chain specifications increasingly require back-of-house system integration for remote monitoring. |
| NSF Certification Fast-Track Investment | FDA Food Code inspection deadlines compress decision timelines for validated equipment replacement. |
| Conveyor Retrofit Kit Development | Aftermarket automation add-ons unlock revenue from installed base of legacy grilling infrastructure. |
| Equipment-as-a-Service Financing Model | Restaurant chain procurement teams unbundle capital expenditure from predictive maintenance obligations. |
Study Parameters
Coverage spans United States, Germany, China, Japan, and United Kingdom markets, with primary inputs from each territory combined with secondary validation. Foodservice equipment procurement directors, restaurant chain operations executives, commercial kitchen contractors, and regulatory affairs specialists at NSF International provided structured interviews. Secondary sources include FDA Food Code documentation, EPA ENERGY STAR certification databases, SEC filings from publicly traded foodservice equipment manufacturers, and municipal fire ordinance records from Texas, California, and Florida jurisdictions. Bottom-up equipment shipment data triangulates against top-down foodservice operator capital expenditure surveys.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology tier, and equipment size format, with additional granularity on regional regulatory cluster intensity. CAGRs derive from equipment replacement cycle analysis intersecting with inspection compliance deadline schedules. Forecast inputs incorporate pellet-feed automation adoption curves and Wi-Fi connectivity penetration rates in commercial installations.
Underlying measurement precision varies by segment; commercial restaurant and food truck categories carry tighter precision than residential home user estimates due to more visible procurement channels. Forecasts reflect assumptions about FDA Food Code enforcement consistency and stainless steel alloy price stability. Material deviation in EPA ENERGY STAR benchmark revisions or municipal fire ordinance adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Automatic Liquid Dispenser Machine Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Plastic Processing Machinery Market