
 Low Methoxyl Pectin Market | 2026-2036
Low Methoxyl Pectin Market Size, Share, and Industry Trends Forecast 2026-2036
Low Methoxyl Pectin Market Analysis
Capital-intensity divergence between extraction-scale specialists and formulation-centric distributors is bifurcating competitive returns in low methoxyl pectin. Herbstreith & Fox leverages its German citrus peel supply network to sustain cost leadership across European dairy applications. CP Kelco anchors North American demand through integrated seaweed-to-pectin processing in Denmark and the United States. Silvateam specializes in apple-derived variants for Italian and French confectionery clients seeking regional provenance claims.
Low methoxyl pectin is a partially amidated or de-esterified polysaccharide with a degree of methylation below 50 percent, requiring calcium ions to form thermally irreversible gels used in low-sugar preserves and controlled-release pharmaceuticals. Food grade formulations dominate volume given clean-label penetration in dairy alternatives and reduced-sugar jams, while pharmaceutical grade commands margin concentration in oral disintegrating tablet matrices. Citrus-derived material leads supply for its high galacturonic acid content, though apple and seaweed sources gain traction where allergen labeling and sustainability credentials influence procurement.
FDA food additive regulations under 21 CFR 184.1588 govern GRAS status for domestic use, while EFSA purity standards and REACH chemical registration obligations shape European import and formulation compliance. China's SAMR and NMPA enforce dual-track oversight for food-grade versus pharmaceutical-grade pectin entering through coastal processing zones. Stakeholders must monitor evolving calcium-reactivity specifications across pharmacopeias and assess backward integration into regional peel or algae supply before capacity commitments harden.
Market Dynamics
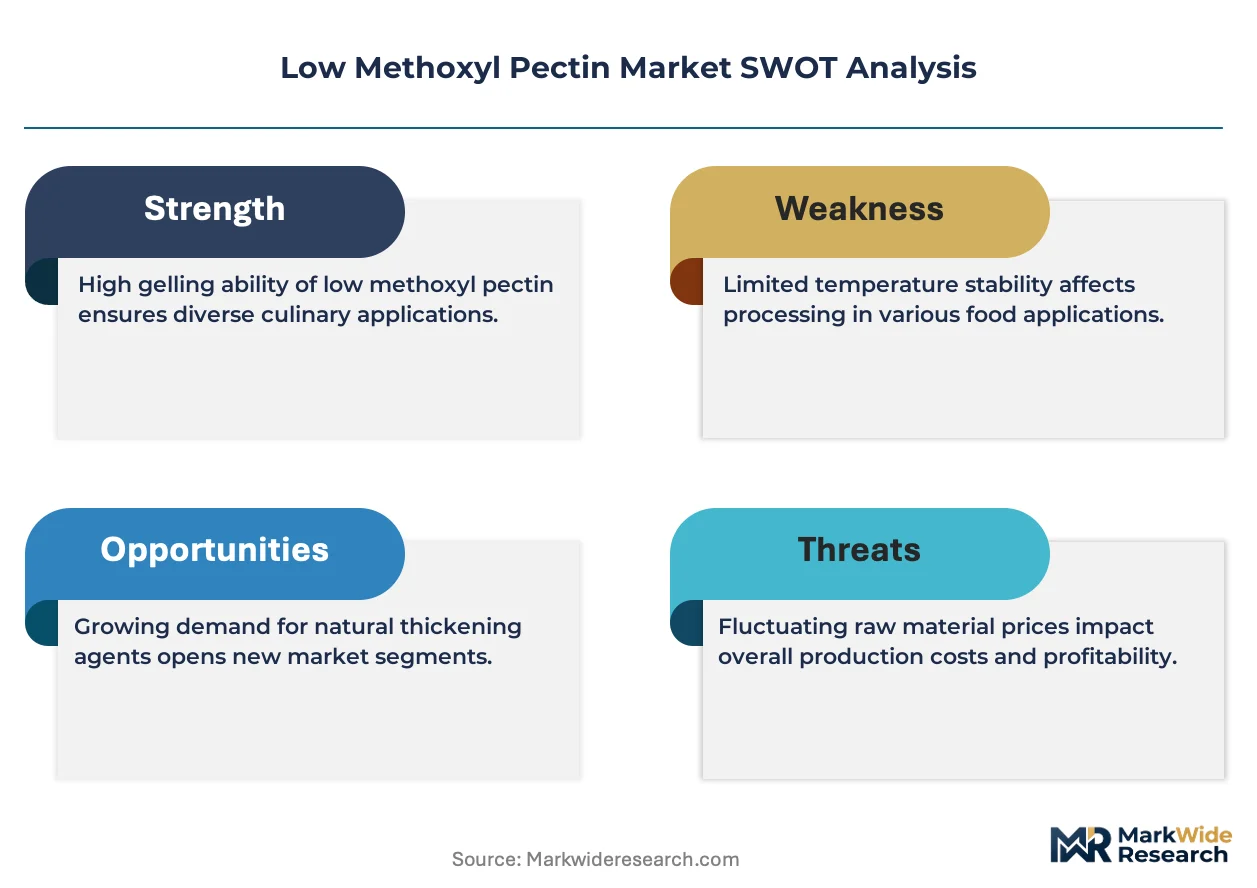
Clean-label reformulation pressure is compressing ingredient substitution timelines across dairy and confectionery sectors, forcing pectin suppliers to validate calcium-reactivity profiles under accelerated commercialization schedules.
Growth Catalysts
- EU Food Additives Regulation updates:Reshaped purity benchmarks compel cross-border suppliers to upgrade filtration infrastructure, locking compliant producers into premium supply tiers.
- Reduced-sugar preserves segment:Thermally irreversible gel requirements in low-sugar jams pull calcium-reactive pectin volumes above conventional high-methoxyl alternatives.
- Germany's ingredient processing corridor:Concentrated citrus peel sourcing and toll-manufacturing infrastructure reduce logistics drag for continental dairy formulators.
Market Restraints
- Citrus peel supply concentration:Mediterranean and Florida growing regions expose processors to climate-induced harvest volatility and pesticide residue variability.
- Seaweed-derived pectin technical ceiling:Lower galacturonic acid content restricts gel strength parity with citrus sources in pharmaceutical tablet matrices.
- REACH registration burdens:ECHA chemical dossier requirements extend European import clearance timelines for non-EU extraction facilities.
Strategic Opportunities
- Controlled-release pharmaceuticals:Oral disintegrating tablet applications command margin premiums above food-grade formulations as bioavailability specifications tighten.
- Apple-derived regional provenance claims:Italian and French confectionery buyers source domestically extracted variants to satisfy clean-label marketing requirements.
- Direct-to-manufacturer digital procurement:Formulation houses bypass distributor markups through integrated specification portals linking peel processors to R&D labs.
Industry Challenges
- Pharmacopeial calcium-reactivity harmonization:Divergent USP, EP, and JP gel-strength testing protocols force dual-validation runs for multinational pharmaceutical clients.
- Peel-to-pectin backward integration capex:Citrus processors face stranded asset risk if regional growing patterns shift outside historical catchment radii.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Methoxyl Pectin Market |
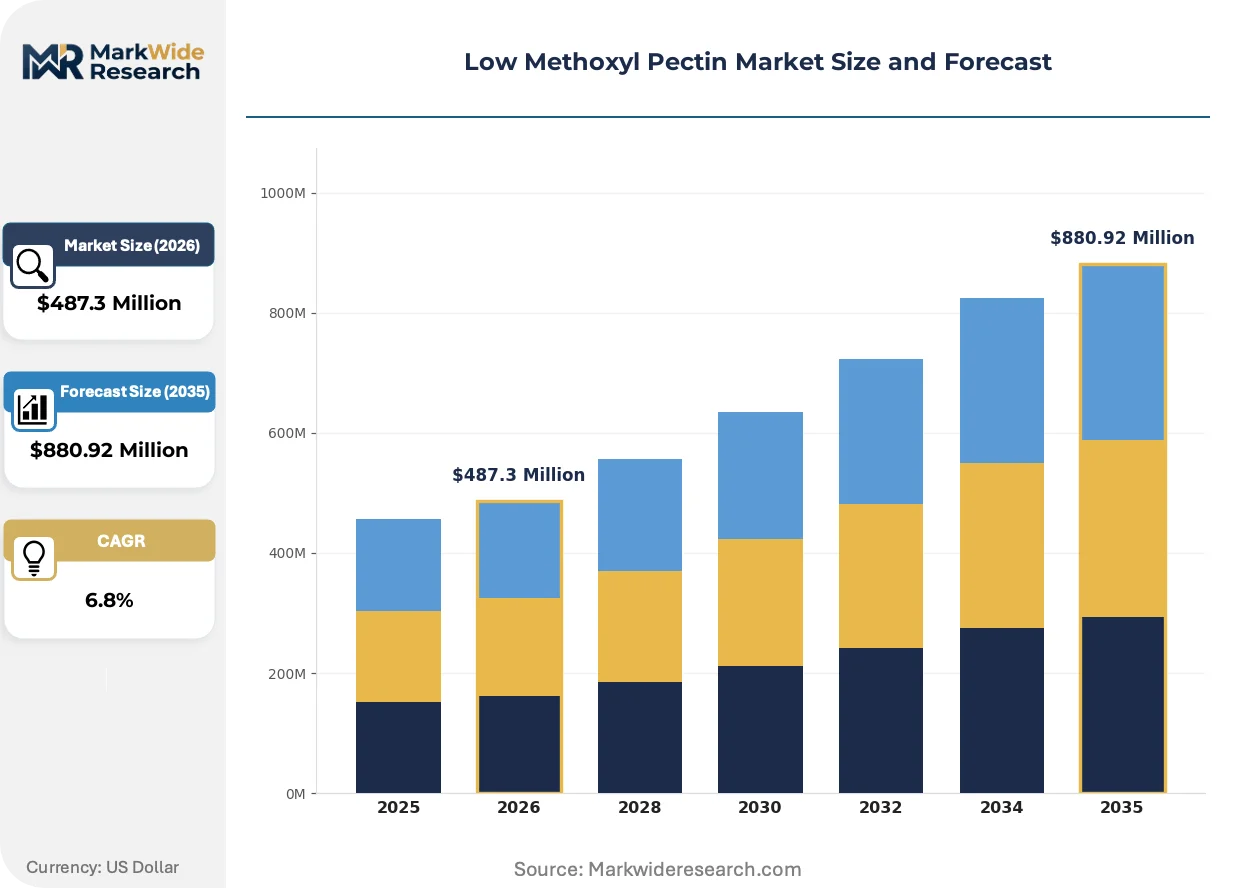
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food & Beverages, Pharmaceuticals, Personal Care, Nutraceuticals Source: Citrus, Apple, Seaweed, Others Form: Powder, Granules, Liquid, Paste |
| Companies Covered | Herbstreith & Fox, FMC Corporation, CP Kelco, Silvateam, Yantai Andre Pectin, Cargill, Naturex, Ceamsa, DuPont Nutrition & Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Methoxyl Pectin Market Emerging Trajectories
Calcium-reactive gel engineering is displacing conventional hydrocolloid stabilization across reduced-sugar and dairy-alternative categories, compressing formulation development cycles and rewiring supplier-manufacturer technical collaboration models.
Enzymatic de-esterification control systems are fragmenting batch-to-batch consistency benchmarks in low methoxyl pectin production. Precision fermentation-derived enzymes enable degree-of-methylation targeting within narrower bands than conventional alkaline hydrolysis. Pharmaceutical tablet manufacturers and premium preserve brands adopt these tighter-specification materials, compressing price premiums for standard-grade alternatives and forcing mid-tier suppliers into specification races they cannot fund.
EFSA purity standard revisions under the EU Food Additives Regulation are tightening heavy metal and solvent residue thresholds for pectin imports. Extraction facilities in non-EU citrus-growing regions face capital-intensive filtration upgrades or exclusion from continental pharmaceutical and infant-nutrition supply chains. German and Dutch toll processors capture volume shifts by offering compliance-guaranteed intermediate processing for raw extract importers.
Buyer consolidation among multinational dairy-alternative brands is compressing supplier negotiation cycles and unbundling technical service from base ingredient pricing. Procurement teams at leading oat and almond milk manufacturers now separate gel-performance validation from volume contracting, sourcing specification development from independent food technology consultants rather than incumbent pectin distributors. This unbundling is most visible in California's functional food cluster, where direct processor-to-formulator relationships displace traditional ingredient house intermediaries.
Low Methoxyl Pectin Market Segmentation
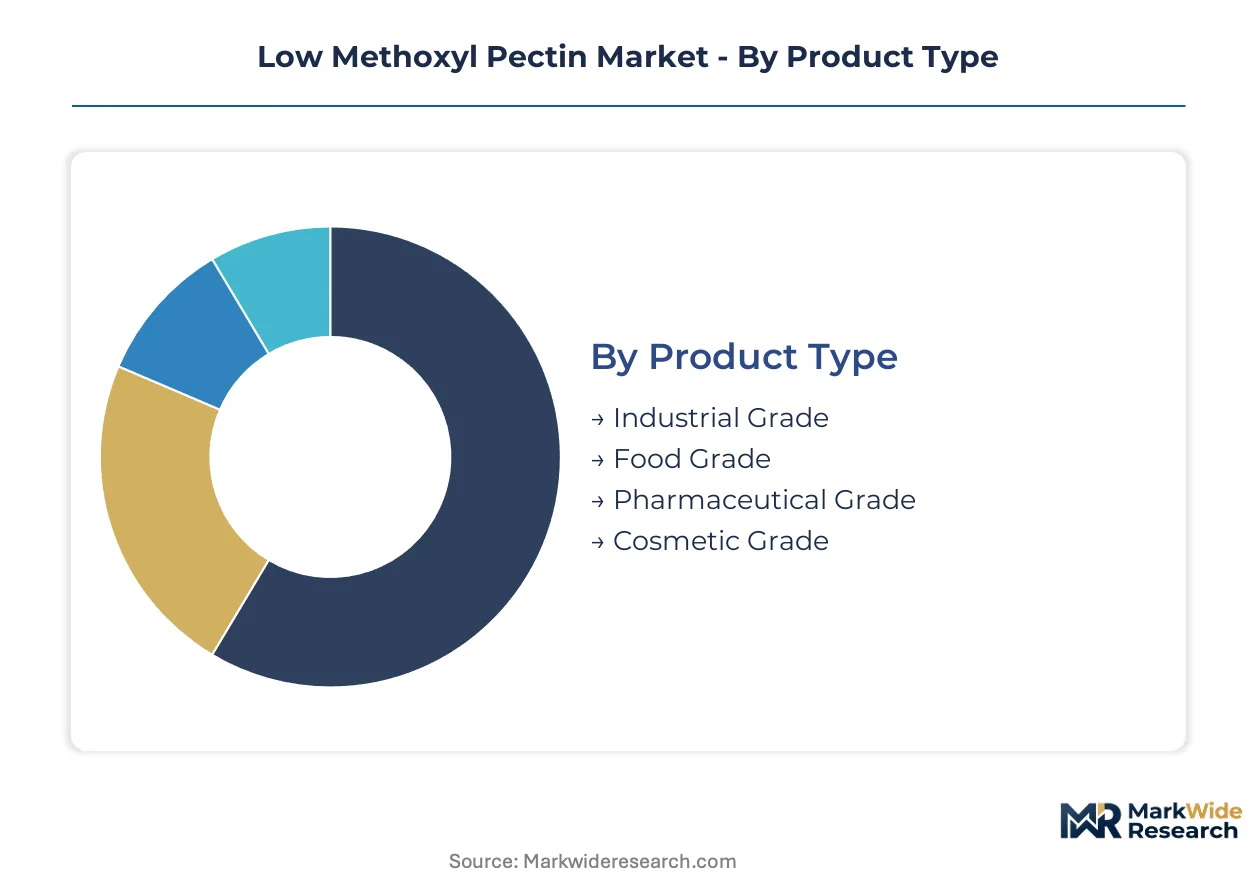
Substitution pressure from amidated and propylene glycol ester alternatives fragments demand across grade specifications and source materials. Formulators prioritize calcium-reactivity consistency over commodity pricing, compressing mid-tier supplier margins while specialty grades capture premium positioning.
Product Type:
Food Grade faces the strongest substitute threat from carrageenan and gellan gum in dairy-alternative applications, while Pharmaceutical Grade maintains technical moats through pharmacopeial certification barriers.
- Food Grade:Clean-label compliant material with degree of methylation below 50 percent enables thermally irreversible gels in reduced-sugar preserves. California's functional food cluster and Germany's ingredient processing corridor concentrate procurement for oat milk and almond yogurt stabilization, driven by EFSA purity standard enforcement.
- Pharmaceutical Grade:Ultra-low ash content and heavy metal thresholds meeting USP, EP, and JP specifications support oral disintegrating tablet matrices. Demand concentrates with multinational pharmaceutical manufacturers seeking bioavailability-controlled release profiles, constrained by pharmacopeial calcium-reactivity harmonization costs.
- Industrial Grade:Technical applications in adhesives and textiles with relaxed purity specifications.
- Cosmetic Grade:Film-forming and thickening agent for skincare emulsions with moderate regulatory burden.
Food Grade anchors the volume base while Pharmaceutical Grade gains share at the steepest rate.
Application:
Cost tier stratification separates formulation service bundles from commodity ingredient supply, with technical collaboration premiums concentrated in regulated end-uses.
- Food & Beverages:Dairy alternatives and reduced-sugar jams dominate volume, with clean-label reformulation compressing substitution timelines. Germany and California processing clusters validate calcium-reactivity profiles under accelerated commercialization schedules.
- Pharmaceuticals:Controlled-release tablet matrices command margin premiums above food-grade formulations. Oral disintegrating tablet demand tightens bioavailability specifications, with FDA 21 CFR 184.1588 and EFSA standards shaping procurement compliance.
- Personal Care:Stabilizer and emulsifier functions in premium skincare with regional provenance marketing.
- Nutraceuticals:Encapsulation and controlled-release delivery for functional ingredients.
Food & Beverages captures the dominant volume position while Pharmaceuticals expands most quickly on value terms.
Source:
Supply concentration in Mediterranean and Florida citrus-growing regions exposes processors to climate-induced harvest volatility and pesticide residue variability.
- Citrus:High galacturonic acid content from lemon, lime, and orange peel delivers superior gel strength for pharmaceutical and premium food applications. Mediterranean and Florida growing regions supply the bulk of raw material, constrained by climate volatility and REACH registration burdens for non-EU extraction facilities.
- Apple:Regional provenance claims satisfy Italian and French confectionery clean-label marketing requirements. Domestic extraction in Southern Europe supports sustainability credentials and allergen labeling preferences.
- Seaweed:Lower galacturonic acid content restricts gel strength parity with citrus sources, limiting penetration in pharmaceutical tablet matrices.
- Others:Sugar beet and sunflower pectin variants for niche regional supply security.
Citrus dominates supply volume while Apple climbs the fastest on premium positioning.
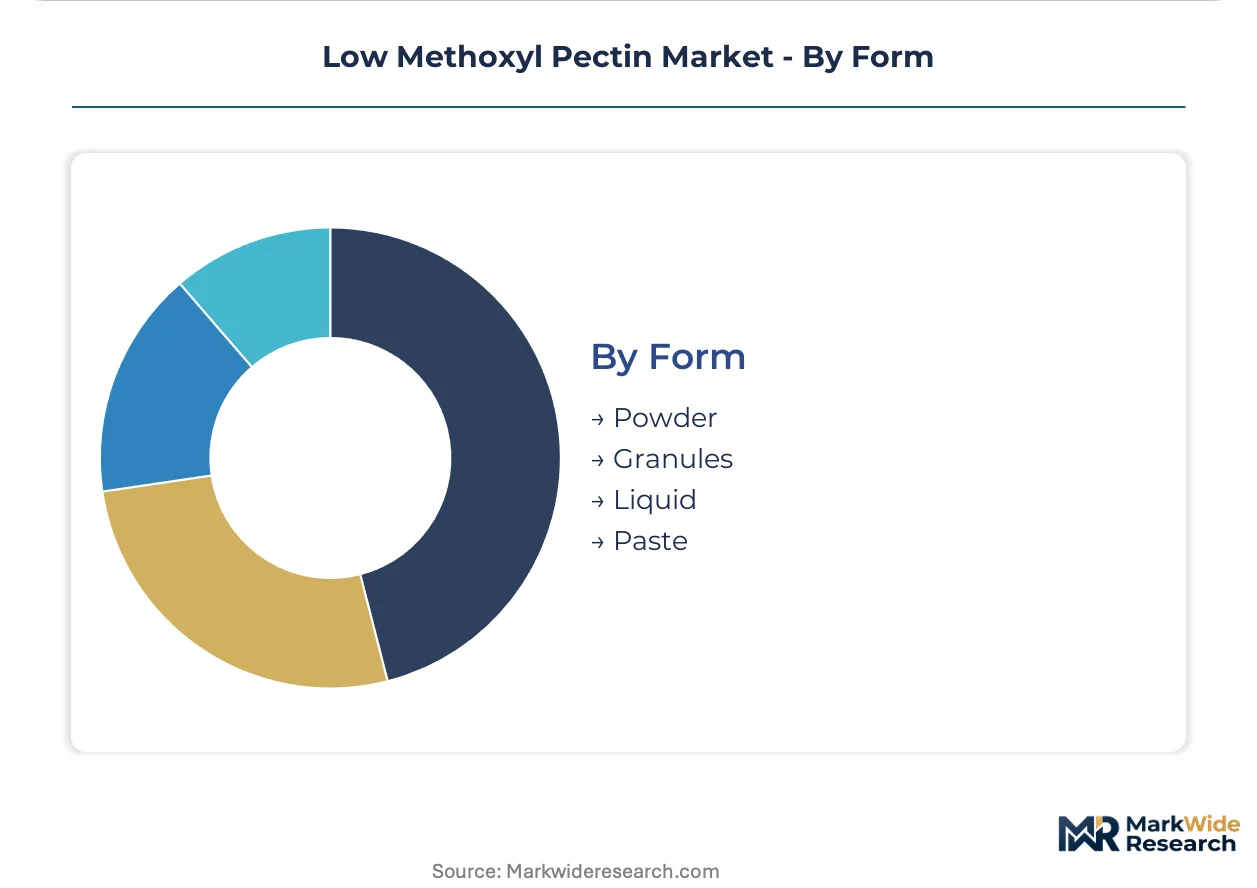
Form:
Customer type differentiation separates R&D-scale sampling from bulk manufacturing procurement, with powder specifications commanding standardization premiums.
- Powder:Standardized particle size distribution enables precise hydration control in automated manufacturing lines. Powder form dominates bulk procurement from multinational dairy-alternative brands and pharmaceutical tablet manufacturers.
- Liquid:Pre-hydrated solutions reduce processing time for small-batch confectionery and beverage applications.
- Granules:Reduced dusting and improved flow characteristics for high-shear mixing environments.
- Paste:Ready-to-use gel precursors for artisanal preserve producers and pilot-scale formulation labs.
Powder anchors manufacturing scale while Liquid gains traction in rapid-formulation service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for low methoxyl pectin diverges sharply across geographies. Pharmaceutical buyers in Germany and the United States absorb premium grades with minimal volume sensitivity, while Asian food processors negotiate aggressively on citrus-derived feedstock costs.
United States
California's functional food cluster drives demand for clean-label dairy alternatives, with oat and almond milk manufacturers validating calcium-reactivity profiles under compressed timelines. FDA 21 CFR 184.1588 governs GRAS status for domestic formulation. The state's ingredient processing corridor concentrates toll-manufacturing infrastructure for cross-border citrus peel supply.
Germany
Reduced-sugar preserves and infant nutrition applications pull pharmaceutical-grade volumes into the ingredient processing corridor concentrated in Lower Saxony and Bavaria. EFSA purity standards under the EU Food Additives Regulation enforce heavy metal thresholds that lock compliant producers into premium supply tiers. Toll processors in Hamburg and Frankfurt offer compliance-guaranteed intermediate filtration for raw extract importers.
China
SAMR and NMPA enforce dual-track oversight for food-grade versus pharmaceutical-grade pectin entering through coastal processing zones in Jiangsu and Zhejiang provinces. Domestic confectionery and dairy-alternative manufacturers source lower-cost apple-derived variants for regional provenance marketing. Yangtze River Delta extraction facilities face capital-intensive upgrades to meet REACH-equivalent export standards for European pharmaceutical clients.
Italy
French and domestic confectionery buyers source apple-derived pectin from Southern European extraction facilities to satisfy clean-label provenance requirements. ANSM and EFSA-aligned national standards shape procurement compliance for pharmaceutical tablet matrices. The Emilia-Romagna and Piedmont regions concentrate domestic apple peel processing for regional sustainability credentialing.
Brazil
ANVISA pharmaceutical regulations and MERCOSUR food additive standards create dual compliance pathways for citrus peel processors in São Paulo and Minas Gerais states. Climate-induced harvest volatility in Mediterranean supply regions has redirected some European buyer attention toward Brazilian orange peel derivatives. Domestic dairy-alternative formulation remains price-sensitive, compressing margins for standard-grade imports.
Low Methoxyl Pectin Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes in low methoxyl pectin supply. The market structures around a consolidated top tier of extraction-scale specialists and a fragmented mid-tier of formulation-centric distributors. Three archetypes dominate: integrated peel-to-pectin processors with captive citrus supply, toll-manufacturing intermediaries offering compliance-guaranteed filtration, and regional provenance specialists sourcing apple or seaweed feedstocks. Competitive moves concentrate on backward integration into regional peel supply and enzymatic de-esterification licensing to tighten degree-of-methylation specifications.
Within the integrated processing tier, Herbstreith & Fox and CP Kelco occupy positions anchored by geographic supply network control. Herbstreith & Fox represents the German citrus peel supply archetype, while CP Kelco exemplifies transatlantic scale with Denmark and United States processing footprints. Silvateam sits within the regional provenance specialist tier, its Italian base supporting apple-derived variant positioning for Southern European confectionery clients.
| Leading Market Players |
|---|
| Herbstreith & Fox |
| FMC Corporation |
| CP Kelco |
| Silvateam |
| Yantai Andre Pectin |
| Cargill |
| Naturex |
| Ceamsa |
| DuPont Nutrition & Biosciences |
| Others |
Supply Flow & Price Mechanics
Extraction-scale capacity utilization in citrus peel processing centers on Germany and Florida directly shapes price floors across pharmaceutical and food-grade tiers, compressing margins for toll-manufacturing intermediaries while amplifying premium capture for integrated processors with captive supply networks.
Pricing Analysis
After-sales technical service contracts for calcium-reactivity validation now drive lifetime value more than base ingredient markups. Three-tier pricing structure across pharmaceutical-grade, premium food-grade, and standard food-grade levels separates USP-certified material from EFSA-compliant and industrial specifications. Pricing pressure stems from buyer unbundling of formulation consulting from volume contracting. Pharmaceutical manufacturers show minimal price sensitivity while Asian confectionery processors negotiate aggressively on citrus-derived feedstock costs.
Supply Chain Analysis
Strategic stockpiling of Mediterranean citrus peel dominates inventory strategy over just-in-time approaches due to climate-induced harvest volatility. Supply concentrates in Spain, Italy, and Florida for citrus peel, with Denmark and China contributing seaweed-derived alternatives. Raw material dependencies center on lemon and orange peel supply, calcium carbonate reagents, and enzymatic de-esterification catalysts. Single-source vulnerability in Florida citrus growing regions exposes processors to hurricane disruption. Distribution runs through German and Dutch toll processors for European pharmaceutical compliance, with direct processor-to-manufacturer relationships displacing traditional ingredient houses in California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated multinational dairy-alternative brands that unbundle technical service from base pricing, fragmenting supplier negotiation leverage across the value chain.
For Market Incumbents: Consolidate backward integration into regional citrus peel supply networks to defend against climate volatility and pesticide residue variability threatening Mediterranean sources. Lock in EFSA compliance-guaranteed filtration capacity before regulatory thresholds tighten further. Prioritize enzymatic de-esterification licensing to tighten degree-of-methylation specifications and compress mid-tier competitors into specification races they cannot fund. For New Entrants and Emerging Players: FDA GRAS certification fast-track for apple-derived variants opens white-space in Italian and French confectionery markets seeking regional provenance claims. Target Southern European domestic extraction facilities with sustainability credentialing advantages over citrus imports. Penetrate through direct-to-manufacturer digital procurement portals that bypass established distributor markups in California's functional food cluster. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors toll-manufacturing intermediaries with compliance-guaranteed filtration infrastructure over raw extraction plays. Long-term viability rests on pharmacopeial calcium-reactivity harmonization capabilities spanning USP, EP, and JP protocols. Acquisition target archetype: German or Dutch processors with EFSA-registered facilities and established pharmaceutical client relationships. Watch for REACH-equivalent export standard adoption in Chinese coastal processing zones as inflection indicator for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Peel Supply | Captive sourcing from Spain and Florida reduces climate volatility exposure for pharmaceutical-grade production. |
| Enzymatic De-esterification Licensing | Precision fermentation-derived enzymes enable tighter degree-of-methylation targeting than alkaline hydrolysis methods. |
| EFSA Compliance-Guaranteed Filtration Investment | Hamburg and Frankfurt toll processors capture volume shifts from non-EU extractors facing heavy metal threshold upgrades. |
| Direct-to-Manufacturer Digital Procurement Portal | California oat milk formulators bypass distributor markups through integrated specification platforms linking peel processors to R&D labs. |
| Apple-Derived Regional Provenance Positioning | Emilia-Romagna extraction facilities satisfy Italian and French confectionery clean-label marketing requirements with domestic sustainability credentials. |
Methodological Framework
Desk research of EFSA additive regulation filings, FDA GRAS petitions, REACH chemical dossiers, and citrus trade flow databases preceded structured interviews with pharmaceutical formulation scientists, dairy-alternative procurement directors, toll-manufacturing plant managers, and enzymatic processing R&D leads. Primary fieldwork with German ingredient processing corridor operators and California functional food cluster formulators combined with secondary validation from customs records and pharmacopeial standard publications. Bottom-up volume estimates triangulated against top-down industry consumption benchmarks.
Variance decomposition across grade tier, source material, application end-use, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic demand drivers. Modeled inputs included calcium-reactivity specification adoption curves in oral disintegrating tablets, clean-label reformulation penetration in oat milk stabilization, and EFSA purity standard enforcement intensity.
Decision-makers should treat outputs as directional under assumptions of sustained EU Food Additives Regulation enforcement and stable citrus peel supply from Mediterranean growing regions; material deviation would warrant model refresh. Specific risk factors include pharmacopeial testing protocol divergence, climate-induced harvest collapse in Florida, and buyer consolidation accelerating price unbundling. Revision becomes warranted when REACH-equivalent export adoption in Chinese processing zones crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Russia Feed Additives Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
France Feed Additives Market
Food Additives and Ingredients
Spain Food Emulsifiers Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
North America Food Enzymes Market