
 South America Food Preservatives Market | 2026-2036
South America Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Preservatives Market Analytics
Buyer concentration among Brazil's meat processing conglomerates is rebalancing as mid-sized exporters from Argentina and Uruguay gain procurement leverage. Cargill Incorporated leverages its integrated grain-to-additive supply chain to sustain pricing power across Mercosur trade zones. Kerry Group anchors its regional position through specialized blends tailored to local microbiological conditions. BASF SE competes on synthetic preservative scale, while Corbion N.V. differentiates through fermentation-derived solutions for clean-label segments.
Food preservatives encompass chemical and natural substances added to food matrices at concentrations typically between 0.01% and 0.3% by weight to inhibit microbial spoilage, enzymatic degradation, and oxidative rancidity. These compounds function through pH reduction, membrane disruption, or free radical scavenging to extend shelf stability in packaged goods. Sorbates maintain dominant volume share across South American applications due to broad-spectrum efficacy against molds and yeasts in dairy and baked goods. Powder formulations lead the form category for logistics efficiency, though liquid preservatives are gaining traction in beverage processing lines where inline dosing reduces handling costs.
ANVISA governs preservative maximum residue limits and additive approvals across Brazil, while Argentina's national food safety authority enforces parallel standards under Mercosur harmonization protocols. Chile's Ministry of Health maintains stricter benzoate thresholds, creating a regulatory gradient that shapes cross-border product registration strategies. Stakeholders must monitor pending updates to CODEX-aligned regional standards that could unify or fragment compliance requirements across Andean and Southern Cone markets.
Market Dynamics
ANVISA's accelerated additive reauthorization timeline is compressing reformulation cycles for Brazilian meat processors, forcing simultaneous compliance investment and clean-label portfolio expansion across São Paulo's manufacturing corridor.
Growth Catalysts
- Clean-Label Mandates:Brazil's retail chains now require preservative transparency declarations, pushing processors toward fermentation-derived alternatives. Argentine exporters leverage this shift to differentiate in Mercosur trade zones.
- Microbiological Risk Management:Extended export supply chains to Asian markets demand enhanced shelf-life protocols. Sorbate blends tailored to tropical humidity conditions see expanded deployment in dairy applications.
- ANVISA Harmonization:Updated maximum residue limits aligned with CODEX standards reduce registration duplication costs. Chilean border facilities adopt parallel testing protocols, streamlining cross-border shipments.
Market Restraints
- Feedstock Volatility:Corn-derived sorbic acid precursors fluctuate with Argentine harvest yields. Preservative blenders lack long-term contracting leverage against grain traders.
- Regulatory Fragmentation:Chile's benzoate thresholds remain stricter than Mercosur baselines. Manufacturers maintain separate SKU inventories for Andean versus Southern Cone distribution.
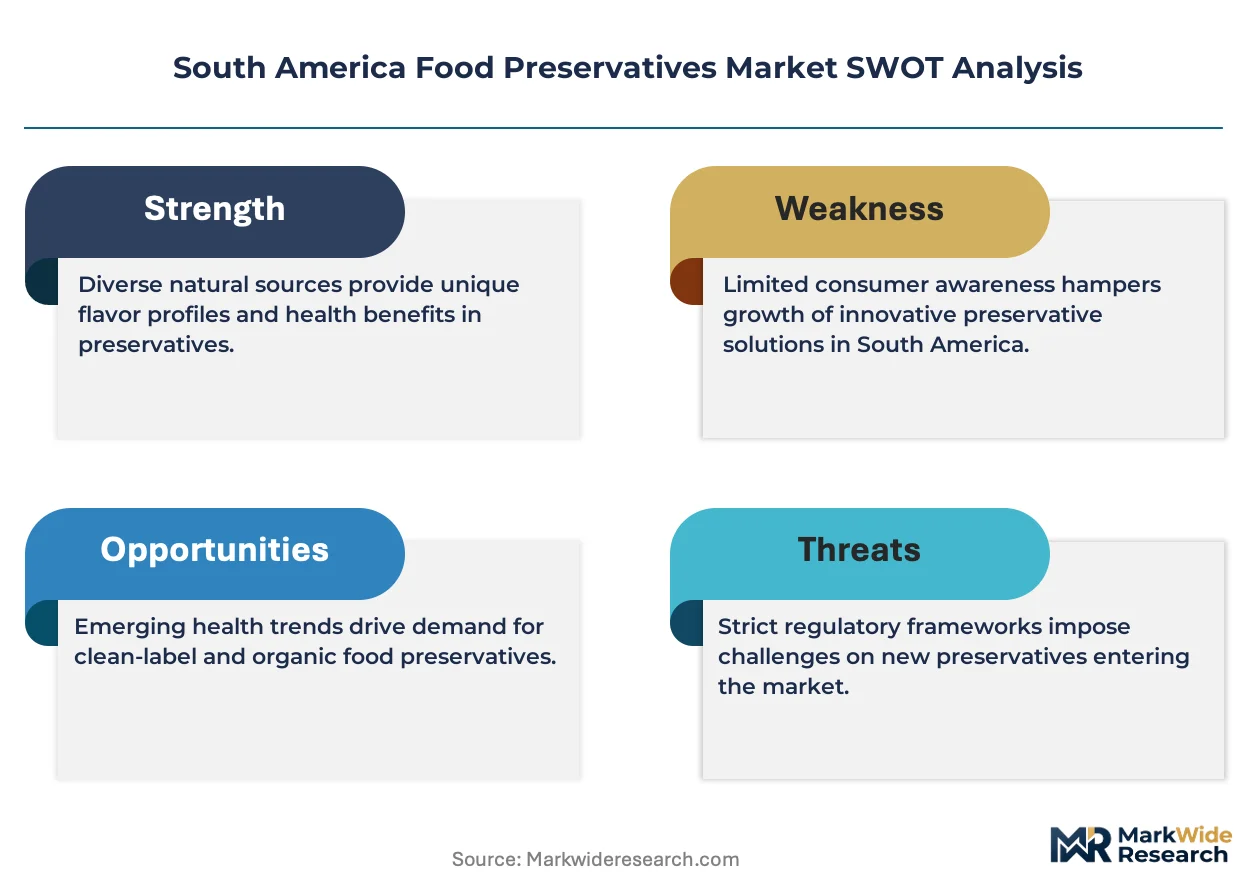
- Natural Preservative Performance Gaps:Rosemary extract and cultured dextrose show inconsistent mold inhibition in high-moisture meat matrices. Synthetic alternatives retain technical dominance in ambient-stable applications.
Strategic Opportunities
- Uruguayan Export Infrastructure:Montevideo's port modernization creates cold-chain-adjacent preservative blending capacity. Mid-sized meatpackers bypass Brazilian distribution chokepoints.
- Beverage Inline Dosing:Liquid preservative systems reduce handling labor in mineral water and juice lines. São Paulo state's bottling corridor presents concentrated deployment potential.
- PLI-Analog Incentives:Argentina's industrial promotion frameworks subsidize fermentation facility construction. Natural preservative producers capture cost advantages against imported synthetics.
Industry Challenges
- Reformulation Talent Scarcity:Food matrix compatibility expertise for clean-label transitions concentrates in São Paulo and Buenos Aires. Regional universities lack specialized preservative chemistry programs.
- Dual Registration Burden:ANVISA's additive approvals require separate toxicology dossiers from Mercosur harmonized submissions. Compliance timelines extend 14-18 months for novel natural compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Preservatives Market |
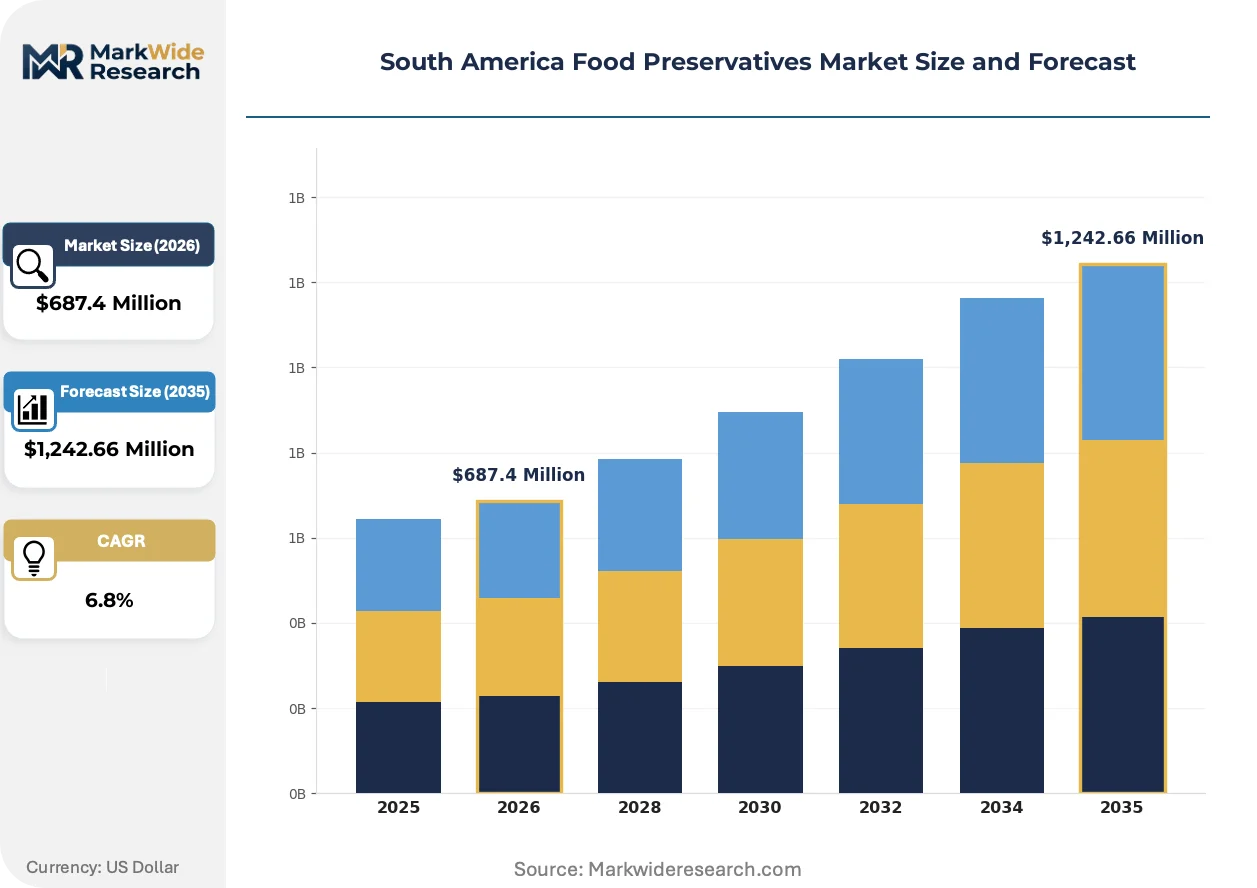
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,242.66 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sorbates, Benzoates, Sulfites, Nitrates Application: Meat Processing, Dairy Products, Baked Goods, Beverages Form: Powder, Liquid, Granules, Tablets End User: Food Manufacturers, Retailers, Restaurants, Exporters |
| Companies Covered | BASF SE, Cargill Incorporated, Kerry Group, DuPont, DSM, Archer Daniels Midland Company, Corbion N.V., Celanese Corporation, Ajinomoto Co., Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Preservatives Market Evolving Landscape
Fermentation-derived preservation systems are displacing synthetic alternatives as the dominant technical pathway, with regulatory acceleration and procurement specifications converging to reshape competitive capability requirements.
Bioprocessed antimicrobial peptides are integrating into meat and dairy matrices as drop-in replacements for benzoates. Brazilian processors in São Paulo state's corridor adopt these systems at pilot scale, with full-line conversions scheduled within 24 months. The technology is integrating pH-independent efficacy profiles that reduce formulation complexity for clean-label product development.
ANVISA's 2023 additive reauthorization framework compresses approval timelines for fermentation-derived substances while maintaining synthetic preservatory scrutiny. Industrial consequence includes accelerated R&D relocation toward Brazilian biotech clusters. Clean-label meat applications face the steepest compliance burden, with processors pre-submitting natural alternative dossiers ahead of formal mandate implementation.
Retail procurement specifications now mandate preservative class disclosure on front-of-pack labeling. São Paulo-based supermarket chains enforce this through supplier scorecards, displacing traditional back-panel-only ingredient lists. Argentine meat exporters to these channels reformulate sorbate-dependent products to qualify for preferred shelf placement, with compliance costs absorbed through volume commitment negotiations.
South America Food Preservatives Market Segmentation
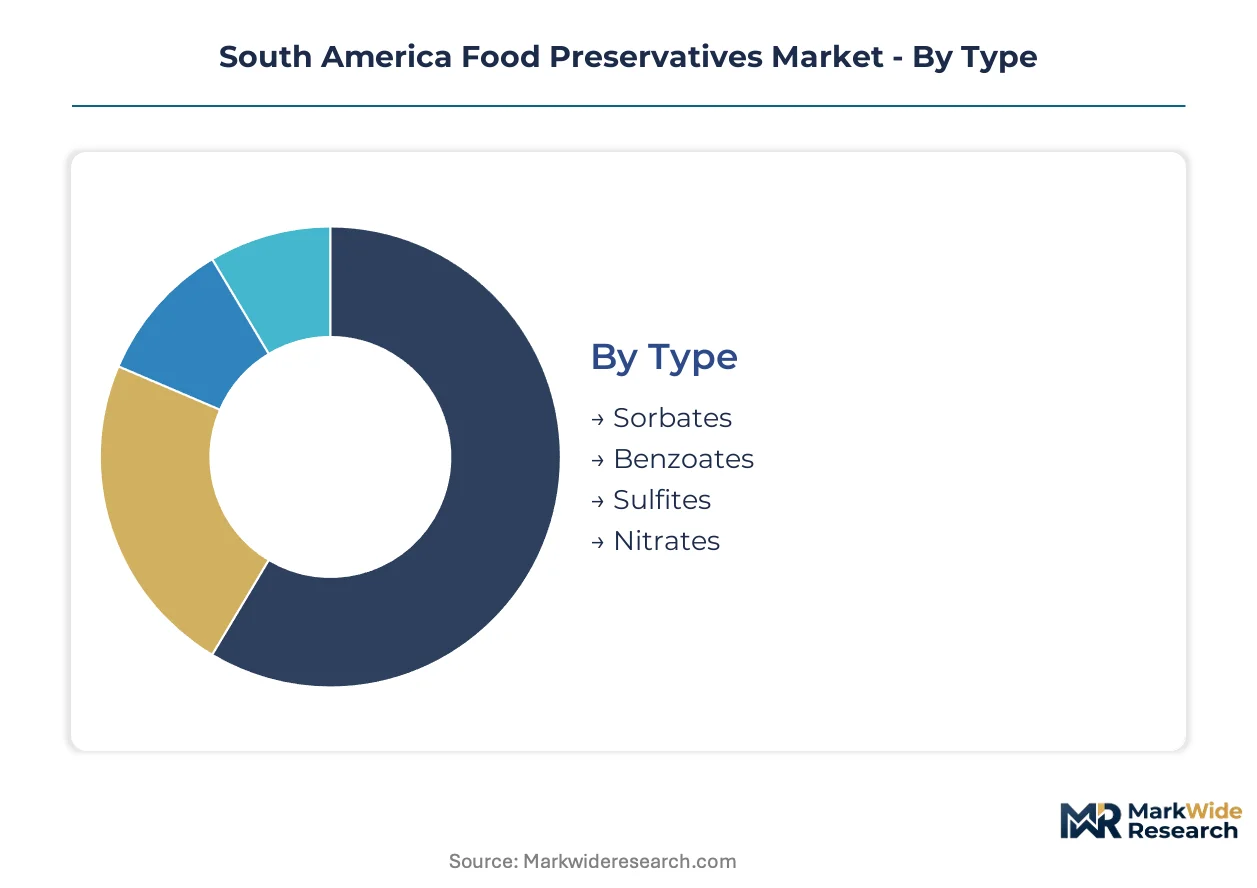
Preservative selection in South America reflects divergent technical requirements across climate zones, regulatory environments, and export destination standards. Segmentation reveals how formulation choices cascade through supply chains from São Paulo's manufacturing corridor to Mercosur border facilities.
Type:
Standardization dominates commodity sorbate and benzoate supply, while nitrates and sulfites demand customized dosing protocols calibrated to specific matrix pH and water activity.
- Sorbates:Potassium sorbate and sorbic acid derivatives inhibit mold and yeast proliferation through membrane disruption. São Paulo's dairy processors deploy these compounds in yogurt and cheese applications where tropical humidity accelerates spoilage, with ANVISA residue limits shaping maximum inclusion rates.
- Benzoates:Sodium benzoate and benzoic acid function optimally in acidic matrices below pH 4.5, making them indispensable for beverage applications. Chile's stricter maximum residue thresholds force reformulation for cross-border products, creating SKU fragmentation between Andean and Mercosur markets.
- Sulfites:Sulfur dioxide and metabisulfite salts preserve color in dried fruits and wines; Argentine wine exporters maintain dedicated sulfite management protocols for EU-bound shipments.
- Nitrates:Sodium nitrite and potassium nitrate cure meats and inhibit botulism; Brazilian meatpackers balance inclusion levels against clean-label procurement mandates from retail chains.
Leading the category by volume: Sorbates. Growing fastest: Benzoates as beverage processing expands.
Application:
Volume concentration tracks protein processing infrastructure, with meat and dairy commanding logistics networks that preservative suppliers must co-locate against.
- Meat Processing:Cured, dried, and ambient-stable meat matrices require antimicrobial and antioxidant preservation. São Paulo's processing corridor consumes the region's largest preservative volumes, with export certification demands driving sorbate-nitrite blend innovation.
- Dairy Products:Fermented and fresh dairy applications favor sorbates for mold control in tropical distribution. Argentine yogurt manufacturers face compressed reformulation timelines as ANVISA harmonizes with CODEX standards.
- Baked Goods:Propionates and sorbates extend shelf life in pan bread and cracker applications; Brazilian millers integrate preservatives at flour-blending stage for distribution efficiency.
- Beverages:Juice, soft drink, and mineral water lines favor liquid benzoate systems for inline dosing. Montevideo's bottling cluster presents emerging demand as Uruguayan export infrastructure modernizes.
Highest volume concentration: Meat Processing. Steepest expansion trajectory: Beverages.
Form:
Powder formulations optimize freight economics, while liquid systems reduce labor intensity in high-throughput processing environments.
- Powder:Crystalline and spray-dried preservative forms dominate bulk logistics, offering stability and dosing precision. Argentine grain-derived sorbic acid precursors feed regional powder production.
- Liquid:Aqueous solutions and concentrated suspensions enable automated inline injection. São Paulo's beverage corridor drives adoption as bottlers eliminate manual handling stages.
- Granules:Free-flowing agglomerated particles reduce dust exposure in meat processing facilities; specialized applications in dry-cured product matrices.
- Tablets:Compressed preservative units serve small-scale artisan producers and restaurant supply channels with limited dosing equipment.
Dominant by tonnage: Powder. Gaining share fastest: Liquid.
End User:
Procurement sophistication stratifies across integrated manufacturers versus fragmented foodservice and retail channels.
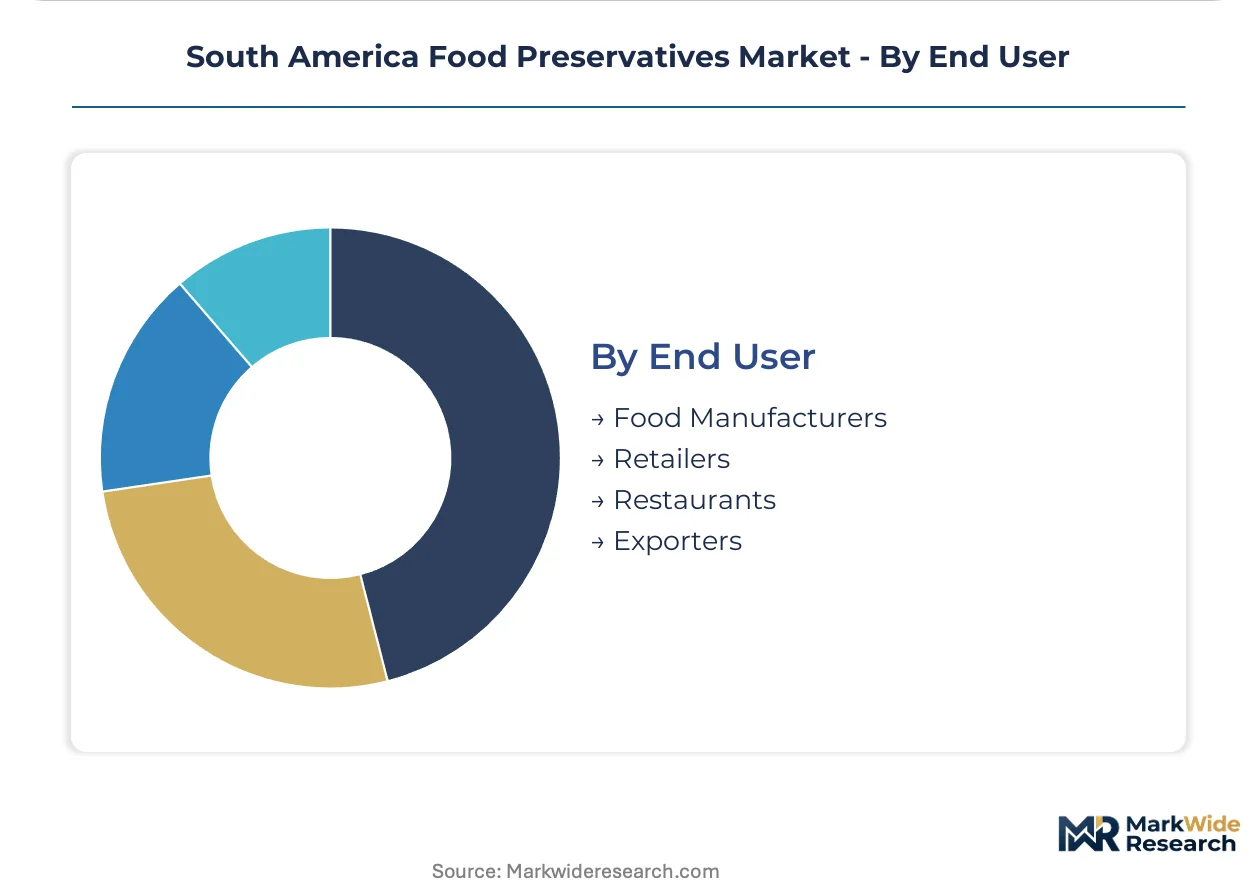
- Food Manufacturers:Integrated meat, dairy, and bakery operations negotiate volume contracts with direct technical service support. São Paulo's conglomerates drive specification-setting for regional supply chains.
- Retailers:Supermarket chains impose clean-label and transparency mandates through supplier scorecards. São Paulo-based retail procurement now requires front-of-pack preservative class disclosure.
- Restaurants:Foodservice distributors supply preservative-treated ingredients to chain and independent operators; secondary demand derived from processed input purchasing.
- Exporters:Mercosur meat and dairy exporters face dual compliance burdens—ANVISA domestic standards plus destination market requirements. Uruguayan mid-sized packers leverage Montevideo port modernization to bypass Brazilian distribution chokepoints.
Largest volume share: Food Manufacturers. Fastest procurement evolution: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's São Paulo state food manufacturing corridor, where meat processors and dairy conglomerates drive preservative procurement volumes. Argentina's export-oriented meatpackers and Uruguay's emerging port infrastructure reshape supply chain configurations across the Southern Cone.
Brazil
São Paulo state's integrated meat processing corridor consumes the region's largest preservative volumes as exporters extend shelf-life protocols for Asian destinations. ANVISA governs maximum residue limits and additive approvals, with updated reauthorization timelines compressing reformulation cycles. Campinas and Sorocaba host specialized preservative blending facilities co-located against protein processing infrastructure.
Argentina
Mid-sized meat exporters from the Pampas region gain procurement leverage through Mercosur trade zone access, differentiating via clean-label positioning. The national food safety authority enforces standards under Mercosur harmonization protocols, creating parallel compliance pathways. Rosario's agro-industrial cluster anchors grain-derived sorbic acid precursor production feeding regional supply chains.
Uruguay
Montevideo's port modernization creates cold-chain-adjacent preservative blending capacity that bypasses Brazilian distribution chokepoints. Industrial promotion frameworks subsidize fermentation facility construction, capturing cost advantages for natural preservative producers. Punta del Este corridor meatpackers leverage streamlined logistics for EU-bound shipments requiring dual compliance certification.
Chile
Santiago's beverage bottling cluster demands liquid preservative systems for inline dosing efficiency in mineral water and juice processing lines. The Ministry of Health maintains stricter benzoate thresholds than Mercosur baselines, forcing SKU fragmentation for cross-border products. Valparaíso port facilities adopt parallel testing protocols aligned with CODEX standards to streamline regional shipments.
South America Food Preservatives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived alternatives and clean-label positioning. The supplier base stratifies between integrated grain-to-additive conglomerates and specialized blenders tailoring formulations to local microbiological conditions. Three archetypes dominate: multinational chemical producers leveraging synthetic scale, food ingredient specialists with regional technical service networks, and biotechnology firms commercializing fermentation-derived antimicrobials. Capacity expansion and portfolio diversification toward natural alternatives constitute the primary competitive vectors.
Among the integrated supply chain operators, Cargill Incorporated anchors procurement leverage across Mercosur trade zones through captive grain sourcing. BASF SE occupies the synthetic preservative scale tier, while Kerry Group exemplifies the specialized blender archetype with region-specific formulation capabilities. Corbion N.V. represents the fermentation-derived pathway, positioning within clean-label segments as regulatory timelines accelerate natural additive approvals.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Kerry Group |
| DuPont |
| DSM |
| Archer Daniels Midland Company |
| Corbion N.V. |
| Celanese Corporation |
| Ajinomoto Co., Inc. |
| Others |
Value Network & Pricing Analysis
Food matrix compatibility expertise concentrates in São Paulo and Buenos Aires, where specialized preservative chemists command wage premiums that widen pricing spreads between premium fermentation-derived formulations and commodity synthetic tiers.
Pricing Analysis
Volume concentrates in commodity sorbate and benzoate contracts, while margins accrue to fermentation-derived clean-label alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and technical service bundling. Cost compression in standard synthetics intensifies because Argentine corn-derived feedstock volatility erodes blender margins. Mid-sized meat exporters exhibit highest price sensitivity; integrated São Paulo conglomerates absorb premiums for formulation support and regulatory dossier preparation.
Supply Chain Analysis
Reverse-logistics flows for preservative returns and reformulation scrap concentrate in Campinas and Sorocaba blending facilities, where batch reprocessing reduces raw material waste. Supply draws from Argentine grain-derived sorbic acid precursors, Brazilian fermentation capacity, and imported benzoate feedstocks from Asian producers. Single-source vulnerability runs through Mercosur customs harmonization delays that strand cross-border ingredient shipments. Distribution runs through São Paulo state's co-located protein processing corridor, with Montevideo's port modernization fragmenting logistics concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's compressed additive reauthorization timeline functions as a cost-of-compliance moat, elevating capital requirements for dossier preparation and toxicology testing that disadvantages undercapitalized entrants.
For Market Incumbents: Anchor regional position through captive fermentation capacity expansion in Brazilian biotech clusters, countering Kerry Group's formulation service dominance. Defend against Corbion N.V.'s clean-label acceleration by pre-submission of natural alternative dossiers ahead of formal mandate implementation. Deepen backward integration into Argentine grain supply to offset feedstock volatility.
For New Entrants and Emerging Players: Beverage bottler technical service partnerships offer the most penetrable channel, given São Paulo's inline dosing upgrade cycle and incumbent blind spots in liquid system automation. Target Uruguay's Montevideo corridor for cold-chain-adjacent blending capacity, leveraging industrial promotion subsidies to undercut Brazilian distribution costs. Lead with fermentation-derived antimicrobial peptides as drop-in benzoate replacements for pH-independent efficacy.
For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-derived specialists given ANVISA's regulatory acceleration favoring natural additive approvals. Long-term viability hinges on clean-label transition completion across meat and dairy matrices. Monitor retail procurement specification tightening as inflection signal, particularly São Paulo supermarket chain front-of-pack disclosure mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Cargill Incorporated leverages captive Argentine grain sourcing to stabilize sorbic acid precursor costs against harvest volatility. |
| Fermentation Facility Construction | Argentina's PLI-analog subsidies enable natural preservative producers to capture cost advantages against imported synthetics. |
| Technical Service Network Expansion | Kerry Group anchors regional position through specialized blends tailored to local microbiological conditions in tropical humidity zones. |
| Regulatory Dossier Pre-Submission | Brazilian meat processors pre-submit natural alternative dossiers to compress 14-18 month ANVISA approval timelines. |
| Liquid System Inline Dosing Deployment | São Paulo beverage bottlers eliminate manual handling stages through automated preservative injection infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with ANVISA regulatory affairs leads, São Paulo meat processor procurement directors, Argentine dairy formulation chemists, and Montevideo port logistics coordinators. Bottom-up segment sizing triangulated against top-down macroeconomic indicators derived from Mercosur trade statistics and CODEX-aligned standard updates.
Granularity extended to preservative type, application matrix, physical form, and end-user procurement sophistication across the projection horizon. CAGRs derived from volume trajectory modeling incorporating feedstock cost indices, regulatory timeline probability weights, and export destination shelf-life requirement shifts. Industry-specific inputs included ANVISA reauthorization queue velocity and retail chain supplier scorecard evolution.
Caveats apply where Argentine harvest yield volatility, ANVISA procedural delays, or Mercosur harmonization reversals could materially shift the outlook. Practitioners should monitor CODEX-aligned regional standard updates and clean-label procurement mandate tightening for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Spain Food Enzymes Market