
 China Food Enzymes Market | 2026-2036
China Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Enzymes Market Outlook
Beverage manufacturing is pivoting toward enzyme-assisted clarification and juice extraction as health-oriented drink categories expand. Novozymes leverages its microbial platform leadership to anchor supply relationships with major bottling groups across the Yangtze Delta. Kerry Group competes through integrated taste-and-nutrition systems that bundle enzymes with flavor masking technologies. Sunson Industry Group dominates domestic fermentation-derived enzyme production, sustaining cost advantages in bulk amylase and protease grades.
Food enzymes are protein-based biocatalysts, typically operating at 30-60°C and pH 4.0-8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. These catalysts enable controlled hydrolysis, polymer modification, and flavor precursor release across industrial food processing. Microbial-sourced enzymes lead the source dimension due to scalable fermentation economics and genetic engineering flexibility, while fungal-derived lipases capture premium positioning in specialty dairy applications. Amylase commands the largest volume share within enzyme types, though protease is gaining fastest in meat tenderization and plant protein processing. The application split shows beverages absorbing disproportionate innovation investment as clean-label extraction protocols replace conventional filtration.
SAMR enforces GB 2760 food additive standards that dictate permitted enzyme sources and usage limits, while MEE oversight of fermentation wastewater discharge shapes plant location decisions. NMPA alignment with food-grade enzyme safety dossiers determines import clearance timelines for foreign suppliers. Stakeholders must monitor evolving dual carbon compliance thresholds for fermentation energy intensity and assess whether backward integration into strain development or captive enzyme production offers sustainable margin protection.
Market Dynamics
China's dual carbon goals are compressing fermentation energy intensity standards and forcing capital redeployment toward cleaner production infrastructure across the food enzyme supply base.
Growth Catalysts
- GB 2760 Compliance Mandates:SAMR's tightening food additive standards are phasing out chemical alternatives and creating structured demand pull for enzymatic processing in dairy and bakery applications.
- Clean-Label Beverage Extraction:Bottling groups across the Yangtze Delta are replacing conventional filtration with enzyme-assisted clarification to meet consumer transparency expectations.
- Eastern Coastal Manufacturing Clusters:Processed food procurement concentrates in Jiangsu, Zhejiang, and Shandong provinces, generating density economies for enzyme suppliers.
Market Restraints
- Fermentation Energy Cost Volatility:Natural gas and electricity input swings compress margins for bulk amylase producers operating at scale.
- Import Clearance Friction:NMPA safety dossier alignment timelines delay foreign enzyme supplier market access and favor domestic incumbents.
- Protease Substitution Risk:Acid and alkaline hydrolysis methods retain cost advantages in low-margin meat processing segments.
Strategic Opportunities
- Western Province Underpenetration:Sichuan and Shaanxi processed food manufacturing lags coastal adoption rates by 40-60%, creating whitespace for distribution expansion.
- Plant Protein Processing Convergence:Protease and lipase blends are capturing emerging applications in pea and oat protein texturization for alternative dairy.
- MEE Wastewater Incentives:Fermentation discharge compliance subsidies are accelerating investment in closed-loop enzyme production systems.
Industry Challenges
- Strain Development Talent Scarcity:CRISPR-enabled microbial engineering expertise concentrates in Beijing and Shanghai, constraining regional facility staffing.
- GB Standard Revision Uncertainty:Pending updates to food-grade enzyme source approvals are freezing R&D pipeline commitments.
- Legacy DCS Integration Complexity:Fermentation control system upgrades require parallel enzyme dosing automation retrofits that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Enzymes Market |
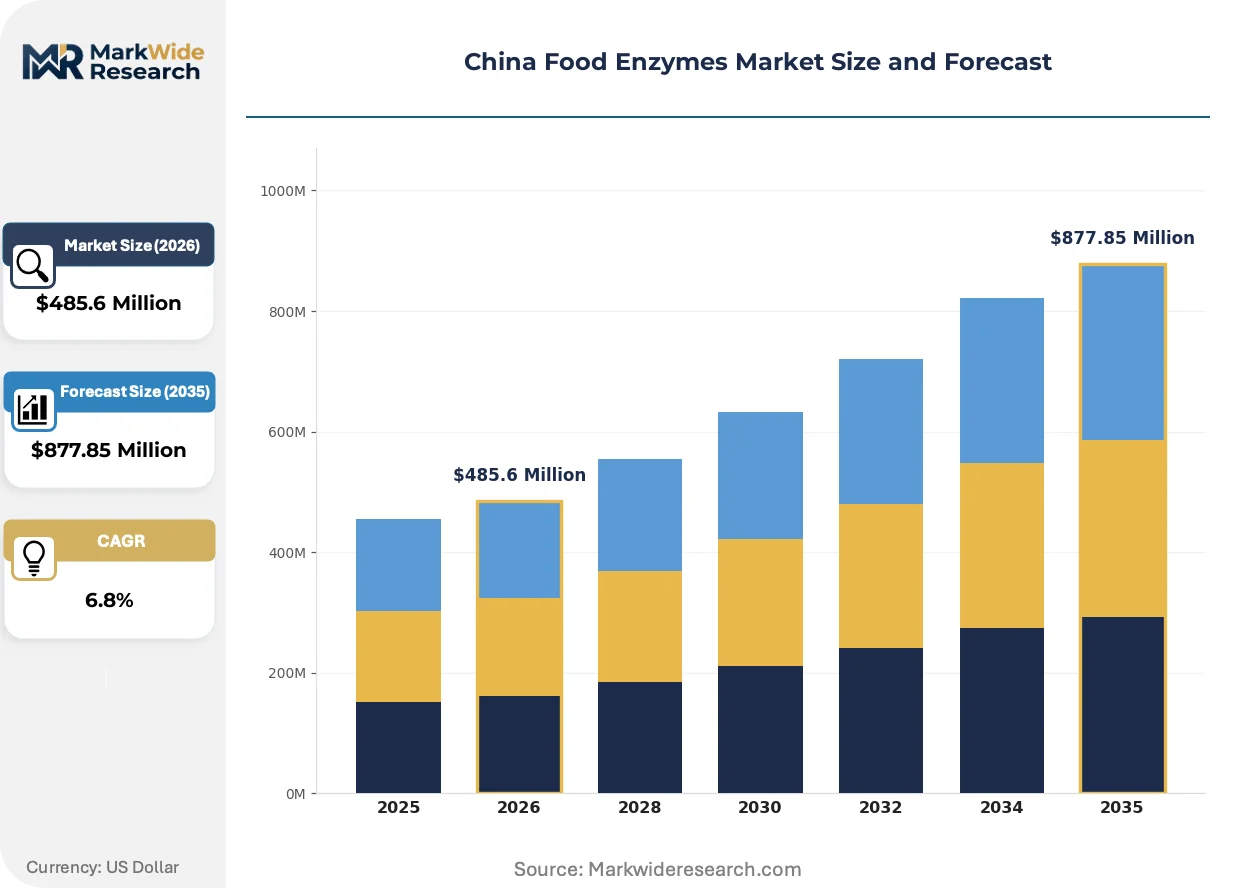
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $877.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Enzyme Type: Amylase, Protease, Lipase, Cellulase Application: Beverages, Bakery, Dairy, Meat Processing Source: Microbial, Plant, Animal, Fungal End User: Food Industry, Beverage Industry, Nutraceuticals, Others |
| Companies Covered | Novozymes, Kerry Group, Koninklijke DSM N.V., Amano Enzymes, Chr. Hansen Holding A/S, Sunson Industry Group, Beijing Challenge Group, Qingdao Vland Biotech Group, DuPont, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Enzymes Market Strategic Shifts
Bioprocess intensification and regulatory precision are reshaping how enzyme suppliers engineer production strains and position performance claims in China's food manufacturing procurement.
CRISPR-Cas9 microbial strain engineering is converging with continuous fermentation bioreactor design to compress enzyme titer yields and reduce batch-to-batch variability. Dairy processors in Jiangsu province are piloting these integrated platforms for lipase production. The technology convergence is enabling domestic suppliers to narrow quality gaps with imported specialty enzymes.
MEE oversight of fermentation wastewater discharge is tightening COD and ammonia nitrogen limits, forcing plant relocation decisions toward industrial park clusters with centralized treatment infrastructure. Enzyme manufacturers are responding with membrane bioreactor investments and anaerobic digestion retrofits. Bulk amylase producers in Shandong face the steepest compliance cost escalation.
Direct technical service engagement is displacing distributor-mediated enzyme sales in large beverage and bakery accounts. Novozymes and domestic competitors are embedding application scientists at major bottling group R&D centers. The model shift is most visible in Shanghai and Hangzhou, where procurement teams demand formulation co-development rather than commodity supply.
China Food Enzymes Market Segmentation
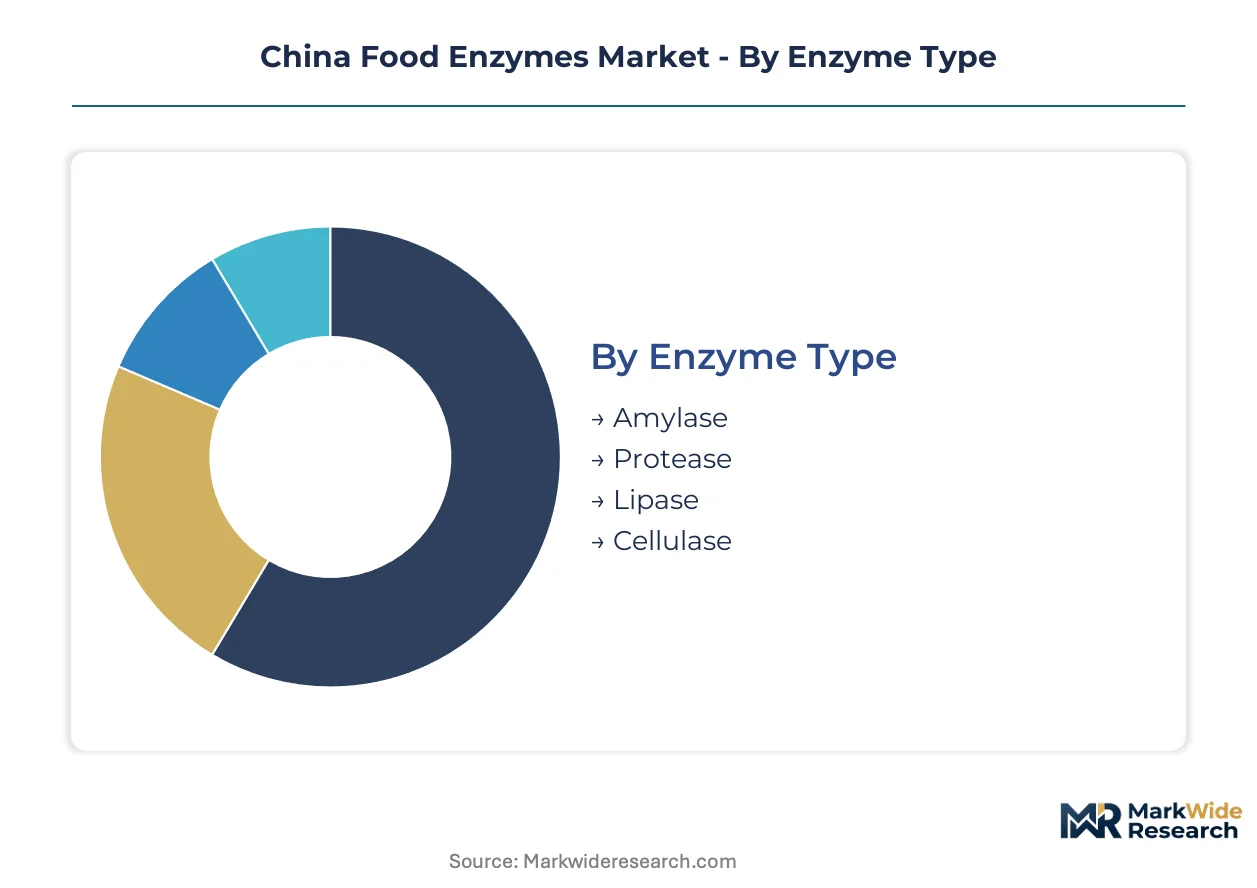
China's food enzyme procurement patterns diverge sharply across technical specifications and processing requirements. Segment boundaries determine supplier qualification criteria, pricing tiers, and technical service intensity for market participants.
Enzyme Type:
Technical performance specifications and thermal stability profiles define competitive positioning across catalyst categories.
- Amylase:Starch-hydrolyzing catalysts operating optimally at 50-70°C and pH 5.5-7.0, with thermostable variants commanding premium positioning in high-temperature liquefaction. Demand concentrates in Shandong province corn processing facilities where SAMR-compliant source documentation determines supplier selection.
- Protease:Peptide bond-cleaving enzymes spanning neutral, alkaline, and acidic pH ranges, with microbial-derived subtilisins capturing meat tenderization applications. Jiangsu dairy processors are expanding neutral protease adoption for whey protein hydrolysate production under tightening GB 2760 purity mandates.
- Lipase:Ester bond-specific catalysts enabling controlled fat modification and flavor ester synthesis.
- Cellulase:Beta-glucan degrading enzyme complexes for plant cell wall disruption and juice yield enhancement.
Mature deployment sits with Amylase. Newer deployment is concentrated in Protease.
Application:
Processing stage integration depth and formulation complexity create divergent margin structures across food manufacturing verticals.
- Beverages:Enzyme-assisted clarification protocols replacing diatomaceous earth filtration in fruit juice and plant-based milk categories. Yangtze Delta bottling groups are standardizing pectinase and cellulase blends for clean-label extraction transparency.
- Bakery:Amylase and xylanase formulations optimizing dough rheology and shelf-life extension in industrial bread production. Zhejiang frozen dough manufacturers are accelerating fungal alpha-amylase adoption for anti-staling performance.
- Dairy:Lipase and protease systems for cheese flavor development and whey processing.
- Meat Processing:Tenderization and flavor precursor release applications in prepared meat products.
Volume concentration favors Bakery. Value expansion is climbing fastest in Beverages.
Source:
Genetic engineering accessibility and fermentation economics shape supply security and cost trajectories across biological origin categories.
- Microbial:Bacterial and yeast-derived enzymes produced via submerged fermentation with CRISPR-enhanced strain optimization. Beijing and Shanghai biotechnology clusters anchor domestic production capacity for bulk industrial grades.
- Fungal:Aspergillus and Trichoderma-sourced catalysts capturing premium positioning in pH-sensitive applications. Thermostable fungal lipases from Jiangsu fermentation facilities are displacing imported specialty grades in aged cheese production.
- Plant:Bromelain and papain extracts from pineapple and papaya processing.
- Animal:Pancreatic and gastric enzyme preparations from slaughterhouse byproduct recovery.
Microbial sources dominate procurement volume. Fungal-derived products are gaining share fastest in high-value dairy applications.
End User:
Technical service requirements and formulation co-development intensity segment the customer base by industry sophistication and procurement centralization.
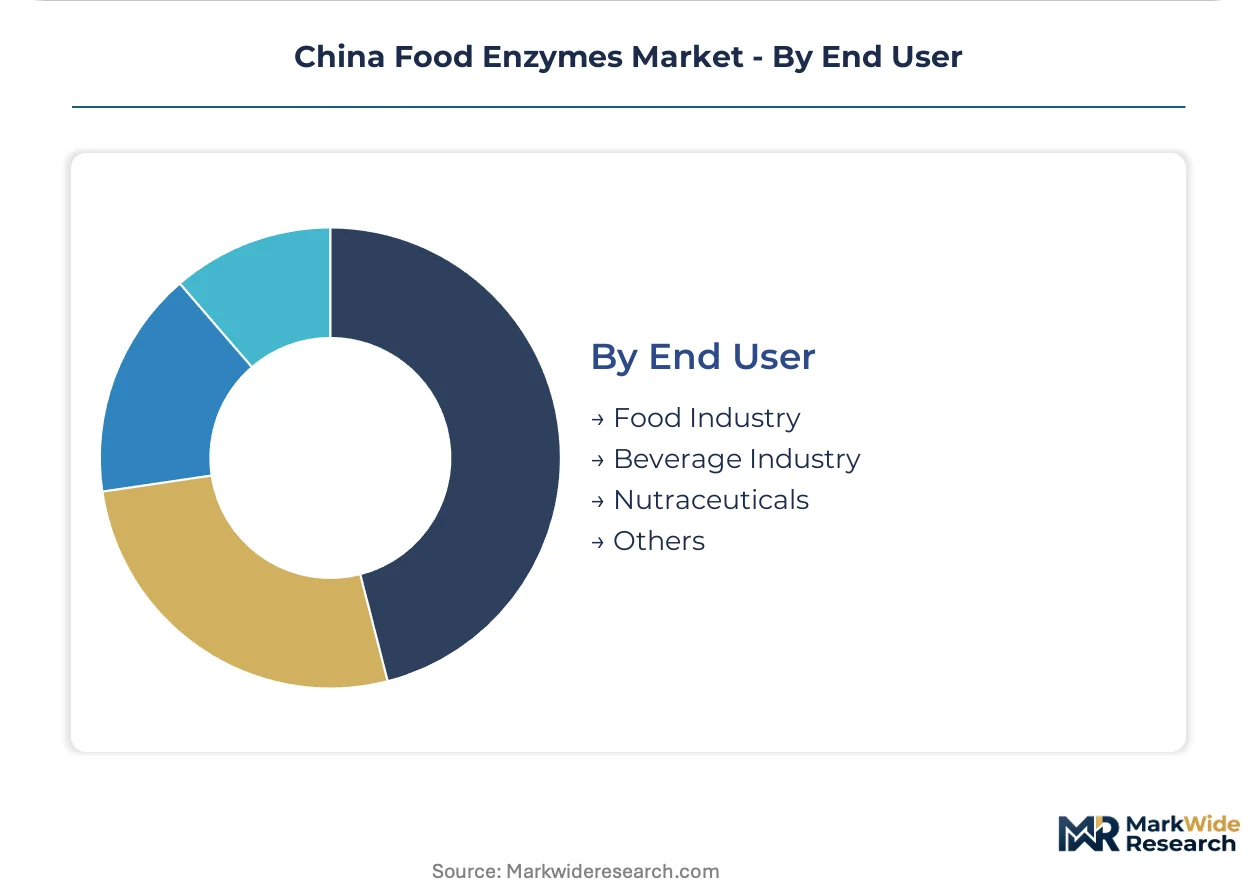
- Food Industry:Integrated processors spanning bakery, dairy, and prepared foods with centralized enzyme procurement functions. Multinational manufacturing joint ventures in Shanghai and Guangzhou are embedding supplier application scientists in R&D co-development protocols.
- Beverage Industry:Standalone bottling and extraction operations with specialized clarification and stabilization requirements. Hangzhou-based plant protein drink manufacturers are driving protease-lipase blend specification for oat and pea protein texturization.
- Nutraceuticals:Dietary supplement and functional food producers with enzyme-based bioactive extraction needs.
- Others:Animal feed and non-food industrial enzyme applications.
Food Industry anchors procurement scale. Beverage Industry is expanding most quickly in enzyme-assisted processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters along China's eastern seaboard while consumption spreads inland through processed food manufacturing networks. Fermentation-derived enzyme output concentrates in Shandong and Jiangsu provinces, generating supply-side economies that coastal dairy and bakery processors exploit. Western provinces remain structurally underserved by technical service infrastructure.
Yangtze River Delta
Beverage clarification and plant protein texturization drive enzyme procurement across Shanghai, Jiangsu, and Zhejiang manufacturing zones. SAMR's GB 2760 compliance audits accelerate adoption of documented microbial-source enzymes in Hangzhou-based oat milk facilities. Novozymes maintains application scientist embeds at major bottling group R&D centers in Shanghai.
Shandong Peninsula
Corn wet milling and starch processing anchor bulk amylase demand throughout Jinan and Qingdao industrial corridors. MEE wastewater discharge limits force fermentation facility relocation toward centralized treatment parks in Weifang. Domestic producers exploit captive strain development capabilities to undercut import pricing in standard-grade catalyst segments.
Pearl River Delta
Guangdong's dairy and bakery manufacturing clusters source thermostable fungal enzymes for high-temperature processing lines. Dual carbon compliance thresholds compress energy intensity standards for fermentation operations in Foshan. Kerry Group bundles taste-and-nutrition systems with enzyme formulations for Shenzhen-based prepared food exporters.
Sichuan-Chongqing
Processed meat and condiment manufacturing lags coastal enzyme adoption by approximately 50%, creating distribution whitespace for technical service expansion. Provincial environmental regulators enforce COD limits on fermentation discharge that favor industrial park concentration in Chengdu. Local meat processors retain acid hydrolysis methods for cost-sensitive tenderization applications.
Beijing-Tianjin-Hebei
Centralized procurement functions at multinational food manufacturing joint ventures concentrate enzyme specification authority in Beijing R&D centers. NMPA import clearance timelines for foreign safety dossiers favor domestic supplier relationships in Tianjin port zones. CRISPR-enabled strain engineering talent scarcity constrains regional facility staffing despite proximity to biotechnology research institutes.
China Food Enzymes Market Competitive Environment
Top-tier vendors anchor premium specialty enzyme supply, while domestic fermentation specialists capture bulk industrial grades through cost-optimized production. The market structures around three tiers: multinational technology leaders with microbial platform dominance, integrated taste-and-nutrition system providers, and domestic bulk producers leveraging captive strain libraries. Strategic archetypes include CRISPR-enabled strain developers, application-embedded technical service providers, and commodity-scale fermentation operators. Competitive moves concentrate on backward integration into strain development and direct R&D center embeds replacing distributor channels.
Among Denmark-based biotechnology leaders, Novozymes and Chr. Hansen Holding A/S exemplify microbial platform specialists with fermentation-derived enzyme capabilities. Kerry Group represents the integrated taste-and-nutrition archetype bundling enzymes with adjacent formulation technologies. Sunson Industry Group anchors domestic bulk production through Shandong-based fermentation infrastructure. These three archetypes illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic actions or market share outcomes.
| Leading Market Players |
|---|
| Novozymes |
| Kerry Group |
| Koninklijke DSM N.V. |
| Amano Enzymes |
| Chr. Hansen Holding A/S |
| Sunson Industry Group |
| Beijing Challenge Group |
| Qingdao Vland Biotech Group |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Fermentation energy costs cascade through China's food enzyme value chain, compressing margins for bulk amylase producers in Shandong while specialty lipase suppliers in Jiangsu maintain pricing power through strain-optimization premiums. Natural gas and electricity input volatility forces three-tier pricing stratification across premium, standard, and economy certification grades, with SAMR-compliant source documentation becoming the decisive tier separator.
Pricing Analysis
Margin tightening in standard-grade amylase reflects Shandong corn wet millers' procurement consolidation and captive fermentation capacity expansion by Sunson Industry Group. Three-tier pricing structure across premium, standard, and economy levels differentiates by GB 2760 compliance documentation depth and thermostability performance certification. Cost-down pressure on economy-grade protease accelerates because acid hydrolysis substitutes retain cost advantages in Sichuan meat processing. Beverage industry buyers in the Yangtze Delta demonstrate lowest price sensitivity, prioritizing formulation co-development and technical embeds over unit cost.
Supply Chain Analysis
Microbial strain libraries rest on Beijing and Shanghai biotechnology clusters, with fermentation capacity concentrated in Shandong and Jiangsu provinces. Corn starch and yeast extract feedstock dependencies anchor input costs to agricultural commodity cycles, while CRISPR-enabled engineering expertise scarcity constrains strain development velocity. Single-source vulnerability concentrates in thermostable fungal lipase supply from Jiangsu facilities serving premium dairy applications. Distribution runs through direct technical service teams embedded at major bottling group R&D centers, displacing traditional distributor channels in large accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's food enzyme sector is consolidating around backward integration into proprietary strain development, with fermentation capacity and CRISPR engineering talent emerging as the decisive upstream levers for sustainable margin protection.
For Market Incumbents: Acquire CRISPR-enabled microbial engineering capabilities to defend against Novozymes' platform dominance and domestic competitors' cost-optimized bulk production. Deepen captive fermentation capacity in Shandong industrial parks with MEE-compliant wastewater treatment infrastructure. Secure exclusive supply relationships with Yangtze Delta bottling groups through embedded application scientist deployments that substitute for distributor margin erosion. For New Entrants and Emerging Players: Capture Sichuan-Chongqing distribution whitespace where enzyme adoption lags coastal benchmarks by approximately half, creating first-mover advantage in condiment and processed meat manufacturing technical service. Target plant protein texturization applications in Hangzhou oat milk facilities with protease-lipase blend formulations. Pursue co-development partnerships with provincial industrial park operators to leverage MEE wastewater compliance subsidies for greenfield fermentation investment. For Investors and Strategic Acquirers: SAMR's pending GB 2760 enzyme source approval revisions are the leading indicator that regulatory clarity will trigger consolidation among strain-development-capable mid-cap specialists. Five-to-ten-year viability favors vertically integrated producers with captive fermentation infrastructure and documented microbial-source compliance dossiers. Watch NMPA import clearance timeline extensions for foreign safety dossiers as the signal that domestic supply security premiums will widen.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive CRISPR engineering capabilities narrow quality gaps with imported specialty enzymes from Danish platform leaders. |
| Direct Technical Service Embedding | Application scientist deployment at Yangtze Delta bottling R&D centers displaces distributor channels and locks formulation co-development. |
| Industrial Park Fermentation Relocation | MEE wastewater compliance subsidies in Weifang and Qingdao clusters reduce COD discharge treatment capital intensity. |
| Plant Protein Processing Convergence | Protease-lipase blend development for oat and pea texturization captures Hangzhou alternative dairy manufacturing expansion. |
| Western Province Distribution Buildout | Chengdu and Chongqing technical service infrastructure addresses Sichuan meat processor underpenetration versus coastal adoption rates. |
Study Parameters
Document review covered SAMR regulatory filings, MEE environmental compliance disclosures, and GB standards documentation, complemented by interviews with fermentation plant managers, dairy processor procurement leads, beverage industry R&D directors, and enzyme distributor channel partners. Secondary validation drew from customs trade data, Shandong and Jiangsu provincial industrial statistics, and SEC filings of multinational enzyme suppliers. Bottom-up capacity and consumption estimates triangulated against top-down market sizing from production cluster analysis.
Segment-level value and volume outputs traced enzyme type, application vertical, biological source, and end-user procurement sophistication across the projection horizon. CAGRs derived from fermentation capacity expansion timelines, GB standard revision implementation schedules, and dual carbon compliance investment cycles. Modeled inputs incorporated corn starch feedstock price trajectories, natural gas energy cost volatility, and NMPA import clearance friction coefficients for foreign supplier market access.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR's pending GB 2760 enzyme source approval revisions and MEE wastewater discharge limit tightenings. Projections reflect assumptions regarding dual carbon policy enforcement consistency and CRISPR talent pool expansion beyond Beijing-Shanghai clusters. A small set of named triggers—SAMR regulatory clarity, MEE subsidy program extensions, and NMPA import timeline normalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market