
 Honey Packaging Market | 2026-2036
Honey Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Honey Packaging Market Outlook
Retail buyer concentration around premium private-label honey brands is consolidating procurement volumes toward fewer but larger packaging contracts. Barkman Honey LLC leverages its co-operative supply structure to sustain long-term container agreements with Midwestern converters. Dabur India Ltd anchors its South Asian position through in-house blow-molding operations for PET honey bottles. Nature Nate's Honey Co. differentiates via transparent sourcing claims printed directly on pressure-sensitive labels.
Honey packaging encompasses primary and secondary containment systems engineered to prevent moisture ingress, resist crystallization-triggering temperature cycles, and maintain hygroscopic stability across shelf lives exceeding eighteen months. Glass jars remain the dominant format in European retail due to oxygen barrier performance and consumer perception alignment, though pouches represent the fastest-growing structural segment as e-commerce shippers seek dimensional weight reductions. Closure type selection increasingly tracks with food service dispenser requirements, where flip-top polypropylene configurations reduce drip waste in high-throughput environments.
FDA food-contact substance notifications govern polymer selection for US-bound honey containers, while EU REACH restrictions on bisphenol derivatives accelerate migration toward epoxy-phenolic alternatives in metal tin linings. The F-Gas Regulation indirectly shapes cold-chain packaging specifications for temperature-sensitive varietal honeys distributed through Central European retail networks. Stakeholders must monitor evolving extended producer responsibility frameworks as these programs expand packaging recovery obligations across core consumption markets.
Market Dynamics
Specialty food retailers and artisanal honey brands are consolidating procurement volumes toward fewer but larger packaging contracts, compressing converter margins while demanding faster turnaround on custom formats. This buyer concentration is the dominant structural force reshaping competitive positioning across the value chain.
Growth Catalysts
- EU Green Deal compliance mandates:REACH restrictions on bisphenol derivatives in metal tin linings are accelerating migration toward epoxy-phenolic alternatives, creating replacement demand across European converter bases.
- E-commerce dimensional weight optimization:Pouch formats are displacing rigid containers in direct-to-consumer shipping channels as logistics providers penalize volumetric inefficiency.
- German organic honey consumption:Packaging specifications for certified organic product lines outpace neighboring markets, pulling premium barrier-coated formats into broader distribution.
Market Restraints
- Bio-based barrier coating cost premiums:PLA and cellulose-derived films carry 15-40% raw material penalties versus conventional multilayer structures, constraining adoption in private-label segments.
- Converter concentration in Central Europe:Cold-chain packaging specifications for temperature-sensitive varietal honeys depend on a limited pool of F-Gas Regulation-compliant laminators.
- Glass jar oxygen barrier lock-in:European retail consumer perception alignment with transparent containment limits structural format diversification despite dimensional disadvantages.
Strategic Opportunities
- Extended producer responsibility frameworks:Packaging recovery obligation expansion across EU member states creates first-mover advantage for closed-loop material recovery partnerships.
- Flip-top polypropylene closure food service penetration:High-throughput dispenser environments in institutional catering represent underdeveloped demand for drip-reduction designs.
- Pressure-sensitive label transparent sourcing integration:Direct-print provenance claims on primary labels enable traceability-as-differentiation without secondary packaging cost.
Industry Challenges
- FDA food-contact substance notification timelines:Polymer selection for US-bound containers faces 90-180 day pre-market clearance cycles that compress product launch windows.
- Hygroscopic stability engineering talent scarcity:Formulation chemists capable of eighteen-month moisture ingress prevention across crystallization-triggering temperature cycles command premium compensation.
- Legacy blow-molding asset retrofit complexity:In-house PET bottle operations face capital intensity trade-offs between single-stage and two-stage reheat stretch machine replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honey Packaging Market |
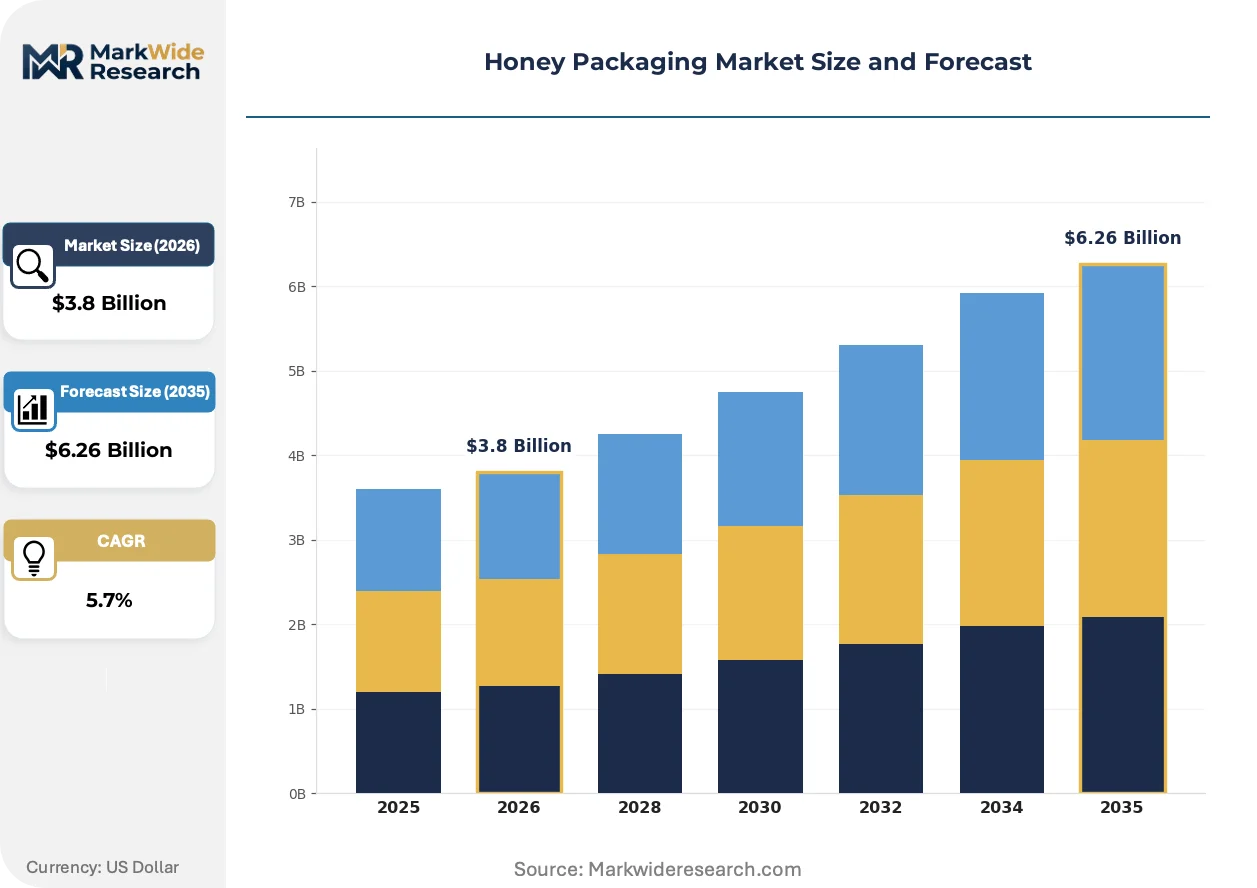
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Jars, Plastic Bottles, Metal Tins, Pouches Closure Type: Screw Caps, Flip Top, Lids, Spouts Labeling Type: Pressure Sensitive, Shrink Sleeve, Paper Labels, In-Mold End User: Retail, Food Service, E-Commerce, Wholesale |
| Companies Covered | Dabur India Ltd, Barkman Honey LLC, BASCO, Nature Nate’s Honey Co., Hive and Wellness, Placon, Sioux Honey Association Co-op, Capilano Honey, SimplKomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honey Packaging Market Strategic Shifts
Active barrier coating chemistry and digital print integration are converging to enable shorter-run customization without sacrificing shelf-life performance. These technical advances are compressing minimum order quantities while expanding format variety.
High-barrier bio-based coatings incorporating nanocellulose and regenerated protein films are consolidating technical validation pathways previously fragmented across academic and pilot-scale facilities. German and Dutch converters are adopting these materials for organic honey lines at accelerated pace. The technology is consolidating specification authority among a narrower tier of coating compounders capable of REACH-compliant migration testing.
EU F-Gas Regulation phase-down schedules are forcing cold-chain packaging redesigns for temperature-sensitive varietal honeys distributed through Central European retail networks. Laminators must certify alternative blowing agents or transition to hydrocarbon-based insulation cores. Central European co-operative honey packers are absorbing compliance costs through seasonal contracting structures that pool certification investments.
Retail buyer concentration around premium private-label brands is compressing supplier bases and extending contract durations. Midwestern US co-operative packers and South Asian integrated manufacturers are responding with captive blow-molding capacity and direct-to-retail logistics investments. Germany displays the most visible procurement consolidation, where three retail banners now control majority organic honey shelf space.
Honey Packaging Market Segmentation
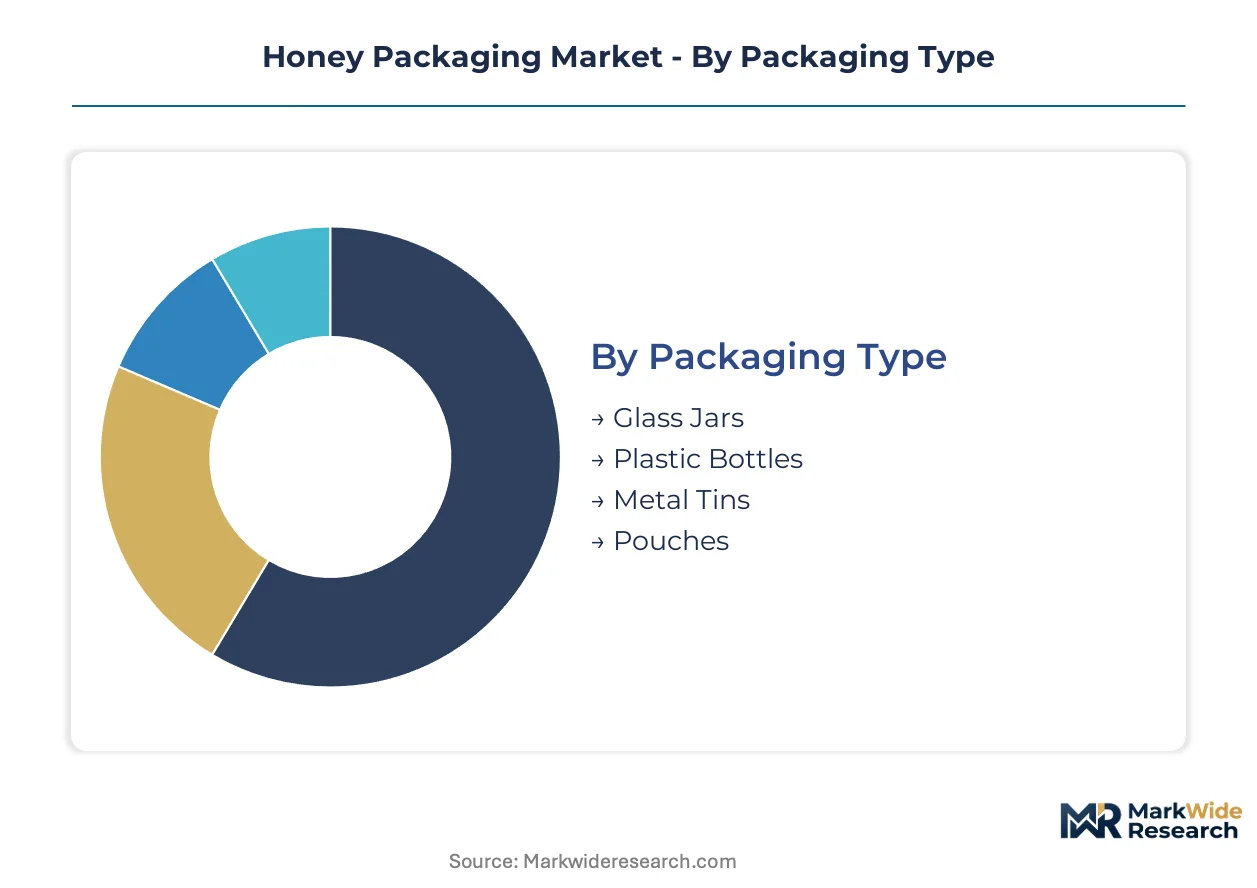
Honey packaging specifications diverge sharply across distribution channels, with each end-use imposing distinct barrier requirements, closure standards, and labeling regulations. Segmentation by material format and functional component reveals where compliance burdens concentrate and where converters capture premium margins.
Packaging Type:
FDA food-contact substance notifications govern polymer selection for US-bound containers, while EU REACH restrictions on bisphenol derivatives in metal linings accelerate migration toward epoxy-phenolic alternatives. Glass formats face separate compliance pathways under EFSA migration limits.
- Glass Jars:Borosilicate and soda-lime compositions deliver superior oxygen barrier performance for eighteen-month shelf life requirements. German organic honey retail specifications favor transparent containment despite dimensional weight penalties in e-commerce channels.
- Pouches:Multilayer structures incorporating aluminum oxide or silicon oxide coatings achieve moisture vapor transmission rates below 0.1 g/m²/day. E-commerce shippers in the Netherlands and Belgium are displacing rigid containers to avoid volumetric freight surcharges.
- Plastic Bottles:PET and HDPE formats require FDA pre-market clearance cycles of 90-180 days for food-contact substance notifications.
- Metal Tins:Epoxy-phenolic linings are replacing bisphenol-based coatings under EU REACH Annex XVII restrictions.
Leading the category by volume: Glass Jars. Growing fastest: Pouches.
Closure Type:
Cost tier differentiation separates commodity screw configurations from precision-molded dispensing systems, with food service procurement consolidating toward higher-unit-value flip-top designs.
- Flip Top:Polypropylene hinge-molded configurations incorporate silicone valve inserts to control drip rates below 0.05 mL per actuation. Institutional catering contracts in Germany specify these closures for high-throughput dispenser environments.
- Screw Caps:Standard 38mm and 43mm thread specifications dominate retail private-label procurement, with tamper-evident band integration adding 12-18% unit cost premiums.
- Lids:Metal lug closures for glass jars face EFSA compliance testing for migration of heavy metal contaminants.
- Spouts:Fitment-weld designs for stand-up pouches require burst pressure validation above 50 kPa for e-commerce drop-testing protocols.
Flip Top closures command the highest unit margins. Screw Caps move the largest absolute volumes.
Labeling Type:
Application method determines print substrate compatibility and regulatory traceability requirements, with direct-print provenance claims emerging as a differentiation vector.
- Pressure Sensitive:Facestock-adhesive-liner laminates enable digital short-run customization with transparent sourcing claims printed directly on primary labels. Nature Nate's Honey Co. leverages this format for traceability-as-differentiation without secondary packaging cost.
- Shrink Sleeve:PETG and OPS substrates provide 360-degree decoration coverage with barrier properties that extend shelf life in high-humidity retail environments.
- Paper Labels:Wet-glue applied kraft and coated stocks face moisture resistance limitations in cold-chain distribution.
- In-Mold:Polypropylene-compatible inks fused during blow-molding eliminate secondary labeling operations for high-volume PET bottle lines.
Pressure Sensitive labels dominate SKU proliferation. Shrink Sleeve formats are climbing the fastest in premium positioning.
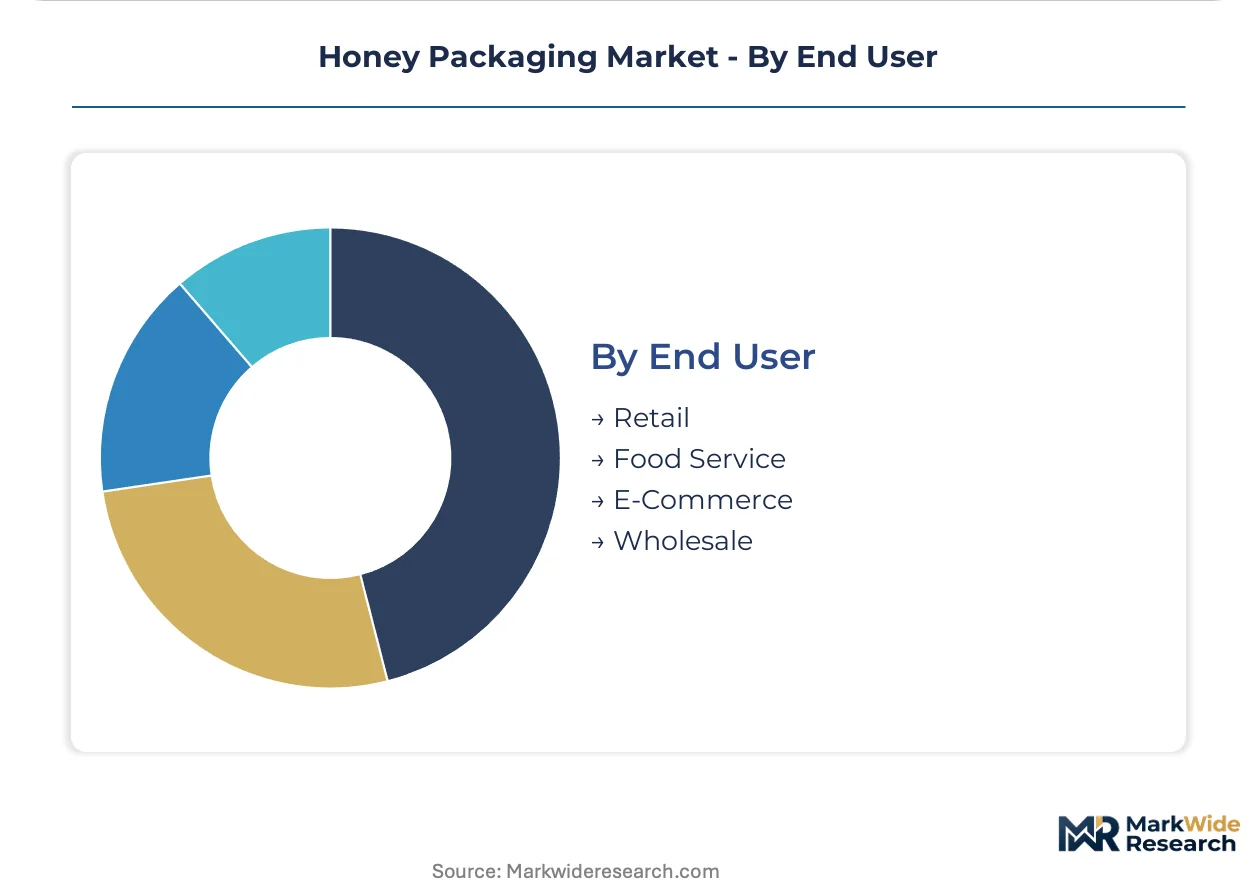
End User:
Customer type dictates order quantity thresholds, customization depth, and cold-chain infrastructure requirements, with procurement patterns diverging between consolidated retail banners and fragmented food service distributors.
- Retail:Three German retail banners now control majority organic honey shelf space, consolidating procurement toward fewer but larger packaging contracts with extended durations and compressed converter margins.
- E-Commerce:Direct-to-consumer shipping channels penalize volumetric inefficiency, pulling pouch formats and corrugated insert designs into broader adoption.
- Food Service:Institutional catering procurement specifies flip-top polypropylene closures for drip reduction in high-throughput environments.
- Wholesale:Co-operative supply structures sustain long-term container agreements with Midwestern converters through seasonal pooling of certification investments.
Retail channels absorb the highest packaging specification compliance costs. E-Commerce represents the steepest expansion trajectory for format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beekeeping cooperatives in Poland's Podlaskie Voivodeship supply the raw material base for Central European converter clusters. Packaging procurement patterns diverge sharply between mature retail markets and emerging e-commerce corridors.
Germany
Organic honey consumption specifications outpace neighboring markets, pulling premium barrier-coated formats into mainstream distribution. ECHA REACH restrictions on bisphenol derivatives in metal linings accelerate converter migration toward epoxy-phenolic alternatives. Bavarian co-operative packers absorb F-Gas Regulation compliance costs through seasonal contracting structures.
United States
Midwestern beekeeping co-operatives sustain long-term container agreements with regional converters through pooled procurement volumes. FDA food-contact substance notification timelines of 90-180 days compress product launch windows for polymer selection. Kansas-based Barkman Honey LLC anchors its supply structure through captive logistics investments.
India
Dabur India Ltd anchors South Asian market positioning through in-house blow-molding operations for PET honey bottles. FSSAI food safety compliance requirements govern packaging material migration limits for domestic and export-bound containers. Maharashtra-based converters serve both domestic retail chains and Middle East export corridors.
Netherlands
E-commerce shippers in Rotterdam and Amsterdam logistics hubs displace rigid containers with pouch formats to avoid volumetric freight surcharges. EU Green Deal bio-based coating mandates push converters toward PLA and cellulose-derived film validation. Dutch laminators certify alternative blowing agents under F-Gas Regulation phase-down schedules.
Australia
Capilano Honey and Hive and Wellness drive specification authority for high-barrier formats serving temperature-sensitive varietal distribution. TGA-equivalent state-level food contact regulations align with EFSA migration limit frameworks. Melbourne and Sydney converter clusters specialize in retail-ready glass jar configurations for premium export markets.
Honey Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based barrier coating specialization and e-commerce format innovation. Market structure reflects moderate consolidation around co-operative supply structures and integrated manufacturing operations. Three archetypes dominate: captive blow-molding operators, specialty label integrators, and logistics-optimized pouch converters. Capacity expansion and strategic partnerships represent the dominant competitive moves, with regional players pooling certification investments to defray compliance costs.
Among India-based integrated manufacturers, Dabur India Ltd exemplifies the captive production archetype through its in-house PET bottle operations. Midwestern US co-operative structures find representation in Barkman Honey LLC, which sustains long-term converter relationships through pooled procurement. Nature Nate's Honey Co. occupies a differentiation position via transparent sourcing claims integrated into pressure-sensitive label formats. These three anchors illustrate how geographic clustering and supply structure choices shape competitive positioning across the value chain.
| Leading Market Players |
|---|
| Dabur India Ltd |
| Barkman Honey LLC |
| BASCO |
| Nature Nate's Honey Co. |
| Hive and Wellness |
| Placon |
| Sioux Honey Association Co-op |
| Capilano Honey |
| SimplKomb |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters across Central Europe and the American Midwest anchor supply discipline through generational capital structures that resist quarterly margin pressure. Their pooled procurement contracts with co-operative honey packers sustain pricing stability even as bio-based coating premiums compress private-label tiers.
Pricing Analysis
Volume concentration in screw-cap glass jars trades margin for throughput, while flip-top polypropylene closures and high-barrier pouches capture premium spreads. Price differentiation hinges on EU organic certification tier and F-Gas Regulation cold-chain compliance grade. Pricing pressure intensifies in standard-tier private-label segments as three German retail banners consolidate procurement volumes. Food service buyers exhibit lowest price sensitivity due to drip-reduction specifications, whereas e-commerce shippers prioritize dimensional weight savings over unit cost.
Supply Chain Analysis
Direct-to-retail channels handle consolidated buyer demand from German organic honey banners, while co-operative pooling structures sustain Midwestern US converter relationships. Raw material supply concentrates in Germany, the Netherlands, and Poland for barrier-coated films and glass container production. Converter operations draw from epoxy-phenolic resin feedstocks, nanocellulose bio-coatings, and borosilicate glass batches. Single-source vulnerability in REACH-compliant laminators for Central European cold-chain specifications poses structural risk. Distribution runs through retail banner direct contracts, food service institutional procurement, and e-commerce logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive blow-molding capacity and in-house barrier coating compounding represent the decisive upstream levers. Players securing control over these inputs will dictate specification authority across consolidated retail procurement.
For Market Incumbents: Deploy captive PET blow-molding capacity to defend against South Asian integrated manufacturers expanding into European export corridors. Co-operative packers should deepen backward integration into bio-based coating formulation to offset REACH compliance cost absorption. Priority investments in F-Gas Regulation-certified laminator partnerships will secure cold-chain specification lock-in for varietal honey lines.
For New Entrants and Emerging Players: EU Green Deal bio-based mandates in the Netherlands and Germany open a window for PLA and cellulose-derived film specialists to penetrate organic honey private-label supply. E-commerce pouch formats for Belgian and Dutch direct-to-consumer channels represent the most penetrable white-space. Target food service flip-top closure design as a differentiation vector against incumbent screw-cap dominance.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Midwestern US co-operative packers with pooled converter relationships and captive logistics infrastructure. Long-term viability centers on extended producer responsibility framework readiness across EU member states. Monitor German retail banner procurement consolidation velocity as the inflection signal for packaging contract repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Coating Formulation | REACH-compliant compounders capture specification authority from fragmented academic pilot facilities. |
| E-Commerce Pouch Format Expansion | Rotterdam logistics hubs penalize rigid containers through dimensional weight surcharges. |
| F-Gas Regulation Certification Investment | Alternative blowing agent validation secures Central European varietal honey cold-chain contracts. |
| Direct-to-Retail Logistics Infrastructure | Kansas-based co-operative structures bypass distributor markups through pooled procurement. |
| Pressure-Sensitive Label Provenance Integration | Digital print transparency claims enable traceability differentiation without secondary packaging cost. |
Study Parameters
Independent corroboration across converter technical directors, retail category buyers, and co-operative procurement managers underwrites the qualitative findings. Primary fieldwork encompassed packaging engineers at German and Dutch laminators, FDA regulatory consultants, and FSSAI compliance officers in Maharashtra. Secondary validation drew from ECHA REACH substance restriction updates, EU F-Gas Regulation phase-down schedules, and customs trade data for honey container imports. Bottom-up volume estimates from segment-level procurement volumes triangulate against top-down market sizing from converter capacity disclosures.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models packaging type, closure configuration, labeling method, and end-use channel dimensions. CAGRs derive from segment-level demand elasticity and input cost trajectory modeling. Forecast inputs include bio-based coating raw material premium trends and e-commerce shipping rate structure evolution.
Caveats apply where REACH Annex XVII expansion or F-Gas Regulation acceleration could materially shift the outlook for metal tin and cold-chain specifications. Forecasts reflect base-case assumptions regarding German retail consolidation pace and bio-barrier coating technical validation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Edible Oil Packaging Market
Food Packaging
Food Tub Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Food Partition Trays Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Cereal Packaging Market