
 Global Natamycin Market | 2026-2036
Global Natamycin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Natamycin Market Foresight
Pharmaceutical-grade purity specifications is collapsing toward food-grade cost structures as fermentation yields improve and downstream processing scales. DSM leverages backward integration into streptomyces strain development to sustain margin control across European dairy supply chains. Zhejiang Silver-Elephant anchors volume production through captive fermentation capacity in Zhejiang province. Handary differentiates via Kosher and Halal certification breadth, occupying premium positions in Middle Eastern and Southeast Asian export channels.
Natamycin is a polyene macrolide antifungal agent produced via submerged fermentation of Streptomyces natalensis, typically formulated at concentrations between 100 and 500 parts per million for surface treatment of cheese and sausage casings. Its primary commercial purpose centers on inhibiting mold and yeast proliferation without bactericidal activity against starter cultures, preserving sensory profiles in fermented and fresh food matrices. Powder formulations dominate current procurement volumes due to stability in ambient storage and flexibility in dry-blend applications, while liquid suspensions represent the fastest-expanding format as automated spray systems penetrate industrial cheese processing lines. Dairy preservation commands the largest application share, though meat protection is deepening its growth trajectory as clean-label demands restrict synthetic alternatives.
The FDA governs natamycin as a GRAS substance under specific use conditions for cheese and sausage coatings, while EFSA maintains maximum residue limits that shape formulation standards across EU member states. China's SAMR enforces GB standards for food additive usage that determine market access for imported and domestically produced natamycin batches. India's FSSAI approval framework for natamycin in dairy applications creates additional compliance layers for suppliers targeting South Asian food manufacturers. Stakeholders must monitor evolving strain-optimization patents and regional clean-label certification requirements as competitive differentiation shifts from purity claims to fermentation-source traceability.
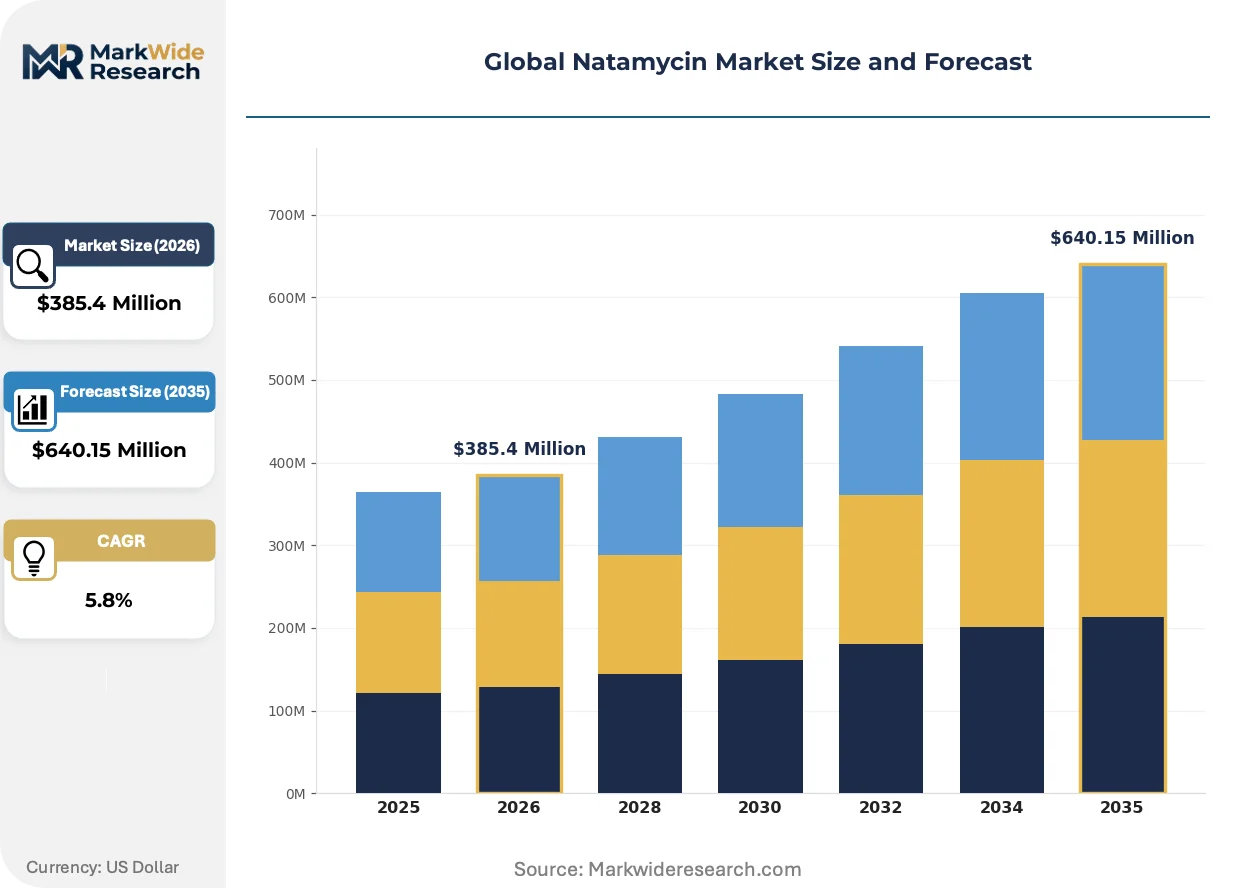
Market Dynamics
Fermentation yield improvements are collapsing pharmaceutical-grade purity premiums toward food-grade cost structures, while the EU Green Deal's food waste reduction mandates accelerate preservative procurement across European dairy supply chains.
Growth Catalysts
- EU Green Deal food waste targets:Stricter reduction mandates are reshaping preservative approval pathways and expanding natamycin adoption in cheese and fermented meat surface treatments across EU member states.
- Cold-chain expansion in China:Domestic dairy processors are building refrigerated distribution networks that extend shelf-life requirements and drive demand for mold-inhibiting coatings.
- Clean-label displacement of synthetics:Food manufacturers are replacing sorbates and benzoates with fermentation-derived natamycin to meet retailer clean-label specifications.
Market Restraints
- Streptomyces strain supply concentration:High-performing natalensis cultures remain concentrated among specialized fermentation houses, creating bottleneck risks for downstream formulators.
- EFSA maximum residue limits:Strict caps on surface treatment concentrations limit formulation flexibility and complicate multi-country compliance for pan-European suppliers.
- Propionic acid substitution in bread:Baked goods manufacturers favor cost-competitive propionates for mold control, constraining natamycin expansion beyond dairy and meat matrices.
Strategic Opportunities
- India FSSAI dairy approval:Pending regulatory clearance for natamycin in cheese coatings would unlock procurement from India's expanding organized dairy sector.
- Automated spray system integration:Liquid suspension formats are penetrating industrial cheese processing lines, creating pull for precision-dosing equipment partnerships.
- Halal certification premium positioning:Middle Eastern and Southeast Asian export channels reward suppliers with comprehensive religious certification breadth.
Industry Challenges
- Fermentation-source traceability documentation:Buyers increasingly demand batch-level strain provenance records, forcing investments in supply chain digitization.
- GB standard batch testing timelines:China's SAMR enforcement of food additive testing protocols creates extended market access delays for imported natamycin shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Natamycin Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Suspension, Emulsion Application: Dairy Preservation, Meat Protection, Beverage Stabilization, Bakery Extension End User: Food Manufacturers, Beverage Producers, Packaging Companies, Quality Control Labs Packaging Type: Plastic Containers, Glass Bottles, Sachets, Drums |
| Companies Covered | DSM, Handary, Zhejiang Silver-Elephant, Beijing Oriental Rada, Lanzhou Weiri, Langfang Meihua, Jiaozuo Joincare, Amtech Biotech, Shandong Freda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Natamycin Market Shifts & Advancements
Bioprocess engineering advances and regulatory harmonization pressures are converging to reshape how natamycin is produced, formulated, and positioned across food preservation applications.
Continuous fermentation technology is miniaturizing production footprints while stabilizing metabolite output. European contract manufacturers are retrofitting stirred-tank systems with perfusion modules that maintain steady-state natamycin titers. This process intensification is compressing capital requirements for regional supply capacity and enabling distributed production closer to dairy clusters.
EFSA's evolving stance on clean-label preservatives is tightening maximum residue limit enforcement across EU member states. Cheese exporters to Germany and France now face enhanced surface-residue testing protocols. Formulators are responding by developing precision-application equipment that reduces overspray and ensures compliance at lower effective concentrations.
Buyer concentration among multinational dairy processors is consolidating procurement decisions into centralized technical sourcing functions. Regional cheese cooperatives in the Netherlands and Denmark are losing direct supplier relationships as parent companies mandate approved vendor lists. This channel compression favors fermentation houses with global certification portfolios and multi-site manufacturing redundancy.
Global Natamycin Market Segmentation
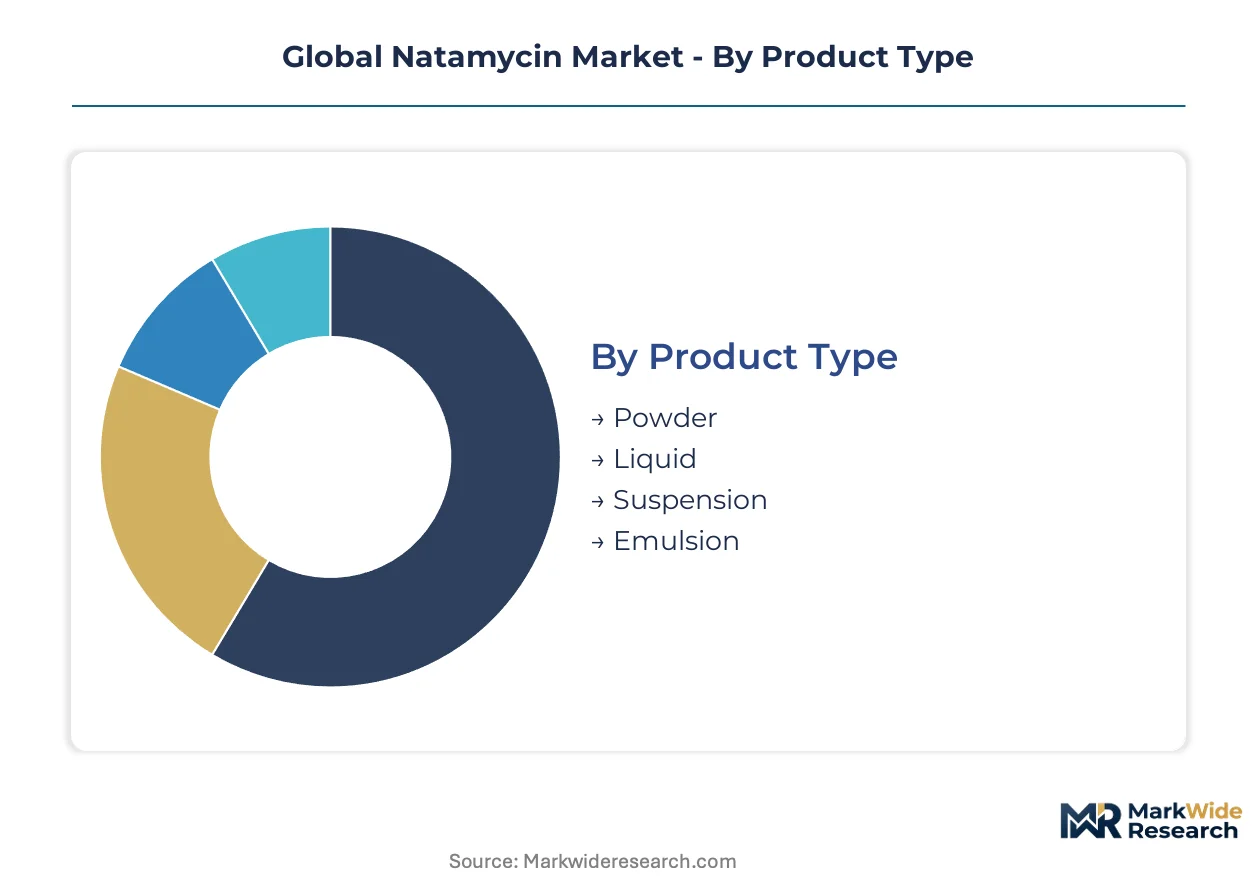
Segmentation in the natamycin market reveals how formulation choices, application matrices, and procurement channels distribute margin capture across the value chain. Understanding these divisions exposes where fermentation houses can defend pricing power and where formulators face commoditization pressure.
Product Type:
Powder formulations command the deepest margin pools due to stability premiums and dry-blend flexibility across ambient supply chains.
- Powder:Crystalline natamycin with standardized potency between 900 and 1000 international units per milligram dominates procurement volumes for cheese surface treatments. European dairy cooperatives in the Netherlands and Denmark specify powder for bulk dry-blend operations where extended ambient storage reduces cold-chain costs.
- Liquid:Aqueous suspensions at 2.5% to 5% concentration enable automated spray application systems penetrating industrial cheese processing lines in Germany and France. Food manufacturers favor liquid formats for precision dosing that reduces overspray waste and ensures EFSA maximum residue limit compliance.
- Suspension:Viscous preparations with stabilizing agents target artisanal cheese producers requiring manual brush or dip application methods.
- Emulsion:Oil-in-water systems integrate natamycin into edible coatings for sausage casings and fermented meat surfaces.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Application:
Volume concentration tracks cold-chain infrastructure maturity, with established networks enabling longer shelf-life targets that favor surface preservatives.
- Dairy Preservation:Cheese coatings represent the dominant consumption channel, spanning hard cheeses in Italy, soft ripened varieties in France, and processed cheese slices in US retail. Surface treatment at 100 to 500 parts per million inhibits mold without bactericidal impact on starter cultures, preserving sensory profiles that clean-label positioning demands.
- Meat Protection:Fermented sausage casings and dried meat surfaces in Spain and Portugal drive deepening adoption as sorbate displacement accelerates. The EU Green Deal's food waste reduction mandates expand procurement across Mediterranean processing facilities seeking fermentation-derived alternatives.
- Beverage Stabilization:Wine and juice applications remain niche due to natamycin's insolubility in aqueous systems below pH thresholds.
- Bakery Extension:Sliced bread and wrapped baked goods show limited penetration as propionic acid cost structures block displacement.
Dairy Preservation holds installed capacity. Meat Protection is climbing the fastest.
End User:
Procurement authority concentration determines contract structure, with centralized technical sourcing functions displacing regional purchasing autonomy.
- Food Manufacturers:Multinational dairy processors in Denmark and Ireland consolidate global vendor lists that demand multi-site manufacturing redundancy and comprehensive certification portfolios. These buyers specify batch-level strain provenance documentation that forces supply chain digitization investments.
- Beverage Producers:Wineries in France and Spain represent fragmented demand with limited scale.
- Packaging Companies:Active packaging integrators in Germany embed natamycin into film coatings for controlled-release applications.
- Quality Control Labs:Reference standard procurement for analytical testing creates stable but low-volume demand.
Food Manufacturers hold installed capacity. Packaging Companies is rotating up the share rankings.
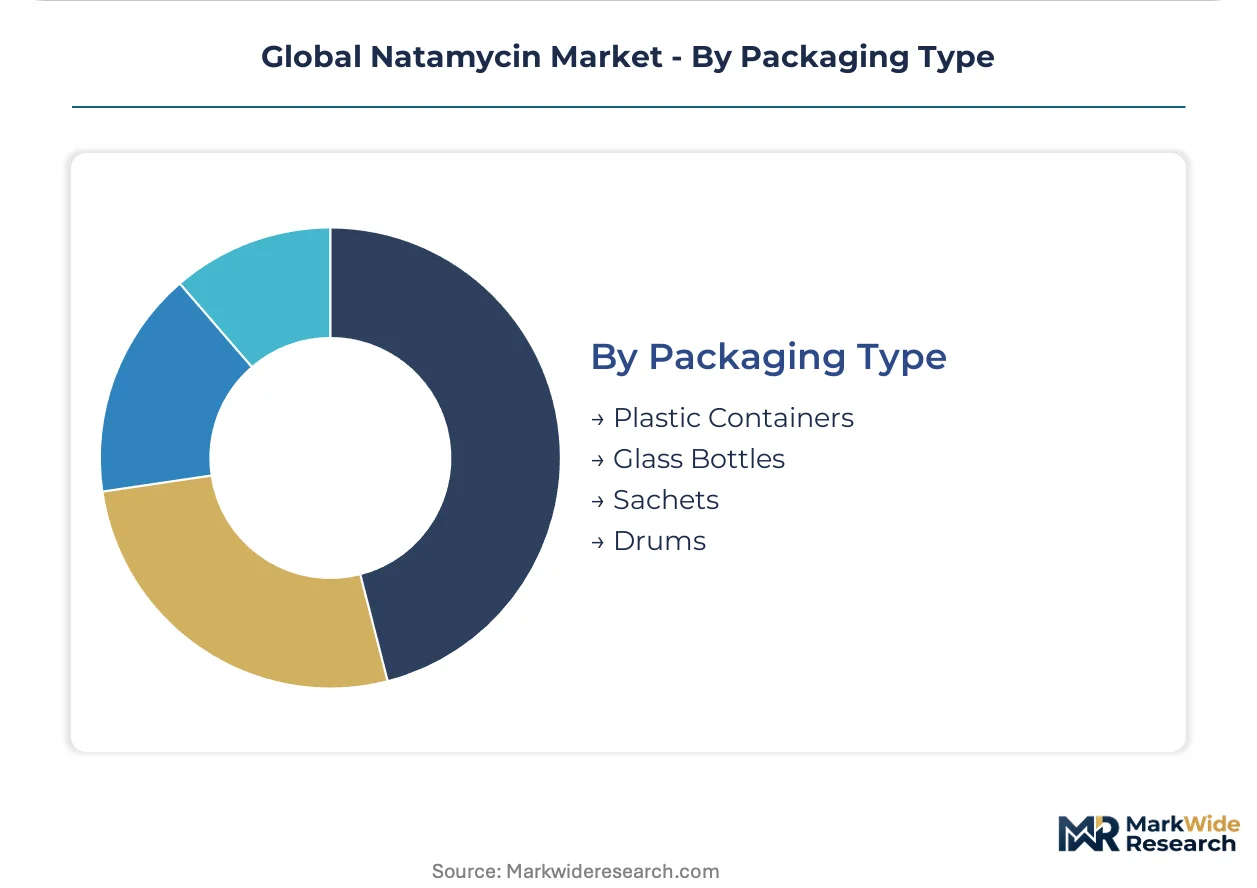
Packaging Type:
Logistics configuration and contamination risk shape format selection across import-dependent and domestic supply chains.
- Plastic Containers:High-density polyethylene drums and pails dominate liquid suspension shipments to industrial processors. China's SAMR enforcement of GB standard batch testing timelines favors plastic's durability through extended customs clearance periods.
- Glass Bottles:Pharmaceutical-grade specifications in analytical reagent channels require inert packaging.
- Sachets:Aluminum-laminate single-use packets target artisanal producers and food service channels in Southeast Asia.
- Drums:Steel and fiber drums handle powder bulk shipments exceeding 200 kilograms for European dairy compounders.
Plastic Containers hold installed capacity. Sachets is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in natamycin track fermentation capacity location against dairy processing clusters, with surplus production in China and the Netherlands supplying deficit markets in Southeast Asia and the Middle East. Cold-chain infrastructure maturity determines regional demand intensity, as extended distribution networks require surface preservatives to maintain shelf-life targets.
China
Domestic dairy processors in Hebei and Inner Mongolia are expanding refrigerated distribution networks that stretch shelf-life requirements beyond traditional limits. SAMR enforcement of GB standard batch testing protocols creates extended customs clearance timelines for imported natamycin shipments, advantaging local Zhejiang-based fermentation capacity. Hangzhou and Ningbo anchor concentrated streptomyces cultivation operations that supply both domestic cheese processors and export channels.
Germany
Industrial cheese processing lines in Bavaria and Baden-Württemberg are automating spray application systems that pull liquid suspension formats at precision dosing specifications. EFSA maximum residue limit enforcement tightens formulation flexibility, forcing equipment investments that reduce overspray waste. The Munich-Stuttgart corridor hosts concentrated dairy technical sourcing functions that consolidate procurement decisions for pan-European operations.
United States
FDA GRAS classification for cheese and sausage coatings enables broad formulation freedom, though clean-label retailer specifications increasingly restrict synthetic alternatives in favor of fermentation-derived preservatives. Wisconsin and California dairy cooperatives specify powder formats for bulk dry-blend operations where ambient storage reduces cold-chain costs. Chicago-based food manufacturers are consolidating approved vendor lists that demand multi-site manufacturing redundancy.
India
FSSAI pending approval for natamycin in cheese coatings would unlock procurement from Maharashtra and Gujarat's expanding organized dairy sectors. Current regulatory uncertainty constrains formal adoption, though informal demand persists through technical-grade imports. The Anand-Mumbai corridor hosts emerging cold-chain infrastructure that will extend shelf-life targets once preservative clearance finalizes.
Netherlands
DSM's backward integration into streptomyces strain development sustains margin control across European dairy supply chains originating from Rotterdam distribution hubs. Friesland and Noord-Brabant cheese cooperatives are losing direct supplier relationships as multinational parent companies mandate centralized technical sourcing. Amsterdam serves as the regulatory compliance gateway for EFSA-aligned documentation across EU member states.
Global Natamycin Market Competitive Landscape
Concentration sits with fermentation houses that control captive streptomyces strain development, while downstream formulators face commoditization pressure from yield-improved supply. Three archetypes populate the competitive terrain: integrated bioprocess specialists with in-house cultivation capacity, regional compounders serving single-country dairy clusters, and certification-focused suppliers targeting religious dietary compliance premiums. Capacity expansion and backward integration into strain optimization represent the dominant competitive moves, with secondary emphasis on precision-application equipment partnerships.
Among Dutch and Belgian integrated specialists, DSM and Handary occupy positions that exemplify divergent strategic anchors—DSM through upstream control over fermentation genetics, Handary through comprehensive Kosher and Halal certification breadth for Middle Eastern and Southeast Asian export channels. Chinese capacity clusters around Zhejiang Silver-Elephant, which anchors volume production through captive fermentation infrastructure in Zhejiang province. These three represent the tiered structure: integrated bioprocess control, certification-premium positioning, and scale-driven regional supply.
| Leading Market Players |
|---|
| DSM |
| Handary |
| Zhejiang Silver-Elephant |
| Beijing Oriental Rada |
| Lanzhou Weiri |
| Langfang Meihua |
| Jiaozuo Joincare |
| Amtech Biotech |
| Shandong Freda |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade purity specifications collapsing toward food-grade cost structures simultaneously shifts production gravity toward high-yield fermentation clusters in China and compresses margin premiums across European supply chains. Yield improvements from continuous fermentation retrofits enable Zhejiang-based producers to undercut legacy pharmaceutical-grade pricing while maintaining EFSA-compliant purity thresholds.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the natamycin market. Certification breadth—Kosher, Halal, and organic-compliant grades—commands premium positioning for Middle Eastern and Southeast Asian export channels, while bulk powder contracts for European dairy cooperatives trade at standard tiers. Cost compression in economy segments is intensifying because Chinese fermentation houses are scaling continuous perfusion systems that collapse unit production costs. Regional cheese cooperatives in the Netherlands and Denmark exhibit highest price sensitivity as multinational parent companies consolidate procurement into centralized technical sourcing functions with mandated vendor lists.
Supply Chain Analysis
China and the Netherlands anchor global streptomyces fermentation capacity, with Zhejiang province and Rotterdam distribution hubs supplying deficit markets across Southeast Asia and the Middle East. Downstream natamycin production draws from specialized streptomyces natalensis cultures, pharmaceutical-grade filtration membranes, and automated spray application equipment as critical inputs. Single-source vulnerability concentrates in high-performing strain development, where DSM's backward integration into genetics creates bottleneck risks for independent formulators. Distribution runs through plastic container shipments for liquid suspensions and steel drum bulk powder deliveries to European dairy compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision-application equipment partnerships represent a service-attach opportunity expanding faster than commodity natamycin supply, as automated spray system integration creates recurring calibration and maintenance revenue streams alongside preservative offtake.
For Market Incumbents: Fortify margin control through captive strain optimization investments and multi-site manufacturing redundancy across European dairy clusters. Propionic acid substitution in bread applications threatens expansion beyond core dairy and meat matrices, while EFSA maximum residue limit enforcement demands precision-dosing equipment partnerships to ensure compliance at lower effective concentrations. For New Entrants and Emerging Players: Anchor in India's pending FSSAI regulatory clearance for cheese coatings, where organized dairy sector expansion in Maharashtra and Gujarat awaits formal preservative approval. Artisanal cheese producers requiring manual brush or dip application methods represent the most penetrable segment, with viscous suspension formats enabling differentiated positioning through application-method specialization. For Investors and Strategic Acquirers: The market sits at a yield-optimization phase that favors fermentation houses with backward-integrated strain development capabilities. Long-term viability across the projection horizon hinges on regulatory harmonization progress and cold-chain infrastructure maturation in emerging dairy markets. Acquisition targets should demonstrate batch-level strain provenance documentation systems; the signal to watch is India's FSSAI final approval timeline as inflection indicator for South Asian demand unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | DSM's streptomyces genetics control sustains margin defense across Rotterdam-anchored European supply chains. |
| Continuous Fermentation Retrofit | Perfusion module installations in Zhejiang compress capital requirements for regional capacity expansion. |
| Precision-Application Equipment Partnership | Automated spray system integration in Bavaria ensures EFSA compliance through reduced overspray waste. |
| Comprehensive Religious Certification Investment | Handary's Kosher and Halal breadth captures premium positioning in Middle Eastern export channels. |
| Multi-Site Manufacturing Redundancy | Global certification portfolios satisfy multinational dairy processor vendor consolidation mandates. |
Research Methodology
A standing panel of fermentation plant managers, dairy procurement leads at multinational processors, regulatory affairs specialists, and active packaging integrators provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA guidance documents, FDA GRAS notifications, China's SAMR GB standards filings, customs trade data for natamycin import flows, and SEC filings of listed fermentation houses. Bottom-up volume modeling across product type, application matrix, and end-user concentration triangulated against top-down market sizing from regional production capacity assessments.
Consistency checks validated volume and value outputs against external benchmarks including regional dairy production statistics, cold-chain infrastructure investment disclosures, and preservative import duty records. Segmentation dimensions spanned formulation format, application matrix, procurement channel authority, and geographic regulatory cluster throughout the modeling period. CAGRs derived from fitted growth curves applied to base-year consumption estimates, with industry-specific inputs including fermentation yield improvement trajectories and EFSA maximum residue limit enforcement intensity.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal food waste target enforcement and China's cold-chain expansion continuity; material deviation in regulatory approval timelines or strain supply concentration would warrant model refresh. Recalibration cycles align with material shifts in FSSAI clearance status, EFSA residue limit revisions, and automated spray system penetration rates in industrial cheese processing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market