
 Non-PHO Emulsifiers Market | 2026-2036
Non-PHO Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Non-PHO Emulsifiers Market Analytics
Ingredient reformulation services is reshaping margin distribution across the non-PHO emulsifiers value chain. Cargill leverages its North American oilseed processing network to secure non-GMO sunflower lecithin streams. BASF SE anchors European supply through enzymatic modification capabilities for high-performance emulsifiers. Kerry Group competes on clean-label application expertise, embedding emulsifier blends directly into customer formulation labs.
Non-PHO emulsifiers are lipid-based surface-active agents manufactured without partially hydrogenated oils, typically derived from lecithin extraction or interesterification of vegetable oils, with HLB values ranging from 3 to 15 to stabilize oil-water interfaces in processed foods. Their primary commercial purpose is to replace trans-fat-bearing PHO emulsifiers while maintaining texture, shelf stability, and aeration in baked goods and dairy systems. Soy lecithin retains the largest volume position due to mature crushing infrastructure and cost structure, though sunflower lecithin captures premium positioning in allergen-sensitive and non-GMO product lines. Baking applications absorb the majority of non-PHO emulsifier volumes, while dairy products represent the fastest-growing application segment as plant-based alternatives require sophisticated emulsification.
FDA trans-fat labeling rules and the EU's F-Gas Regulation on processing emissions shape formulation mandates and production equipment standards across major supply regions. EFSA evaluations of novel emulsifier sources determine market access timelines for European suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation cost impacts and sourcing flexibility requirements.
Market Dynamics
Ingredient reformulation services are redistributing margin capture across the non-PHO emulsifiers value chain, as clean-label mandates force manufacturers to embed technical expertise deeper into customer operations rather than selling commoditized inputs alone.
Growth Catalysts
- FDA trans-fat labeling rules:Clean-label bakery chains in the United States are accelerating PHO replacement programs ahead of enforcement deadlines, creating sustained demand pull for enzymatically modified lecithin alternatives.
- Plant-based dairy expansion:Oat and almond milk processors require sophisticated emulsification systems to stabilize fat-protein matrices, driving technical-grade emulsifier consumption in beverage applications.
- German sunflower crushing infrastructure:EFSA guidance on sustainable palm alternatives has concentrated supplier qualification activity in Baden-Württemberg and Bavaria, anchoring European non-GMO lecithin supply.
Market Restraints
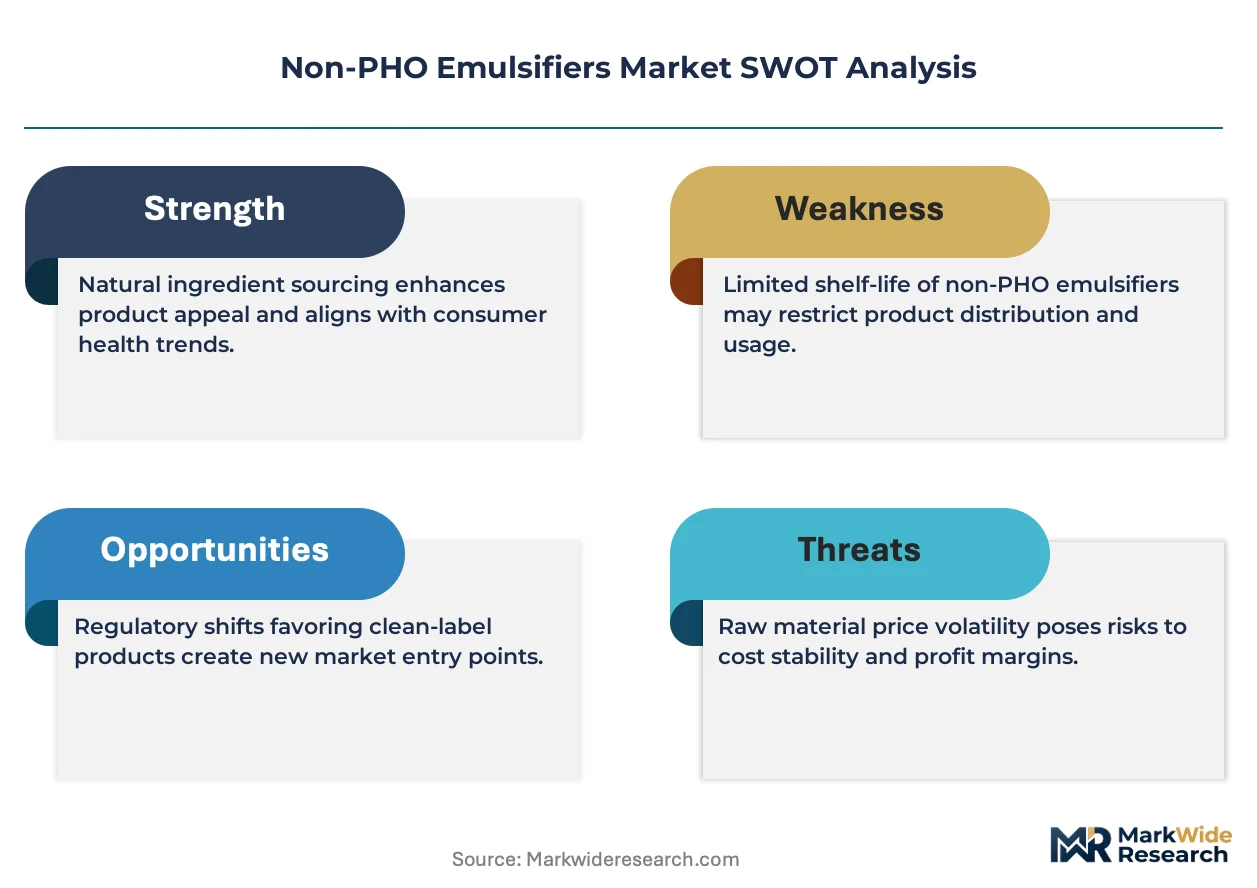
- Sunflower seed price volatility:Black Sea supply disruptions and weather-driven yield fluctuations in Ukraine and Russia transmit directly into lecithin input cost instability.
- Soy lecithin allergen classification:EFSA and FDA labeling requirements for soy-derived ingredients restrict formulation flexibility in pediatric and allergen-sensitive product lines.
- Interesterification capacity concentration:High-performance emulsifier production depends on specialized enzymatic processing equipment concentrated among a limited European supplier base.
Strategic Opportunities
- India FSSAI clean-label adoption:Processed food manufacturers in Maharashtra and Gujarat are initiating PHO reformulation programs ahead of anticipated trans-fat limits in the packaged foods sector.
- Cell-cultured fat integration:Precision fermentation-derived lipids are converging with conventional emulsifier systems to create hybrid stabilization platforms for next-generation alternative proteins.
- EU F-Gas Regulation compliance:Processing equipment upgrades mandated for emissions control are creating retrofit demand for energy-efficient emulsifier production lines in Netherlands and Belgium.
Industry Challenges
- Enzymatic process engineering talent:Interestification and phospholipase modification operations require specialized biochemists and chemical engineers in short supply across European manufacturing clusters.
- Clean-label certification timelines:Non-GMO Project and organic accreditation processes extend supplier qualification cycles by 12-18 months, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-PHO Emulsifiers Market |
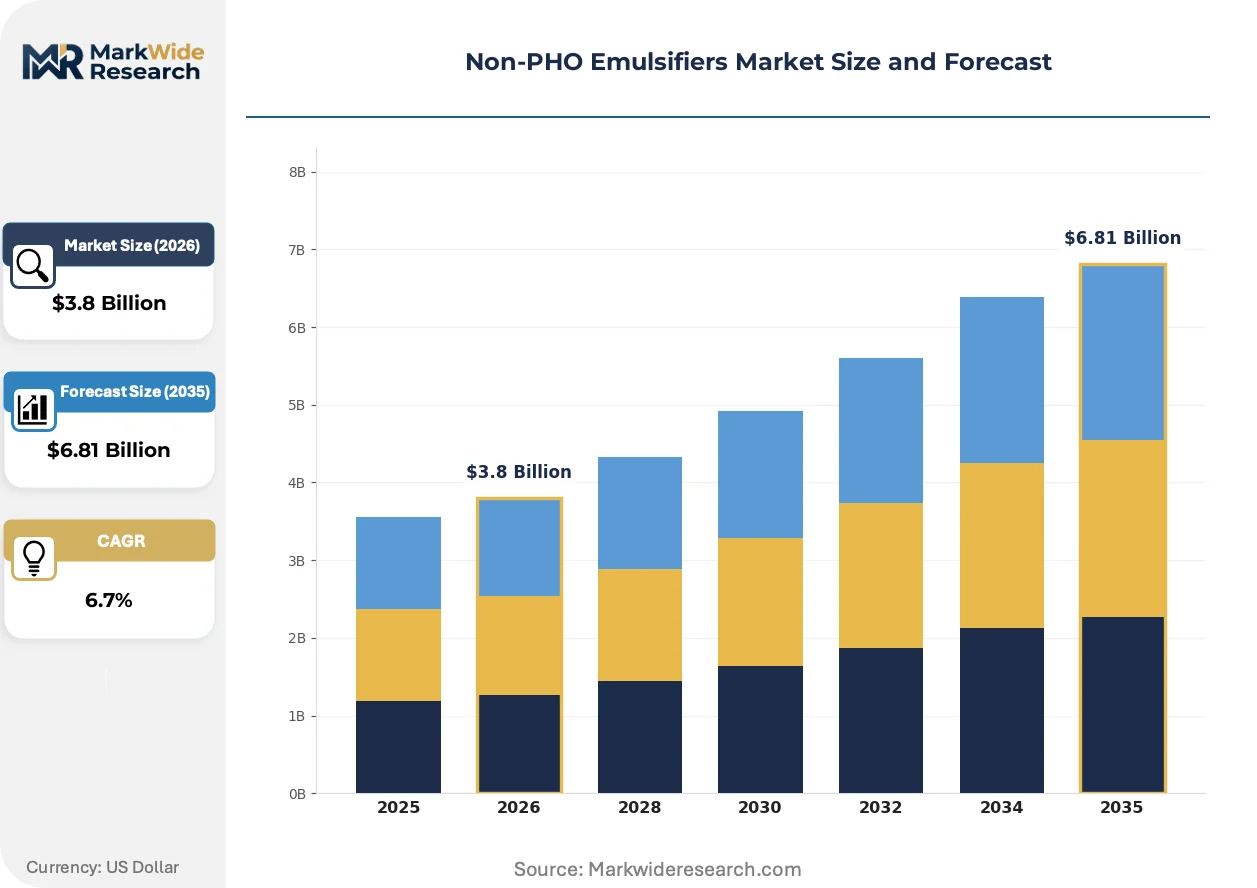
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Lecithin, Sunflower Lecithin, Palm Oil Emulsifiers, Egg Yolk Powder Application: Baking, Dairy Products, Sauces, Dressings End User: Food Manufacturers, Beverage Producers, Bakery Chains, Catering Services Distribution Channel: Online Retail, Grocery Chains, Specialty Stores, Direct Sales |
| Companies Covered | Cargill, Archer Daniels Midland, Ingredion Incorporated, Kerry Group, DuPont Nutrition & Biosciences, Corbion, BASF SE, Palsgaard, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-PHO Emulsifiers Market Evolving Landscape
Enzymatic phospholipid modification and cell-cultured lipid integration are collapsing traditional boundaries between natural extraction and biotechnology-derived emulsification systems.
Enzymatic interestification is collapsing the performance gap between chemically modified and clean-label emulsifiers. High-performance bakery manufacturers in France and Germany are adopting phospholipase-treated sunflower lecithin at accelerated qualification cycles. This technology is collapsing premium pricing tiers for traditional distilled monoglycerides in laminated dough applications.
EFSA novel food evaluations are extending market access timelines for microbial-derived emulsifier sources. European suppliers face 18-24 month authorization delays for precision fermentation lipids intended for infant formula. Dairy alternative processors in Netherlands and Denmark are most affected, reformulating with interim plant-based systems while awaiting regulatory clearance.
Direct supplier embedding in customer R&D facilities is displacing traditional ingredient distribution models. Large bakery and dairy manufacturers in the United States are consolidating emulsifier procurement through dedicated formulation partnerships rather than spot purchasing. This pattern is most visible in California and Illinois, where clean-label product development cycles have compressed from 24 months to 12 months.
Non-PHO Emulsifiers Market Segmentation
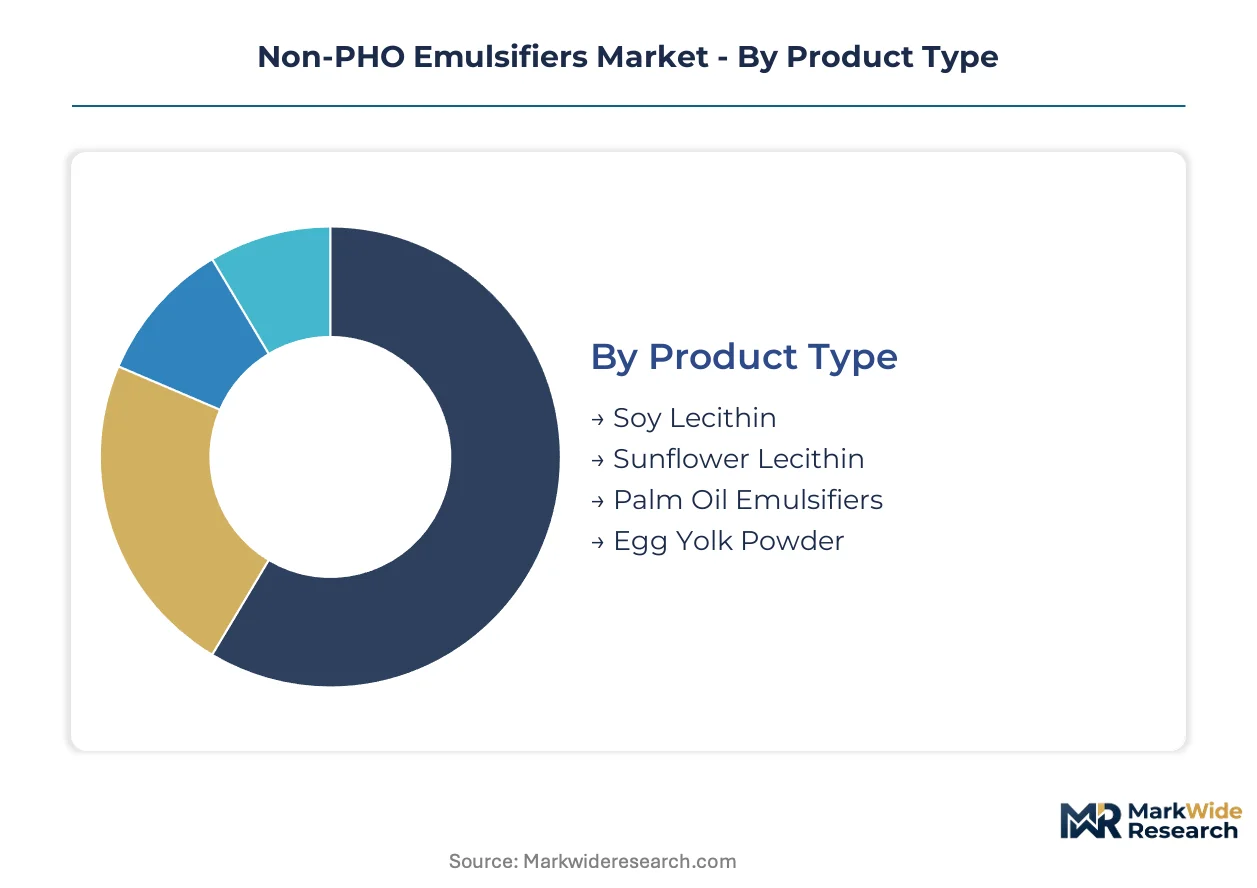
Non-PHO emulsifier procurement patterns diverge sharply across product chemistry, application viscosity requirements, and end-user technical capabilities. Each segmentation dimension reveals distinct margin structures and supplier qualification barriers that reshape competitive positioning.
Product Type:
Use-case spectrum spans commodity-scale baking operations to premium allergen-sensitive formulations, with extraction source and modification intensity determining price positioning and clean-label certification eligibility.
- Soy Lecithin:Extracted through solvent or mechanical processing from soybean oil degumming streams, soy lecithin carries standardized phosphatidylcholine content of 15-22%. Crushing infrastructure concentration in Argentina and Brazil secures volume supply for U.S. baking conglomerates, though FDA allergen labeling mandates constrain pediatric and sensitive-segment deployment.
- Sunflower Lecithin:Cold-pressed extraction yields lighter color and neutral flavor profiles prized in European premium confectionery. Black Sea supply volatility and non-GMO certification premiums position this grade 40-60% above soy equivalents, with German and French chocolate manufacturers absorbing cost premiums for clean-label positioning.
- Palm Oil Emulsifiers:Interesterified palm fractions deliver HLB-tunable performance for industrial margarine systems, with Malaysian and Indonesian refining clusters supplying Asian bakery processors.
- Egg Yolk Powder:Spray-dried phospholipid concentrates from avian sources command niche positioning in mayonnaise and hollandaise applications where emulsion stability under thermal stress is non-negotiable.
The dominant share belongs to soy lecithin, while sunflower lecithin is closing the gap fastest.
Application:
Formulation viscosity and thermal processing intensity create divergent technical requirements across food manufacturing segments.
- Baking:Laminated dough systems and cake aeration demand emulsifiers with precise HLB balancing for fat-protein interface stabilization. U.S. clean-label bakery chains are consolidating procurement through direct supplier partnerships to compress 24-month reformulation cycles.
- Dairy Products:Plant-based oat and almond milk processors require sophisticated emulsification to prevent fat separation during UHT treatment. Netherlands and Denmark lead technical-grade consumption as dairy alternative innovation clusters concentrate formulation expertise.
- Sauces:Cold-process emulsions in mayonnaise and dressings prioritize phospholipid-based systems over synthetic alternatives for label simplicity.
- Dressings:Vinaigrette stability under refrigerated distribution favors lecithin blends with modified starch synergists for extended shelf life.
Baking commands volume leadership, though dairy applications are expanding most quickly as plant-based alternatives proliferate.
End User:
Technical sophistication and reformulation autonomy separate large-scale manufacturers from service-dependent operators.
- Food Manufacturers:Integrated R&D facilities enable direct emulsifier specification and supplier co-development agreements. Cargill and BASF SE embed technical staff in customer labs to accelerate clean-label transitions.
- Beverage Producers:Plant-based milk specialists in California and Illinois drive phospholipase-modified lecithin demand for protein-fat matrix stabilization.
- Bakery Chains:Regional clean-label players in France and Germany consolidate procurement through formulation service contracts rather than spot purchasing.
- Catering Services:Cost-sensitive institutional buyers rely on distributor-blended emulsifier systems with limited specification control.
Food manufacturers retain procurement volume dominance, while beverage producers are gaining share fastest through alternative protein expansion.
Distribution Channel:
Supply chain configuration separates technical-grade direct relationships from commodity spot markets.
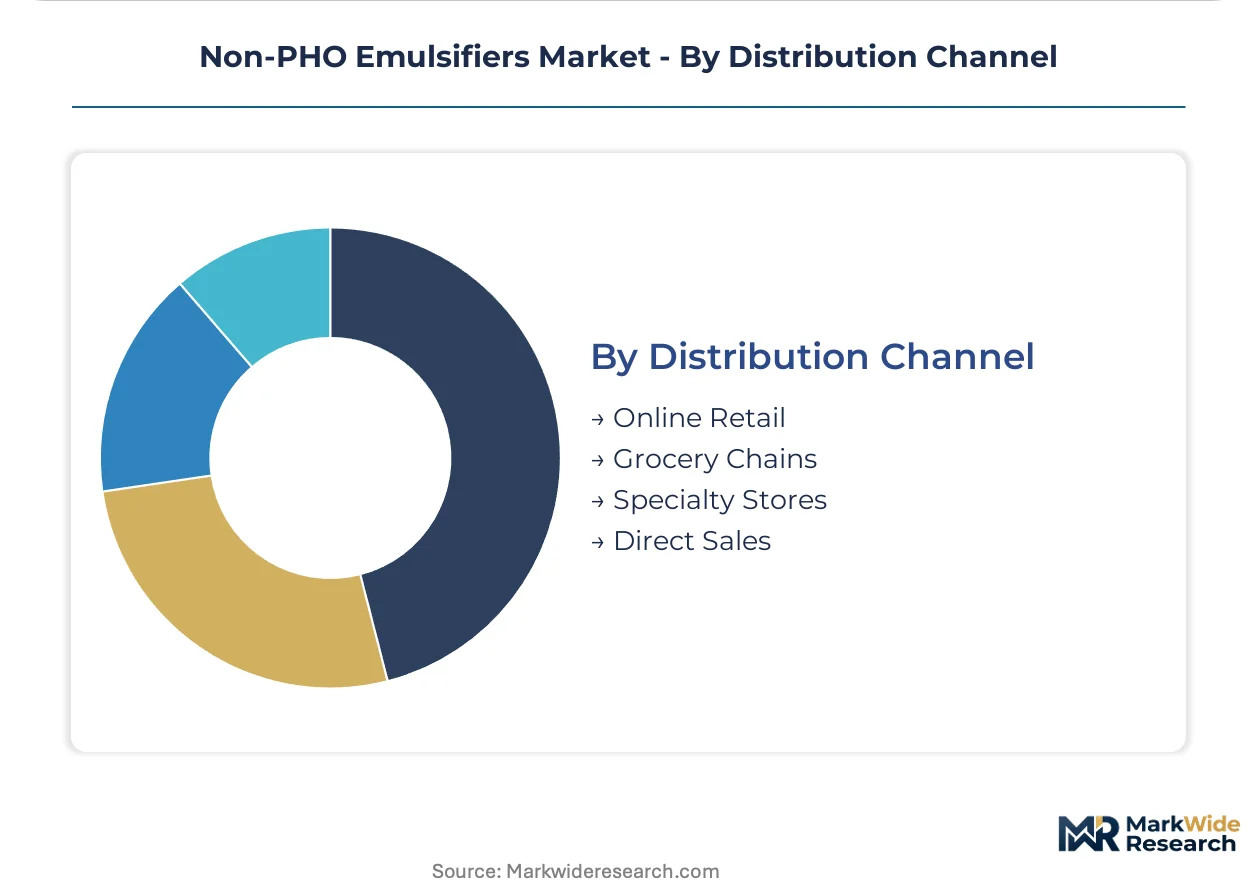
- Direct Sales:High-volume bakery and dairy manufacturers in the United States and Germany bypass distribution tiers for enzymatically modified lecithin with embedded formulation support.
- Grocery Chains:Private-label food manufacturers procure standard-grade emulsifiers through consolidated ingredient distributors with regional warehousing.
- Specialty Stores:Artisan bakery suppliers and allergen-sensitive formulators source non-GMO sunflower lecithin through certified ingredient brokers.
- Online Retail:Small-scale food entrepreneurs access packaged lecithin powders through B2B platforms with technical documentation portals.
Direct sales anchor volume throughput, though online retail is climbing the fastest as micro-manufacturer formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across major demand centers. German and French buyers absorb sunflower lecithin premiums for clean-label positioning, while U.S. baking conglomerates prioritize soy-derived volume economics. Indian and Brazilian processors exhibit intermediate sensitivity, trading certification depth against reformulation speed.
United States
FDA trans-fat labeling enforcement drives PHO replacement programs among clean-label bakery chains. The agency's 2015 determination that partially hydrogenated oils are not generally recognized as safe compresses formulation timelines. Illinois and California host concentrated alternative protein innovation clusters where beverage processors demand phospholipase-modified lecithin for oat milk stabilization.
Germany
EFSA guidance on sustainable palm alternatives shapes supplier qualification criteria for chocolate manufacturers. The EU F-Gas Regulation mandates processing equipment upgrades for emissions control. Baden-Württemberg and Bavaria anchor European non-GMO lecithin supply through specialized sunflower crushing infrastructure.
France
Premium confectionery producers prioritize cold-pressed sunflower lecithin for neutral flavor profiles. EFSA novel food evaluations extend authorization timelines for microbial-derived emulsifier sources. Paris and Lyon metropolitan areas concentrate enzymatic modification expertise for high-performance bakery applications.
India
FSSAI clean-label adoption accelerates ahead of anticipated trans-fat limits in packaged foods. Processed food manufacturers in Maharashtra and Gujarat initiate PHO reformulation programs. Mumbai and Ahmedabad industrial corridors attract technical-grade emulsifier distributors establishing regional formulation support centers.
Brazil
Soy crushing infrastructure dominance supports volume supply for regional baking operations. ANVISA regulatory alignment with Codex standards shapes import qualification requirements. São Paulo state anchors South American emulsifier distribution networks serving Mercosur processed food manufacturers.
Non-PHO Emulsifiers Market Competitive Landscape
Integrated agribusiness conglomerates and specialized ingredient technology firms split the market along vertical integration depth. The structure consolidates around three tiers: oilseed processors with captive lecithin streams, enzymatic modification specialists, and application-focused formulation service providers. Dominant competitive moves include backward integration into oilseed crushing and forward embedding of technical staff in customer R&D facilities.
Within the integrated processing tier, Cargill and Archer Daniels Midland occupy positions anchored by North American and South American oilseed networks. BASF SE represents the enzymatic modification archetype through European-based phospholipase capabilities. Kerry Group exemplifies the formulation service model, competing on clean-label application expertise rather than commodity supply alone.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Ingredion Incorporated |
| Kerry Group |
| DuPont Nutrition & Biosciences |
| Corbion |
| BASF SE |
| Palsgaard |
| Tate & Lyle |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp barge freight corridors transmit Black Sea sunflower seed volatility directly into European lecithin spot markets, compressing margins for traders while amplifying price spreads between non-GMO certified and standard grades.
Pricing Analysis
After-sales formulation support contracts now generate more lifetime value than base ingredient sales for enzymatic modification specialists. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and HLB performance specification. Cost compression in commodity soy lecithin is intensifying because Argentine crushing overcapacity floods spot markets. Large U.S. baking conglomerates exhibit lowest price sensitivity, absorbing sunflower premiums for clean-label positioning, while Indian institutional buyers remain most price-sensitive.
Supply Chain Analysis
Extended payment terms from German chocolate manufacturers now finance upstream Ukrainian sunflower crushing operations through supply-chain finance facilities anchored in Frankfurt banking networks. Supply concentrates in Argentina, Brazil, and Ukraine for oilseed inputs, with enzymatic modification capacity clustering in Germany and Netherlands. The chain draws from phospholipid-rich degumming streams, specialized phospholipase enzymes, and HLB-tuning fractionation equipment. Single-source vulnerability runs through Black Sea seed supply. Distribution runs through direct technical partnerships for high-performance grades and regional distributors for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large clean-label bakery chains as they consolidate procurement through dedicated formulation partnerships rather than fragmented spot purchasing.
For Market Incumbents: Insulate margin position by deepening backward integration into non-GMO sunflower crushing in Baden-Württemberg and Bavaria, countering Black Sea supply volatility. Accelerate phospholipase modification capacity expansion ahead of EFSA novel food clearance timelines for microbial-derived alternatives, neutralizing biotechnology entrant threats. For New Entrants and Emerging Players: Maharashtra and Gujarat processed food corridors represent underpenetrated demand pockets where FSSAI trans-fat anticipation drives PHO reformulation urgency. Target beverage-grade phospholipase-modified lecithin for plant-based dairy processors in these clusters, offering embedded formulation support to bypass established distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oilseed processors seeking to divest non-core specialty ingredients divisions. Long-term viability hinges on enzymatic modification capabilities and direct customer embedding depth. Watch EFSA authorization timelines for precision fermentation lipids as inflection signals for biotechnology substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sunflower Crushing | Cargill's North American oilseed network secures non-GMO lecithin streams against Black Sea volatility. |
| Phospholipase Modification Capacity Expansion | BASF SE anchors European high-performance supply through enzymatic HLB tuning for laminated dough applications. |
| Direct Customer R&D Embedding | Kerry Group displaces traditional distribution by placing technical staff inside bakery and dairy formulation labs. |
| Clean-Label Certification Investment | Non-GMO Project and organic accreditation compress supplier qualification cycles for premium positioning. |
| Regional Formulation Support Centers | Technical-grade distributors establish Mumbai and Ahmedabad facilities to capture FSSAI-driven reformulation demand. |
Research Methodology
The analysis maps soy lecithin, sunflower lecithin, palm oil emulsifiers, and enzymatic modification sub-sectors, each validated through plant managers at crushing facilities, procurement leads at bakery and dairy manufacturers, distribution channel partners, and technical R&D directors. Primary interviews triangulate with secondary sources including FDA trans-fat enforcement documentation, EFSA novel food evaluation registers, EU F-Gas Regulation compliance filings, and customs trade data. Bottom-up volume modeling and top-down value reconciliation cross-validate segment outputs.
Assumptions held fixed include FDA trans-fat labeling enforcement trajectories and EFSA guidance continuity on sustainable palm alternatives, while Black Sea supply disruption frequency and enzymatic process yield improvements were varied across sensitivity scenarios. Segmentation dimensions modeled encompass extraction source, modification intensity, application viscosity requirements, and end-user technical sophistication. CAGRs derive from regression against historical volume elasticities and substitution rate assumptions. Forecast inputs include sunflower seed price volatility indices and plant-based dairy formulation adoption curves.
Practitioners should monitor EFSA authorization delays for precision fermentation lipids and FSSAI trans-fat limit announcements for early signals of demand inflection. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Global Fatty Acids Market