
 Yeast Peptide Market | 2026-2036
Yeast Peptide Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast Peptide Market Analytics
Pharmaceutical firms is reorganizing procurement priorities for yeast-derived bioactive ingredients, pulling volume away from legacy food and beverage buyers. Angel Yeast Co., Ltd. anchors production scale across Asia-Pacific fermentation corridors. Kerry Group plc differentiates through integrated extraction-to-formulation capabilities in Europe and North America. Lesaffre Group sustains decades of strain-development expertise that underpins consistent peptide yield profiles.
Yeast peptides comprise short-chain amino acid sequences liberated through controlled enzymatic hydrolysis of Saccharomyces cerevisiae cell walls, typically yielding fractions between 500 and 10,000 daltons with standardized degrees of hydrolysis. These bioactive fractions serve as functional precursors for umami enhancement, immunomodulation, and cell-signaling applications across regulated industries. Hydrolyzed yeast occupies the largest existing volume position due to mature flavor-house demand, while yeast beta-glucans commands premium positioning in pharmaceutical and cosmeceutical channels where immunomodulatory claims require rigorous substantiation. Powder form dominates industrial handling efficiency, though liquid concentrates gain traction in automated beverage and feed-manufacturing lines.
FDA oversight of GRAS self-affirmation and new dietary ingredient notifications shapes US market entry timelines for novel yeast peptide isolates, while EFSA Novel Food catalog requirements govern European commercialization pathways. China's NMPA and SAMR jointly enforce biotech-sourced ingredient registration rules that increasingly align with GB standard revisions for peptide purity thresholds. Stakeholders must track divergent regulatory clocks across these jurisdictions to avoid pipeline delays that compound formulation development costs.
Market Dynamics
Pharmaceutical procurement cycles now compress from 18-month horizons to 90-day sprints for bioactive yeast fractions, forcing fermentation capacity to reconfigure around just-in-time peptide isolation rather than bulk flavor-house contracts.
Growth Catalysts
- China's NMPA-SAMR peptide purity mandates:GB standard revisions for biotech-derived ingredients create compliance-driven replacement cycles across domestic nutraceutical formulators.
- Enzymatic hydrolysis precision gains:Controlled degree-of-hydrolysis targeting now yields 500-10,000 dalton fractions with reproducible immunomodulatory markers.
- Germany's industrial cluster density:Hamburg and Frankfurt corridor concentration enables shared fermentation infrastructure and cross-facility strain optimization.
Market Restraints
- Saccharomyces cerevisiae feedstock volatility:Molasses and corn steep liquor prices swing with Brazilian sugarcane harvest cycles and US ethanol policy.
- Single-source strain dependency:Proprietary yeast lineages locked behind decades of Lesaffre and Angel Yeast breeding programs limit second-source qualification.
- EFSA Novel Food catalog backlog:Immunomodulatory claim substantiation timelines stretch 18-24 months for new peptide isolates.
Strategic Opportunities
- Automated beverage manufacturing integration:Liquid concentrate formats bypass powder handling infrastructure for mid-scale functional drink producers.
- Cosmeceutical channel expansion:Topical cell-signaling applications bypass oral-delivery GRAS requirements through dermal absorption pathways.
- US IRA biomanufacturing incentives:Domestic fermentation tax credits offset capital intensity for greenfield peptide isolation facilities.
Industry Challenges
- Peptide analytics talent scarcity:Mass spectrometry and bioassay validation expertise concentrates in pharmaceutical hubs, leaving food-grade labs understaffed.
- Dual-use facility qualification:GMP-grade peptide isolation requires cleanroom retrofitting that conflicts with existing flavor-house hygiene zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast Peptide Market |
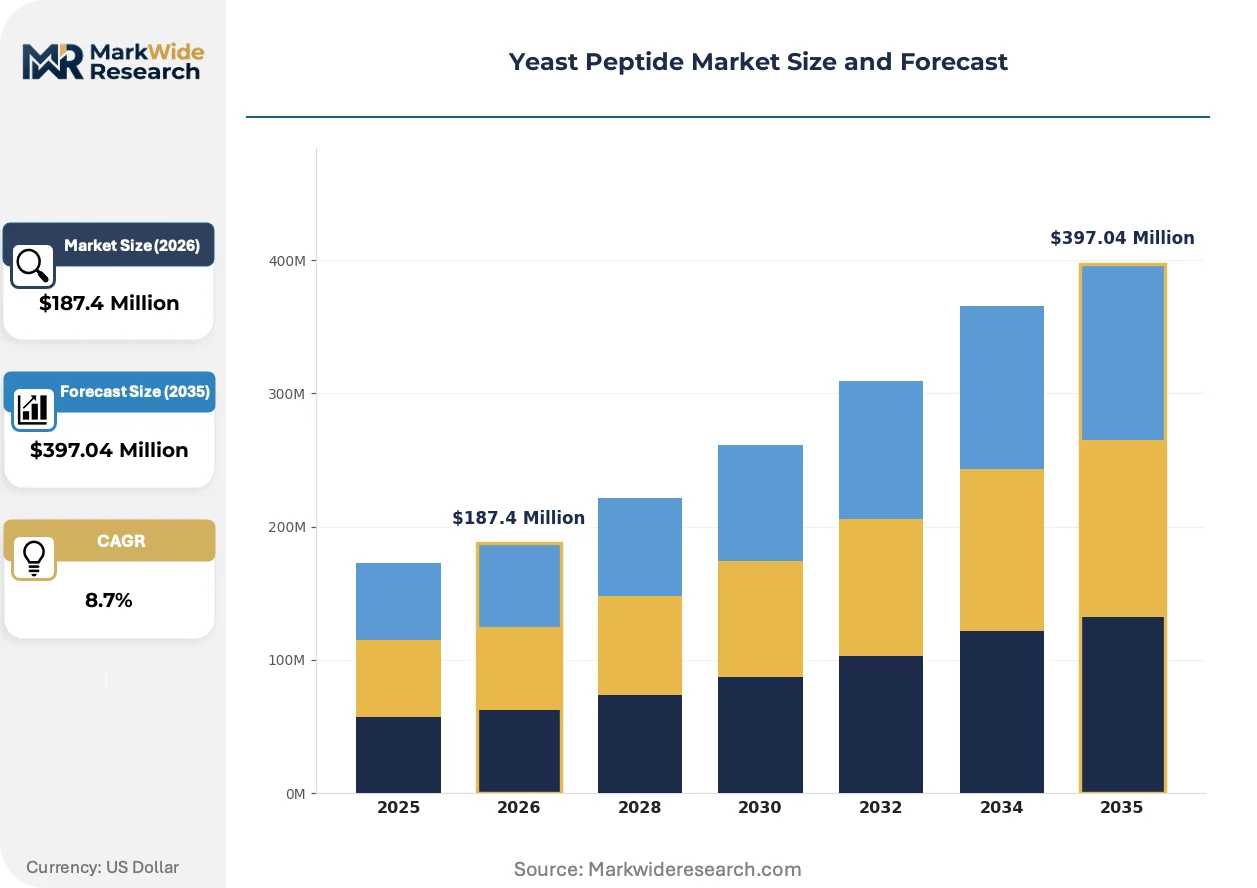
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Yeast, Yeast Extract, Yeast Protein, Yeast Beta-Glucans Application: Food & Beverage, Pharmaceuticals, Cosmetics, Animal Nutrition End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Animal Feed Producers Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Angel Yeast Co., Ltd., Lesaffre Group, Kerry Group plc, Lallemand Inc., AB Mauri, Leiber GmbH, DSM Nutritional Products, Ohly GmbH, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast Peptide Market Evolving Landscape
Precision fermentation and enzymatic engineering are collapsing the traditional boundary between commodity hydrolyzed yeast and high-value beta-glucan isolates, creating intermediate peptide grades that challenge established pricing hierarchies.
Membrane filtration cascades is fragmenting the standardized 500-10,000 dalton window into narrower subfractions with targeted bioactivity signatures. Pharmaceutical formulators now specify exact molecular weight cutoffs for toll-manufactured batches. This capability compression erodes the volume advantage of legacy hydrolyzed yeast producers who optimized for broad-spectrum flavor enhancement.
EFSA's expanding Novel Food catalog requirements now demand peptide-specific toxicology dossiers separate from parent yeast safety data. European commercialization timelines for immunomodulatory claims have extended by eight to fourteen months. German and Dutch ingredient houses are pre-submitting master files to compress subsequent product-specific approvals.
Buyer concentration among multinational pharmaceutical procurement consortia is compressing supplier negotiation cycles from annual frameworks to quarterly volume commitments. Food and beverage manufacturers now face allocation priority tiers that relegate their orders to spot-market pricing. This channel bifurcation is most visible in North American and Western European supply agreements where pharma offtake guarantees secure fixed fermentation slots.
Yeast Peptide Market Segmentation
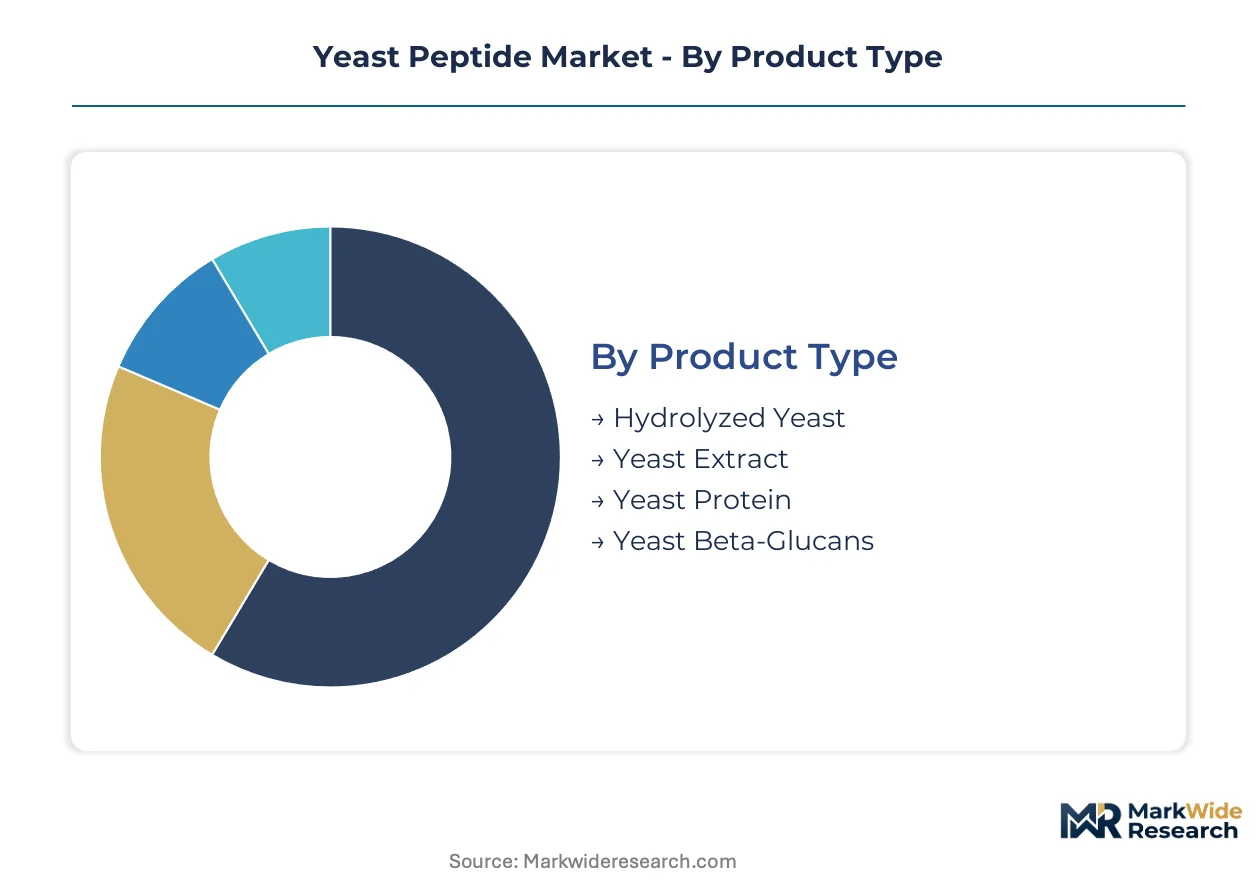
Yeast peptide suppliers face divergent technical specifications across end-use channels, forcing fermentation facilities to maintain parallel isolation trains. Pharmaceutical-grade fractions command purity thresholds that legacy food-grade infrastructure cannot achieve without capital-intensive retrofitting.
Product Type:
Hydrolyzed yeast dominates domestic procurement cycles across established flavor-house networks, while yeast beta-glucans drive export-led pharmaceutical offtake to North American and European immunotherapy formulators.
- Hydrolyzed Yeast:Broad-spectrum amino acid fractions produced through non-specific enzymatic hydrolysis, typically standardized for umami intensity rather than bioactivity markers. Demand concentrates in domestic food manufacturing corridors where mature toll-processing agreements lock in volume commitments. Molasses feedstock volatility from Brazilian harvest cycles squeezes margin predictability for producers lacking long-term supply contracts.
- Yeast Beta-Glucans:Purified (1,3)-(1,6)-D-glucan polymers extracted through alkaline-enzymatic processing with validated immunomodulatory potency. Export-led demand clusters in German pharmaceutical clusters around Hamburg, where toll manufacturers service EFSA-regulated immunotherapy developers. NMPA-SAMR purity mandates in China are accelerating domestic substitution investments that threaten established import flows.
- Yeast Extract:Concentrated soluble fractions retaining nucleotides and peptides for savory flavor modulation, primarily serving processed food manufacturers in mature Western European markets.
- Yeast Protein:Isolated protein concentrates competing with plant-based alternatives in alternative protein formulations, gaining traction in automated beverage manufacturing lines.
Hydrolyzed yeast commands the established base. The steepest expansion runs through yeast beta-glucans.
Application:
Cost tier stratification separates commodity flavor applications from premium pharmaceutical channels, with cosmetics occupying an intermediate positioning that leverages dermal absorption pathways to bypass oral-delivery regulatory burdens.
- Food & Beverage:Mature demand channel anchored by processed meat, savory snack, and instant noodle manufacturers seeking cost-efficient umami enhancement. Volume concentrates in industrial clusters with shared fermentation infrastructure, particularly around Frankfurt's integrated ingredient processing corridor. EFSA Novel Food catalog requirements now extend timelines for new peptide isolates by eight to fourteen months.
- Pharmaceuticals:High-margin channel demanding GMP-grade isolation with validated bioactivity markers and batch-to-batch reproducibility. Procurement cycles have compressed from eighteen-month horizons to ninety-day sprints, forcing suppliers to maintain dedicated peptide isolation capacity. US IRA biomanufacturing tax credits are redirecting greenfield investment toward domestic fermentation facilities.
- Cosmetics:Topical cell-signaling applications exploiting dermal absorption pathways to circumvent GRAS self-affirmation requirements, with demand clustering in South Korean and French cosmeceutical formulators.
- Animal Nutrition:Feed-grade peptide fractions for gut health modulation in poultry and aquaculture, primarily serving Southeast Asian integrated protein producers.
Food and beverage absorbs the volume base. Pharmaceuticals deliver the margin expansion trajectory.
End User:
Customer-type concentration has shifted dramatically as pharmaceutical procurement consortia secure fixed fermentation slots through quarterly volume commitments, relegating legacy food manufacturers to spot-market pricing tiers.
- Food Manufacturers:Established buyers of hydrolyzed yeast and yeast extract for processed food applications, now facing allocation priority downgrades as pharmaceutical offtake guarantees absorb available capacity. Procurement teams are exploring liquid concentrate formats to bypass powder handling infrastructure constraints.
- Pharmaceutical Firms:Rapidly consolidating buyers of immunomodulatory peptide fractions, driving specification precision toward exact molecular weight cutoffs. German and Dutch ingredient houses are pre-submitting master files to EFSA to compress subsequent product-specific approvals.
- Cosmetic Companies:Formulators of topical anti-aging and barrier-repair products, sourcing through specialized distributors with cosmetic GMP certification.
- Animal Feed Producers:Volume buyers of standardized hydrolyzed yeast for gut health applications, concentrated in Vietnamese and Indonesian aquaculture operations.
Food manufacturers retain the volume foundation. Pharmaceutical firms capture the prioritization premium.
Form:
Supply concentration favors powder handling infrastructure in established fermentation corridors, while liquid formats gain adoption in automated manufacturing environments seeking to eliminate dust exposure and weighing variability.
- Powder:Dominant industrial format optimized for shelf stability, bulk handling efficiency, and established logistics networks. Mature demand across food manufacturing and pharmaceutical tableting operations, with production gravity centering on Angel Yeast's Asia-Pacific fermentation corridors and Lesaffre's European facilities.
- Liquid:Concentrated solutions gaining traction in automated beverage manufacturing and mid-scale functional drink producers seeking to bypass powder reconstitution steps. German industrial clusters around Hamburg are pioneering integrated liquid-to-bottle processing lines.
- Granular:Free-flowing agglomerated particles for direct compression tableting in pharmaceutical applications, requiring specialized spray-drying capacity.
- Paste:High-moisture format for artisanal food applications and specialized cosmetic compounding, serving niche European and Japanese formulators.
Powder commands the infrastructure base. Liquid formats deliver the automation adaptation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container terminals handle the bulk of yeast peptide feedstock imports into Central Europe, underwriting Germany's dominance in pharmaceutical-grade fermentation infrastructure.
Germany
Pharmaceutical procurement consortia in Hamburg and Frankfurt drive demand for immunomodulatory beta-glucan fractions. EFSA Novel Food catalog requirements extend approval timelines for new peptide isolates. The Hamburg industrial corridor hosts shared fermentation infrastructure enabling cross-facility strain optimization.
China
Domestic nutraceutical formulators face compliance-driven replacement cycles under NMPA-SAMR peptide purity mandates. GB standard revisions for biotech-derived ingredients tighten registration rules. Yangtze River Delta fermentation clusters around Shanghai anchor Angel Yeast's production scale.
United States
IRA biomanufacturing tax credits redirect greenfield investment toward domestic peptide isolation facilities. FDA GRAS self-affirmation pathways shape market entry timelines for novel isolates. Midwest ethanol policy volatility disrupts Saccharomyces cerevisiae feedstock pricing.
France
Cosmeceutical formulators in Paris and Lyon exploit dermal absorption pathways to bypass oral-delivery regulatory burdens. ANSM enforces cosmetic GMP certification for topical peptide suppliers. The Île-de-France region concentrates specialized distributors serving anti-aging product developers.
India
CDSCO registration requirements for biotech-sourced ingredients create entry barriers for imported yeast peptides. FSSAI standards govern food-grade hydrolyzed yeast deployment in processed food manufacturing. Maharashtra's pharmaceutical corridors attract toll-manufacturing partnerships.
Yeast Peptide Market Competitive Landscape
Concentration sits with integrated fermentation specialists who control strain development, enzymatic hydrolysis, and downstream isolation under single ownership. The market structure tiers across legacy yeast producers, diversified ingredient houses, and emerging precision fermentation entrants. Three archetypes dominate: strain-heritage players with decades of breeding programs, extraction-to-formulation integrators, and toll-manufacturing specialists serving pharmaceutical qualification requirements. Capacity expansion and backward integration into captive molasses supply represent the dominant competitive moves.
Among Asia-Pacific-based fermentation specialists, Angel Yeast Co., Ltd. anchors production scale across regional corridors. Lesaffre Group exemplifies the strain-heritage archetype with proprietary yeast lineages underpinning consistent peptide yield profiles. Kerry Group plc occupies a position as an extraction-to-formulation integrator with capabilities spanning Europe and North America.
| Leading Market Players |
|---|
| Angel Yeast Co., Ltd. |
| Lesaffre Group |
| Kerry Group plc |
| Lallemand Inc. |
| AB Mauri |
| Leiber GmbH |
| DSM Nutritional Products |
| Ohly GmbH |
| Sensient Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Fermentation capacity utilization above 85% at Angel Yeast's Yangtze River Delta facilities anchors price floors across pharmaceutical-grade peptide tiers, concentrating supply-side leverage among heritage strain developers while compressing margins for toll-dependent flavor houses. This scale asymmetry forces second-tier hydrolyzed yeast producers into spot-market molasses procurement that amplifies feedstock cost volatility.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade beta-glucans, food-grade hydrolyzed yeast, and feed-standard fractions reflects certification-grade differentiation and volume-commitment scale. Price differentiation hinges on GMP-grade isolation infrastructure and EFSA Novel Food catalog pre-submission status, with pharmaceutical procurement consortia locking annual contracts while food manufacturers absorb spot-market premiums. Cost compression in hydrolyzed yeast intensifies because Brazilian molasses supply contracts face ethanol policy diversion. Animal feed producers exhibit highest price sensitivity due to undifferentiated peptide specifications, whereas immunotherapy formulators prioritize batch-to-batch reproducibility over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites molasses feedstock flows from Brazilian sugarcane crushers to Yangtze River Delta fermentation corridors, creating chokepoint exposure for Asia-Pacific peptide isolation. Geographic supply concentration clusters in China, Germany, and France, with Hamburg's container terminals anchoring European pharmaceutical-grade distribution. Raw material dependencies center on Brazilian molasses, corn steep liquor from US ethanol plants, and specialized enzymatic hydrolysis reagents. Single-source strain vulnerability from Lesaffre and Angel Yeast proprietary lineages threatens second-source qualification timelines. Distribution runs through integrated fermentation specialists with captive extraction-to-formulation capabilities rather than merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where decades of strain-development heritage and EFSA Novel Food master file accumulation create switching costs that pharmaceutical procurement consortia cannot readily replicate with new suppliers.
For Market Incumbents: Fortify strain-heritage advantages through backward integration into captive molasses supply contracts in Brazil and Uruguay, insulating against US ethanol policy volatility. Expand GMP-grade cleanroom retrofitting at Hamburg and Frankfurt facilities to capture compressed 90-day pharmaceutical procurement cycles before precision fermentation entrants achieve comparable peptide yield profiles. For New Entrants and Emerging Players: EFSA Novel Food fast-track pre-submission protocols offer the most penetrable regulatory pathway for immunomodulatory beta-glucan fractions targeting German pharmaceutical clusters. Liquid concentrate formats for automated beverage manufacturing bypass powder-handling infrastructure investments that incumbent flavor houses cannot readily abandon, enabling white-space entry through equipment-light value propositions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated extraction-to-formulation specialists with established EFSA master files over pure-play fermentation capacity. Long-term viability across the analysis window hinges on regulatory entrenchment depth rather than scale alone. The inflection signal to monitor is NMPA-SAMR domestic substitution investment velocity that threatens established import flows into Chinese nutraceutical formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Molasses Supply | Long-term Brazilian supply contracts insulate Angel Yeast and Lesaffre from US ethanol policy swings. |
| GMP-Grade Cleanroom Retrofitting | Hamburg facility upgrades enable 90-day pharmaceutical procurement cycle capture versus 18-month legacy timelines. |
| EFSA Novel Food Master File Pre-Submission | German and Dutch ingredient houses compress eight-to-fourteen-month approval extensions for immunomodulatory claims. |
| Liquid Concentrate Format Development | Automated beverage manufacturing integration bypasses powder-handling infrastructure for mid-scale functional drink producers. |
| Precision Fermentation Capacity Buildout | US IRA biomanufacturing tax credits offset capital intensity for domestic peptide isolation greenfield investments. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, pharmaceutical procurement directors, regulatory affairs specialists at EFSA-notified bodies, and flavor-house R&D directors, then refined through secondary validation against NMPA-SAMR registration databases, EFSA Novel Food catalog submissions, US FDA GRAS notification filings, and Brazilian customs export records. Bottom-up capacity utilization estimates from Yangtze River Delta and Hamburg industrial corridors were triangulated against top-down peptide fraction demand projections from immunotherapy formulators.
Variance decomposition across product type, application channel, end-user concentration, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand modeling that weighted pharmaceutical procurement cycle compression against food-grade spot-market volatility. Industry-specific forecast inputs incorporated molasses futures curve sensitivity and EFSA approval timeline distributions from master file pre-submission patterns.
Underlying assumptions cover sustained NMPA-SAMR enforcement intensity, stable Brazilian sugarcane harvest cycles, and continued IRA biomanufacturing credit availability, with deviation risk concentrated in single-source strain dependency and EFSA catalog backlog extensions. Practitioners should keep alternative scenarios live as Chinese domestic substitution investments and precision fermentation yield improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Gymnema Extract Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
North America Dairy Protein Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Wheat Starch Market
Ingredients
Pomace Olive Oil Market
Ingredients
Pea Starch Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Fucoidan Extract Market
Ingredients
Tomato Concentrate Market
Ingredients
Honey Powder Market