

Food Grade Cassia Gum Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Cassia Gum Powder Market Insights
Aftermarket technical service revenue is tilting toward formulation support and regulatory compliance consulting. Agro Gums leverages its Gujarat-based processing infrastructure to dominate bulk supply contracts with multinational food manufacturers. Altrafine Gums differentiates through specialized organic grade certifications that sustain premium positioning in European dairy applications. Avlast Hydrocolloids competes on backward integration into cassia seed crushing, which anchors cost control across volatile raw material cycles.
Food grade cassia gum powder is the purified endosperm flour of Cassia tora seeds, containing minimum 75% galactomannan with controlled viscosity between 2,000–3,500 cps for consistent gelling performance. It functions primarily as a thickener, water-binding agent, and texture stabilizer in processed foods requiring moisture retention and freeze-thaw stability. Standard grade occupies the volume base in meat processing and cost-sensitive bakery segments where functional performance thresholds are moderate. Organic grade commands expanding placement in dairy products and infant nutrition lines as EU Green Deal sourcing requirements tighten supply chain documentation. Modified grade, though smaller in current volume, leads margin pools through customized cross-linked variants for high-shear beverage applications.
FDA food additive regulations under 21 CFR 172.655 govern cassia gum's permitted use levels in US meat and poultry products, while FSSAI standards in India enforce purity specifications for export-grade material. EFSA evaluations of cassia gum as a food additive in the EU create compliance gatekeeping that filters out uncertified processors. REACH registration obligations for imported gum derivatives into Europe further shape supplier qualification requirements. Stakeholders must monitor evolving clean-label certification demands and dual-track their supply chains between conventional and organic grade capacity.
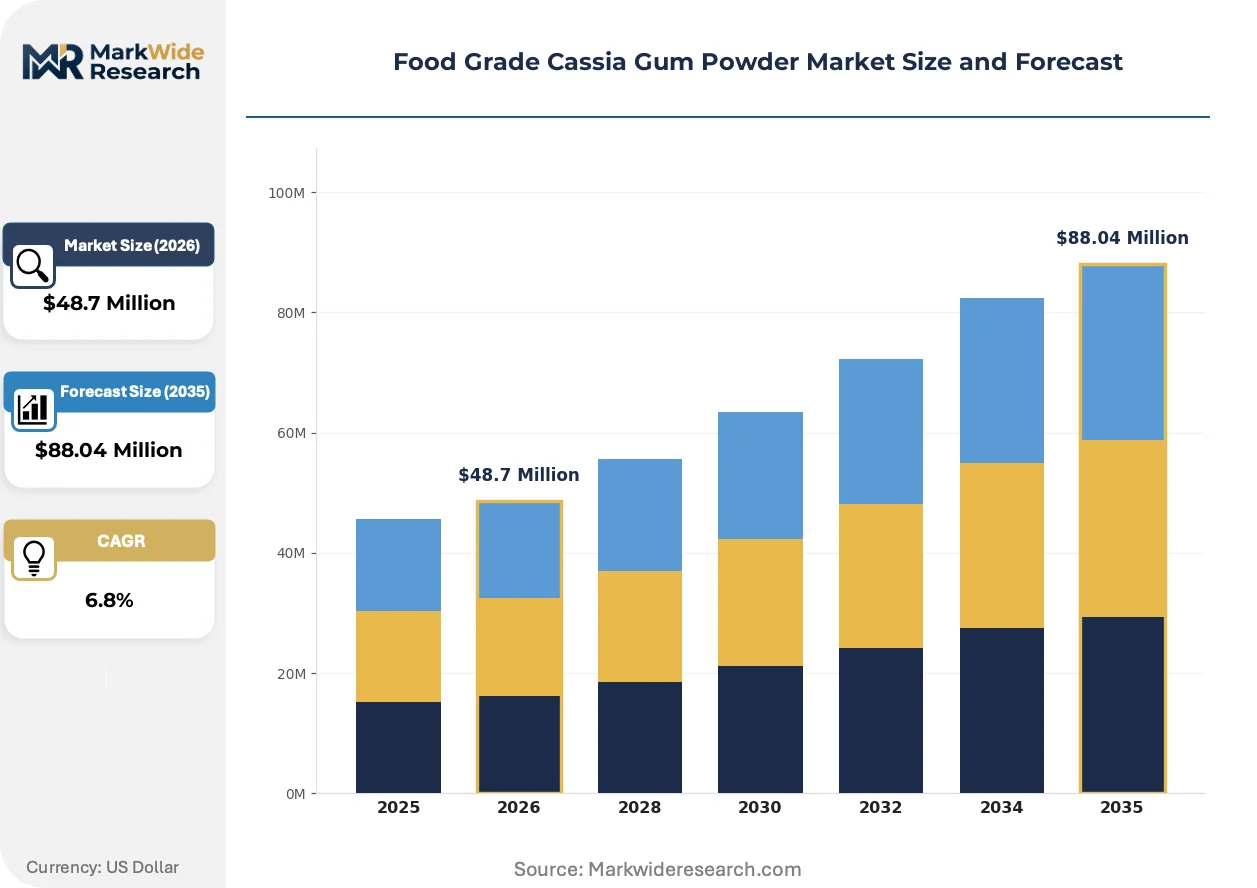
Market Dynamics
India's dominance in cassia seed crushing and purification infrastructure concentrates supply-side leverage among Gujarat-based processors, while EU Green Deal documentation requirements and FSSAI export purity standards are bifurcating procurement channels between conventional and certified-organic grades.
Growth Catalysts
- EU Green Deal sourcing mandates:Dairy and infant nutrition manufacturers across Germany, France, and the Netherlands now require documented sustainable supply chains, pulling organic-certified cassia gum into premium formulation slots previously held by locust bean gum.
- Wet pet food stabilization demand:Pet food manufacturers in the United States are expanding cassia gum usage as a gelling agent in gravy-based formulations, displacing carrageenan in clean-label repositioning efforts.
- Seed-to-powder traceability infrastructure:Blockchain-enabled lot tracking systems deployed by Indian processors are unlocking export contracts with Japanese and South Korean food manufacturers previously blocked by documentation gaps.
Market Restraints
- Cassia tora seed price volatility:Monsoon-dependent harvests across Rajasthan and Gujarat create input cost swings of 20-35% within single growing cycles, compressing processor margins and destabilizing contract pricing.
- Single-origin supply concentration:Over 80% of global cassia gum purification capacity sits within 200 kilometers of Ahmedabad, creating geographic risk exposure to regional logistics disruptions or regulatory enforcement actions.
- REACH registration friction:European chemical safety documentation requirements for imported gum derivatives filter out uncertified Indian processors, limiting qualified supplier pools and extending procurement lead times.
Strategic Opportunities
- Clean-label meat processing in Brazil:ANVISA's evolving food additive standards are opening formulation trials for cassia gum in processed poultry applications, creating first-mover positioning for exporters with Portuguese-language technical support capabilities.
- Cross-linked modified grade development:High-shear beverage applications in energy drinks and ready-to-drink coffee are driving demand for customized viscosity profiles that command 40-60% price premiums over standard grades.
- Direct-to-manufacturer digital platforms:Indian processors are bypassing traditional gum traders through B2B marketplaces, capturing margin previously lost to Rotterdam and Hamburg-based distributors.
Industry Challenges
- Galactomannan assay standardization:Inconsistent viscosity testing protocols between FSSAI laboratories and private European certifiers create batch rejection disputes, requiring duplicate analytical work and delaying shipments.
- Organic certification timeline compression:EU organic conversion periods and India Organic NPOP audits extend qualification cycles to 18-24 months, straining working capital for processors expanding certified capacity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Cassia Gum Powder Market Trends and Innovations
Formulation science and supply chain documentation are converging to reshape competitive positioning, with technology vendors and certification bodies now co-determining market access rather than operating in separate spheres.
Enzymatic purification technology is hybridizing traditional mechanical seed splitting with targeted polysaccharide refinement, enabling processors to achieve 85%+ galactomannan purity without the solvent residues that trigger EU contaminant thresholds. Mid-sized Indian manufacturers with fermentation partnerships are deploying these systems ahead of large integrated players. The technology is compressing the cost gap between standard and premium grades while raising baseline purity expectations across import specifications.
EFSA's 2023 updated guidance on food additive purity criteria is tightening heavy metal and microbiological limits for cassia gum entering European dairy applications. The regulation is forcing Indian exporters to invest in HACCP-aligned processing lines and third-party laboratory relationships that smaller crushers cannot afford. Organic-certified processors with existing EU organic regulatory compliance infrastructure are absorbing displaced conventional volume as qualified supplier pools contract.
Specification-driven procurement is replacing spot-market purchasing among multinational food manufacturers, with annual contracts now locking in 12-18 month viscosity stability guarantees and documented seed origin traceability. Technical service teams at ingredient distributors are being disintermediated as buyers demand direct processor relationships for formulation troubleshooting. This pattern is most visible in German and Dutch dairy conglomerates consolidating supplier panels to three qualified partners per region.
Food Grade Cassia Gum Powder Market Segmentation
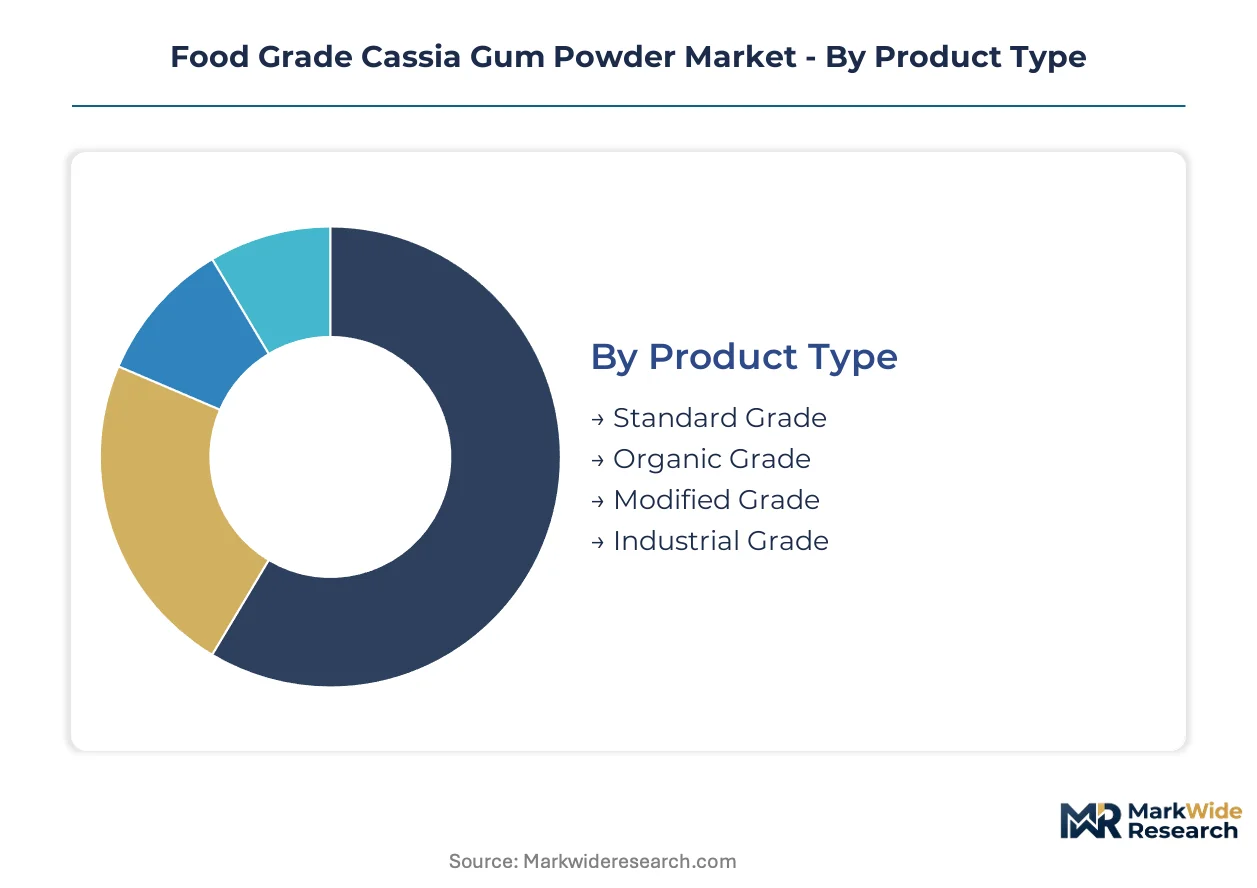
Segmentation in cassia gum powder reveals how technical specifications and certification tiers fragment procurement channels. Food manufacturers now route purchases through parallel supply chains based on end-use compliance requirements rather than consolidating around a single grade.
Product Type:
After-sales service intensity varies sharply across product tiers, with modified grade demanding formulation troubleshooting and organic grade requiring audit documentation support.
- Standard Grade:Contains minimum 75% galactomannan with viscosity between 2,000–3,500 cps, serving as the baseline thickener for cost-sensitive meat processing and bakery applications. Demand concentrates in Indian domestic meat processing and Southeast Asian noodle manufacturing where FSSAI purity specifications anchor procurement decisions.
- Organic Grade:Carries EU organic and India Organic NPOP certifications with full seed-to-powder traceability documentation. Dairy manufacturers across Germany, France, and the Netherlands now mandate this grade for infant nutrition lines as EU Green Deal sourcing requirements displace conventional locust bean gum.
- Modified Grade:Cross-linked variants engineered for high-shear beverage applications command 40-60% price premiums through customized viscosity profiles.
- Industrial Grade:Falls outside food-grade purity thresholds, serving non-food applications with lower galactomannan requirements and minimal regulatory documentation.
Standard grade holds the largest share; momentum sits with organic grade.
Application:
Cost tier differentiation separates commodity applications from premium formulation slots where certification documentation commands procurement priority.
- Dairy Products:Organic-certified cassia gum stabilizes yogurt, ice cream, and cheese spreads requiring freeze-thaw stability and clean-label positioning. EU dairy conglomerates in Germany and the Netherlands now lock in 12-18 month contracts with direct processor relationships, bypassing traditional distributors.
- Pet Food:Wet gravy-based formulations in the United States are displacing carrageenan with cassia gum as manufacturers reposition around clean-label claims. Pet food stabilization demand is climbing the fastest among all application segments.
- Meat Processing:Standard grade dominates processed poultry and emulsified meat applications where FDA 21 CFR 172.655 governs permitted use levels.
- Bakery Items:Moisture retention in frozen dough and shelf-stable baked goods drives volume, though price sensitivity limits grade migration.
- Beverages:Modified grade penetration in energy drinks and ready-to-drink coffee depends on high-shear stability during homogenization.
Dairy applications command the highest margins; pet food is gaining share fastest.
End User:
Customer type determines whether procurement flows through spot markets or specification-driven annual contracts with embedded technical service clauses.
- Food Manufacturers:Multinational meat and dairy processors dominate volume, consolidating supplier panels to three qualified partners per region with direct formulation support requirements.
- Beverage Producers:Energy drink and ready-to-drink coffee manufacturers drive modified grade development through customized viscosity specifications.
- Animal Feed Companies:Pet food specialists in the United States are expanding wet formulation capacity with gelling agent substitution strategies.
- Confectionery Units:Chewy candy and jelly applications represent a smaller volume pool with moderate growth trajectory.
Food manufacturers hold the largest share; beverage producers show the steepest expansion trajectory.
Packaging Type:
Volume scale and handling infrastructure segment procurement logistics between industrial-scale operations and specialty ingredient distributors.
- Bulk Bags:500-1000 kg flexible intermediate bulk containers serve multinational food manufacturers with dedicated silo systems and high-throughput processing lines.
- Plastic Drums:25-50 kg lined drums protect against moisture ingress for mid-scale dairy and meat processors without bulk handling capability.
- Paper Bags:Multi-wall kraft constructions with polyethylene liners balance cost and protection for regional bakery and confectionery procurement.
- Sachets:1-5 kg retail-scale packaging serves small-batch artisan producers and research and development laboratories with minimal order quantities.
Bulk bags hold the largest share; plastic drums are climbing fastest as mid-tier processors upgrade from paper packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States pet food manufacturers prioritize clean-label gelling agents in wet formulations. European dairy processors mandate organic-certified grades with full seed-to-powder traceability. Indian processors dominate export supply while serving domestic meat processing demand.
United States
Wet pet food stabilization drives formulation demand as manufacturers displace carrageenan with cassia gum in gravy-based products. FDA 21 CFR 172.655 governs permitted use levels in meat and poultry applications. Midwest pet food production clusters around Kansas and Iowa are expanding gelling agent substitution trials.
Germany
Organic dairy and infant nutrition lines require documented sustainable supply chains under EU Green Deal sourcing mandates. EFSA evaluations enforce purity criteria that filter uncertified processors. Bavarian dairy conglomerates now lock in 12-18 month direct contracts with qualified Indian suppliers.
India
Domestic meat processing and export purification capacity concentrate in Gujarat-based operations. FSSAI export purity specifications anchor procurement decisions for international buyers. Ahmedabad and surrounding districts host over 80% of global cassia gum purification infrastructure.
Netherlands
Dairy manufacturers demand organic-certified grades with blockchain-enabled lot tracking for Japanese and South Korean export documentation. REACH registration obligations shape supplier qualification requirements. Rotterdam serves as the primary European distribution hub for qualified Indian processors.
Brazil
ANVISA's evolving food additive standards are opening formulation trials for cassia gum in processed poultry applications. Clean-label meat processing trends create first-mover positioning for exporters with Portuguese-language technical support. São Paulo-based food manufacturers are initiating supplier qualification programs.
Food Grade Cassia Gum Powder Market Competitive Landscape
Capability concentration sits with specialized organic-certified processors; scale advantage sits with integrated seed-crushing operations. The vendor base separates into three tiers: bulk supply contractors with Gujarat-based infrastructure, premium-grade specialists with dual organic certifications, and backward-integrated crushers controlling raw material cycles. Dominant competitive moves include direct-to-manufacturer digital platform deployment and enzymatic purification technology licensing.
Among Gujarat-based processors, Agro Gums occupies a position exemplifying bulk supply scale, while Altrafine Gums represents the organic-certified premium tier. Avlast Hydrocolloids anchors the backward-integrated archetype with captive seed-crushing capabilities. These three patterns illustrate how procurement channels now bifurcate between conventional volume contracts and certified-grade premium positioning.
| Leading Market Players |
|---|
| Agro Gums |
| Avlast Hydrocolloids |
| Altrafine Gums |
| H. B. Gum Industries Private Limited |
| Premcem Gums |
| Agro Herb Gums |
| JD Gums And Chemicals |
| Dwarkesh Industries |
| Amba Gums & Feeds Products |
| Others |
Pricing and Supply Chain Analysis
Idle capacity at Gujarat-based purification facilities during the 2023 monsoon shortfall compressed spot pricing discipline while reinforcing contract premiums for qualified organic grades. This utilization asymmetry now drives supplier behavior toward long-term offtake commitments that lock in margin protection against raw material volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational food manufacturers and Indian processors, displacing spot-market purchasing as EFSA purity criteria tighten. Price differentiation hinges on organic certification tier and galactomannan purity assay, with EU organic-India Organic NPOP dual-certified material commanding substantial premiums over standard FSSAI export grade. Cost compression in conventional standard grade is intensifying because seed price volatility from Rajasthan harvest cycles transmits directly to processor margins. Mid-scale dairy processors without bulk handling infrastructure exhibit highest price sensitivity, while German infant nutrition lines demonstrate lowest sensitivity due to regulatory compliance non-negotiability.
Supply Chain Analysis
Gujarat-based processors including Agro Gums, Altrafine Gums, and Avlast Hydrocolloids hold dominant purification capacity within 200 kilometers of Ahmedabad. Raw material supply draws from Rajasthan and Gujarat cassia tora seed harvests, with galactomannan content and moisture levels determining crush economics. Single-origin geographic concentration creates vulnerability to regional logistics disruptions or FSSAI enforcement actions. Distribution runs through Rotterdam and Hamburg hub-and-spoke networks for European dairy manufacturers, with direct B2B digital platforms emerging for qualified Japanese and South Korean buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic purification technology represents a high-growth disruption reshaping competitive economics, as processors achieving 85%+ galactomannan purity without solvent residues capture premium formulation slots previously inaccessible to mechanical-only operations.
For Market Incumbents: Entrench market position through backward integration into captive seed-crushing capacity and accelerated HACCP-aligned processing line investments. Carrageenan displacement momentum in US wet pet food creates substitution threat requiring formulation support service bundling. Dual organic certification infrastructure serves as the priority defensive lever against qualified supplier pool contraction under EFSA 2023 guidance. For New Entrants and Emerging Players: Modified grade development for high-shear beverage applications in energy drinks and ready-to-drink coffee represents the most penetrable entry point, commanding 40-60% price premiums through customized viscosity specifications. Portuguese-language technical support capabilities unlock first-mover positioning in Brazilian processed poultry as ANVISA standards evolve. Direct-to-manufacturer digital platform deployment offers go-to-market angle bypassing Rotterdam and Hamburg distributor margins. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because EU Green Deal sourcing mandates and FSAI-EFSA regulatory divergence create persistent premium capture for dual-certified processors with traceability infrastructure. Acquisition target archetype: mid-scale Indian manufacturers with fermentation partnerships deploying enzymatic purification ahead of integrated players. Monitor blockchain-enabled lot tracking adoption rates as inflection indicator for Japanese and South Korean export contract accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Purification Technology Licensing | Enables 85%+ galactomannan purity achievement without EU-contaminant-triggering solvent residues. |
| Dual Organic Certification Investment | Unlocks premium dairy and infant nutrition slots under EU Green Deal sourcing mandates. |
| Backward Integration into Seed Crushing | Anchors cost control across Rajasthan and Gujarat monsoon-dependent harvest volatility cycles. |
| Direct-to-Manufacturer Digital Platform | Captures margin previously lost to Rotterdam and Hamburg-based traditional gum distributors. |
| Blockchain-Enabled Lot Tracking Deployment | Satisfies Japanese and South Korean documentation requirements previously blocking export contracts. |
Research Methodology
A spread of perspectives from Gujarat-based processing plant managers, procurement leads at German and Dutch dairy conglomerates, FSSAI regulatory affairs specialists, and Rotterdam distribution channel partners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FSSAI export purity specifications, EFSA food additive evaluations, EU Green Deal documentation requirements, and India Organic NPOP audit protocols. Bottom-up capacity modeling across Ahmedabad-cluster purification facilities triangulated against top-down demand estimation from meat processing, dairy, and pet food formulation trends.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type tiers, application categories, end-user procurement patterns, and packaging format logistics. CAGRs derived from regression-based trajectory fitting against historical seed price volatility patterns and regulatory compliance timeline compression effects. Forecast inputs incorporated enzymatic purification technology adoption curves and blockchain traceability infrastructure deployment rates.
Practitioners should monitor EFSA purity criteria evolution, FSSAI laboratory assay standardization disputes, and EU organic conversion period extensions for early signals requiring forecast revision. Cross-checking against India Agricultural and Processed Food Products Export Development Authority trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.