
 Spain Food Preservatives Market | 2026-2036
Spain Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Preservatives Market Analytics
Buyer concentration among Spanish food manufacturers is expanding as mid-tier processors consolidate procurement to secure volume pricing on sorbate and benzoate blends. Chr. Hansen Holdings leverages its fermentation-derived preservative portfolio to dominate clean-label supply contracts with Iberian dairy cooperatives. Cargill Inc. anchors its position through backward integration into citric acid supply chains serving Andalusian beverage bottlers. Corbion competes via specialized propionate formulations targeting artisan bakery segments across Madrid and Valencia.
Food preservatives encompass chemical and biological additives that inhibit microbial spoilage, enzymatic degradation, and oxidative rancidity in packaged foods, typically dosed at 0.05% to 0.3% by weight depending on water activity and pH targets. Sorbates maintain the largest volume position due to broad-spectrum efficacy against molds and yeasts in Spanish dairy and bakery applications. Benzoates command premium positioning in acidified beverages where pH-dependent activation optimizes cost-per-dose economics. Powder formulations lead industrial uptake for handling stability and shelf-life extension, though liquid emulsions gain traction in automated meat brine injection systems across Galician processing plants.
EFSA's ongoing re-evaluations of benzoate safety margins and the EU's Farm to Fork Strategy under the European Green Deal tighten permissible additive thresholds, forcing reformulation investments across Spanish food manufacturers. Spain's national food safety agency, AESAN, enforces Royal Decree 1425/2006 implementing EU food additive regulations with additional labeling requirements for preservative-containing products marketed to children. Stakeholders must monitor ECHA's REACH substance restriction proposals and AESAN's forthcoming guidance on natural preservative equivalence claims to anticipate compliance cost shifts.
Market Dynamics
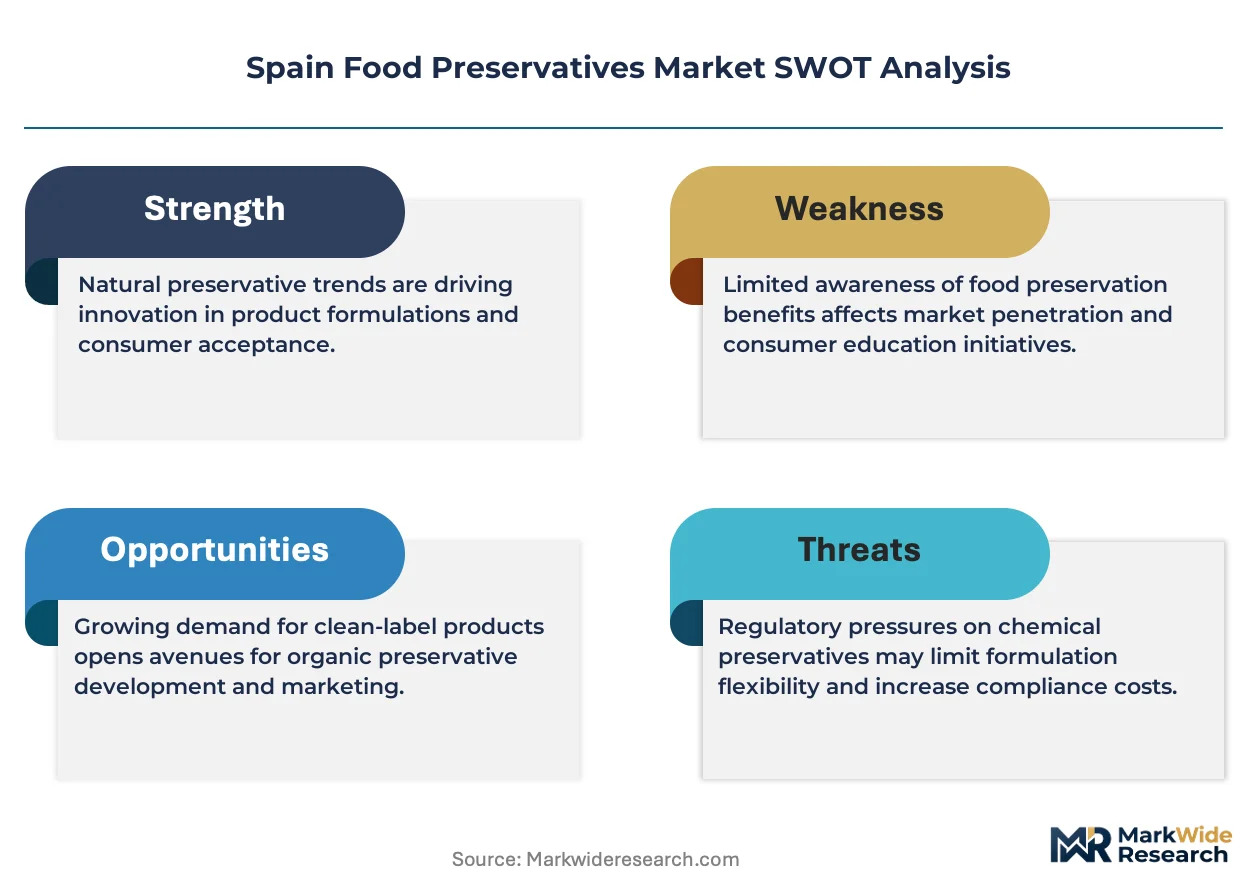
EFSA's preservative reassessment programs and the EU's Clean Labeling Directive are forcing Spanish food manufacturers into costly reformulation cycles, compressing profit margins while redistributing competitive advantage toward fermentation-derived and plant-extract alternatives.
Growth Catalysts
- Processed meat applications:Galician and Catalonian processors are expanding automated brine injection systems that rely on sorbate and benzoate blends for shelf-life extension in export-ready cured products.
- AESAN enforcement alignment:Spain's national food safety agency is harmonizing Royal Decree 1425/2006 with updated EU additive regulations, creating compliance clarity that accelerates clean-label investments.
- Citric acid supply chain localization:Backward integration into Andalusian citrus processing is reducing import dependency for acidulants used in beverage preservation.
Market Restraints
- Benzoate safety margin compression:EFSA's ongoing re-evaluations of acceptable daily intake levels are narrowing formulation flexibility for Spanish soft drink bottlers.
- Fermentation capacity concentration:Clean-label biological preservatives depend on specialized bioreactor infrastructure concentrated among a handful of Northern European suppliers.
- Natural extract substitution economics:Rosemary and green tea extracts remain cost-prohibitive at scale for mid-tier bakery segments in Madrid and Valencia.
Strategic Opportunities
- Andalusian beverage cluster expansion:Seville and Málaga bottling corridors offer underpenetrated demand for buffered propionate systems in non-carbonated functional drinks.
- ECHA REACH substance incentives:Spain's chemical registration framework rewards early adopters of bio-based preservative platforms with streamlined authorization pathways.
- Plant-based meat analogues:Barcelona food tech startups are creating novel application demand for clean-label mold inhibitors in high-moisture extruded proteins.
Industry Challenges
- Formulation chemist scarcity:Spanish technical universities are producing insufficient graduates trained in pH-dependent preservative synergy modeling for complex multi-component foods.
- Clean-label certification timelines:AESAN's pending guidance on natural preservative equivalence claims is delaying product launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Preservatives Market |
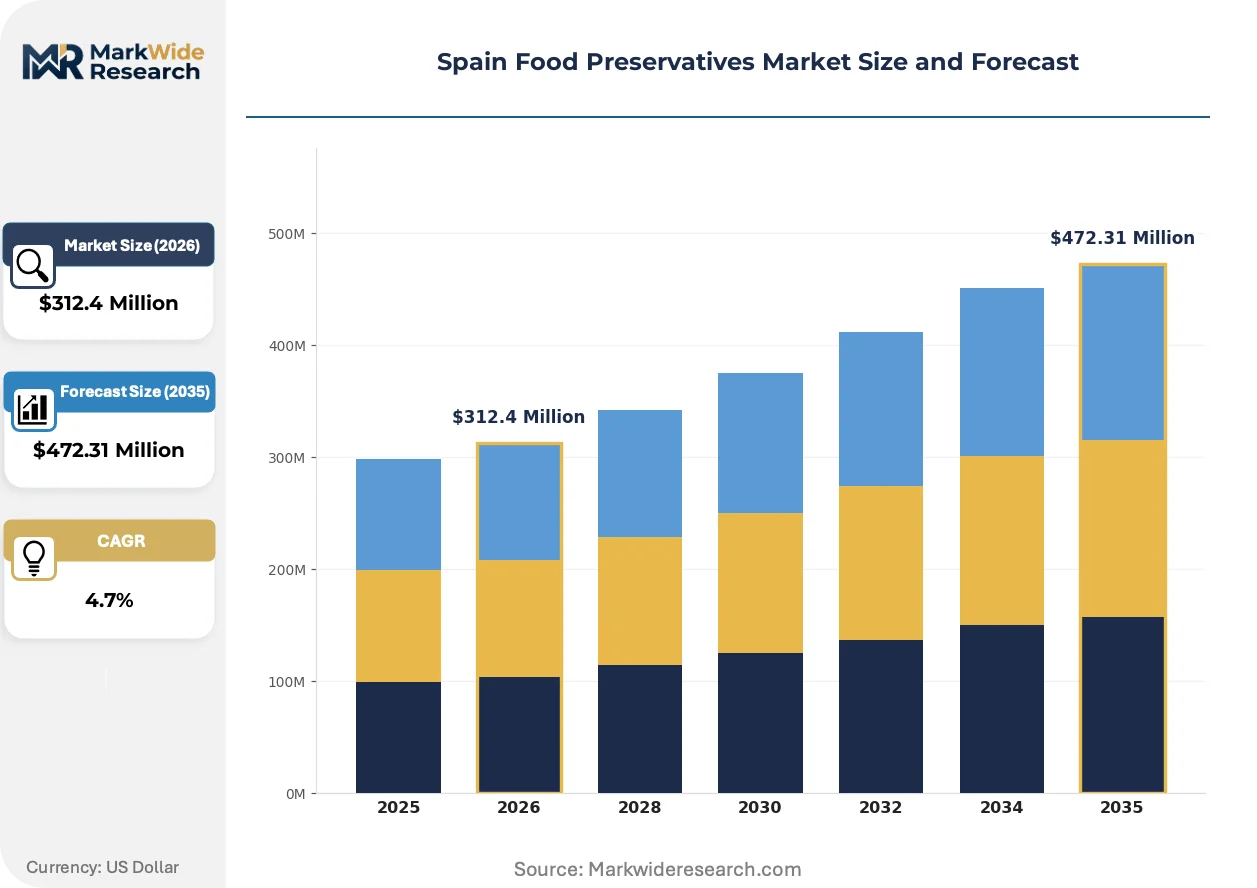
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrates, Propionates Application: Meat Processing, Dairy Products, Bakery Products, Beverages Form: Powder, Liquid, Granular, Emulsion End User: Food Manufacturers, Retailers, Food Service Providers, Households |
| Companies Covered | Chr. Hansen Holdings, Koninklijke DSM N.V., Corbion, Cargill Inc., BASF SE, Bordas S.A., Barcelona Food Ingredient, Tate & Lyle PLC, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Preservatives Market Evolving Landscape
Preservation technology in Spain is pivoting from synthetic chemical dominance toward bio-derived and fermentation-based systems, driven by regulatory pressure and retailer clean-label mandates that now determine supplier selection criteria.
Fermentation-derived propionates and cultured dextrose solutions are converging with high-pressure processing equipment to deliver extended shelf life without synthetic additive declarations. Iberian dairy cooperatives are adopting these integrated systems fastest, with Catalonian yogurt producers leading implementation. This convergence is compressing the addressable market for traditional benzoate-sorbate blends in chilled dairy applications.
EFSA's additive re-evaluation framework under the EU's Farm to Fork Strategy is tightening permissible thresholds for benzoates and sulfites across member states. Spanish manufacturers face mandatory label warnings for preservative-containing products marketed to children under forthcoming AESAN guidance. Acidified beverage segments in Barcelona and Valencia are responding by accelerating citric acid and ascorbate substitution programs.
Spanish food manufacturers are consolidating procurement functions to secure volume pricing and technical service commitments from preservative suppliers. Mid-tier processors in Galicia and Castile-La Mancha are abandoning fragmented spot purchasing in favor of multi-year supply agreements with formulation support. This concentration is most visible in Catalonia's meat processing cluster, where three cooperatives now negotiate sorbate blends as a single purchasing entity.
Spain Food Preservatives Market Segmentation
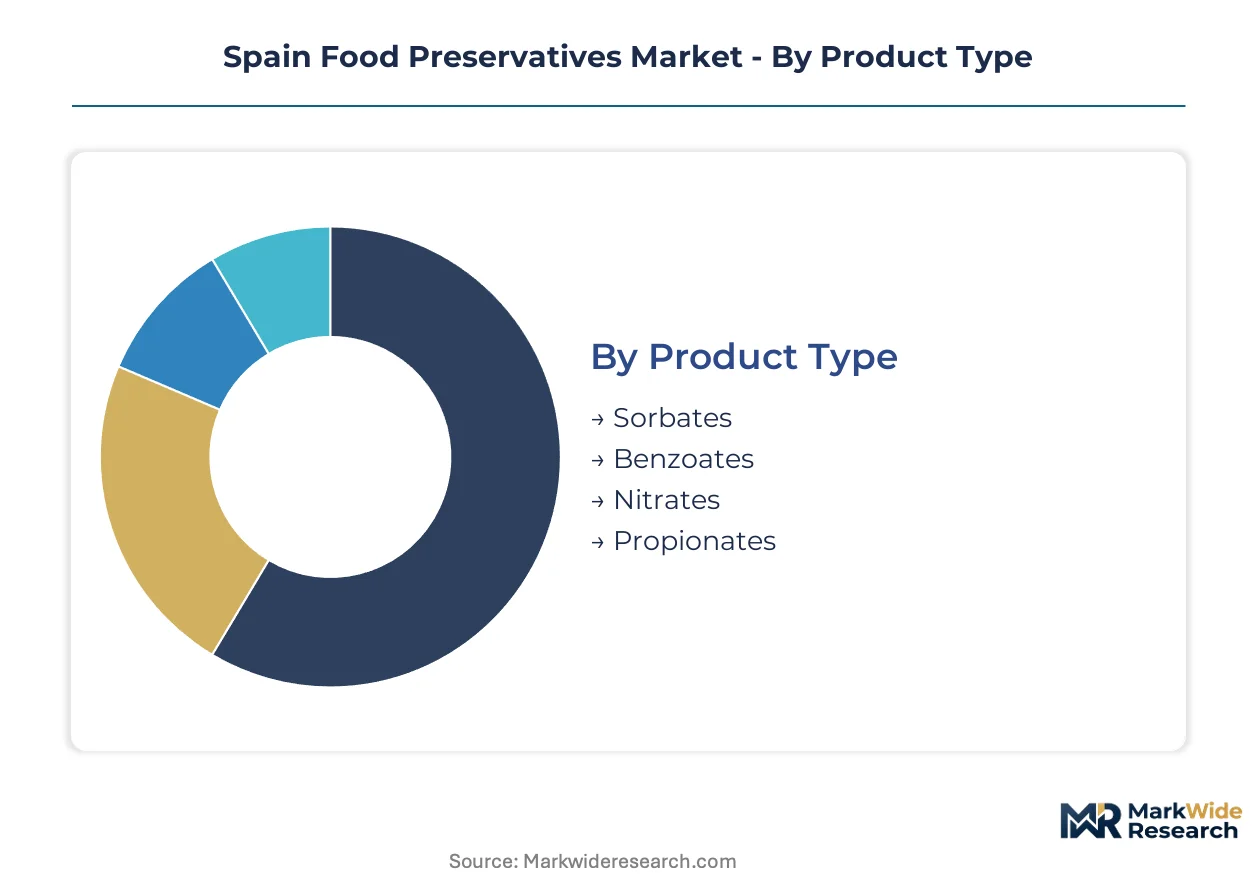
Preservative selection in Spain hinges on pH compatibility, water activity targets, and EFSA compliance thresholds. Manufacturers segment procurement by functional performance rather than commodity pricing, reflecting the technical complexity of reformulation under tightening additive regulations.
Product Type:
Cost-per-dose economics and regulatory headwinds drive buyer preference toward broad-spectrum efficacy and clean-label positioning.
- Sorbates:Potassium sorbate dominates Spanish dairy and bakery applications through superior mold and yeast inhibition across pH ranges below 6.5. Galician cured meat processors specify sorbate blends for export shelf-life extension to Northern European markets. Sorbates lead on scale; propionates lead on momentum.
- Benzoates:Sodium and potassium benzoates deliver pH-dependent antimicrobial activation optimized for acidified beverages below pH 4.5. Barcelona and Valencia soft drink bottlers face formulation pressure as EFSA narrows acceptable daily intake margins for benzoic acid derivatives. Benzoates lead on scale; sorbates lead on momentum.
- Nitrates:Sodium nitrite and potassium nitrate preserve color and inhibit Clostridium botulinum in traditional Spanish cured meats, though AESAN mandates residual level disclosures on retail packaging.
- Propionates:Calcium and sodium propionates target rope spoilage prevention in Madrid and Valencia artisan bakeries, with Corbion supplying specialized formulations for high-moisture dough systems.
Sorbates lead on scale; propionates lead on momentum.
Application:
End-use concentration in Catalonia and Galicia shapes regional supplier technical service investments.
- Meat Processing:Automated brine injection systems in Galician and Catalonian plants demand preservative blends with uniform dissolution kinetics for cured ham and chorizo production. Export certification requirements to France and Germany drive sorbate-nitrate combination specifications.
- Dairy Products:Catalonian yogurt producers adopt fermentation-derived propionates and cultured dextrose to meet retailer clean-label mandates while maintaining chilled shelf life.
- Bakery Products:Madrid and Valencia mid-tier bakeries balance propionate cost efficiency against rosemary extract premiums for mold inhibition in sliced bread.
- Beverages:Andalusian citrus processors integrate citric acid with ascorbate systems to reduce benzoate dependency in functional and conventional soft drinks.
Meat processing leads on scale; beverages lead on momentum.
Form:
Handling infrastructure and dosing automation determine formulation preference across processor tiers.
- Powder:Crystalline sorbates and benzoates dominate industrial procurement for storage stability and precise gravimetric dosing in high-volume Catalonian dairy plants.
- Liquid:Pre-solubilized concentrates enable automated metering in Galician meat brine injection lines, reducing dissolution tank maintenance.
- Granular:Low-dust granulations serve Castile-La Mancha mid-tier bakeries with limited pneumatic conveying infrastructure.
- Emulsion:Oil-in-water systems penetrate Barcelona food tech startups developing high-moisture extruded plant proteins requiring uniform lipid-phase preservative distribution.
Powder leads on scale; emulsion leads on momentum.
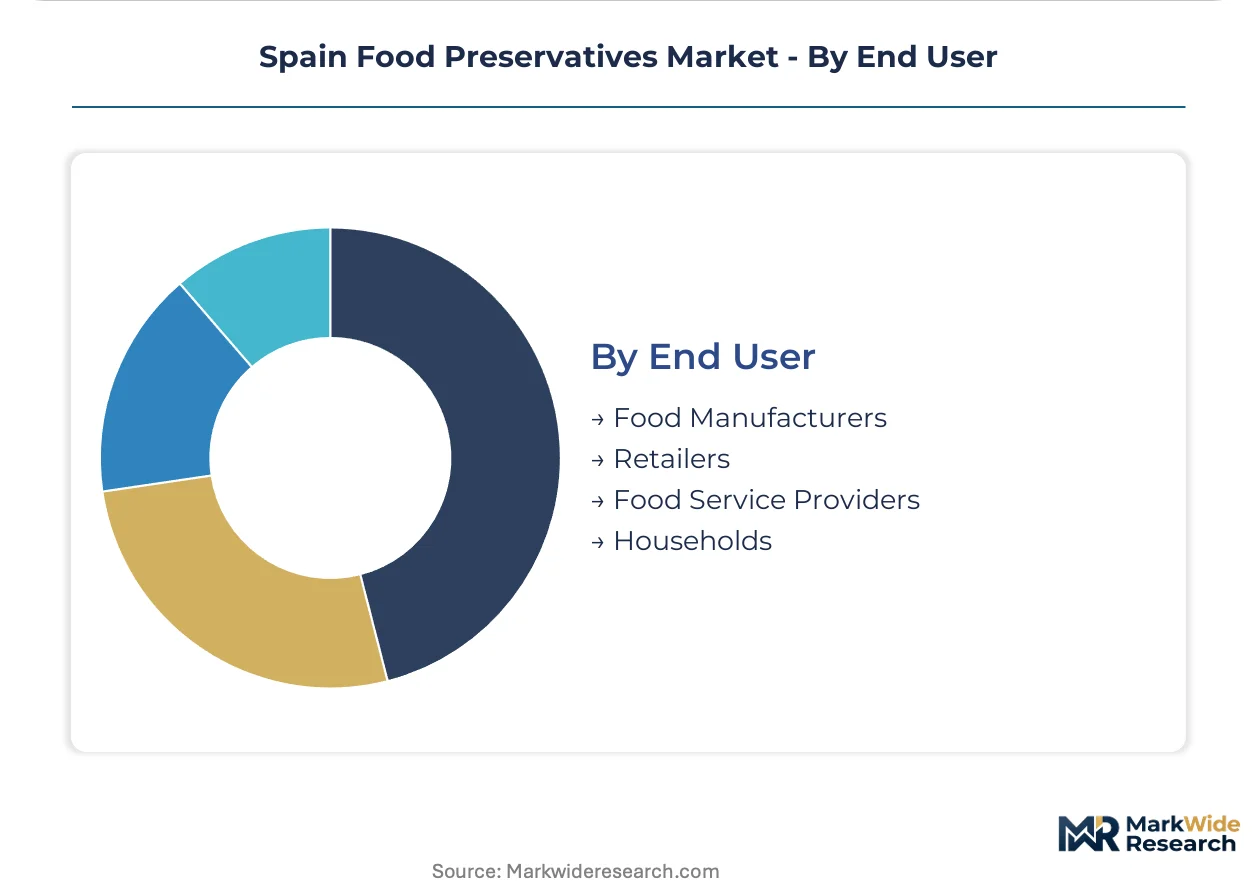
End User:
Procurement consolidation and technical service demands separate institutional from fragmented purchasing patterns.
- Food Manufacturers:Consolidated purchasing entities in Catalonia's meat cooperative cluster negotiate multi-year sorbate blend contracts with embedded formulation support.
- Retailers:Mercadona and Carrefour España impose clean-label additive restrictions on private-label suppliers, accelerating fermentation-derived preservatory adoption.
- Food Service Providers:HORECA distributors in Madrid and Barcelona specify preservative-free or minimal-additive sauces and prepared meals for contract catering.
- Households:Consumer-packaged vinegar and salt-based home preservation kits capture marginal share in traditional cooking segments.
Food manufacturers lead on scale; retailers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands a larger absolute market for food preservatives than Spain, yet Spanish processors demonstrate faster reformulation velocity under AESAN's accelerated compliance timelines for clean-label transitions.
Catalonia
Barcelona's food processing cluster drives sorbate and propionate consumption through dairy cooperative consolidation and meat export certification demands. AESAN's Royal Decree 1425/2006 enforcement creates regulatory clarity that accelerates clean-label investments. Girona's automated brine injection facilities supply cured ham to French and German retail chains.
Andalusia
Seville and Málaga bottling corridors generate citric acid and ascorbate demand as beverage manufacturers reduce benzoate dependency. The EU's Farm to Fork Strategy tightens additive thresholds for functional drinks marketed across Southern Europe. Córdoba's citrus processing infrastructure enables backward integration into acidulant supply chains.
Galicia
Cured meat processors in Lugo and Ourense specify sorbate-nitrate combinations for export shelf-life extension to Northern European markets. EFSA's ongoing benzoate safety reassessments narrow formulation flexibility for traditional chorizo production. Santiago de Compostela's cooperative purchasing entities negotiate multi-year preservative contracts as consolidated blocks.
Madrid
Mid-tier bakeries in the capital balance propionate cost efficiency against rosemary extract premiums for mold inhibition in sliced bread distribution. Spain's national food safety agency coordinates with ECHA on REACH substance registration incentives for bio-based alternatives. Alcalá de Henares hosts formulation technical service centers serving Castile-La Mancha's grain processing corridor.
Valencia
Artisan bakery segments adopt specialized propionate formulations for high-moisture dough systems in pa de quilo production. The EU's Clean Labeling Directive mandates disclosure requirements that disadvantage synthetic preservatory positioning in Mediterranean retail channels. Valencia's port infrastructure facilitates citric acid import substitution from Andalusian citrus processors.
Spain Food Preservatives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's preservative procurement landscape. The market structure concentrates around fermentation-derived biological suppliers and integrated chemical acidulant producers. Three archetypes dominate: Northern European biotech specialists with clean-label portfolios, global agribusiness conglomerates with captive citric acid supply, and Iberian regional blenders with formulation service capabilities. Capacity expansion and backward integration into raw material supply chains represent the primary competitive vectors.
Among Northern European fermentation specialists, Chr. Hansen Holdings and Koninklijke DSM N.V. exemplify the clean-label biological tier, supplying cultured dextrose and propionate alternatives to Catalonian dairy cooperatives. Corbion occupies a position within the specialized propionate formulation segment, while Cargill Inc. anchors the integrated agribusiness archetype through upstream citrus processing control. BASF SE represents the diversified chemical conglomerate tier with broad acidulant and antioxidant portfolios.
| Leading Market Players |
|---|
| Chr. Hansen Holdings |
| Koninklijke DSM N.V. |
| Corbion |
| Cargill Inc. |
| BASF SE |
| Bordas S.A. |
| Barcelona Food Ingredient |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Backward integration into Andalusian citrus processing anchors Cargill's supply position and pricing power against importers dependent on Chinese citric acid shipments. This captive acidulant supply insulates Iberian beverage bottlers from spot market volatility while compressing margins for non-integrated blenders serving Madrid and Valencia bakeries.
Pricing Analysis
Capacity additions in Northern European fermentation facilities are reshaping price floors for clean-label biological preservatives. Three-tier pricing structure across premium fermentation-derived, standard chemical, and economy commodity tiers reflects certification grade and volume scale differentiation. Cost compression in synthetic sorbate blends is intensifying because Galician meat cooperatives consolidated procurement into multi-year offtake agreements. Mid-tier Castile-La Mancha processors show highest price sensitivity; Catalonian dairy exporters with clean-label mandates show lowest.
Supply Chain Analysis
Fermentation-derived propionate supply rests on Danish and Dutch bioreactor infrastructure concentrated among Chr. Hansen and DSM facilities. Raw material dependencies span Brazilian sugarcane feedstock, Belgian enzyme cultures, and Spanish citrus pulp for acidulant extraction. Single-source vulnerability runs through Northern European biological production clusters serving Iberian clean-label demand. Distribution runs through Barcelona and Madrid formulation technical service centers with just-in-time replenishment to Galician meat plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's accelerated AESAN compliance timelines relative to French enforcement create a regulatory-arbitrage window for early clean-label adopters to capture export share into Northern European retail chains.
For Market Incumbents: Cement dominance in Catalonia's dairy cooperative cluster through embedded fermentation capacity and multi-year technical service contracts. Deepen backward integration into Andalusian citrus supply chains to defend margin position against Chinese acidulant importers. Prioritize EFSA pre-submission dossiers for novel biological preservatives ahead of benzoate threshold tightening. For New Entrants and Emerging Players: Automated brine injection-compatible liquid emulsion formulations offer a technology-first wedge into Galician cured meat export specifications currently served by powder incumbents. Target Andalusian functional beverage bottlers in Seville and Málaga corridors with buffered propionate systems reducing benzoate dependency. Lead with formulation chemist placement and rapid AESAN equivalence claim navigation as go-to-market anchor. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier Spanish blenders lack fermentation access and clean-label certification capabilities. Five-to-ten year viability favors specialists with captive biological production or upstream citrus control over commodity chemical traders. Watch EFSA's final benzoate acceptable daily intake determination as inflection signal for reformulation investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Processing | Cargill's Andalusian acidulant supply secures cost position against Chinese import dependency. |
| Fermentation Capacity Expansion | Chr. Hansen's bioreactor investments serve Catalonian dairy clean-label mandates ahead of regulatory deadlines. |
| Clean-Label Certification Program | AESAN equivalence claim navigation compresses product launch timelines for biological preservative adopters. |
| Long-Term Supply Agreement | Galician meat cooperatives consolidated procurement secures volume pricing and embedded technical service. |
| Joint Venture with Food Tech Startup | Barcelona extruded protein innovators create novel demand for emulsion-based mold inhibitors in plant-based analogues. |
Research Methodology
Bottom-up food manufacturer procurement modeling reconciled against top-down preservative supplier shipment tracking forms the analytical core of this study. Primary interviews with formulation chemists at Spanish dairy cooperatives, procurement leads at Galician meat processors, technical service directors at Northern European fermentation specialists, and AESAN regulatory affairs officers combined with secondary validation. Secondary sources encompass EFSA additive re-evaluation dossiers, AESAN Royal Decree implementation guidance, EU Farm to Fork Strategy policy documents, and customs trade data on citric acid and sorbate imports.
Input-output matrices map preservative consumption by application, form, and end-user tier across the projection horizon. Segmentation dimensions modeled include product type, application, physical form, and regional processing cluster. CAGRs derive from trend extrapolation of procurement volumes against EFSA regulatory milestone timelines. Industry-specific forecast inputs incorporate AESAN enforcement acceleration schedules and retailer clean-label mandate adoption curves.
The model holds under stable EU regulatory implementation timelines; deviation in EFSA benzoate safety margin determinations or REACH substance restriction acceleration would shift reformulation investment velocity. Forecasts reflect documented assumptions on cooperative procurement consolidation and fermentation capacity expansion. A small set of named triggers—EFSA final opinion publication, AESAN natural equivalence guidance release, and ECHA bio-based authorization pathway rulings—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Ascorbyl Palmitate Market