
 Russia Food Additives Market | 2026-2036
Russia Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Food Additives Market Analytics
Subscription-based technical service and reformulation support is pivoting how ingredient suppliers monetize relationships beyond bulk commodity sales. Cargill leverages its global application labs to sustain long-term contracts with Russian dairy processors seeking clean-label emulsifier systems. BASF anchors its position through specialized antioxidant portfolios tailored to local oil and fat stability challenges. Koninklijke DSM competes by extending enzyme technology platforms that reduce additive loadings in bakery applications.
Food additives encompass chemically synthesized or naturally derived substances incorporated at specified concentrations to enhance sensory properties, extend shelf stability, or modify textural behavior in processed foods. These compounds function through controlled interactions with food matrices, where preservatives inhibit microbial proliferation via pH modulation or membrane disruption, while emulsifiers reduce interfacial tension between immiscible phases. Flavoring agents command the deepest margin pools as Russian beverage and confectionery producers prioritize taste differentiation in saturated categories. Sweeteners exhibit the fastest structural expansion as sugar taxation and diabetic-friendly positioning reshape formulation strategies across bakery and dairy segments. Preservatives retain mature, volume-heavy demand from convenience foods manufacturers managing extended distribution cycles across Russia's vast territory.
Rospotrebnadzor enforces sanitary-epidemiological standards that determine permissible additive categories and maximum usage levels, while Eurasian Economic Union technical regulations harmonize conformity assessment procedures across member states. The country's national standardization body certifies compliance with GOST-R requirements, creating layered compliance obligations that favor suppliers with established regulatory navigation capabilities. Stakeholders must monitor evolving EAEU labeling mandates and import substitution incentives that could redirect sourcing patterns toward domestic or friendly-country manufacturers.
Market Dynamics
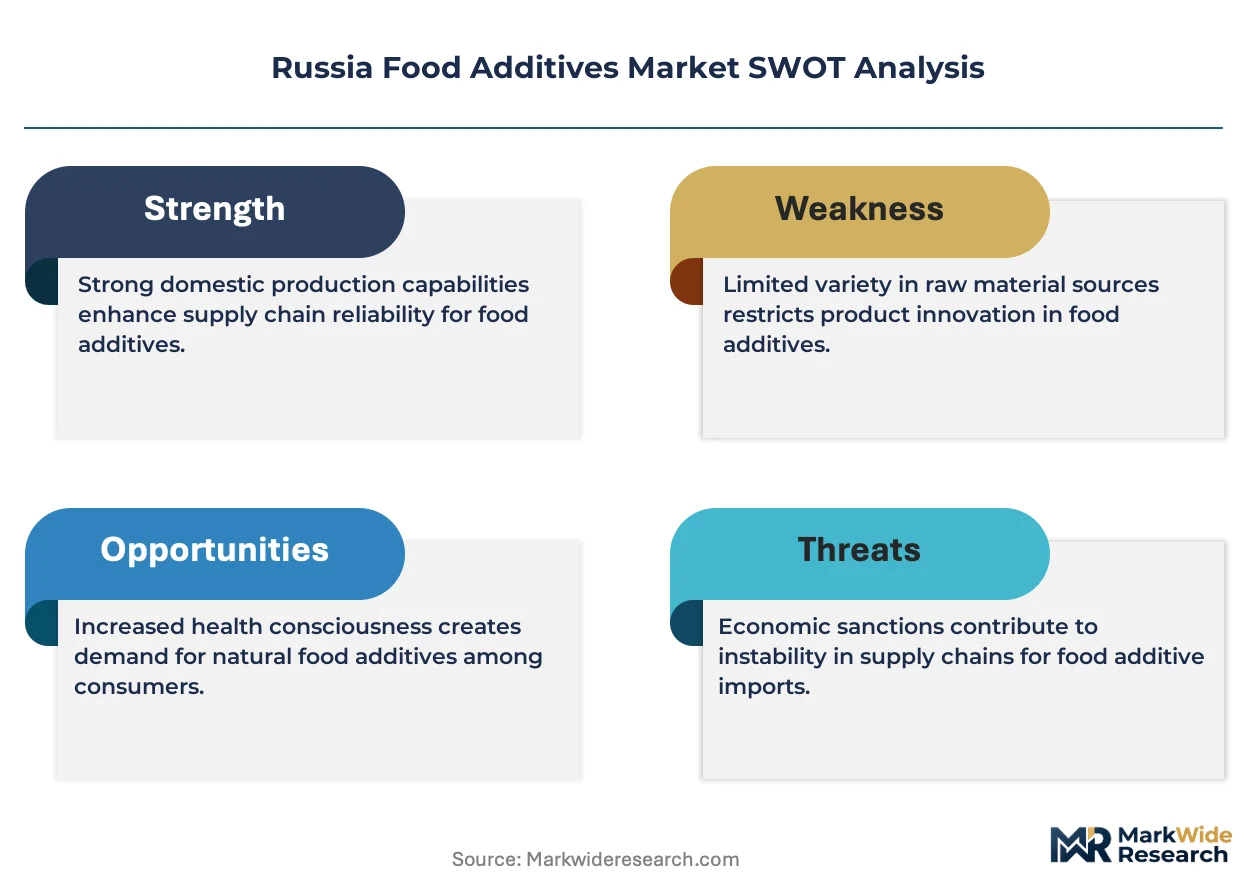
Eurasian Economic Union technical regulations are forcing Russian food processors to reformulate entire product lines, creating concentrated demand for clean-label emulsifiers and natural preservatives as manufacturers race to comply with tightened additive labeling mandates before enforcement deadlines.
Growth Catalysts
- EAEU Technical Regulation 029/2013:Harmonized food additive safety standards across member states are standardizing procurement specifications, enabling cross-border supplier qualification and reducing regional fragmentation in sourcing decisions.
- Processed meat sector expansion:Large-scale processors in the Central Federal District are scaling production capacity, driving volume procurement of phosphate blends and nitrite curing systems for extended shelf-life positioning.
- Enzymatic fat modification:Lipase-catalyzed interesterification is displacing chemical interesterification in bakery shortenings, reducing trans-fat content while maintaining functional performance in laminated dough applications.
Market Restraints
- Import dependency for specialty hydrocolloids:Guar gum and xanthan gum supply concentrates in India and China, exposing Russian compounders to currency volatility and logistics disruptions through Baltic port congestion.
- GOST-R certification complexity:Multi-layered conformity assessment procedures create 8-14 month approval timelines for novel additives, delaying commercialization of fermentation-derived alternatives to synthetic preservatives.
- Natural antioxidant performance gaps:Tocopherol and rosemary extract formulations exhibit inferior oxidative stability compared to synthetic TBHQ in high-temperature frying applications, limiting clean-label penetration in snack manufacturing.
Strategic Opportunities
- Volga Federal District dairy clusters:Underpenetrated processing capacity in Samara and Kazan presents white-space demand for starter culture and stabilizer systems as regional milk collection networks consolidate.
- Siberian convenience food manufacturing:Extended distribution cycles to remote population centers create specialized demand for hurdle-technology preservation combining modified atmosphere packaging with bioprotective cultures.
- Import substitution incentives:Federal industrial development programs are redirecting capital toward domestic citric acid and sorbic acid fermentation capacity, creating captive supply opportunities for local formulators.
Industry Challenges
- Reformulation technical talent scarcity:Food matrix compatibility expertise for clean-label transitions concentrates in Moscow and St. Petersburg, constraining regional processor capability building.
- Dual certification burden:Simultaneous GOST-R and EAEU conformity requirements demand redundant testing protocols, inflating compliance costs for imported specialty ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Food Additives Market |
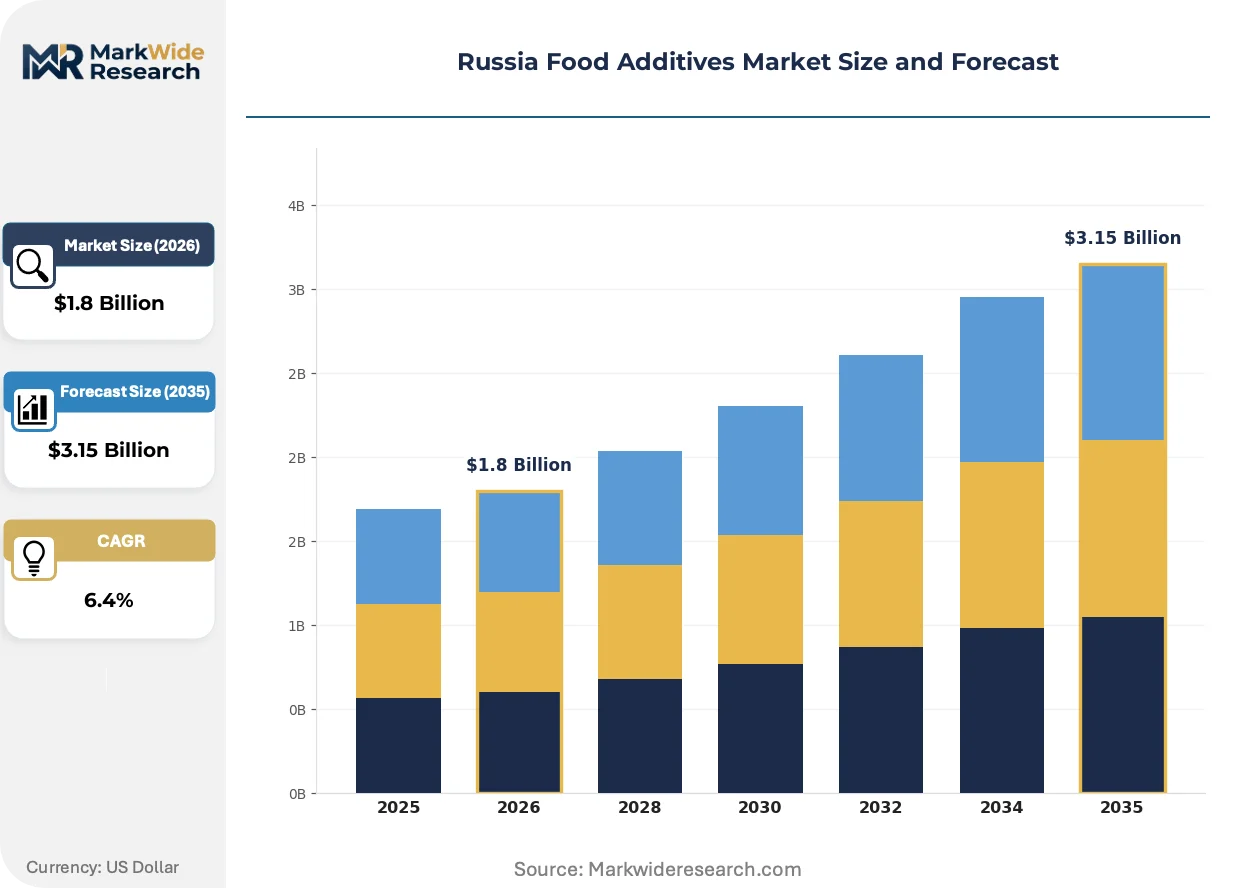
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Sweeteners, Preservatives, Emulsifiers Application: Beverages, Dairy Products, Bakery, Convenience Foods End User: Food Processing, Retail, Food Service, Home Cooking Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Tate & Lyle, Koninklijke DSM, Cargill, Avangard Group of Companies, International Flavors and Fragrances, Archer Daniels Midland, Givaudan, Symrise, BASF, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Food Additives Market Evolving Landscape
Biotechnology-derived additives are compressing the traditional synthetic-natural performance gap, while regulatory labeling mandates and procurement centralization are restructuring how Russian food manufacturers evaluate and source functional ingredients.
Precision fermentation for natural sweeteners is decentralizing supply chain control away from agricultural commodity markets. Recombinant yeast strains producing steviol glycosides and rare sugars achieve purity grades impossible through conventional extraction. Russian beverage formulators in the Central Federal District are qualifying these inputs at pilot scale. The technology is decentralizing procurement power from stevia leaf processors toward biotech compounders with fermentation infrastructure.
Rospotrebnadzor's 2023 amendments to sanitary-epidemiological regulations have expanded mandatory allergen labeling for sulfur dioxide and sulfite preservatives above 10 mg/kg thresholds. Bakery and dried fruit processors face reformulation pressure or enhanced declaration requirements. Confectionery manufacturers in Moscow oblast are accelerating transitions to alternative mold inhibitors like propionic acid salts to avoid consumer-facing allergen warnings.
Centralized procurement consortia among retail-owned private label manufacturers are compressing supplier negotiation cycles. Magnit and X5 Retail Group have consolidated additive sourcing decisions at headquarters level, displacing decentralized plant-level purchasing. Tier-2 dairy processors in the Northwestern Federal District report margin pressure as volume commitments become prerequisites for technical service access from major emulsifier suppliers.
Russia Food Additives Market Segmentation
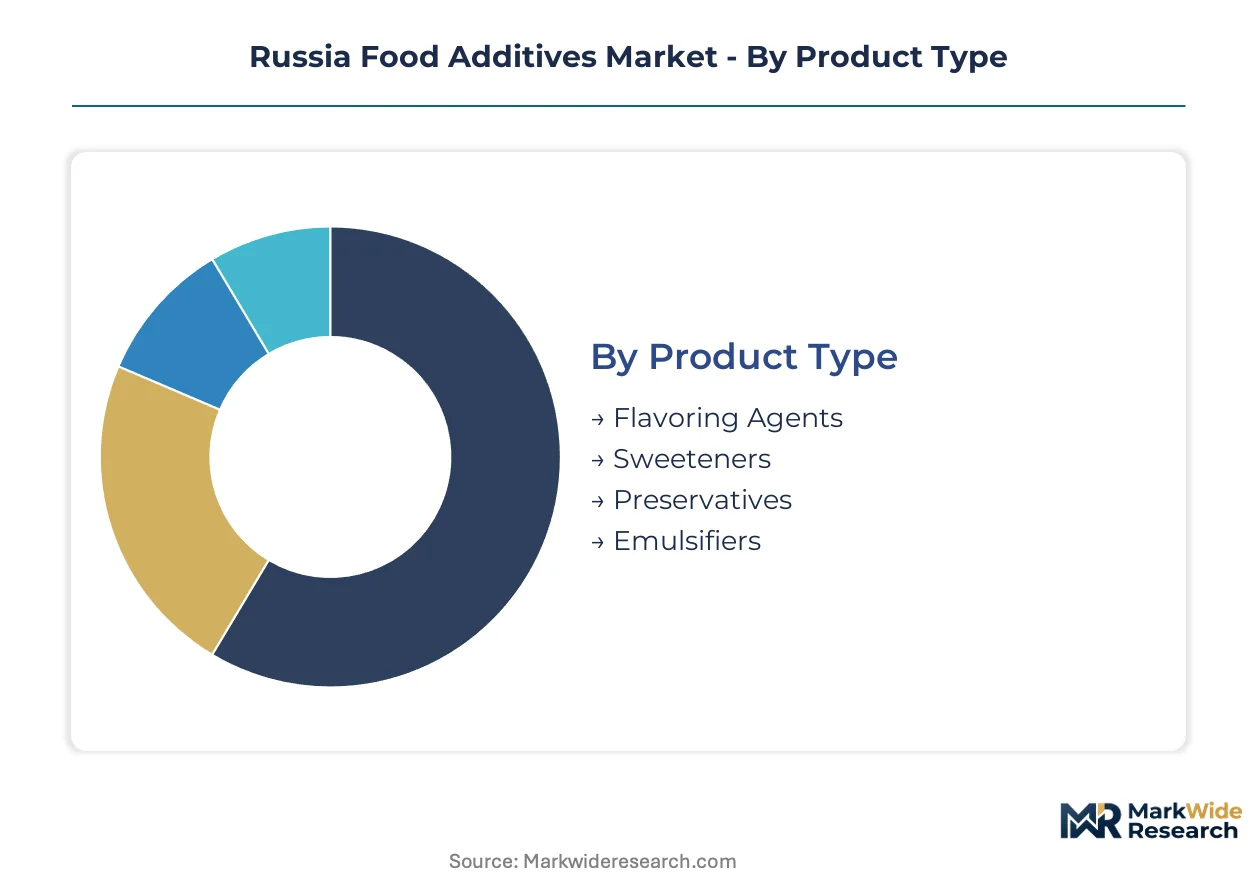
Russian food additive procurement concentrates around reformulation imperatives driven by EAEU technical regulations. Segment boundaries blur as clean-label transitions force multi-functional ingredient selection across product categories.
Product Type:
Supply concentration varies sharply across functional categories, with fermentation-derived and extraction-based segments exhibiting divergent import dependency profiles.
- Flavoring Agents:Complex volatile compounds and reaction flavors deliver taste differentiation in saturated beverage and confectionery categories. Moscow-based beverage producers command the deepest procurement budgets for proprietary flavor systems as carbonated drink competition intensifies.
- Sweeteners:High-intensity compounds and bulk sugar replacers modify sweetness profiles while managing caloric load and glycemic response. Bakery and dairy formulators in the Central Federal District are accelerating adoption as sugar taxation reshapes cost structures and diabetic-friendly positioning gains traction.
- Preservatives:Antimicrobial and antioxidant systems extend shelf stability through pH modulation, membrane disruption, or radical scavenging. Convenience food manufacturers managing distribution cycles across Russia's vast territory generate mature, volume-heavy demand for synthetic and natural alternatives.
- Emulsifiers:Surface-active agents reduce interfacial tension between immiscible phases in processed foods. Dairy processors seeking clean-label reformulation under EAEU mandates are consolidating procurement around lecithin and mono-diglyceride systems.
Flavoring agents absorb the bulk of installed capacity; sweeteners are expanding most quickly.
Application:
End-use demand fragments across processing clusters with varying technical sophistication and regulatory exposure.
- Beverages:Carbonated, still, and functional drink categories require acidity regulators, sweeteners, and flavor systems for taste stability. Major producers in Moscow oblast drive concentrated demand for clean-label emulsifier blends as EAEU labeling mandates tighten.
- Dairy Products:Fermented milk, cheese, and ice cream applications depend on stabilizers, emulsifiers, and bioprotective cultures for texture and safety. Volga Federal District clusters in Samara and Kazan present underpenetrated demand as regional milk collection networks consolidate processing capacity.
- Bakery:Bread, pastry, and biscuit manufacturing employs enzymes, emulsifiers, and preservatives for volume, shelf life, and crumb structure. Rospotrebnadzor's expanded sulfite allergen labeling is accelerating transitions to propionic acid salt mold inhibitors.
- Convenience Foods:Ready meals, snacks, and frozen products combine hurdle technologies for extended distribution cycles. Siberian manufacturers serving remote population centers create specialized demand for modified atmosphere packaging paired with bioprotective cultures.
Beverages command the steepest expansion trajectory; convenience foods exhibit the most fragmented procurement patterns.
End User:
Customer type determines specification complexity, with centralized retail procurement displacing decentralized plant-level purchasing.
- Food Processing:Industrial-scale manufacturers formulate finished products for retail and foodservice channels. Large processors in the Central Federal District generate volume procurement of phosphate blends and nitrite curing systems for meat applications.
- Retail:Private label manufacturers and branded goods producers specify additives for shelf-stable and fresh products. Magnit and X5 Retail Group headquarters in Moscow have consolidated additive sourcing decisions, compressing supplier negotiation cycles.
- Food Service:Restaurant chains, catering operations, and institutional kitchens utilize prepared bases and semi-finished ingredients with embedded additive systems. Regional operators face margin pressure from centralized procurement requirements.
- Home Cooking:Consumer-packaged additives for domestic preparation represent a marginal segment with limited commercial significance in Russia's market structure.
Food processing absorbs the bulk of installed capacity; retail is gaining share fastest.
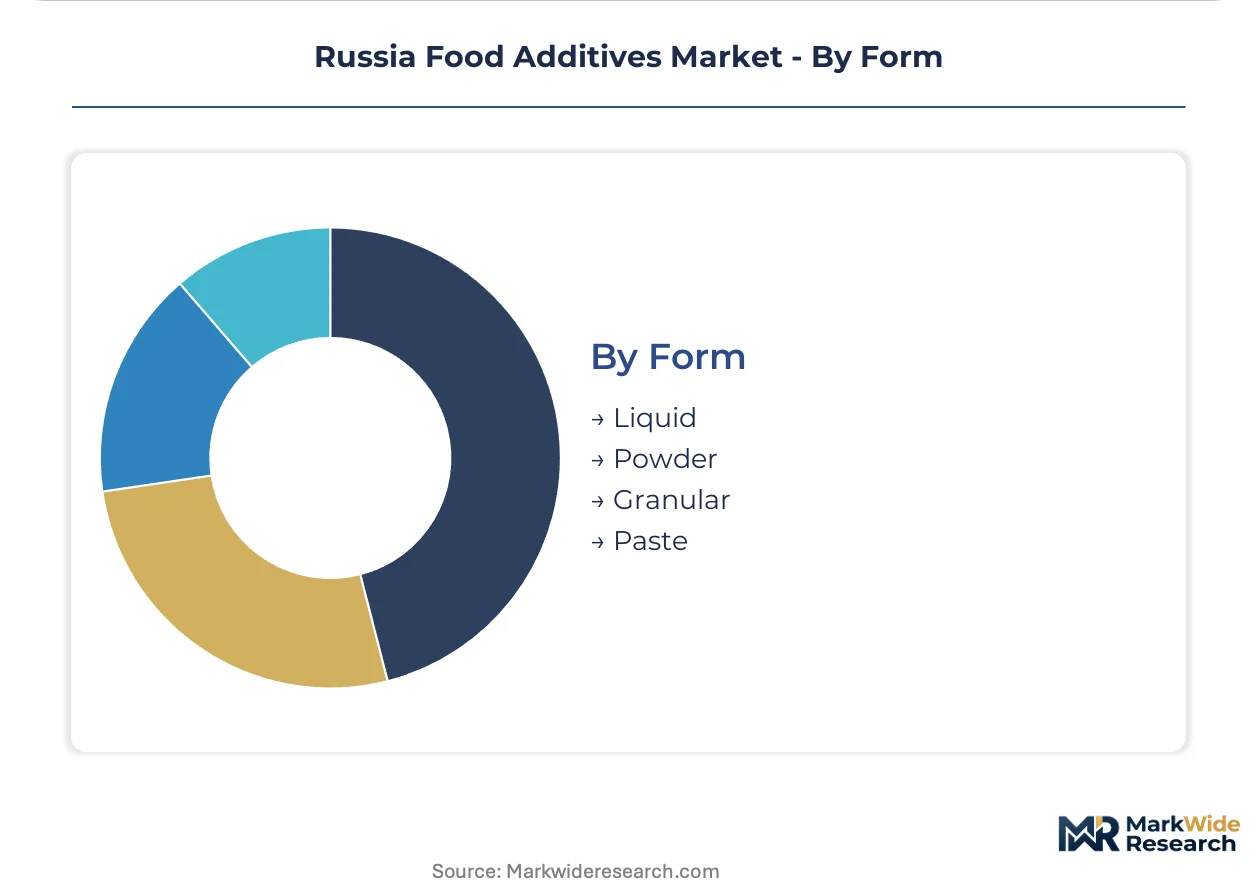
Form:
Physical presentation shapes handling infrastructure, dissolution kinetics, and compatibility with specific manufacturing equipment.
- Liquid:Pumpable concentrates and solutions enable precise dosing in continuous processing lines. Beverage and dairy applications in high-throughput Moscow facilities favor liquid systems for rapid dispersion.
- Powder:Free-flowing particulates offer extended stability and flexible reconstitution across bakery and dry mix applications. Spray-dried emulsifiers and encapsulated flavors dominate procurement for powder-compatible processes.
- Granular:Intermediate particle size reduces dusting while maintaining rapid dissolution compared to coarse powders. Limited penetration reflects narrow application specificity in Russian processing infrastructure.
- Paste:Semi-solid concentrates deliver high active loading for specialized textural modifications. Bakery shortenings and confectionery applications employ paste formats for fat-phase incorporation.
Powder absorbs the bulk of installed capacity; liquid is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's food additive production concentrates in the Central Federal District while consumption spreads across eight federal districts with divergent processing sophistication. Domestic fermentation capacity lags behind formulation demand, creating import dependency for specialty hydrocolloids and high-purity sweeteners.
Central Federal District
Moscow and the surrounding oblast host the densest food processing clusters and additive distribution infrastructure. EAEU technical regulation harmonization proceeds through the Ministry of Industry and Trade's conformity assessment procedures. Large-scale dairy and beverage manufacturers in Podolsk and Domodedovo drive concentrated procurement of clean-label emulsifier systems.
Volga Federal District
Samara and Kazan processing facilities are consolidating regional milk collection networks into industrial-scale dairy operations. Federal industrial development programs channel capital toward import substitution in citric acid fermentation. Underpenetrated stabilizer demand is attracting technical service investments from global suppliers seeking volume commitments.
Northwestern Federal District
St. Petersburg anchors formulation expertise for clean-label transitions, though regional processors report margin pressure from centralized retail procurement. Rospotrebnadzor's expanded sulfite allergen labeling enforcement affects bakery and dried fruit operations. Tier-2 dairy manufacturers in Leningrad oblast face compressed supplier negotiation cycles.
Siberian Federal District
Extended distribution cycles to remote population centers create specialized demand for hurdle-technology preservation systems. Convenience food manufacturers in Novosibirsk and Krasnoyarsk combine modified atmosphere packaging with bioprotective cultures. Logistics infrastructure gaps limit just-in-time additive delivery to smaller processors.
Ural Federal District
Yekaterinburg serves as a distribution node for compound feed and food processing additives serving the mining belt's concentrated workforce. Regional oil and fat processors require antioxidant portfolios tailored to local stability challenges. Import substitution incentives are redirecting sourcing patterns toward domestic fermentation capacity.
Russia Food Additives Market Competitive Landscape
Top-tier vendors anchor technical service relationships through application laboratories and reformulation support, while mid-tier commodity suppliers compete on volume pricing and distribution reach. The vendor base stratifies across global ingredient conglomerates with EAEU regulatory navigation capabilities, regional compounders leveraging import substitution incentives, and domestic fermentation startups scaling citric acid and sorbic acid capacity. Strategic moves concentrate on long-term contract anchoring through technical partnerships and backward integration into fermentation feedstocks.
Within the premium-tier technical service segment, Cargill, Koninklijke DSM, and BASF occupy positions defined by global application infrastructure and specialized portfolio depth. Cargill exemplifies the clean-label emulsifier archetype through its Moscow-anchored dairy processor relationships. Koninklijke DSM represents enzyme technology platforms that reduce additive loadings in bakery applications. BASF anchors antioxidant specialization for oil and fat stability challenges. These three firms illustrate how regulatory navigation capabilities and application laboratory proximity determine contract longevity in EAEU compliance-driven procurement.
| Leading Market Players |
|---|
| Tate & Lyle |
| Koninklijke DSM |
| Cargill |
| Avangard Group of Companies |
| International Flavors and Fragrances |
| Archer Daniels Midland |
| Givaudan |
| Symrise |
| BASF |
| Others |
Value Network & Pricing Analysis
Guar gum and xanthan gum import costs cascade through Russian compounder pricing tiers, with Baltic port congestion surcharges compressing margins on standard-grade hydrocolloids while premium clean-label emulsifiers retain pricing power through technical service bundling.
Pricing Analysis
Margin tightening in commodity emulsifiers reflects centralized procurement consolidation by Magnit and X5 Retail Group headquarters. Three-tier pricing structure across premium, standard, and economy levels separates Cargill-anchored technical partnerships from volume-driven phosphate blend suppliers. Price differentiation hinges on GOST-R certification completion and EAEU regulatory navigation support. Cost-down pressure on synthetic preservatives accelerates because natural antioxidant alternatives command 15-25% premiums for inferior frying stability. Retail private label manufacturers exhibit highest price sensitivity; dairy processors seeking clean-label reformulation show lowest.
Supply Chain Analysis
Reverse logistics for fermentation-derived additives remains underdeveloped, with spent yeast biomass and citric acid mother liquor lacking established recovery pathways. Supply concentrates in India, China, and domestic Volga Federal District fermentation startups. Raw material dependencies span corn feedstock for citric acid, molasses for yeast cultures, and guar seed from Rajasthan. Single-source vulnerability pervades specialty hydrocolloids through Mumbai-Antwerp-Riga shipping corridors. Distribution runs through Moscow-anchored compounder warehouses serving Central Federal District processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EAEU Technical Regulation 029/2013 erects a compliance moat that rewards incumbent suppliers with established conformity assessment navigation while filtering speculative entrants lacking regulatory affairs infrastructure.
For Market Incumbents: Cement long-term contract anchoring through Moscow-proximate application laboratories offering reformulation support. Threats concentrate in Indian and Chinese hydrocolloid suppliers capturing import substitution incentives. Leverage backward integration into fermentation feedstocks to defend margin position against commodity pricing cycles. For New Entrants and Emerging Players: Enter via Volga Federal District dairy clusters in Samara and Kazan where stabilizer demand outpaces technical service supply. The most penetrable segment comprises regional milk processors consolidating collection networks into industrial-scale operations. Go-to-market positioning should emphasize EAEU compliance bundling rather than price competition. For Investors and Strategic Acquirers: Federal industrial development program announcements for domestic citric acid capacity are the leading indicator that import substitution momentum is accelerating. Long-term viability favors compounders with captive fermentation infrastructure and GOST-R certification track records. Acquisition targets should demonstrate established Rospotrebnadzor relationships and EAEU technical regulation expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Application Laboratory Expansion | Moscow-proximate facilities anchor Cargill's technical service contracts with dairy reformulation clients. |
| Fermentation Capacity Buildout | Volga Federal District citric acid plants capture federal import substitution capital allocations. |
| Regulatory Navigation Partnership | EAEU conformity assessment expertise filters supplier qualification for cross-border procurement. |
| Clean-Label Portfolio Repositioning | Lecithin and mono-diglyceride systems displace synthetic emulsifiers under tightened labeling mandates. |
| Centralized Procurement Consolidation | Magnit and X5 headquarters-level sourcing compresses supplier negotiation cycles for tier-2 processors. |
Research Methodology
Document review covered EAEU technical regulations, Rospotrebnadzor sanitary-epidemiological standards, GOST-R certification databases, and customs import records, complemented by interviews with food processing R&D directors, procurement leads at Central Federal District dairy manufacturers, compounder distribution managers, and regulatory affairs consultants. Secondary validation drew from trade association publications, federal industrial development program disclosures, and Eurasian Economic Union conformity assessment procedures. Bottom-up volume modeling triangulated against top-down market sizing across ingredient categories.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework. Segmentation dimensions modeled include product type, application category, end-user archetype, and physical form across the projection horizon. CAGRs derived from volume trajectory analysis incorporating reformulation cycle timing, regulatory enforcement phase-ins, and import substitution incentive disbursement schedules. Industry-specific forecast inputs encompassed EAEU technical regulation amendment pipelines and federal fermentation capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Baltic port logistics disruptions, ruble volatility episodes, and accelerated EAEU labeling mandate enforcement. Practitioners should monitor Rospotrebnadzor draft regulation releases, federal subsidy program announcements, and Indian monsoon patterns affecting guar seed harvests for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
Russia Feed Additives Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
United States Anti-Caking Market