
 Carmine Alternatives Market | 2026-2036
Carmine Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Carmine Alternatives Market Outlook
Clean-label food and beverage manufacturers are reorganizing procurement priorities around non-insect colorants. DDW The Color House leverages extensive natural colorant libraries to anchor European bakery and dairy accounts. GNT Group specializes in vertically integrated beetroot and paprika supply chains that sustain volume commitments to multinational confectionery buyers. Chr. Hansen Holding A/S dominates fermentation-derived color platforms that compete directly with traditional carmine in cultured dairy applications.
Carmine alternatives comprise plant-derived, synthetic, and mineral-based colorants engineered to replicate the red-pink hue spectrum of cochineal extract without insect-sourced ingredients. Beetroot extract delivers betalain pigments suited to heat-stable beverage applications, while paprika extract provides carotenoid-based orange-red tones common in processed meats and savory formulations. Powder formulations lead current volume owing to extended shelf stability and standardized dosing protocols, though liquid concentrates represent the fastest-growing format as beverage manufacturers retrofit existing dosing equipment. Synthetic sources retain entrenched positions in pharmaceutical tablet coatings where batch-to-batch consistency overrides clean-label positioning.
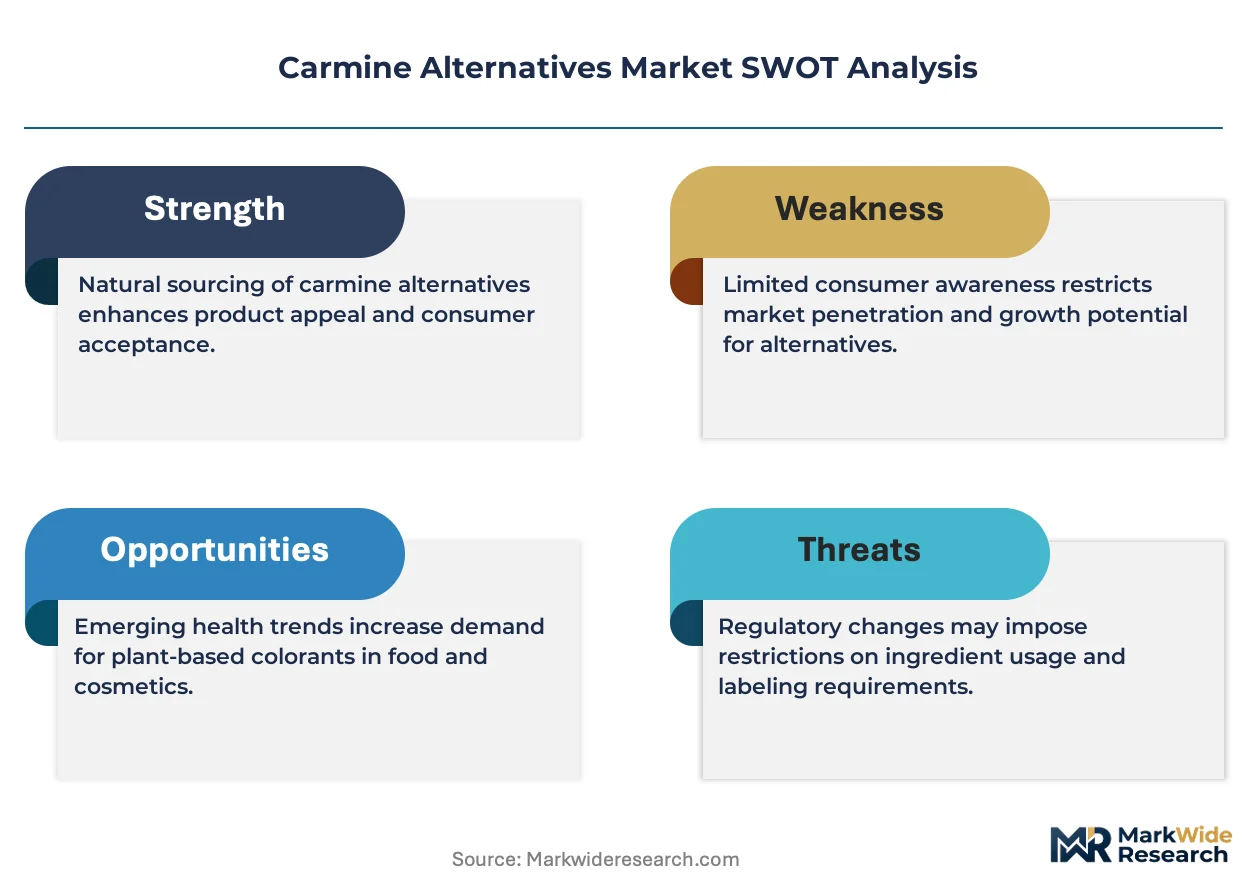
EU EFSA disclosure mandates and US FDA labeling requirements for cochineal and carmine in foods and cosmetics have redirected formulation budgets toward certified plant-based substitutes. REACH compliance and EU Green Deal sustainability reporting obligations further constrain mineral-based and petroleum-derived colorant pathways in European personal care markets. Stakeholders must monitor evolving definitions of natural claims across regulatory jurisdictions while building dual-source qualification programs that hedge against supply interruptions in concentrated agricultural growing regions.
Market Dynamics
Clean-label disclosure mandates from EFSA and FDA are compressing formulation timelines as manufacturers must certify non-insect colorant supply chains before product relaunches.
Growth Catalysts
- EFSA Allergen Labeling Expansion:EU mandates requiring explicit cochineal and carmine disclosure on packaged foods are forcing confectionery brands to reformulate with beetroot and paprika derivatives.
- Fermentation-Derived Platforms:Precision fermentation technologies for carotenoid and betalain production are achieving cost parity with agricultural extraction for dairy applications.
- Western European Retail Consolidation:Supermarket private-label programs in Germany, France, and the Netherlands are standardizing plant-based colorant specifications across supplier bases.
Market Restraints
- Agricultural Input Volatility:Beetroot and paprika harvest yields in Poland and Spain fluctuate with drought cycles, creating pigment concentration inconsistency.
- Technical Color Stability:Plant-derived alternatives lack the pH and heat resilience of cochineal in high-temperature meat curing processes.
- REACH Registration Burden:Novel fermentation-derived colorants face extended toxicity testing timelines and documentation costs before EU market authorization.
Strategic Opportunities
- US Beverage Retrofit Wave:Soft drink and ready-to-drink cocktail manufacturers are converting liquid dosing systems to accept concentrated anthocyanin and beetroot formulations.
- EU Green Deal Procurement Incentives:Public sector foodservice contracts now award preference points for certified sustainable colorant sourcing.
- Encapsulation-Convergence:Microencapsulation technologies paired with spray-drying systems are opening oil-soluble paprika applications in plant-based meat analogues.
Industry Challenges
- Fermentation Scale-Up Talent Gap:Bioprocess engineers with industrial-scale pigment production experience command premium compensation and extended recruitment cycles.
- Dual-Source Qualification Complexity:Manufacturers must maintain parallel approved suppliers for beetroot and paprika to hedge against climate-driven crop failures.
- Legacy Equipment Retrofit Costs:Powder-to-liquid conversion in existing dosing infrastructure requires capital expenditure that mid-tier ingredient suppliers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carmine Alternatives Market |
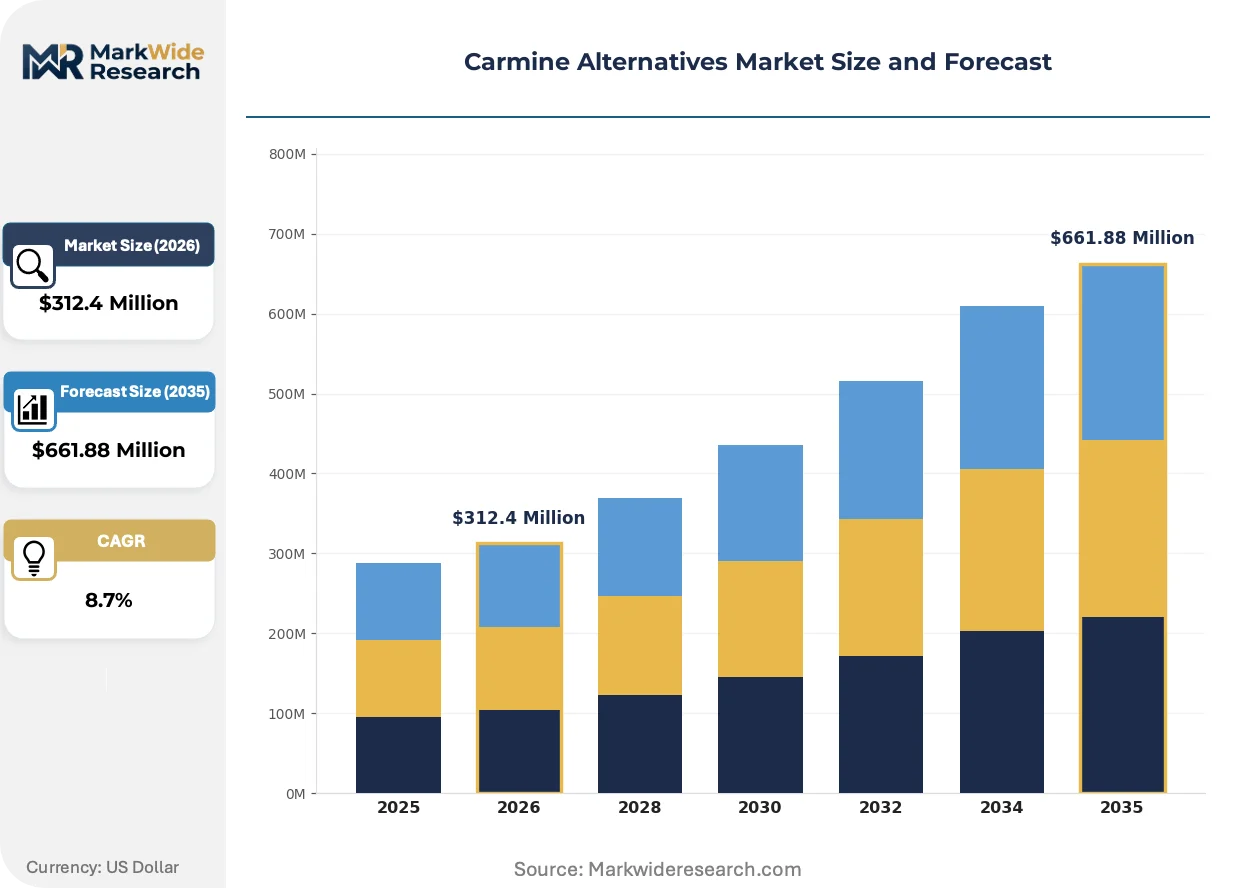
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beetroot Extract, Paprika Extract, Annatto Extract, Turmeric Extract Application: Food & Beverages, Cosmetics, Pharmaceuticals, Nutraceuticals Source: Plant-Based, Synthetic, Mineral-Based, Organic Form: Powder, Liquid, Paste, Granule |
| Companies Covered | DDW The Color House, Kalsec, Givaudan, GNT Group, Archer Daniels Midland Company, Chr. Hansen Holding A/S, FMC Corporation, Roha Dyechem Pvt. Ltd., Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carmine Alternatives Market Strategic Shifts
Formulation science is diverging toward bioengineered pigments and advanced stabilization systems that narrow the performance gap with insect-derived colorants.
Precision fermentation for carotenoid production is fragmenting the traditional agricultural extraction value chain. Cultured dairy and alternative protein manufacturers are adopting these platforms at accelerated qualification cycles. This technology is fragmenting supplier hierarchies by enabling chemical companies to bypass crop procurement entirely.
EFSA's 2023 updated guidance on novel food assessments is extending safety dossier requirements for fermentation-derived colorants. The regulatory friction is compressing launch timelines for new entrants. Personal care applications in France and Germany are experiencing the most significant reformulation delays as brands await positive opinions.
Ingredient buyers are consolidating supplier relationships around vertically integrated colorant houses with captive agricultural or bioreactor capacity. Long-term offtake agreements are displacing spot-market purchasing in confectionery and bakery procurement departments. This pattern is most pronounced in Dutch and Belgian processing clusters where margin pressure from retailers demands supply security.
Carmine Alternatives Market Segmentation
Colorant substitution pressures vary sharply across product categories, with heat-sensitive applications demanding entirely different technical specifications than shelf-stable formats. Procurement teams segment supplier qualification programs around stability thresholds and regulatory disclosure burdens rather than hue matching alone.
Product Type:
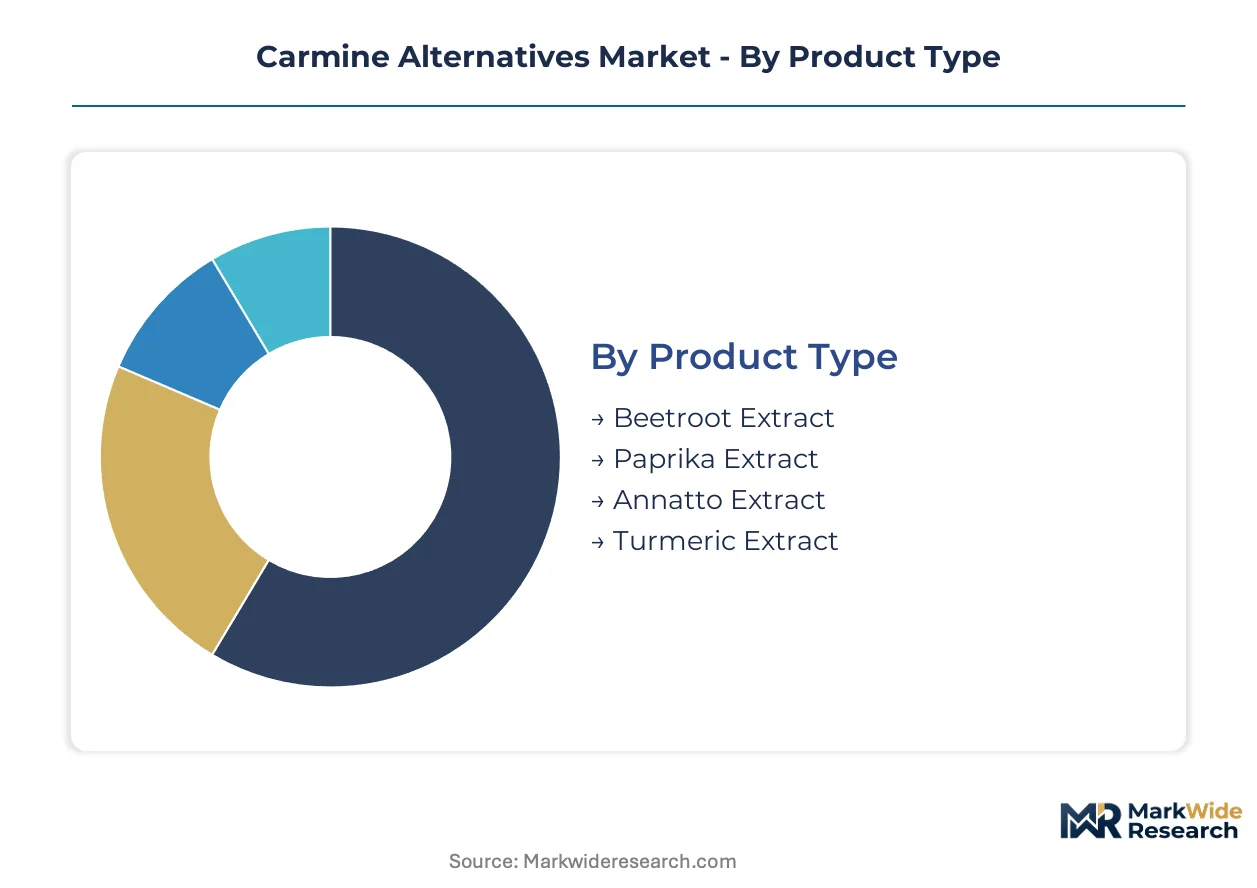
Beetroot and paprika extracts face the most intense substitution pressure as direct carmine replacements in European confectionery, while turmeric and annatto serve adjacent color spaces with lower technical barriers.
- Beetroot Extract:Betalain pigments deliver violet-red tones with moderate heat stability up to 75°C, making them suitable for dairy and beverage applications where pasteurization temperatures remain controlled. German and Dutch dairy processors have standardized beetroot specifications across private-label yogurt and ice cream lines following EFSA disclosure mandates for cochineal.
- Paprika Extract:Carotenoid-based orange-red colorants provide superior light stability compared to beetroot, dominating processed meat and savory snack formulations where extended retail shelf exposure is unavoidable. Spanish paprika cooperatives in Murcia and Extremadura have expanded extraction capacity to meet French and Italian sausage manufacturer demand.
- Annatto Extract:Bixin and norbixin carotenoids from achiote seeds deliver yellow-orange hues common in cheese and butter applications where cost sensitivity limits premium plant-derived alternatives.
- Turmeric Extract:Curcumin-based yellow colorants face pH-driven hue shift limitations but retain entrenched positions in mustard and curry powder blends where traditional ingredient claims override technical performance.
Beetroot extract retains volume leadership; paprika extract holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity food applications from premium cosmetic and pharmaceutical segments where batch consistency commands price premiums.
- Food & Beverages:Confectionery, bakery, and dairy manufacturers drive procurement volume as EFSA and FDA labeling requirements force systematic reformulation away from cochineal-derived colorants. Powder formulations dominate dry mix applications while liquid concentrates gain share in beverage retrofit programs.
- Cosmetics:Lipstick and blush formulations demand high pigment loadings with minimal staining, pushing formulators toward encapsulated paprika and beetroot derivatives that replicate carmine's adhesion properties.
- Pharmaceuticals:Tablet coatings and liquid suspensions prioritize batch-to-batch color consistency over clean-label positioning, preserving synthetic dye positions despite regulatory pressure.
- Nutraceuticals:Gummy and softgel applications combine colorant functions with antioxidant marketing claims, favoring turmeric and beetroot for their dual-purpose ingredient profiles.
Food and beverage applications command procurement volume; cosmetics represents the fastest-growing trajectory as clean beauty standards tighten.
Source:
Supply concentration in agricultural growing regions creates vulnerability patterns that reshape qualification strategies across synthetic and mineral alternatives.
- Plant-Based:Agricultural extraction from beetroot, paprika, and turmeric biomass dominates European procurement as REACH compliance burdens constrain synthetic pathways. Polish and Spanish crop cycles introduce pigment concentration variability that fermentation platforms aim to eliminate.
- Synthetic:Petroleum-derived azo and triarylmethane dyes retain pharmaceutical and industrial applications where regulatory disclosure requirements remain less stringent than food and cosmetic sectors.
- Mineral-Based:Iron oxide and titanium dioxide preparations serve limited niche applications in cosmetics and coatings, constrained by EU Green Deal sustainability reporting obligations on mined inputs.
- Organic:Certified organic plant extracts command price premiums in premium confectionery and baby food segments where retailer specifications exceed baseline regulatory requirements.
Plant-based sources retain volume leadership; fermentation-derived platforms within this category are climbing the fastest as bioprocess scale-up matures.
Form:
Equipment retrofit economics separate powder-dominant legacy infrastructure from liquid-concentrate growth in greenfield beverage facilities.
- Powder:Spray-dried and drum-dried formulations provide extended shelf stability and standardized dosing protocols, dominating bakery and dry mix applications where moisture control is critical.
- Liquid:Concentrated extracts and emulsions enable direct injection into existing beverage processing lines, with German and US soft drink manufacturers leading conversion investments.
- Paste:High-viscosity preparations serve artisanal confectionery and small-batch cosmetic producers with limited capital for dosing system upgrades.
- Granule:Agglomerated formats reduce dust exposure in industrial handling environments, common in large-scale meat processing and seasoning blend operations.
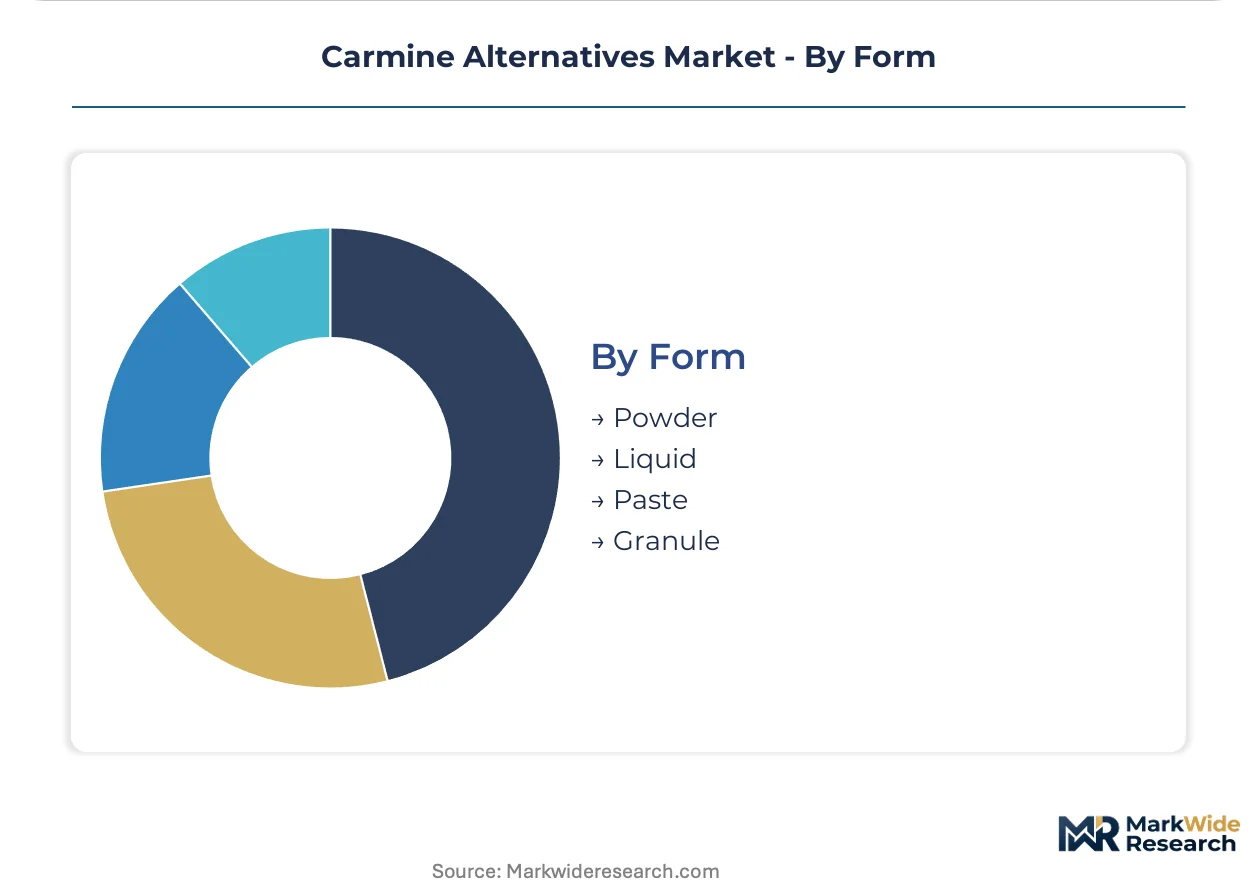
Powder retains volume leadership; liquid holds the steepest expansion curve as beverage retrofit programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beetroot and paprika extraction capacity clusters in Poland and Spain, creating pigment supply vulnerability that fermentation platforms in Germany and the Netherlands aim to offset. EFSA disclosure mandates have compressed formulation timelines across Western European confectionery and dairy processing.
Germany
Dairy processors in Bavaria and Lower Saxony drive beetroot extract procurement for private-label yogurt lines following EFSA allergen labeling expansion. The country's Federal Ministry of Food and Agriculture enforces strict novel food assessment protocols for fermentation-derived colorants. Cologne and Hamburg host ingredient distribution hubs that coordinate just-in-time deliveries to Dutch and Belgian confectionery clusters.
France
Cosmetic formulators in Île-de-France demand encapsulated paprika derivatives for lipstick and blush applications as clean beauty standards tighten. ANSM maintains extended safety dossier requirements for biotech-derived colorants entering personal care markets. Lyon and Marseille processing facilities specialize in high-pigment-load emulsions for premium cosmetic brands.
United States
Soft drink manufacturers in Georgia and Texas retrofit liquid dosing systems to accept concentrated anthocyanin and beetroot formulations. FDA labeling requirements for cochineal and carmine in foods and cosmetics redirect beverage formulation budgets toward certified plant-based substitutes. Chicago and New Jersey ingredient terminals manage cross-border distribution to Canadian dairy processors.
Netherlands
Supermarket private-label programs in Randstad standardize plant-based colorant specifications across pan-European supplier bases. EU Green Deal procurement incentives award preference points for certified sustainable colorant sourcing in public sector foodservice contracts. Wageningen University research clusters accelerate microencapsulation technology transfer to regional colorant houses.
Spain
Paprika cooperatives in Murcia and Extremadura expanded extraction capacity to meet French and Italian sausage manufacturer demand. The country's agricultural ministry monitors drought cycles that create pigment concentration inconsistency in domestic harvests. Barcelona and Valencia serve as export logistics nodes for Mediterranean-facing confectionery buyers.
Carmine Alternatives Market Competitive Environment
Concentration sits with vertically integrated colorant houses possessing captive agricultural or bioreactor capacity. The supplier base fragments across regional extraction specialists, multinational flavor houses, and emerging fermentation platforms. Two strategic archetypes dominate: heritage natural colorant houses with deep beetroot and paprika supply chains, and biotech entrants scaling precision fermentation for carotenoid production. Competitive moves center on long-term offtake agreements displacing spot-market purchasing, and backward integration into Polish and Spanish agricultural sourcing.
Within the heritage integrated tier, DDW The Color House and GNT Group exemplify suppliers with extensive natural colorant libraries and vertically controlled agricultural supply chains. Chr. Hansen Holding A/S occupies a position representing fermentation-derived platform specialists competing directly with traditional extraction methods. These three entities anchor the competitive structure that smaller regional extraction cooperatives and multinational flavor houses must navigate.
| Leading Market Players |
|---|
| DDW The Color House |
| Kalsec |
| Givaudan |
| GNT Group |
| Archer Daniels Midland Company |
| Chr. Hansen Holding A/S |
| FMC Corporation |
| Roha Dyechem Pvt. Ltd. |
| Sensient Technologies Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German dairy processors and Polish beetroot cooperatives lock in multi-year pigment supply access while capping price volatility exposure ahead of EFSA disclosure mandate deadlines. These contractual structures concentrate procurement power with vertically integrated colorant houses capable of guaranteeing volume commitments across variable agricultural harvest cycles.
Pricing Analysis
Volume-discount tiering structures separate multinational confectionery buyers securing sub-economy pricing through five-year supply commitments from mid-tier bakery operators purchasing on quarterly contracts. Certification grade differentiation—conventional versus EU organic—creates pricing spreads that fermentation-derived alternatives exploit as they bypass agricultural input volatility. Cost compression in commodity beetroot extract runs through Polish crop yield instability, while premium paprika derivatives face less price sensitivity from French cosmetic formulators demanding encapsulated stability profiles.
Supply Chain Analysis
Just-in-time inventory strategies dominate Dutch and Belgian confectionery clusters where Randstad distribution hubs coordinate daily pigment deliveries, though Spanish paprika cooperatives maintain strategic stockpiles against Murcia drought cycles. Geographic concentration in Polish beetroot fields and Extremadura pepper regions creates single-source vulnerability for European natural colorant procurement. Raw material dependencies on seasonal agricultural biomass, fermentation feedstock sugars, and specialized spray-drying equipment tether output capacity to climate-driven harvest windows. Distribution runs through Cologne and Hamburg terminals serving pan-European dairy and meat processing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment—specifically EFSA allergen labeling mandates and REACH novel food assessment protocols—creates switching costs that protect qualified supplier relationships against price-based displacement.
For Market Incumbents: Consolidate backward integration into Polish beetroot and Spanish paprika agricultural sourcing to defend margin position against fermentation platform entrants achieving cost parity. Prioritize capacity reservation agreements with Murcia cooperatives before drought cycles tighten pigment concentration availability. Lock in multi-year offtake structures with Dutch supermarket private-label programs to preempt spot-market competitors. For New Entrants and Emerging Players: Anchor in US beverage retrofit demand where Georgia and Texas soft drink manufacturers seek liquid anthocyanin concentrates compatible with existing dosing infrastructure. Target mid-tier nutraceutical gummy producers in North America with dual-purpose beetroot colorant-antioxidant positioning that commands premium pricing over commodity synthetic dyes. Pursue direct technical sales partnerships with equipment retrofit specialists rather than commodity ingredient distribution. For Investors and Strategic Acquirers: Fermentation-derived colorant specialists with demonstrated bioreactor scale-up capability represent the most defensible acquisition archetype as precision platforms fragment traditional agricultural extraction value chains. Long-term viability hinges on regulatory approval velocity for novel food dossiers across EU member states. Watch EFSA positive opinion publication timelines for fermentation-derived carotenoid platforms as the critical inflection signal distinguishing scalable biotech assets from stranded R&D expenditures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Sourcing | Captive beetroot and paprika supply chains insulate German and Dutch processors from Polish drought-driven pigment concentration volatility. |
| Fermentation Platform Scale-Up | Precision bioreactor capacity in the Netherlands and Germany bypasses climate-dependent harvest cycles that constrain Spanish extraction cooperatives. |
| Long-term Supply Agreement with Retail Consolidators | Randstad supermarket private-label standardization locks in volume commitments across pan-European confectionery and dairy accounts. |
| Encapsulation Technology Investment | Microencapsulation paired with spray-drying systems opens oil-soluble paprika applications in French cosmetic and plant-based meat analogue formulations. |
| Novel Food Regulatory Dossier Submission | EFSA approval pathways for fermentation-derived colorants determine market access velocity for biotech entrants competing with established extraction methods. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with German dairy procurement directors, French cosmetic formulators, Dutch supermarket category managers, Spanish agricultural cooperative leaders, and US beverage R&D heads. Secondary validation drew from EFSA novel food guidance documents, FDA labeling requirement filings, EU Green Deal procurement incentive specifications, REACH registration databases, and customs trade flow records for beetroot and paprika extract shipments. Bottom-up pigment volume estimates triangulated against top-down colorant market sizing derived from downstream food and cosmetic production data.
Across the analysis window, the forecast framework modeled segmentation dimensions spanning colorant source type, formulation stability grade, end-use application, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of substitution rates away from cochineal-derived colorants, calibrated against EFSA and FDA mandate implementation timelines. Industry-specific inputs included fermentation platform cost curve projections, Polish and Spanish agricultural yield variance patterns, and beverage equipment retrofit investment cycles.
Underlying assumptions cover sustained EFSA disclosure mandate enforcement and stable fermentation technology cost reduction trajectories, with deviation risk concentrated in extended novel food safety dossier timelines and climate-driven crop yield collapses. Revision becomes warranted when regulatory approval velocity for biotech-derived colorants crosses thresholds that materially accelerate or delay platform substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Phytogenic Feed Additives Market