
 Food and Beverage Air Filtration Market | 2026-2036
Food and Beverage Air Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverage Air Filtration Market Foresight
FSMA compliance is rebalancing capital allocation toward validated air filtration architectures in U.S. food processing. Donaldson Company leverages its agricultural and industrial heritage to anchor positions in grain handling and snack manufacturing facilities. Parker-Hannifin sustains engineering depth across pneumatic and filtration integration for beverage bottling lines. MANN+HUMMEL dominates European-origin membrane and adsorption technologies that compete on total cost of ownership in dairy cleanrooms.
Food and Beverage Air Filtration encompasses engineered media and systems designed to remove particulates, microorganisms, volatile organic compounds, and odors from air streams entering or circulating within production environments, typically achieving filtration efficiencies from MERV 13 through HEPA H14 depending on risk zone classification. HEPA Filters and Activated Carbon Filters lead product type value pools due to their codified status in hazard analysis protocols, while HVAC Integration outpaces standalone deployment as retrofit demand surges in legacy plants. Beverage Production and Dairy Processing command disproportionate application spending because liquid product vulnerability to airborne spoilage organisms mandates continuous positive-pressure air management.
FDA, EPA, and OSHA frameworks collectively determine filtration performance thresholds, maintenance documentation, and worker exposure limits that shape procurement specifications in U.S. facilities. EMA and EFSA standards in Europe impose parallel microbial air quality benchmarks that filter manufacturers must satisfy for CE-marked equipment access. Stakeholders should monitor evolving alignment between FDA draft guidance on environmental monitoring and ISO 14698 cleanroom standards, as convergence or divergence will redirect R&D spending toward either unified global platforms or region-specific certification stacks.
Market Dynamics
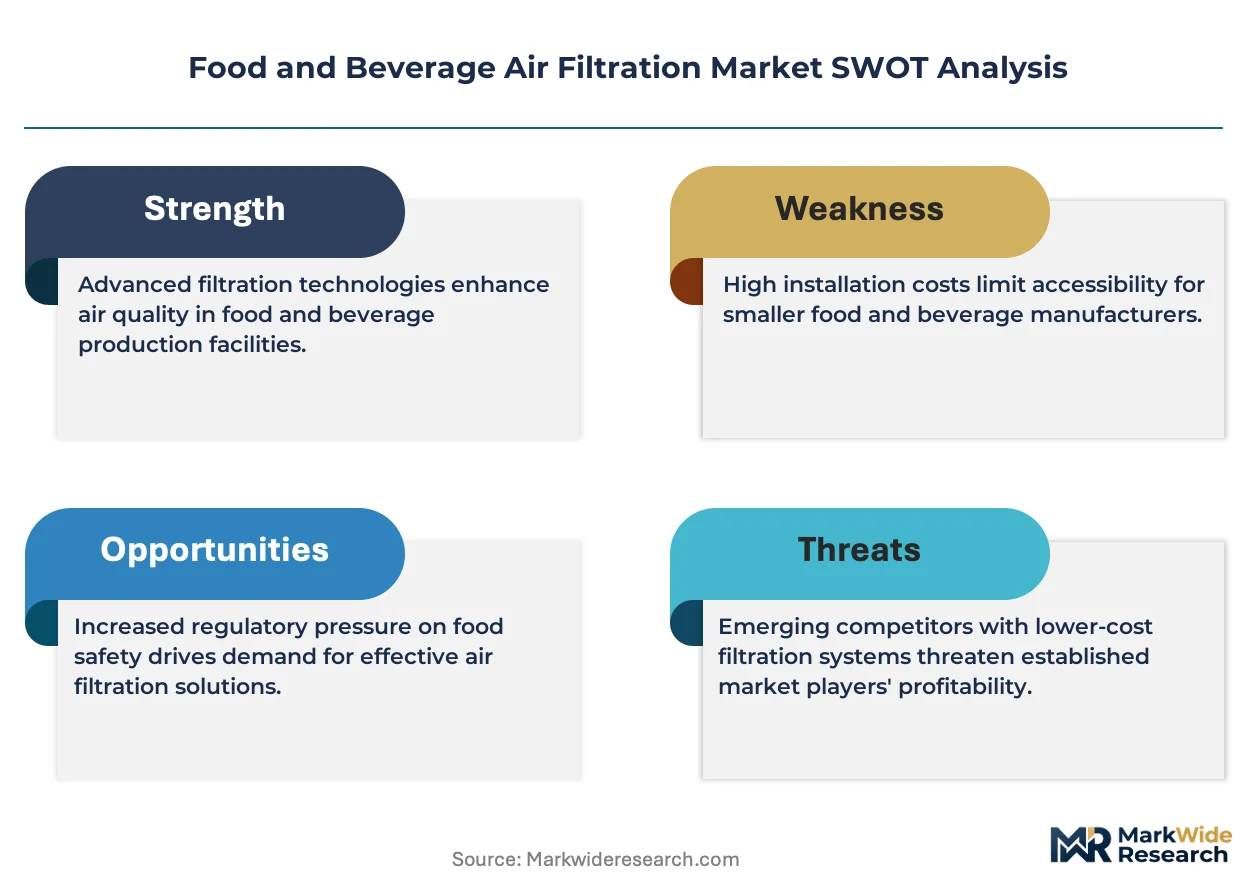
FSMA enforcement is compressing replacement cycles for legacy HVAC filtration systems as processors face documented environmental monitoring mandates and third-party audit requirements that tie air quality directly to facility operating permits.
Growth Catalysts
- Microbial safety mandates:FDA Food Safety Modernization Act inspection protocols now explicitly score airborne contamination controls, forcing beverage bottlers and dairy processors to upgrade filtration architectures ahead of schedule.
- Grain handling expansion:North American ethanol and specialty grain processing capacity additions are driving demand for explosion-rated filtration systems in pneumatic conveying applications.
- Activated carbon adsorption:Odor abatement requirements in urban-adjacent food plants are accelerating deployment of hybrid HEPA-carbon configurations for volatile organic compound capture.
Market Restraints
- Membrane supply concentration:European and Japanese suppliers control high-efficiency glass microfiber media production, exposing buyers to extended lead times and freight cost volatility.
- Technical performance ceilings:H14 HEPA filters face pressure-drop limitations that restrict airflow capacity in high-volume meat processing chillers without ductwork redesign.
- Substitution by UV-C systems:Upper-room ultraviolet germicidal irradiation is displacing filtration in certain low-risk zones, compressing addressable volume in warehouse and storage applications.
Strategic Opportunities
- Cleanroom dairy expansion:Wisconsin and California cheese processors are constructing ISO 14698-compliant environments that demand validated HEPA terminal filtration with continuous particle monitoring.
- Service contract unbundling:Filter replacement and validation documentation are separating from OEM equipment sales, creating recurring revenue pools for specialized service providers.
- CE marking convergence:Alignment between FDA draft guidance and EU cleanroom standards is enabling unified product platforms that reduce certification costs for multinational suppliers.
Industry Challenges
- Commissioning validation timelines:FDA-required installation qualification and operational qualification documentation for HEPA systems extends project completion by four to eight weeks.
- Retrofit integration complexity:Legacy meat processing plants built before 1990 lack structural capacity for modern air handling unit loads, requiring costly reinforcement or partial reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverage Air Filtration Market |
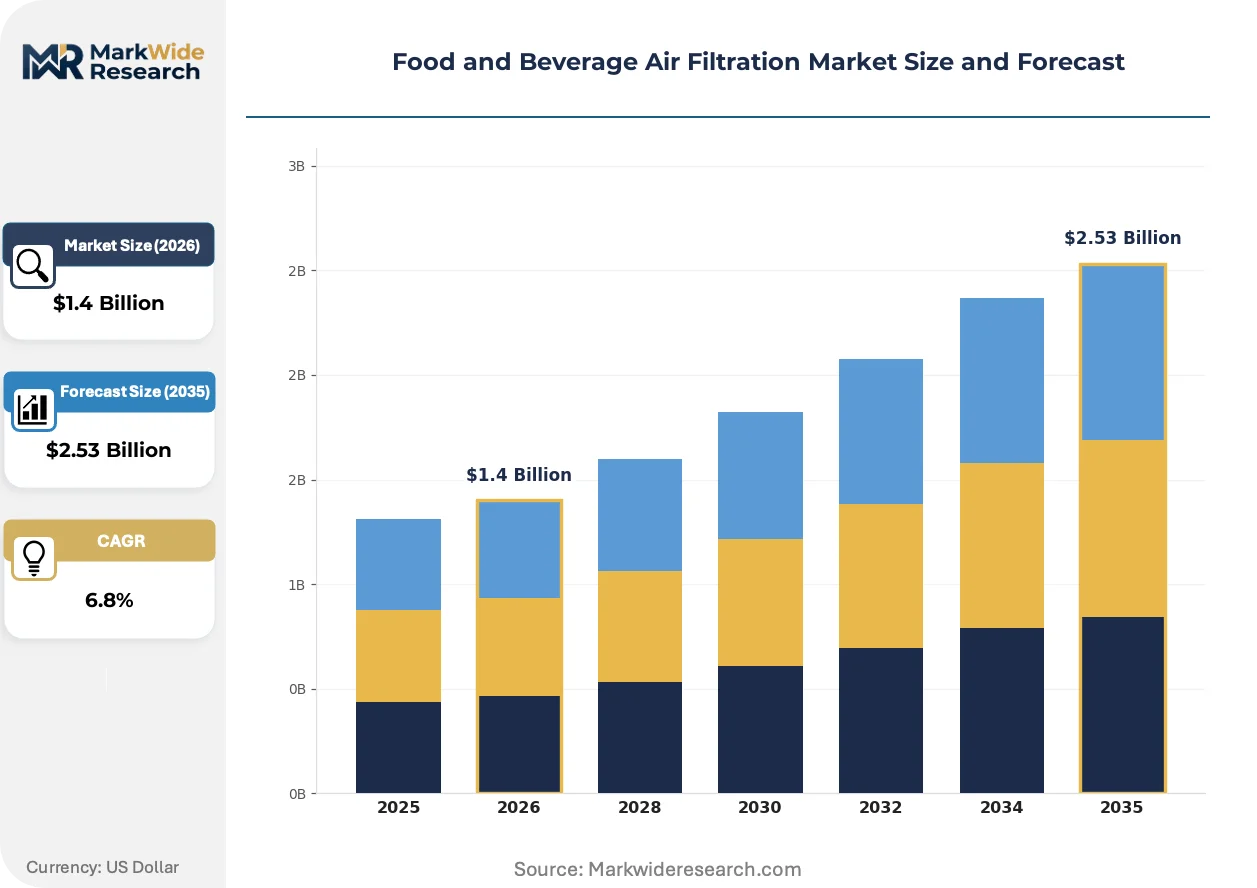
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
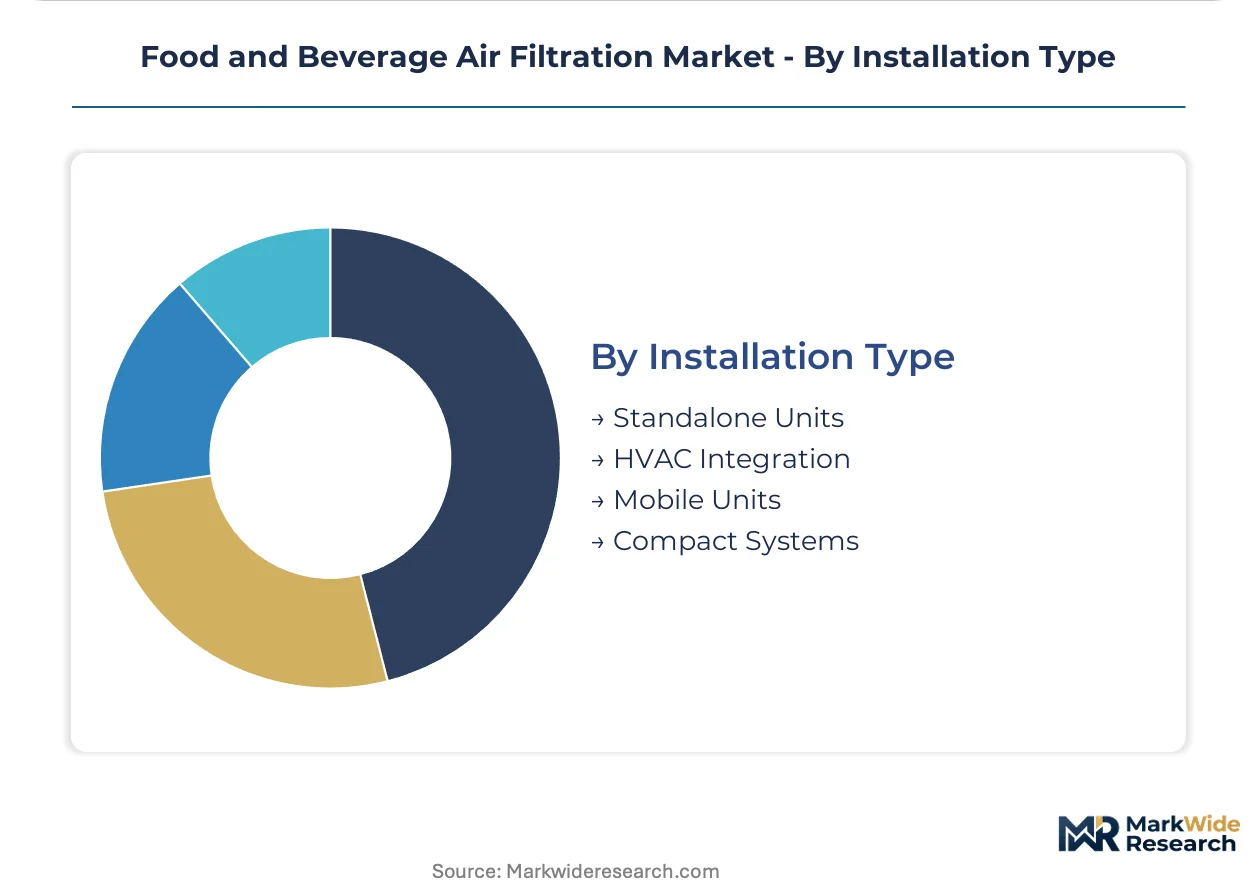
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, UV Air Purifiers, Electrostatic Precipitators, Ionizers Application: Beverage Production, Dairy Processing, Meat Processing, Snack Manufacturing, Brewing End User Industry: Food Processing Plants, Packaging Facilities, Cold Storage Units, Flavoring Operations Installation Type: Standalone Units, HVAC Integration, Mobile Units, Compact Systems |
| Companies Covered | Donaldson Company, Inc., Parker-Hannifin Corporation, 3M, MANN+HUMMEL, Porvair Filtration Group Ltd., Camfil Group, Freudenberg Filtration Technologies, AAF International, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverage Air Filtration Market Shifts & Advancements
Filtration system architecture is fragmenting into configurable sub-assemblies that processors can scale across risk zones without full facility redesign, compressing capital deployment timelines and enabling phased compliance investments.
Modular HEPA fan filter units are modularizing cleanroom construction for beverage producers. Craft breweries and kombucha facilities are adopting standardized ceiling-grid modules that install without dedicated HVAC contractors. This approach is modularizing what previously required centralized duct engineering, cutting deployment costs for mid-scale producers.
REACH restrictions on fluorinated compounds are pressuring membrane manufacturers to reformulate hydrophobic coatings used in high-humidity dairy applications. ECHA substance evaluation timelines are accelerating substitution research for perfluorinated surface treatments. European filter suppliers are responding with silicone-based alternatives that trade some efficiency for regulatory compliance certainty.
Buyer consolidation among national dairy cooperatives is compressing supplier negotiation cycles and unbundling filter procurement from original equipment maintenance agreements. Large-scale cheese and fluid milk processors are establishing direct relationships with media manufacturers, bypassing traditional distribution. This pattern is most visible in the Upper Midwest, where cooperative purchasing alliances now specify filtration performance standards across multiple plant locations.
Food and Beverage Air Filtration Market Segmentation
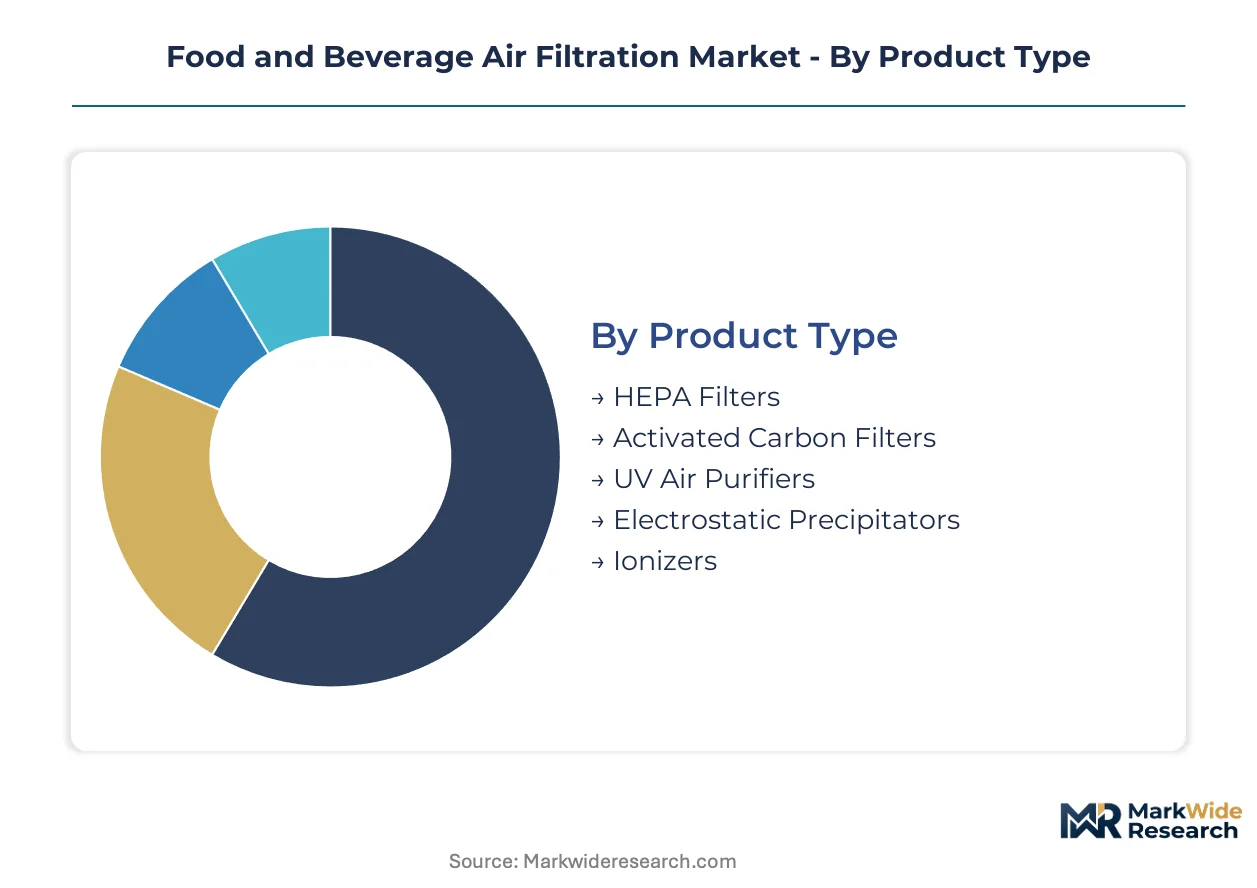
Food and beverage air filtration architectures fragment across risk-zone classifications, equipment integration depth, and facility vintage. Procurement patterns diverge sharply between greenfield ISO 14698-compliant dairy cleanrooms and legacy meat plants retrofitting explosion-rated grain handling systems.
Product Type:
Standardization dominates at the media level, while system configuration tilts toward custom-engineered pressure-drop and adsorption profiles.
- HEPA Filters:Glass microfiber media achieving H13-H14 efficiencies serve as the validated barrier against airborne spoilage organisms in beverage bottling cleanrooms. Demand concentrates in Wisconsin and California cheese processing clusters where FDA environmental monitoring mandates require continuous positive-pressure maintenance.
- Activated Carbon Filters:Impregnated carbon beds adsorb volatile organic compounds and odor molecules through physisorption and chemisorption mechanisms. Urban-adjacent snack manufacturing facilities in Illinois and New Jersey deploy hybrid HEPA-carbon configurations to satisfy municipal air quality ordinances.
- UV Air Purifiers:Upper-room germicidal irradiation systems supplement filtration in low-risk storage zones.
- Electrostatic Precipitators:Charged-collection systems handle high-particulate loads in grain pneumatic conveying.
- Ionizers:Bipolar ionization units address odor control in compact brewery taprooms.
Leading the category by volume: HEPA Filters. Growing fastest: Activated Carbon Filters.
Application:
Margin structures vary by spoilage vulnerability—liquid products command premium filtration investments over solid food matrices.
- Beverage Production:Bottled water, soft drink, and kombucha facilities require terminal HEPA filtration at filling heads to prevent yeast and mold contamination. Craft breweries in Colorado and Oregon are modularizing cleanroom construction with standardized ceiling-grid fan filter units that install without dedicated HVAC contractors.
- Dairy Processing:Fluid milk and cheese plants operate under the most stringent airborne microbial limits of any food category. California and Wisconsin processors are constructing ISO 14698-compliant environments with validated HEPA terminal filtration and continuous particle monitoring systems.
- Meat Processing:Chiller humidity and temperature cycling stress filter media in beef and pork facilities.
- Snack Manufacturing:Oil mist and particulate loads from frying operations drive pre-filtration requirements.
- Brewing:Fermentation-area bioaerosol control balances ventilation rates against energy costs.
Highest filtration intensity: Dairy Processing. Expanding most quickly: Beverage Production.
End User Industry:
Facility function determines whether air management serves product protection, worker safety, or regulatory documentation.
- Food Processing Plants:Integrated HVAC filtration systems handle make-up air and recirculation across production halls, ingredient handling, and packaging zones. Large-scale cooperatives in the Upper Midwest are establishing direct procurement relationships with media manufacturers, bypassing traditional distribution channels.
- Packaging Facilities:Secondary packaging areas require lower filtration grades but higher air change rates to manage cardboard particulate and worker comfort.
- Cold Storage Units:Low-temperature operation degrades standard media efficiency, requiring synthetic fiber formulations.
- Flavoring Operations:Volatile compound recovery and odor abatement drive activated carbon specification.
Dominant procurement volume: Food Processing Plants. Steepest compliance-driven upgrade cycle: Packaging Facilities.
Installation Type:
Capital deployment timelines stretch from immediate mobile deployment to multi-month HVAC infrastructure reconstruction.
- HVAC Integration:Centralized air handling units with banked filtration stages serve large-footprint meat and dairy plants built after 2000. Retrofit demand surges in legacy facilities where FSMA environmental monitoring mandates expose insufficient air change rates and unfiltered recirculation pathways.
- Standalone Units:Self-contained recirculating systems address localized contamination sources without ductwork modification. Craft beverage producers deploy these for phased compliance investments ahead of full facility redesign.
- Mobile Units:Portable HEPA filtration supports temporary production lines and maintenance shutdowns.
- Compact Systems:Under-ceiling and wall-mounted units fit low-headroom urban manufacturing sites.
Primary revenue pool: HVAC Integration. Gaining share fastest: Standalone Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates and bonded warehouse districts in the Netherlands are concentrating filtration system distribution hubs serving dairy and beverage exporters. These zones offer deferred duty structures that lower total landed costs for membrane media imports from Japan and Germany.
United States
FSMA inspection protocols now explicitly score airborne contamination controls, forcing beverage bottlers in Colorado and Oregon to upgrade filtration ahead of schedule. FDA draft guidance on environmental monitoring is tightening microbial air quality benchmarks. Wisconsin cheese processors are constructing ISO 14698-compliant cleanrooms with validated HEPA terminal filtration.
Germany
REACH restrictions on fluorinated compounds are pressuring membrane manufacturers to reformulate hydrophobic coatings for high-humidity dairy applications. ECHA substance evaluation timelines are accelerating substitution research. Bavarian filtration specialists are developing silicone-based alternatives that trade some efficiency for regulatory compliance certainty.
China
Dual carbon goals are driving energy-efficient air handling retrofits in Yangtze River Delta beverage plants. SAMR food safety standards are converging with ISO cleanroom benchmarks for dairy exports. Shanghai-area processors are deploying modular fan filter units to reduce HVAC energy intensity while maintaining positive-pressure environments.
India
FSSAI microbial limits for packaged beverages are tightening compliance requirements for bottling facilities in Maharashtra and Gujarat. The PLI scheme for food processing infrastructure is subsidizing cleanroom investments. Karnataka dairy cooperatives are establishing direct procurement relationships with media manufacturers, bypassing traditional distribution channels.
Brazil
ANVISA pharmaceutical-grade air quality standards are spilling over into premium dairy and juice processing regulations. São Paulo state environmental agencies are enforcing odor abatement mandates near urban manufacturing zones. Minas Gerais cheese producers are importing European membrane technologies to satisfy export market certification requirements.
Food and Beverage Air Filtration Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the filtration value chain, creating a tiered structure where scale-driven system integrators coexist with regional media suppliers. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with cross-sector filtration portfolios, European-origin membrane technology specialists, and regional HVAC integration contractors. Competitive moves center on unbundling service contracts from equipment sales and pursuing CE marking convergence to reduce certification costs for multinational deployments.
Among diversified industrial conglomerates, Donaldson Company, Inc. and Parker-Hannifin Corporation occupy positions spanning agricultural handling and pneumatic integration. MANN+HUMMEL represents the European membrane technology archetype, while 3M sits within the diversified materials science tier. These named entities exemplify how competitive positioning fragments across heritage competencies rather than converging on unified platform strategies.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Parker-Hannifin Corporation |
| 3M |
| MANN+HUMMEL |
| Porvair Filtration Group Ltd. |
| Camfil Group |
| Freudenberg Filtration Technologies |
| AAF International |
| Pall Corporation |
| Others |
Supply & Pricing Matrix
Glass microfiber media engineers concentrated in Bavaria and Stuttgart anchor European supply tiers, with labor-cost differentials between German technical specialists and Asian manufacturing technicians driving pricing spreads across HEPA certification grades.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to validated H14 HEPA filters from Japanese glass microfiber suppliers, while spot inventory discounts emerge for standard-grade HVAC media from regional distributors. A three-tier pricing structure across premium, standard, and economy levels separates FDA-validated terminal filtration with full IQ/OQ documentation from generic MERV-rated replacements and unbranded commodity media. Cost compression in the economy tier is intensifying because dairy cooperative purchasing alliances now specify performance standards across multiple plant locations, squeezing distributor markups. National dairy cooperatives exhibit the highest price sensitivity due to volume consolidation, while ISO 14698-compliant cheese processors in Wisconsin and California accept premium positioning for validated systems with continuous monitoring integration.
Supply Chain Analysis
CE marking and FDA installation qualification documentation serve as gating mechanisms that filter out uncertified regional HVAC contractors from high-value dairy cleanroom projects. High-efficiency glass microfiber media production concentrates in Germany, Japan, and the United States, with membrane coating operations drawing from fluorinated compound suppliers now facing REACH substitution timelines. Raw material dependencies include borosilicate glass fibers, activated carbon feedstocks from coconut shell and bituminous coal sources, and silicone-based hydrophobic coatings replacing perfluorinated treatments. Single-source vulnerability characterizes the H14 HEPA segment where two Japanese suppliers control premium microfiber production. Distribution runs through OEM equipment manufacturers, specialized filtration distributors, and direct procurement relationships that large-scale cooperatives are establishing with media manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food and beverage air filtration is transitioning from centralized HVAC architectures toward modular fan filter units, with UV-C upper-room germicidal irradiation displacing legacy filtration in low-risk warehouse zones.
For Market Incumbents: Anticipate margin compression in standard-grade HVAC media as dairy cooperatives consolidate procurement and bypass traditional distribution channels. Prioritize backward integration into glass microfiber membrane production to secure supply certainty against Japanese supplier lead-time volatility. Invest in silicone-based hydrophobic coating R&D ahead of ECHA perfluorinated substance restrictions to maintain European dairy market access.
For New Entrants and Emerging Players: Direct-to-craft-brewery digital channels offer white-space penetration without incumbent distributor relationships. Target Colorado and Oregon kombucha facilities adopting standardized ceiling-grid modules that install without dedicated HVAC contractors. Pursue service contract unbundling strategies separating filter replacement and validation documentation from equipment sales.
For Investors and Strategic Acquirers: The window for entry favors specialized membrane technology specialists with European regulatory compliance heritage. Long-term viability hinges on positioning for CE marking convergence between FDA draft guidance and ISO 14698 cleanroom standards. Monitor alignment timelines between FDA environmental monitoring protocols and EU benchmarks as the inflection indicator for unified global platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Cleanroom Platform Development | Craft breweries in Colorado deploy standardized ceiling-grid fan filter units without HVAC contractors. |
| Silicone-Based Membrane Coating Transition | Bavarian filtration specialists reformulate hydrophobic treatments ahead of ECHA perfluorinated restrictions. |
| Direct Procurement Channel Establishment | Upper Midwest dairy cooperatives bypass distributors to specify filtration standards across multiple plants. |
| Service Contract Unbundling | Filter replacement and IQ/OQ documentation separate from OEM equipment sales creating recurring revenue. |
| CE Marking Convergence Investment | Alignment between FDA draft guidance and EU cleanroom standards reduces certification costs for multinational suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that this study combined with primary interviews across plant engineers at meat and dairy processing facilities, procurement leads at beverage bottling cooperatives, HVAC integration contractors, and regulatory affairs specialists at filtration OEMs. FDA FSMA inspection protocols, ECHA substance evaluation timelines, EPA air quality enforcement records, and ISO 14698 cleanroom certification databases provided secondary validation. Bottom-up demand modeling across facility retrofit cycles and greenfield construction pipelines triangulated against top-down filtration media production estimates.
Reconciliation of equipment shipment data, media consumption surveys, and facility environmental monitoring compliance records informed the analytical framework across the projection horizon. Segmentation dimensions modeled include filtration efficiency tier, application risk zone classification, installation integration depth, and facility vintage category. CAGRs derived from fitted growth curves applied to validated HEPA terminal filtration demand in dairy cleanrooms and activated carbon adsorption specifications in urban-adjacent snack manufacturing. Industry-specific forecast inputs incorporated FSMA enforcement intensity scoring and REACH fluorinated compound substitution timelines.
Inputs from FDA inspection databases and ECHA substance evaluation registers were available through the study window; gaps in real-time craft brewery capital expenditure tracking introduce uncertainty bands around modular fan filter unit adoption trajectories. Forecasts reflect assumptions regarding regulatory alignment between FDA environmental monitoring guidance and ISO 14698 benchmarks, with potential divergence redirecting R&D spending toward region-specific certification stacks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Pathogen Reduction Systems Market