
 Food Authenticity Market | 2026-2036
Food Authenticity Market Size, Share, and Industry Trends Forecast 2026-2036
Food Authenticity Market Intelligence
The capital-intensity divergence between full-service laboratories and boutique specialists is rotating competitive advantage toward scale operators. SGS leverages its global network of ISO-accredited facilities to anchor multi-jurisdictional testing contracts for meat and dairy authenticity. Eurofins Scientific differentiates through proprietary DNA barcoding platforms that compete directly with conventional spectroscopy methods. Mérieux NutriSciences sustains long-term retailer relationships by controlling cold-chain sampling logistics across fragmented European supplier bases.
Food authenticity encompasses the scientific verification of product origin, composition, and processing history through analytical techniques such as polymerase chain reaction (PCR) amplification, isotope ratio mass spectrometry, and distributed ledger traceability systems. Its primary commercial purpose is to prevent economically motivated adulteration, mislabeling, and substitution fraud that erodes consumer trust and exposes brands to liability. The technology dimension shows DNA analysis occupying the highest-margin verification tier for meat and spices, while blockchain-enabled traceability grows fastest among beverage applications seeking real-time supply chain transparency. Product-type demand fragments across dairy authenticity testing in Europe and spice fraud detection in Asian sourcing corridors, with compliance verification representing the most mature application segment.
The FDA enforces food fraud prevention requirements through its Food Safety Modernization Act framework, while the EU Green Deal and EFSA origin-labeling protocols tighten documentary evidence standards for cross-border food shipments. REACH-compliant reference materials and ISO 17025 accreditation now function as baseline market-access credentials rather than competitive differentiators. Stakeholders must decide whether to build captive analytical capabilities or outsource to consolidated laboratory networks as regulatory granularity intensifies across multiple jurisdictions.
Market Dynamics
Blockchain-enabled traceability is decomposing the traditional paper-based verification infrastructure that has governed food supply chains for decades, forcing laboratories and manufacturers to rebuild authentication workflows around distributed ledger architectures.
Growth Catalysts
- EU Green Deal origin-labeling mandates:Cross-border food shipments now require documentary evidence standards that compel investment in third-party verification systems across European supplier networks.
- DNA barcoding adoption:Meat and spice processors deploy polymerase chain reaction amplification to detect substitution fraud at points of import consolidation.
- Germany's enforcement intensity:The national food regulator applies strict origin-labeling protocols that drive concentrated demand for ISO 17025-accredited testing facilities.
Market Restraints
- Reference material cost volatility:REACH-compliant certified standards for isotope ratio mass spectrometry command premium pricing that compresses margins for boutique laboratories.
- Cold-chain sampling infrastructure:Perishable dairy and meat categories require temperature-controlled logistics networks that concentrate operational capability among scale operators.
- Spectroscopy displacement friction:Conventional optical methods retain installed-base advantages in beverage applications where real-time blockchain integration remains technically immature.
Strategic Opportunities
- Asian spice corridor penetration:Sourcing hubs in India and Vietnam lack accredited testing density, creating white space for mobile PCR laboratory deployment.
- Real-time beverage traceability:Blockchain-IoT convergence enables continuous provenance monitoring that premium bottled water and wine producers now specify in procurement contracts.
- CSRD-aligned verification services:Corporate sustainability reporting mandates create new revenue streams for laboratories offering carbon-footprint authentication alongside composition testing.
Industry Challenges
- ISO 17025 accreditation timelines:Multi-jurisdictional facility certification requires eighteen-to-twenty-four-month approval cycles that delay market entry for new laboratory networks.
- DNA analysis talent scarcity:Shortages of trained molecular biologists constrain expansion of high-margin PCR testing capacity at regional laboratory facilities.
- Legacy ERP integration complexity:Blockchain traceability platforms require substantial middleware development to interface with incumbent supply chain management systems at processed food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Authenticity Market |
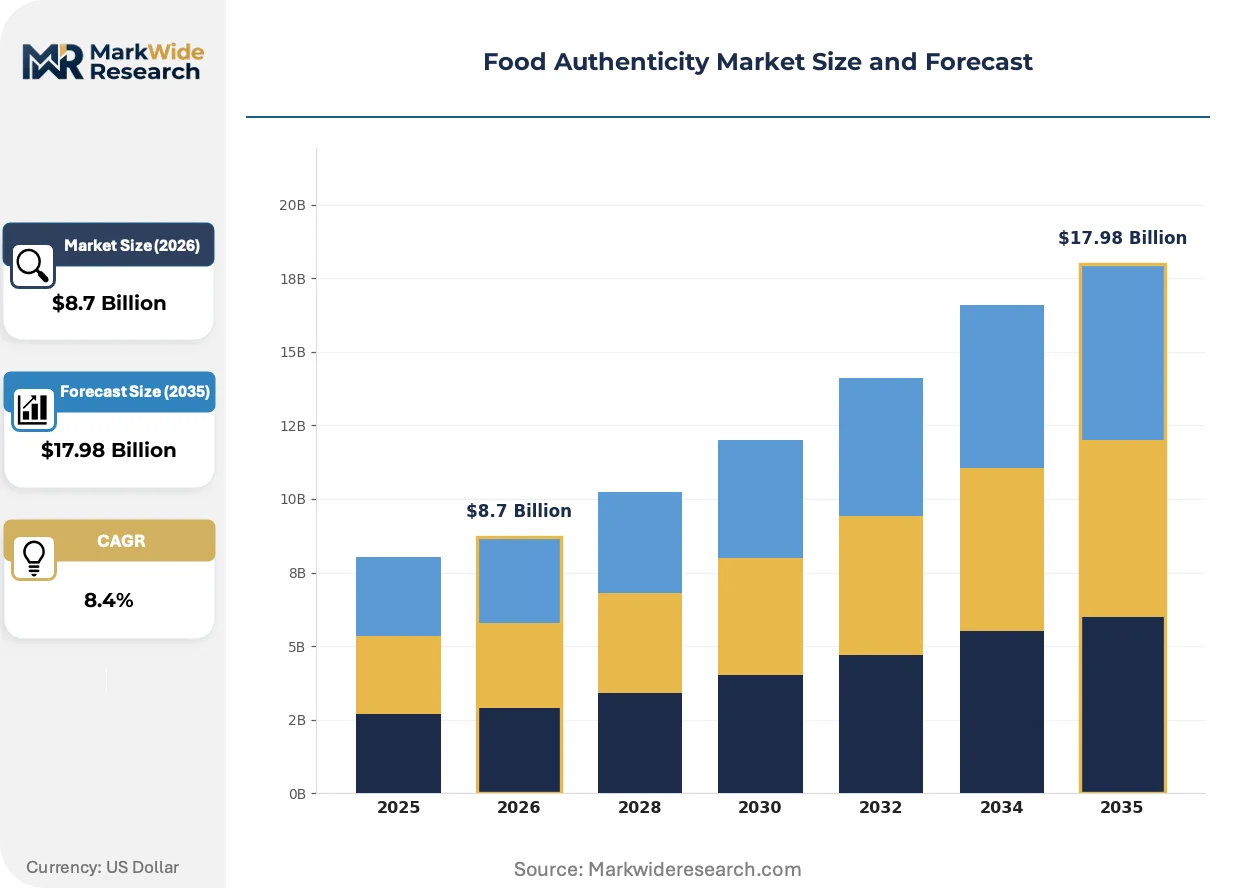
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Spices, Beverages Technology: DNA Analysis, Spectroscopy, Blockchain, QR Codes End User: Food Manufacturers, Retailers, Wholesalers, Consumers Application: Quality Control, Compliance Verification, Traceability, Supply Chain Management |
| Companies Covered | ALS, Mérieux NutriSciences, SGS, EMSL Analytical, Microbac Laboratories, Intertek, LGC Science Group, Romer Labs, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Authenticity Market Strategic Shifts & Innovations
Verification technology is bifurcating between rapid on-site screening tools and centralized high-precision analysis, with the boundary between them shifting as portable equipment capabilities advance.
Next-generation sequencing platforms are decomposing the market structure that separated rapid immunoassay screening from laboratory-based DNA barcoding. Spice importers and meat processors now deploy portable PCR units at receiving docks, compressing the time between shipment arrival and authenticity confirmation from days to hours. This capability migration is collapsing the traditional tiering between field and laboratory testing services.
The FDA's Food Safety Modernization Act framework now mandates preventive controls that include economically motivated adulteration vulnerability assessments. Processed food manufacturers must document supply chain verification procedures or face enforcement action, which has triggered wholesale replacement of paper-based traceability with digital audit trails. Dairy and infant formula categories exhibit the most intensive compliance response due to historical contamination liability exposure.
Retailer consolidation is compressing supplier qualification cycles and unbundling testing services from long-term analytical contracts. Large grocery chains now mandate direct data feeds from third-party laboratories rather than accepting manufacturer-provided certificates of analysis. Germany and France demonstrate the most advanced procurement models, with centralized buying offices specifying blockchain-verified provenance as a condition of shelf access.
Food Authenticity Market Segmentation
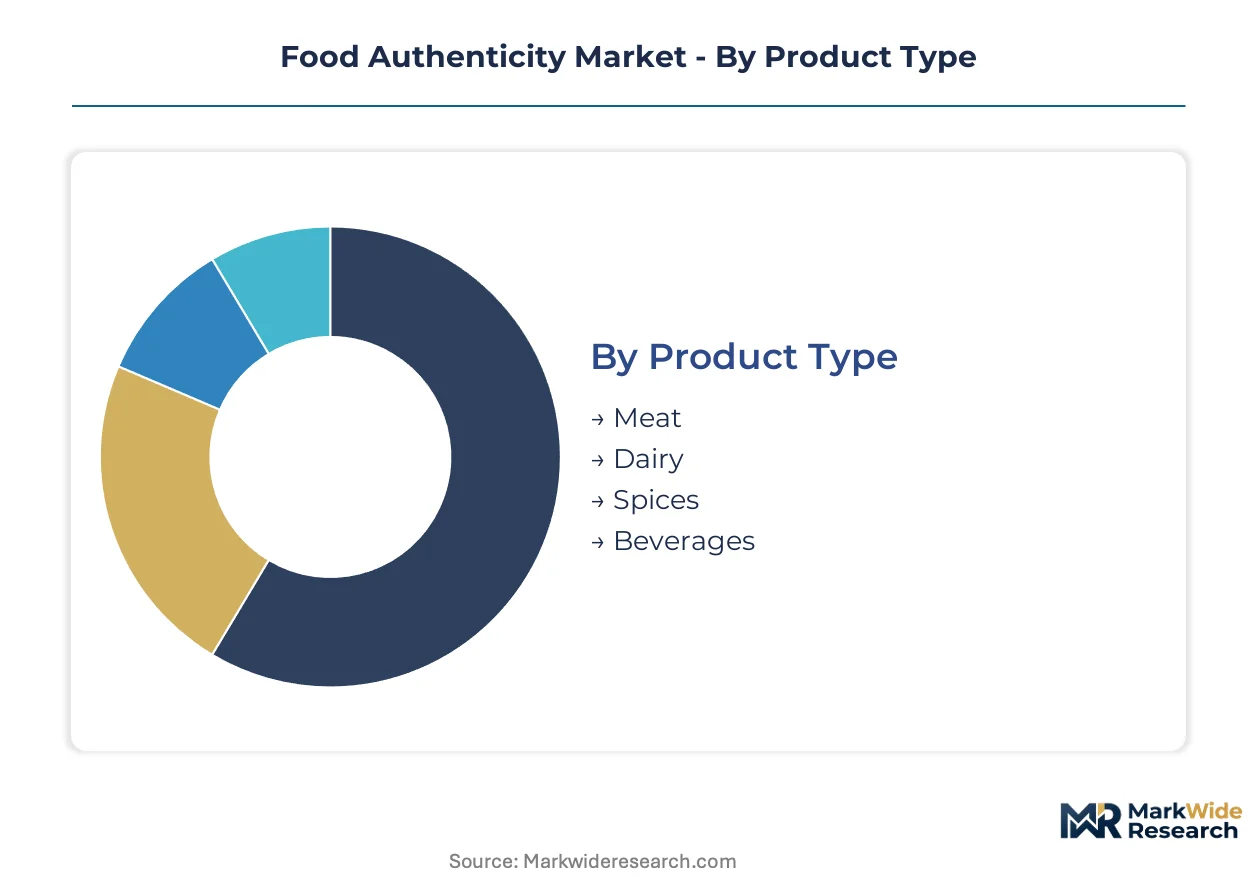
Food authenticity verification fragments across four analytical dimensions that shape procurement patterns and technology deployment. Product type determines testing methodology intensity. Technology selection drives margin structure and capital requirements. End-user concentration dictates contract duration and service bundling. Application purpose governs regulatory exposure and audit frequency.
Product Type:
Substitution pressure concentrates in protein categories where fraud economics reward adulteration most heavily, forcing differential investment in detection infrastructure.
- Meat:Species substitution and undeclared offal inclusion demand polymerase chain reaction protocols at slaughterhouse and import consolidation points. German retail chains now mandate ISO 17025-accredited verification for all fresh and processed meat suppliers, compressing laboratory turnaround requirements to under 48 hours.
- Dairy:Melamine adulteration history and infant formula liability exposure sustain the highest testing frequency per ton across any food category. European cold-chain logistics networks concentrate sampling capability in the Netherlands and Denmark, where dairy cooperative vertical integration enables captive laboratory deployment.
- Spices:Saffron, turmeric, and paprika face routine botanical substitution and synthetic dye contamination. Indian and Vietnamese sourcing corridors lack accredited testing density, creating white space for mobile PCR laboratory deployment at port consolidation points.
- Beverages:Wine, bottled water, and premium spirits deploy blockchain-IoT provenance tracking that bypasses conventional laboratory verification for origin claims.
Meat retains volume leadership; spices hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive laboratory platforms from deployable field tools, with middleware integration costs determining total cost of ownership.
- DNA Analysis:Barcoding and next-generation sequencing occupy the highest-margin verification tier for species identification and botanical authentication. Eurofins Scientific and SGS anchor multi-jurisdictional contracts through proprietary PCR platform standardization.
- Spectroscopy:Near-infrared and Raman methods retain installed-base advantages in beverage applications where real-time blockchain integration remains technically immature. Reference material cost volatility for isotope ratio mass spectrometry compresses margins for boutique operators.
- Blockchain:Distributed ledger traceability grows fastest among beverage applications seeking real-time supply chain transparency. The EU Green Deal origin-labeling mandates compel documentary evidence standards that accelerate procurement specification.
- QR Codes:Static labeling technology faces displacement pressure from dynamic blockchain verification, limiting expansion to cost-sensitive commodity categories.
Blockchain is climbing the fastest; DNA analysis commands the premium pricing tier.
End User:
Customer type determines contract structure, with retailer consolidation unbundling long-term analytical relationships into transactional data-feed arrangements.
- Food Manufacturers:Processed food manufacturers now represent the fastest-expanding end-user segment as FDA Food Safety Modernization Act preventive controls mandate economically motivated adulteration vulnerability assessments. Cold-chain sampling infrastructure requirements concentrate operational capability among scale operators.
- Retailers:Large grocery chains mandate direct laboratory data feeds rather than accepting manufacturer-provided certificates of analysis. France and Germany demonstrate the most advanced procurement models, with centralized buying offices specifying blockchain-verified provenance as a condition of shelf access.
- Wholesalers:Import consolidation points in Rotterdam and Hamburg deploy rapid screening tools to clear customs holds and avoid demurrage penalties.
- Consumers:Premium segment buyers access verification through branded mobile applications, though mass-market penetration remains limited by price sensitivity.
Food manufacturers drive absolute volume; retailers are gaining share fastest.
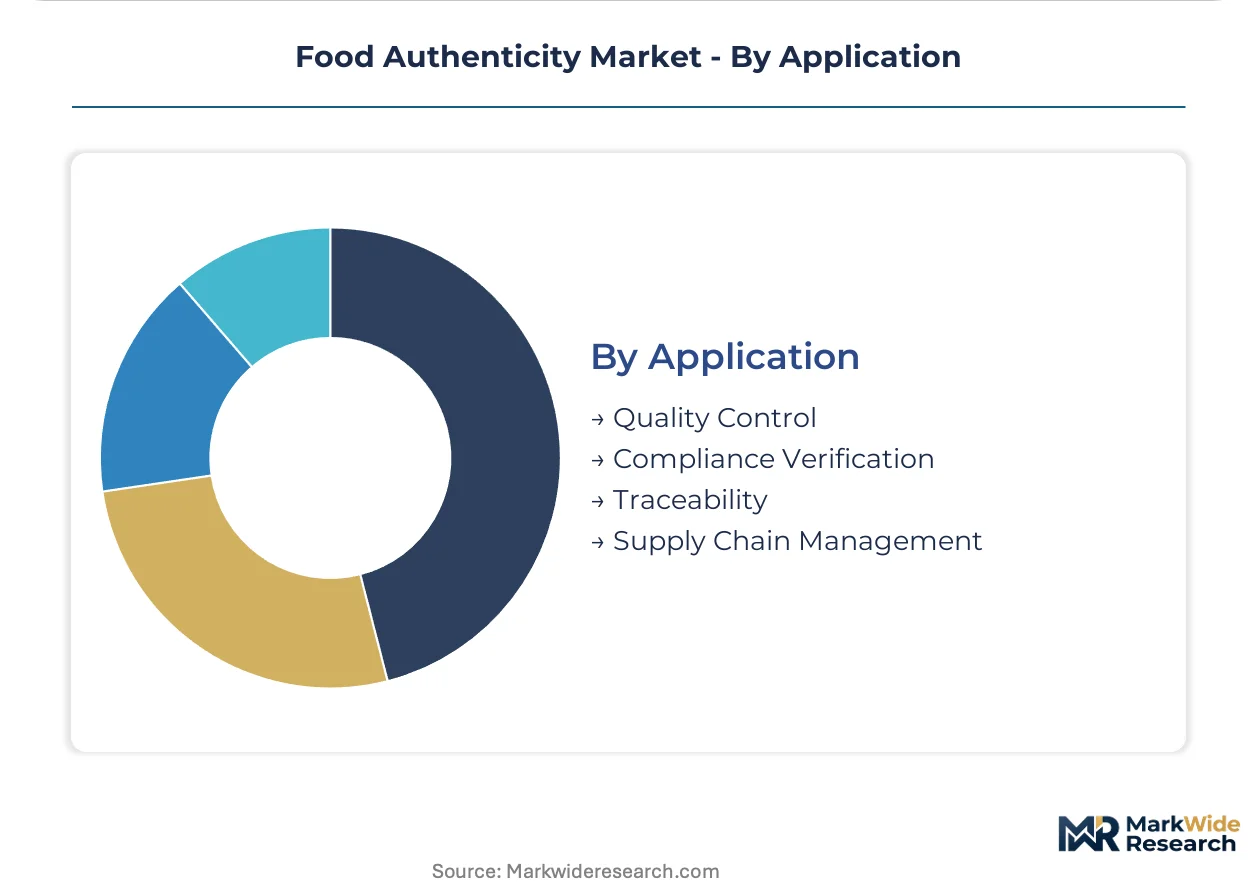
Application:
Maturity gradients separate established compliance verification from emerging traceability services that bundle carbon-footprint authentication.
- Quality Control:Routine composition testing at production facilities represents the most mature application segment, with pricing compressed by standardized methodology.
- Compliance Verification:Regulatory documentation for cross-border shipment clearance sustains stable demand through EFSA origin-labeling protocols and FDA enforcement frameworks. REACH-compliant reference materials and ISO 17025 accreditation function as baseline market-access credentials.
- Traceability:Real-time provenance monitoring expands fastest in premium beverage and organic produce categories where procurement contracts now specify continuous ledger verification.
- Supply Chain Management:ERP integration complexity constrains blockchain deployment, with middleware development costs delaying adoption at mid-scale processed food manufacturers.
Compliance verification retains revenue concentration; traceability shows the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German buyers absorb premium verification costs without volume elasticity, while Indian spice processors treat third-party testing as discretionary spend. French and US markets occupy intermediate positions where regulatory pressure overrides pure cost optimization.
Germany
The national food regulator enforces strict origin-labeling protocols that compel investment in ISO 17025-accredited testing facilities. EU Green Deal cross-border documentation requirements sustain demand for documentary evidence systems at import consolidation points. Hamburg and Frankfurt host dense laboratory networks serving meat and dairy verification contracts.
United States
FDA Food Safety Modernization Act preventive controls mandate economically motivated adulteration vulnerability assessments across processed food supply chains. FSMA documentation requirements triggered wholesale replacement of paper-based traceability with digital audit trails. Chicago and Minneapolis-St. Paul anchor cold-chain sampling infrastructure for dairy cooperative networks.
France
Centralized retail buying offices specify blockchain-verified provenance as a condition of shelf access for premium meat and wine suppliers. EFSA origin-labeling protocols tighten documentary evidence standards for cross-border shipment clearance. Paris and Lyon concentrate laboratory capacity serving retailer direct data-feed contracts.
India
Spice sourcing corridors in turmeric and saffron face routine botanical substitution fraud without sufficient accredited testing density. FSSAI enforcement capacity lags behind EU and US regulatory intensity, creating white space for mobile PCR laboratory deployment. Mumbai and Kochi port facilities represent critical intervention points for import verification.
United Kingdom
Post-EU regulatory divergence creates dual compliance burden for exporters serving both continental and domestic markets. UK Food Standards Agency maintains parallel authenticity verification requirements with distinct accreditation pathways. London and Birmingham laboratory clusters specialize in dual-jurisdiction certification for processed food manufacturers.
Food Authenticity Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in food authenticity verification. SGS, Eurofins Scientific, and Intertek anchor multi-jurisdictional testing contracts through global ISO-accredited facility networks. Boutique molecular biology laboratories compete on DNA barcoding specialization but face margin compression from reference material cost volatility. Scale operators defend position through cold-chain logistics control and ERP integration capabilities. Strategic moves concentrate on M&A-driven geographic densification and proprietary platform licensing.
Within the integrated testing tier, SGS and Eurofins Scientific exemplify scale-driven competitive positioning. SGS leverages its Swiss-headquartered network for multi-jurisdictional meat and dairy contracts. Eurofins Scientific occupies a position defined by proprietary DNA barcoding platform deployment. Mérieux NutriSciences represents the long-term relationship archetype, sustaining retailer contracts through cold-chain sampling logistics specialization.
| Leading Market Players |
|---|
| ALS |
| Mérieux NutriSciences |
| SGS |
| EMSL Analytical |
| Microbac Laboratories |
| Intertek |
| LGC Science Group |
| Romer Labs |
| Eurofins Scientific |
| Others |
Cost & Logistics Intelligence
ISO 17025 accreditation gates both laboratory market access and price tier positioning, forcing boutique operators into cost compression while scale players capture premium multi-jurisdictional contracts. Certification density in Germany and the United States creates geographic price stratification that rewards cold-chain logistics control with margin protection.
Pricing Analysis
After-sales service revenue from multi-year testing contracts and ERP integration support drives lifetime value for scale laboratory networks. Three-tier pricing structure across premium ISO-accredited verification, standard compliance documentation, and economy rapid-screening tiers separates SGS and Eurofins from regional competitors. Pricing pressure stems from REACH-compliant reference material cost volatility that squeezes boutique molecular biology laboratories. Processed food manufacturers exhibit highest price sensitivity due to FSMA-mandated volume testing, while German retailers absorb premiums without elasticity.
Supply Chain Analysis
Cold-chain sampling infrastructure chokepoints in the Netherlands and Denmark concentrate perishable dairy and meat verification capacity among integrated operators. Reference materials for isotope ratio mass spectrometry draw from specialized chemical suppliers in Switzerland and Germany, while PCR reagents hinge on biotech manufacturing clusters in the United States and Singapore. Single-source vulnerability runs through certified reference material producers facing regulatory restriction under REACH amendments. Distribution runs through Rotterdam and Hamburg port consolidation points serving European import corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-IoT platform interoperability is collapsing the traditional separation between field screening and laboratory analysis, creating winner-take-most dynamics for laboratories that control both data layers.
For Market Incumbents: Compound ISO-accredited facility density through targeted acquisition of regional cold-chain specialists in India and Vietnam spice corridors. Defend against portable PCR unit displacement by embedding proprietary barcoding platforms into retailer direct data-feed contracts. Prioritize ERP middleware development to capture blockchain traceability integration revenue at processed food manufacturers facing FSMA documentation mandates. For New Entrants and Emerging Players: Differentiate on mobile PCR laboratory deployment at Asian spice port consolidation points where accredited testing density remains lowest. Target Indian turmeric and saffron sourcing hubs as the most penetrable geography, with FSSAI enforcement lag creating temporary white space. Pursue pay-per-test revenue models against long-term analytical contracts to bypass incumbent relationship lock-in. For Investors and Strategic Acquirers: EU Green Deal origin-labeling mandates reshape the acquisition landscape toward laboratories with multi-jurisdictional certification coverage. Long-term viability over the next decade rests on controlling both DNA analysis capability and blockchain platform integration. Target acquisition archetypes combine cold-chain logistics specialization with proprietary PCR barcoding IP. Watch for FDA enforcement intensity on economically motivated adulteration assessments as the signal for laboratory consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile PCR Laboratory Deployment | Captures spice corridor testing demand in India and Vietnam where accredited density lags. |
| Blockchain Platform Integration | Locks in processed food manufacturer contracts through FSMA-mandated digital audit trail compliance. |
| Cold-Chain Logistics Expansion | Secures perishable dairy and meat verification margins in Netherlands and Denmark clusters. |
| ISO 17025 Accreditation Densification | Creates regulatory barrier against boutique competitors in Germany's enforcement-intensive market. |
| Reference Material Backward Integration | Insulates margins from REACH-compliant certified standard cost volatility squeezing regional players. |
Research Approach
Operator-level perspectives from laboratory technical directors, food manufacturer quality assurance leads, retailer procurement officers, and regulatory compliance managers anchored the qualitative base. Primary interview data combined with secondary validation from FDA FSMA guidance documents, EFSA origin-labeling protocols, ISO 17025 accreditation registries, and EU Green Deal implementation frameworks. Bottom-up testing volume estimates triangulated against top-down market sizing from customs trade flows and laboratory capacity disclosures.
Sensitivity analysis across technology adoption curves, regulatory enforcement intensity scenarios, and reference material cost trajectories shaped the analytical framework. Segmentation dimensions modeled include product type, verification technology, end-user concentration, and application purpose across the projection horizon. CAGRs derived from fitted growth curves against documented laboratory expansion announcements and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated blockchain-IoT convergence rates and PCR platform standardization adoption.
Material uncertainties — regulatory enforcement delays, reference material supply disruptions, and blockchain protocol fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions on ISO accreditation timeline stability and cold-chain infrastructure investment continuity. Practitioners should keep alternative scenarios live as EU Green Deal implementation pacing and FDA FSMA audit intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Food and Beverage Air Filtration Market