
 Natural Antimicrobials Market | 2026-2036
Natural Antimicrobials Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Antimicrobials Market Outlook
Subscription-based technical support for formulation optimization is realigning how antimicrobial suppliers monetize expertise beyond ingredient sales. Cargill leverages its integrated supply chain from botanical sourcing to finished food applications. BASF SE anchors its position through fermentation-derived natural preservatives with pharmaceutical-grade purity specifications. Kemin Industries specializes in shelf-life extension solutions tailored to clean-label meat and dairy processors.
Natural antimicrobials comprise bioactive compounds extracted from plants, fungi, and microbial fermentation that inhibit bacterial, fungal, or viral proliferation through membrane disruption, enzyme inhibition, or competitive metabolic interference, typically characterized by minimum inhibitory concentrations ranging from 0.1 to 10 percent depending on target organism and food matrix. These substances serve primarily to replace synthetic preservatives in perishable goods while meeting consumer demands for recognizable ingredient declarations. Essential oils and plant-based compounds command the deepest margin pools due to extraction complexity and organic certification premiums, while natural preservatives lead volume growth as food manufacturers retrofit existing production lines with drop-in alternatives. Herbal extracts occupy a mature niche in personal care applications where long-standing regulatory familiarity supports stable procurement patterns.
The FDA governs natural antimicrobial safety through food additive and GRAS notification pathways, while the EPA regulates pesticidal claims for botanical antimicrobial products, and the EU Green Deal accelerates substitution mandates for synthetic biocides across member states. Compliance with REACH substance registration and F-Gas Regulation phase-out timelines shapes supplier R&D allocation and market access eligibility. Stakeholders must monitor evolving GRAS self-determination enforcement patterns and EU taxonomy alignment requirements to anticipate which natural antimicrobial platforms will secure preferential procurement status from multinational food and pharmaceutical buyers.
Market Dynamics
Formulation budgets are redirecting toward botanical alternatives as REACH substance restrictions and EU Green Deal substitution mandates tighten chemical preservative pathways, compressing synthetic incumbent margins while fermentation-derived natural platforms capture displaced volume.
Growth Catalysts
- REACH phase-out timelines:ECHA substance evaluation schedules are forcing food manufacturers to accelerate clean-label reformulation programs ahead of 2027 restriction deadlines.
- German biotech corridor concentration:Fermentation-based antimicrobial production clusters in Baden-Württemberg and Bavaria are scaling pharmaceutical-grade output capacity for cross-border supply into France and the Netherlands.
- Essential oil extraction advances:Supercritical CO2 processing technology is reducing organic-certified botanical input waste rates below 15 percent, improving unit economics for rosemary and oregano-derived actives.
Market Restraints
- Organic botanical input cost volatility:Weather-driven supply fluctuations in Mediterranean thyme and clove growing regions are compressing gross margins for extraction-dependent suppliers.
- GRAS self-determination enforcement uncertainty:FDA notification pathway scrutiny is extending time-to-market for novel microbial fermentation products by 8-14 months.
- Performance variability in high-moisture matrices:Plant-derived antimicrobials exhibit inconsistent minimum inhibitory concentrations above 60 percent water activity, limiting adoption in ready-to-eat fresh produce applications.
Strategic Opportunities
- Indian pharmaceutical outsourcing:CDMOs in Hyderabad and Bangalore are building fermentation capacity for natural preservative APIs targeting EU and US export markets under bilateral equivalence agreements.
- Personal care microbiome positioning:Skincare brands are reformulating with selective antimicrobial botanicals that preserve beneficial skin flora while suppressing pathogenic bacteria.
- Japan METI biomanufacturing incentives:Subsidies for precision fermentation infrastructure are attracting joint ventures between domestic food conglomerates and European technology licensors.
Industry Challenges
- Cross-functional formulation expertise scarcity:Food science professionals with combined microbiology, regulatory affairs, and sensory evaluation capabilities command 40-60 percent compensation premiums.
- Legacy synthetic preservative line retrofit costs:Dairy and meat processors face capital expenditure requirements for pH adjustment and aseptic handling systems incompatible with plant-derived active stability windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Antimicrobials Market |
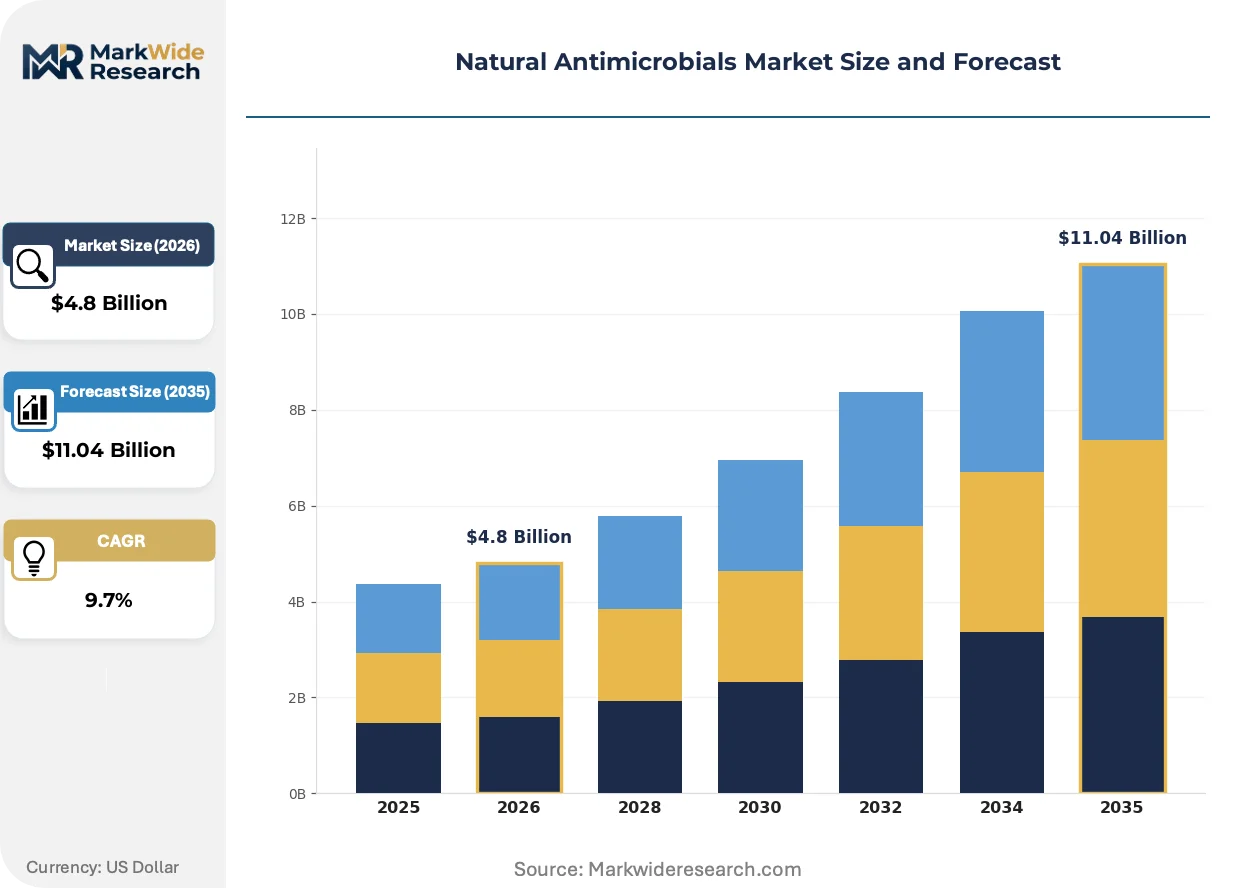
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbal Extracts, Natural Preservatives, Plant-Based Compounds Application: Food Preservation, Pharmaceuticals, Personal Care, Veterinary Products End User: Food Manufacturers, Healthcare Providers, Cosmetic Companies, Animal Health Sector Form: Liquid, Powder, Spray, Emulsion |
| Companies Covered | Cargill, BASF SE, Ashland, Active Micro Technologies, SEPPIC, DuPont Nutrition & Biosciences, Kemin Industries, Chr. Hansen, Evonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Antimicrobials Market Strategic Shifts
Bioprocessing platforms are displacing solvent extraction as the dominant production paradigm, while regulatory alignment across FDA GRAS and EFSA safety assessments is compressing multi-jurisdiction approval timelines.
Precision fermentation of antimicrobial peptides is expanding into industrial-scale production, with yeast and fungal expression systems now achieving gram-per-liter yields previously restricted to laboratory conditions. Contract manufacturers in Denmark and the Netherlands are commissioning 10,000-liter bioreactor trains for nisin and pediocin analogs. This platform is expanding into cost parity with plant extraction for high-purity applications.
EU F-Gas Regulation phase-down schedules are accelerating substitution investment for synthetic biocides in food processing equipment sanitation, with ECHA guidance documents clarifying natural-derived surface treatment authorization pathways. Cold-chain logistics operators in Germany and France are piloting botanical-based fogging protocols for transport container decontamination. The regulation is compressing incumbent chemical supplier contract renewal rates.
Clean-label certification is becoming a gatekeeping criterion in retail buyer specifications, with IFS and BRC audit schemes incorporating antimicrobial declaration transparency scoring. French and UK supermarket chains are delisting suppliers unable to document botanical preservative provenance through blockchain-tracked supply chains. This specification tightening is most visible in private-label chilled ready-meal procurement.
Natural Antimicrobials Market Segmentation
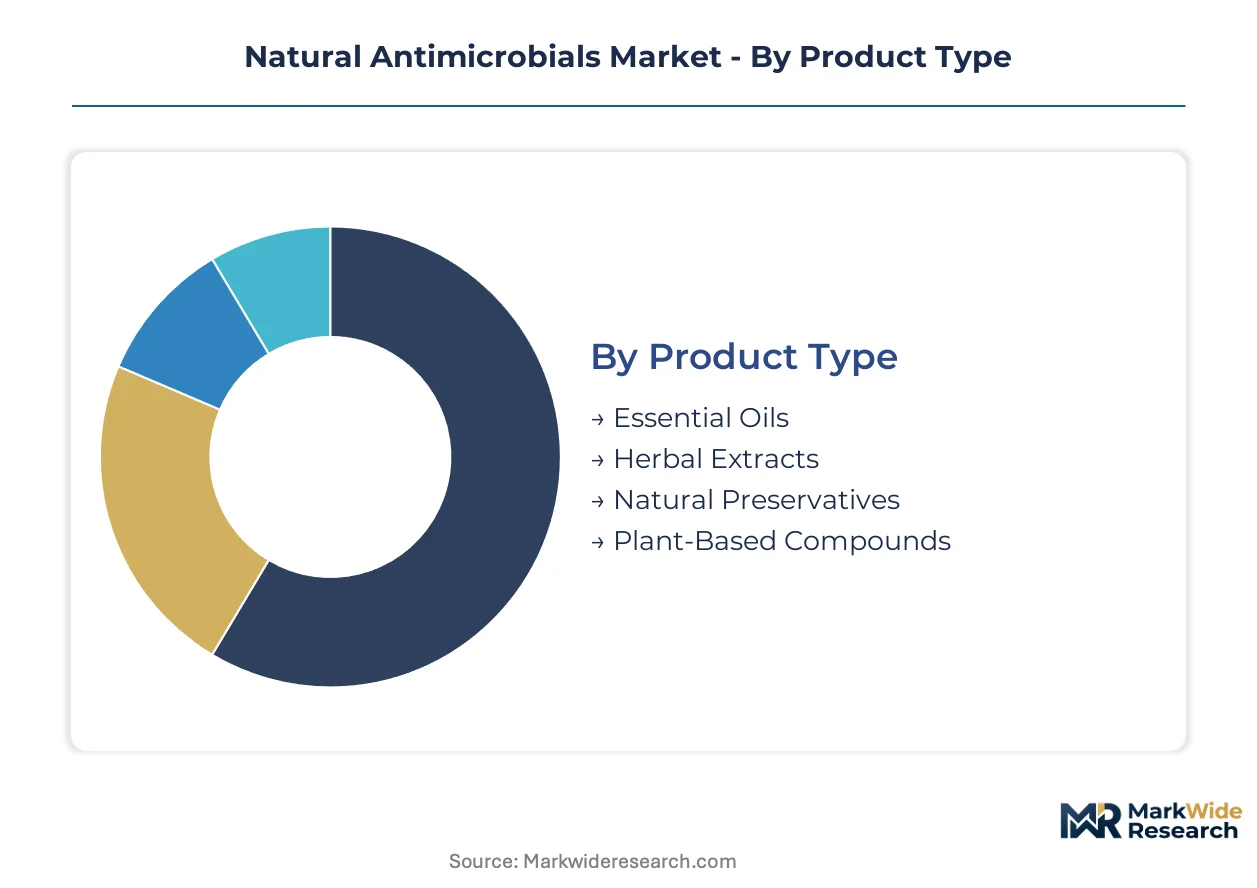
Segmentation in natural antimicrobials reveals how extraction complexity and regulatory pathways fragment procurement strategies across end-use industries. Product form and application matrix determine whether suppliers compete on pharmaceutical-grade purity or cost-per-dose efficiency in food matrices.
Product Type:
Standalone extraction-based products command premium positioning in certified organic channels, while fermentation-derived platforms embed more deeply into integrated preservation systems requiring drop-in compatibility.
- Essential Oils:Concentrated volatile compounds from rosemary, oregano, and thyme deliver membrane-disruption antimicrobial activity. German clean-label meat processors in Bavaria specify organic-certified essential oil blends for shelf-life extension in chilled sausages. REACH substance restrictions on synthetic biocides are accelerating substitution contracts for transport container fogging applications.
- Natural Preservatives:Fermentation-derived peptides including nisin and pediocin analogs achieve pharmaceutical-grade purity through precision bioprocessing. Danish and Dutch contract manufacturers are scaling 10,000-liter bioreactor capacity for cross-border supply into French dairy retrofit programs. EU F-Gas Regulation phase-down timelines are compressing synthetic incumbent contract renewal rates in food processing sanitation.
- Herbal Extracts:Standardized polyphenol fractions from green tea and grape seed occupy mature personal care applications with established regulatory familiarity.
- Plant-Based Compounds:Isolated bioactives including carvacrol and thymol provide consistent minimum inhibitory concentrations for high-throughput food manufacturing.
Volume placements concentrate in natural preservatives; the faster expansion belongs to essential oils.
Application:
Cost-tier stratification separates pharmaceutical-grade specifications from food-grade volume plays, with personal care occupying a mid-tier position defined by microbiome-selective positioning.
- Food Preservation:Clean-label reformulation in perishable goods drives demand for botanical alternatives with documented provenance through blockchain-tracked supply chains. French and UK supermarket chains now mandate antimicrobial declaration transparency scoring in IFS and BRC audit schemes for private-label chilled ready-meal procurement.
- Personal Care:Skincare brands reformulate with selective antimicrobial botanicals that suppress pathogenic bacteria while preserving beneficial skin flora, commanding formulation premiums in premium channel positioning.
- Pharmaceuticals:Fermentation-based antimicrobial APIs from Indian CDMOs in Hyderabad and Bangalore target EU and US export markets under bilateral equivalence agreements.
- Veterinary Products:Natural alternatives to antibiotic growth promoters face regulatory pathway complexity across jurisdictions with divergent animal health frameworks.
Revenue concentration sits with food preservation; steepest expansion trajectory appears in personal care microbiome positioning.
End User:
Customer-type fragmentation separates multinational formulators with integrated R&D capabilities from mid-tier processors dependent on external technical support subscriptions.
- Food Manufacturers:Dairy and meat processors face capital expenditure requirements for pH adjustment and aseptic handling systems incompatible with plant-derived active stability windows. German clean-label processing clusters in Baden-Württemberg scale fermentation-based antimicrobial production for cross-border supply.
- Cosmetic Companies:Premium skincare brands drive selective antimicrobial botanical demand with microbiome-preservation specifications.
- Healthcare Providers:Hospital formulary procurement emphasizes pharmaceutical-grade purity specifications with documented EFSA safety assessments.
- Animal Health Sector:Feed additive regulations vary across export destination markets, complicating procurement standardization.
Procurement scale concentrates in food manufacturers; the most rapid share gains belong to cosmetic companies.
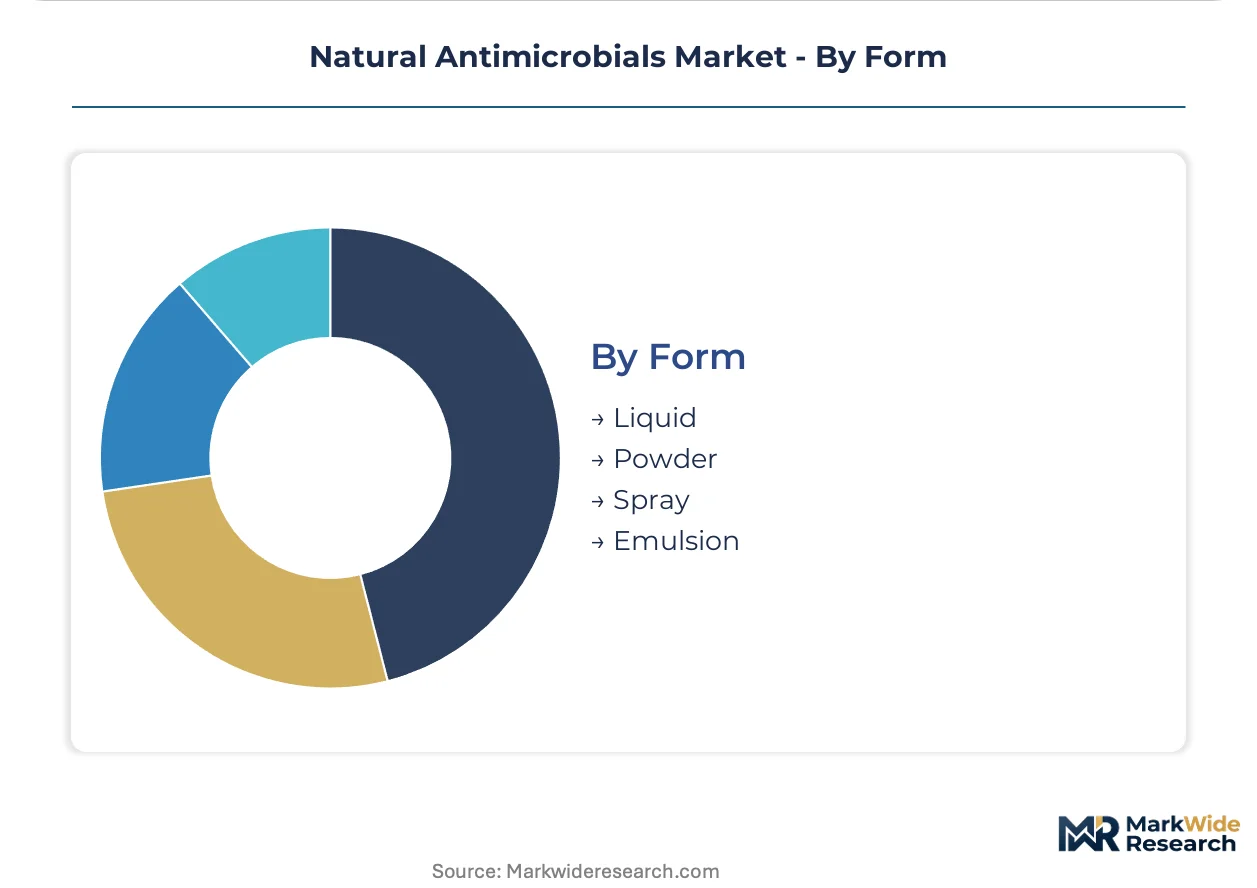
Form:
Supply concentration in liquid extraction infrastructure shapes regional availability, while powder and emulsion forms require downstream processing investment that fragments the supplier base.
- Liquid:Supercritical CO2 extraction output dominates organic-certified botanical supply chains with waste rates below 15 percent for rosemary and oregano-derived actives.
- Powder:Spray-dried formulations enable shelf-stable distribution to processors lacking liquid handling infrastructure.
- Emulsion:Oil-in-water systems address high-moisture matrix compatibility challenges above 60 percent water activity in ready-to-eat fresh produce.
- Spray:Aerosolized delivery formats serve surface sanitation applications in cold-chain logistics pilot programs across Germany and France.
Production gravity centers on liquid formats; emulsion development is climbing the fastest for matrix compatibility solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based production clusters concentrate in Germany, while extraction-dependent supply chains anchor in Mediterranean growing regions. Consumption gravity shifts toward clean-label reformulation hubs in France and the United Kingdom.
United States
GRAS notification pathways govern novel microbial fermentation products entering food applications. FDA enforcement scrutiny extends time-to-market timelines, compressing margins for suppliers dependent on rapid commercialization. Greater Boston and Research Triangle Park host precision fermentation startups scaling peptide analog production for meat and dairy processors.
Germany
Baden-Württemberg and Bavaria biotech corridors scale pharmaceutical-grade antimicrobial output for cross-border supply into French and Dutch markets. EU F-Gas Regulation phase-down schedules accelerate substitution investment for synthetic biocides in food processing equipment sanitation. REACH substance evaluation deadlines force manufacturers to accelerate clean-label reformulation programs ahead of 2027 restrictions.
France
Supermarket chains mandate antimicrobial declaration transparency scoring through blockchain-tracked supply chains for private-label chilled ready-meal procurement. ECHA guidance documents clarify natural-derived surface treatment authorization pathways for cold-chain logistics operators. Île-de-France food processing clusters pilot botanical-based fogging protocols for transport container decontamination.
India
CDMOs in Hyderabad and Bangalore build fermentation capacity for natural preservative APIs targeting EU and US export markets under bilateral equivalence agreements. FSSAI regulatory alignment with Codex standards shapes formulation export eligibility for botanical extraction houses. Maharashtra and Gujarat host solvent extraction infrastructure serving personal care manufacturers with established regulatory familiarity.
Japan
METI biomanufacturing subsidies attract joint ventures between domestic food conglomerates and European technology licensors for precision fermentation infrastructure. PMDA pharmaceutical-grade purity specifications govern antimicrobial peptide applications in medical device coatings. Kanto region food processors reformulate with selective antimicrobial botanicals preserving beneficial flora in fermented product categories.
Natural Antimicrobials Market Competitive Environment
Top-tier vendors anchor integrated supply chains from botanical sourcing to finished applications, while mid-tier specialists compete on formulation expertise subscriptions. The vendor base stratifies across fermentation-derived purity platforms, extraction-dependent organic certification premiums, and clean-label technical support services. Three archetypes dominate: integrated agribusiness conglomerates, fermentation-focused biotech suppliers, and botanical extraction houses with certified organic positioning. Competitive moves concentrate on backward integration into captive raw material supply and geographic expansion through CDMO partnerships in Asian manufacturing hubs.
Among integrated agribusiness conglomerates, Cargill represents supply chain control from field to formulation. BASF SE and Kemin Industries exemplify divergent specialization vectors within the premium tier—BASF SE anchors fermentation-derived pharmaceutical-grade positioning, while Kemin Industries occupies clean-label meat and dairy shelf-life extension. These three names illustrate how competitive positioning fragments across production technology rather than converging on uniform platform strategies.
| Leading Market Players |
|---|
| Cargill |
| BASF SE |
| Ashland |
| Active Micro Technologies |
| SEPPIC |
| DuPont Nutrition & Biosciences |
| Kemin Industries |
| Chr. Hansen |
| Evonik |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal substitution mandates gate qualified supply and premium-tier pricing access, restricting botanical sourcing to REACH-registered extraction houses and fermentation platforms with pharmaceutical-grade certification. Buyers face tiered procurement thresholds where clean-label provenance commands 40-60 percent compensation premiums for cross-functional formulation expertise.
Pricing Analysis
Margin tightening in essential oils reflects weather-driven supply fluctuations across Mediterranean thyme and clove growing regions. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates fermentation-derived peptides from solvent-extracted botanicals. Cost compression in organic-certified channels accelerates because supercritical CO2 processing technology has reduced waste rates below 15 percent. Food manufacturers exhibit highest price sensitivity due to capital expenditure requirements for pH adjustment systems, while pharmaceutical buyers absorb premiums for documented EFSA safety assessments.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for rosemary and oregano-derived actives across German, Dutch, and Danish processing clusters. Raw material dependencies rest on Mediterranean botanical inputs, Indian fermentation capacity in Hyderabad and Bangalore, and supercritical CO2 extraction infrastructure in Germany and France. Single-source vulnerability concentrates in organic-certified growing regions exposed to climate volatility. Distribution runs through integrated agribusiness conglomerates with backward integration into captive raw material supply and contract manufacturing partnerships in Asian hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance evaluation schedules have transformed this market into a cost-of-compliance story, creating a barrier-to-entry moat for extraction houses and fermentation platforms with pre-registered dossiers ahead of 2027 restriction deadlines.
For Market Incumbents: Hedge against GRAS self-determination enforcement uncertainty by accelerating FDA notification submissions for novel microbial fermentation products. Prioritize backward integration into captive organic botanical supply in Baden-Württemberg and Bavaria to offset weather-driven input cost volatility. Lock in long-term offtake agreements with French and UK supermarket chains before IFS and BRC audit scheme transparency scoring hardens into mandatory procurement gates. For New Entrants and Emerging Players: Precision fermentation of antimicrobial peptides offers a technology-first wedge into cost parity with plant extraction for high-purity applications. Target emulsion development for high-moisture matrix compatibility above 60 percent water activity, the most penetrable white space where plant-derived antimicrobials currently exhibit inconsistent performance. Pursue joint venture structures with Japanese food conglomerates leveraging METI biomanufacturing subsidies to access precision fermentation infrastructure without capital-heavy greenfield investment. For Investors and Strategic Acquirers: ECHA guidance document releases clarifying natural-derived surface treatment authorization pathways are the leading indicator that cold-chain logistics fogging applications will scale beyond pilot programs. Five-to-ten year viability favors fermentation-focused biotech suppliers with pharmaceutical-grade purity specifications over extraction-dependent organic certification plays. Monitor CDMO capacity buildout in Hyderabad and Bangalore as the inflection signal for cross-border supply cost structures achieving sustainable export economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Botanical Supply | Baden-Württemberg extraction houses secure weather-hedged rosemary and oregano input streams. |
| Precision Fermentation Scale-Up | Danish and Dutch contract manufacturers commission 10,000-liter bioreactor trains for nisin analogs. |
| Regulatory Pre-Registration Investment | REACH dossier completion ahead of 2027 deadlines locks in qualified supplier status for EU procurement. |
| Blockchain-Tracked Supply Chain Certification | French supermarket chains mandate provenance documentation for private-label chilled ready-meal procurement. |
| Joint Venture with Asian CDMO Partners | Hyderabad and Bangalore fermentation capacity targets EU and US export markets under bilateral equivalence agreements. |
Study Parameters
Multi-period observation of formulation budget reallocation patterns, GRAS notification timelines, and REACH substance evaluation schedules anchored the trend analysis, supplemented by interviews with food science R&D directors, regulatory affairs leads at antimicrobial suppliers, clean-label procurement managers at French and UK supermarket chains, and precision fermentation platform engineers. Secondary validation drew from ECHA guidance documents, FDA GRAS notification databases, EU F-Gas Regulation phase-down schedules, and IFS and BRC audit scheme transparency scoring protocols. Bottom-up segment sizing triangulated against top-down macro constraint modeling.
Input-output matrices mapped extraction-based versus fermentation-derived production economics across essential oils, natural preservatives, herbal extracts, and plant-based compound categories, further segmented by food preservation, personal care, pharmaceutical, and veterinary end-use applications. CAGRs were derived from regression analysis of historical substitution rates for synthetic biocides correlated with regulatory deadline proximity. Industry-specific forecast inputs included supercritical CO2 processing yield improvements and METI biomanufacturing subsidy uptake rates.
Several conditions sit outside the modeled scope, including unilateral FDA enforcement shifts on GRAS self-determination, catastrophic climate events in Mediterranean growing regions, and geopolitical disruption to bilateral equivalence agreements governing Indian CDMO export eligibility. Forecasts assume sustained EU Green Deal implementation trajectory and stable Codex alignment for FSSAI regulatory convergence. Deviation in ECHA substance evaluation acceleration or delay would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Food and Beverage Air Filtration Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Precision Food Thermometers Market