
 Testing, Inspection, and Certification Market | 2026-2036
Testing, Inspection, and Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Testing, Inspection, and Certification Market Intelligence
Third-party laboratory networks is narrowing as consolidation pressures independent operators across Europe and North America. SGS leverages its geographic breadth to sustain multi-regional accreditation coverage for industrial clients. Bureau Veritas anchors its position through maritime and energy sector specialization, while Intertek Group competes aggressively in consumer product safety programs.
Testing, inspection, and certification encompasses the independent verification of product conformance, system integrity, and process safety against codified technical standards through sampling, measurement, and audit protocols. Laboratory analysis remains the foundational methodology, involving spectroscopic, chromatographic, and mechanical stress procedures to determine material composition and performance thresholds. Compliance testing commands the largest revenue pool due to recurring regulatory mandates, while non-destructive testing represents the fastest-expanding technology segment as infrastructure aging and aerospace maintenance cycles intensify. Manufacturing firms constitute the dominant customer segment, though regulatory agencies are deepening their outsourcing of surveillance activities to accredited private bodies.
The FDA, EPA, and OSHA frameworks in the United States impose continuous compliance burdens that sustain demand for recurring inspection contracts across food, environmental, and workplace safety domains. EMA pharmaceutical GMP inspections and EU AI Act conformity assessments are creating new certification categories that reshape service provider capabilities. Stakeholders must monitor how divergent national accreditation requirements affect cross-border recognition and contract portability.
Market Dynamics
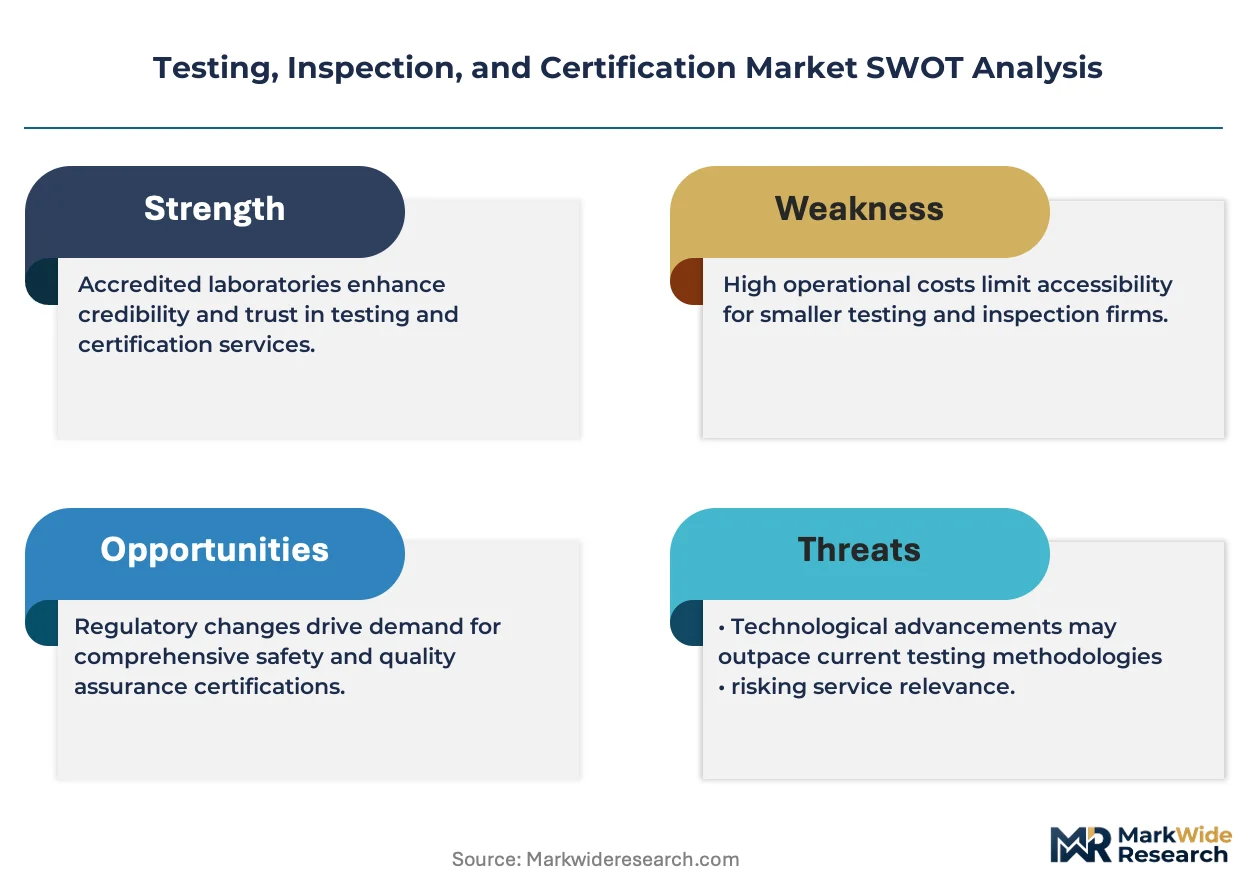
Regulatory fragmentation across jurisdictions is forcing TIC providers to maintain parallel accreditation portfolios, multiplying fixed costs while compressing contract margins for multi-national clients.
Growth Catalysts
- EU AI Act conformity assessments:Artificial intelligence system verification creates new recurring revenue streams for accredited bodies serving European technology deployers.
- Battery testing for automotive electrification:German automotive OEMs require specialized thermal runaway and cycle-life validation for lithium-ion packs entering European supply chains.
- Infrastructure aging in North America:Bridge, pipeline, and power grid deterioration accelerates demand for non-destructive testing services across the United States and Canada.
Market Restraints
- Accreditation cost inflation:ISO 17025 laboratory certification and ILAC mutual recognition maintenance consume 8-12% of annual operating budgets for mid-sized operators.
- Specialized equipment import dependencies:Spectroscopy and chromatography instrument supply concentrates in German and Japanese manufacturing bases, exposing testing firms to currency volatility and extended lead times.
- Regulatory misalignment:Divergent FDA and EMA pharmaceutical testing protocols prevent full test-result portability, forcing redundant validation studies for cross-Atlantic product launches.
Strategic Opportunities
- India's PLI scheme manufacturing expansion:Electronics and pharmaceutical production incentives attract TIC providers to establish local laboratories serving export-bound production.
- Carbon accounting verification:CSRD corporate sustainability reporting mandates in Europe create demand for emissions measurement and assurance services beyond traditional product testing.
- Remote inspection platforms:Drone-based and AR-assisted examination protocols reduce technician dispatch costs while accelerating turnaround for geographically dispersed assets.
Industry Challenges
- PhD-level analytical chemist scarcity:Advanced materials characterization requires specialized expertise that outpaces university pipeline output in multiple European markets.
- Laboratory information management system integration:Legacy paper-based workflows resist digitization, delaying real-time client reporting and automated compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testing, Inspection, and Certification Market |
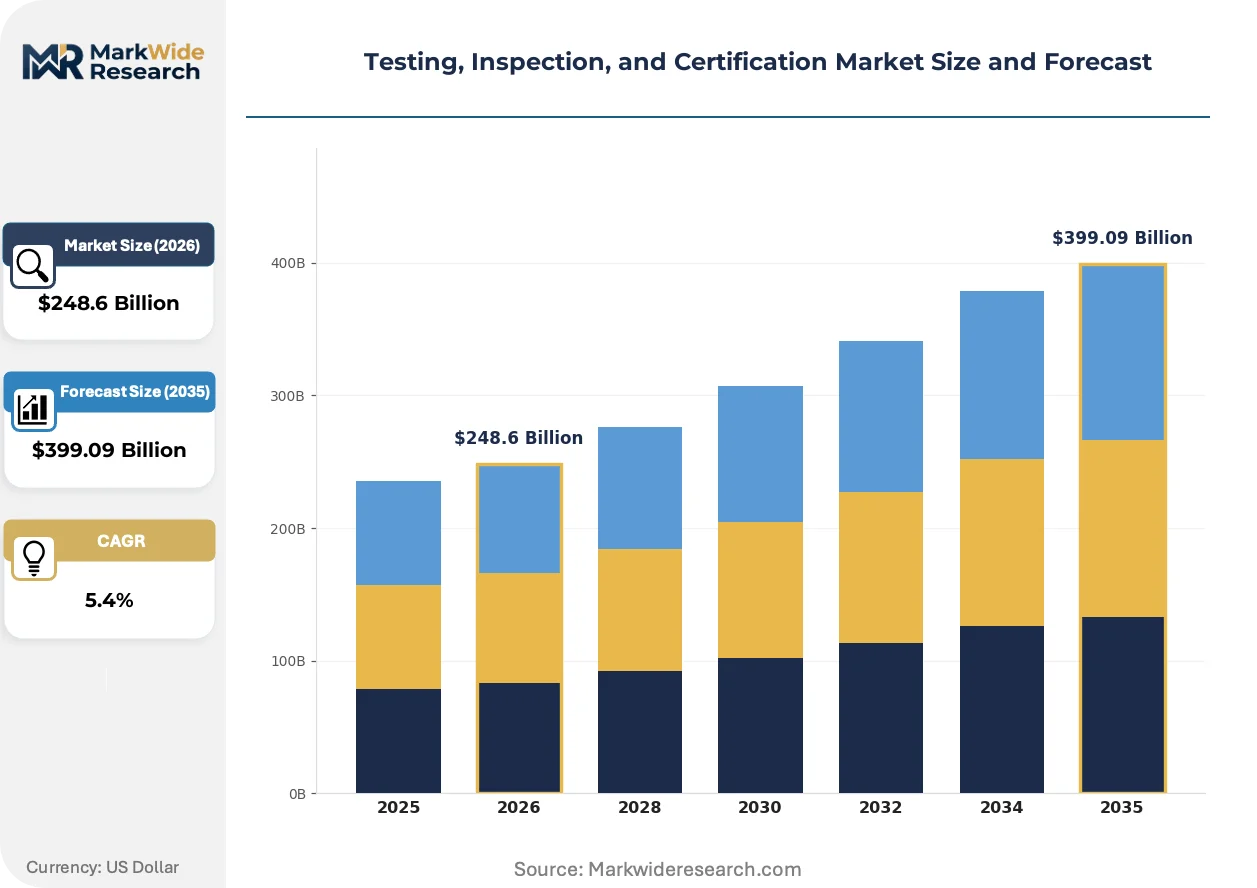
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $399.09 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Compliance Testing, Quality Inspection, Certification Audit, Risk Assessment, Safety Evaluation Industry Application: Consumer Electronics, Aerospace Components, Food Safety, Pharmaceuticals, Construction Materials Testing Technology: Non-Destructive Testing, Destructive Testing, Laboratory Analysis, Field Inspection, Remote Sensing Customer Segment: Manufacturing Firms, Retail Chains, Regulatory Agencies, Research Institutions, Logistics Providers |
| Companies Covered | TÜV SÜD, Eurofins Scientific, SGS, DNV GL, DEKRA, Bureau Veritas, TÜV Rheinland, UL Solutions, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testing, Inspection, and Certification Market Strategic Shifts & Innovations
Artificial intelligence and machine learning applications are penetrating core testing methodologies, compressing analysis timelines while raising questions about algorithmic validation and regulatory acceptance of automated determinations.
Blockchain-based audit trails are digitizing certificate provenance and sample chain-of-custody documentation. Pharmaceutical and food safety clients in Switzerland and Singapore are piloting immutable record systems to satisfy FDA and EFSA traceability requirements. Distributed ledger verification is digitizing cross-border recognition protocols, reducing document fraud risk while accelerating customs clearance for certified goods.
REACH chemical substance restrictions are expanding testing obligations for imported articles entering European single market circulation. ECHA substance of very high concern candidate list growth forces manufacturers to reformulate or commission extensive analytical screening. Textile, electronics, and automotive component suppliers bear the heaviest compliance burden, redirecting procurement toward pre-certified material streams.
Subscription-based testing programs are displacing transactional inspection contracts among recurring-volume manufacturing clients. Tier-one automotive and aerospace suppliers in Germany and Japan are consolidating vendor relationships into multi-year framework agreements with guaranteed capacity allocation. This procurement consolidation favors accredited providers with geographic coverage breadth, pressuring single-site laboratories to affiliate with larger networks or exit contested segments.
Testing, Inspection, and Certification Market Segmentation
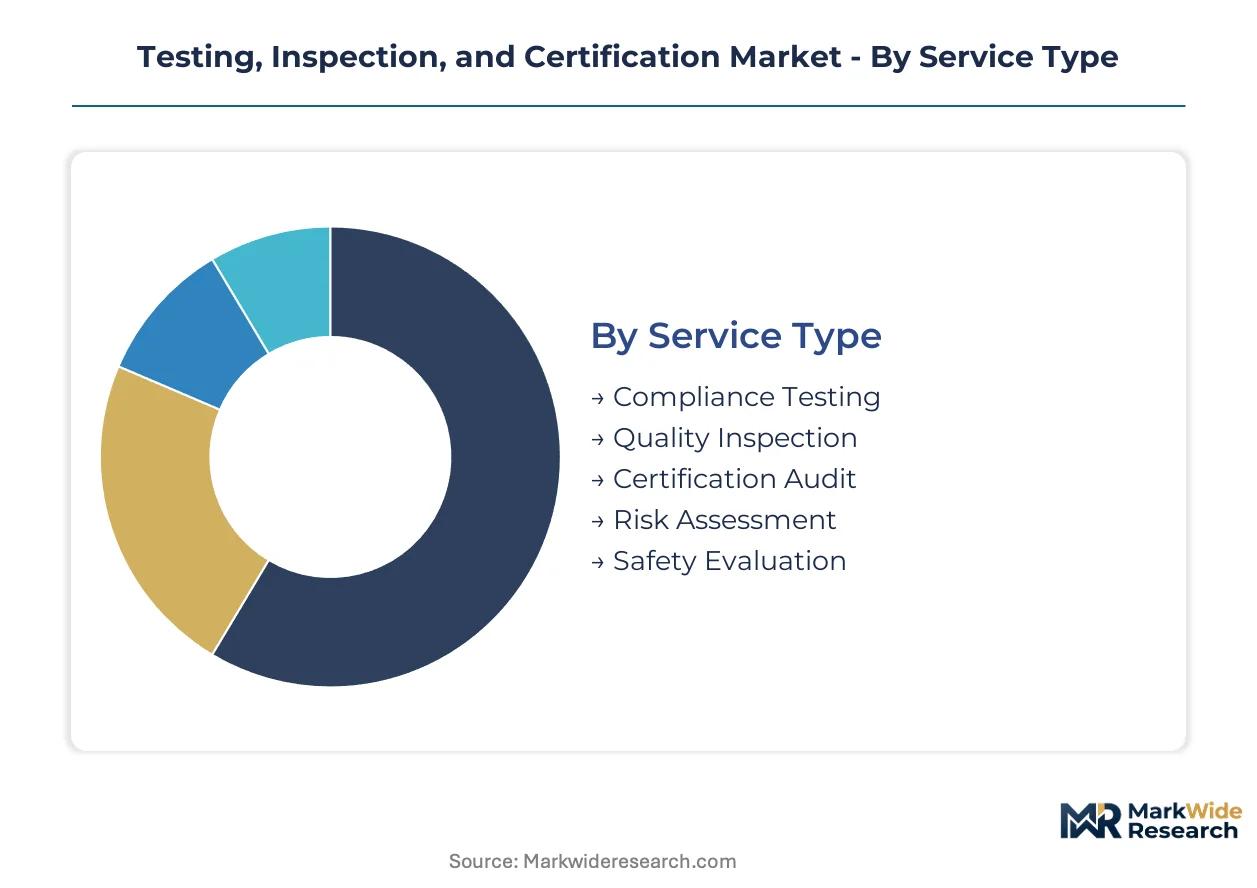
Testing, Inspection, and Certification providers structure service portfolios around distinct technical capabilities, regulatory domains, and client risk profiles. Segmentation clarity enables buyers to match verification requirements with provider specializations and accreditation scope.
Service Type:
Service selection tracks the regulatory intensity and commercial consequence of non-conformance across client supply chains.
- Compliance Testing:Recurring analytical verification against codified standards such as REACH chemical restrictions and FDA food contact material limits. German automotive suppliers commission extensive battery electrolyte and thermal barrier testing to satisfy ECE R100 electric vehicle safety mandates. The dominant share belongs to Compliance Testing, while Risk Assessment is closing the gap fastest.
- Quality Inspection:Lot-by-lot examination of physical dimensions, functional performance, and cosmetic attributes against purchase order specifications. Electronics contract manufacturers in Vietnam and Mexico deploy third-party inspectors to verify component authenticity before surface-mount assembly.
- Certification Audit:Systematic evaluation of management systems against ISO 9001, ISO 14001, and sector-specific frameworks. Maritime classification societies extend audit protocols to cover EU MRV carbon monitoring and IMO 2020 fuel sulfur verification.
- Risk Assessment:Proactive identification of failure modes and operational hazards across product lifecycles and infrastructure assets. Pipeline operators in Alberta and Texas commission external corrosion risk modeling to satisfy PHMSA integrity management rules.
- Safety Evaluation:Hazard characterization and exposure assessment for workplace chemicals, consumer products, and medical devices. French cosmetics manufacturers submit safety dossiers to ANSM for ingredient toxicity review before market placement.
Margin concentration favors recurring compliance contracts over one-off safety evaluations due to accreditation switching costs and regulatory renewal cycles.
Industry Application:
End-use specialization determines laboratory equipment configurations, chemist expertise requirements, and geographic accreditation needs.
- Consumer Electronics:Electromagnetic compatibility, battery safety, and RoHS substance screening for devices entering EU and North American distribution. Shenzhen-based testing laboratories handle pre-shipment verification for 5G infrastructure components bound for European mobile network operators.
- Aerospace Components:Material fatigue, non-destructive inspection, and airworthiness documentation for turbine blades, airframes, and avionics systems. FAA Parts Manufacturer Approval and EASA Design Organization Approval create dual-certification requirements for suppliers serving Boeing and Airbus assembly lines.
- Food Safety:Microbiological screening, allergen detection, and supply chain authenticity verification against FSMA preventive controls and EU 178/2002 general food law. Third-party laboratories in São Paulo and Rotterdam handle mycotoxin analysis for grain imports entering Brazilian and Dutch processing facilities.
- Pharmaceuticals:GMP batch release testing, stability studies, and container closure integrity validation. CDSCO in India and PMDA in Japan impose distinct analytical method requirements that prevent full study portability across jurisdictions.
- Construction Materials:Compressive strength, fire resistance, and environmental emission testing for structural steel, concrete, and engineered wood products. Dubai Municipality mandates third-party verification of cladding fire performance following high-profile tower incidents.
Aerospace and pharmaceuticals command premium pricing due to specialized accreditation requirements, while food safety volumes scale through automated high-throughput screening platforms.
Testing Technology:
Technology selection balances information yield against sample destruction, equipment capital requirements, and field portability needs.
- Non-Destructive Testing:Ultrasonic, radiographic, and eddy current inspection methods that preserve asset integrity during evaluation. Pipeline operators across Alberta and Texas deploy automated ultrasonic corrosion mapping to satisfy PHMSA integrity management timelines without service interruption.
- Destructive Testing:Tensile, impact, and fatigue protocols that consume specimens to determine ultimate performance limits. Automotive OEMs in Stuttgart and Wolfsburg require crash-relevant aluminum extrusion characterization before series production approval.
- Laboratory Analysis:Spectroscopic and chromatographic determination of material composition, purity, and contaminant levels. Swiss pharmaceutical manufacturers rely on Geneva and Basel laboratories for heavy metal and residual solvent quantification under ICH Q3D and Q3C guidelines.
- Field Inspection:On-site examination of installed equipment, infrastructure, and operating facilities. Wind turbine blade inspectors in Denmark and Scotland combine rope access with drone photography to document leading-edge erosion without crane mobilization.
- Remote Sensing:Satellite, aerial, and IoT-enabled monitoring of environmental conditions and asset status. Methane detection contractors serve Permian Basin operators with optical gas imaging to meet EPA New Source Performance Standards.
Laboratory analysis retains the largest revenue base, though non-destructive testing climbs fastest as infrastructure age and predictive maintenance programs expand.
Customer Segment:
Procurement patterns diverge sharply between volume-driven manufacturing accounts and surveillance-oriented regulatory outsourcing.
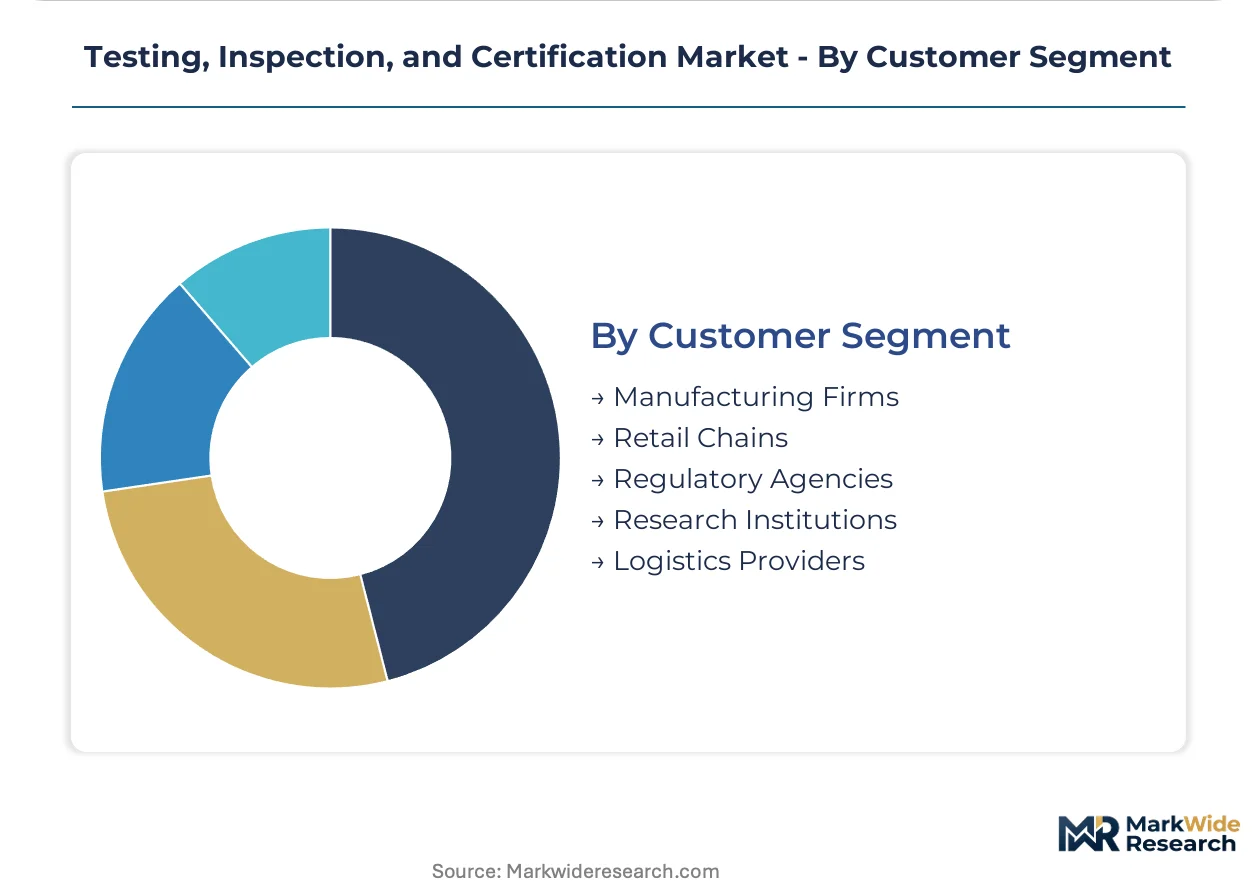
- Manufacturing Firms:OEMs and component suppliers integrating testing into production workflows and supplier qualification protocols. German automotive tier-one suppliers consolidate annual testing spend into multi-year framework agreements with guaranteed laboratory capacity allocation.
- Retail Chains:Private-label importers requiring pre-shipment inspection and supplier audit services for quality assurance and brand protection. Mass-market apparel retailers in Spain and Sweden commission social compliance and chemical testing for Asian textile suppliers.
- Regulatory Agencies:Government bodies outsourcing surveillance inspection, laboratory analysis, and certification audit functions to accredited private providers. Health Canada contracts specialized toxicology laboratories for pesticide residue monitoring in imported produce.
- Research Institutions:Universities and technology centers requiring analytical services beyond internal core facility capabilities. Materials science departments in Singapore and Switzerland outsource electron microscopy and X-ray diffraction for advanced alloy characterization.
- Logistics Providers:Freight forwarders and cold-chain operators verifying cargo condition, documentation compliance, and customs pre-clearance eligibility. Pharmaceutical distributors in Belgium and the Netherlands deploy temperature logger verification for EU GDP-compliant shipments.
Manufacturing firms generate the dominant contract volume, while regulatory agency outsourcing expands fastest as government inspection capacity constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive corridors while North American infrastructure operators absorb premium rates for expedited non-destructive testing. European regulatory complexity sustains margin premiums for multi-accredited providers. Asian manufacturing expansion compresses contract values through volume-driven procurement.
United States
Bridge deterioration and pipeline integrity mandates drive non-destructive testing demand across Texas and Pennsylvania corridors. EPA New Source Performance Standards and OSHA process safety management rules sustain recurring inspection contracts. Houston hosts specialized laboratories serving Permian Basin methane detection and Gulf Coast petrochemical surveillance.
Germany
Automotive electrification and battery system validation command premium testing rates from Stuttgart and Wolfsburg OEMs. EU AI Act conformity assessments and ECE R100 electric vehicle safety mandates create new certification categories. Bavarian industrial clusters anchor specialized thermal runaway testing capacity for lithium-ion supply chains.
China
Electronics manufacturing concentration in Shenzhen and Dongguan generates massive pre-shipment inspection volumes. NMPA pharmaceutical GMP requirements and GB standards compliance sustain domestic laboratory expansion. Yangtze River Delta clusters absorb growing third-party verification demand for export-bound medical devices.
India
PLI scheme manufacturing incentives attract TIC providers to establish local laboratories serving pharmaceutical and electronics exports. CDSCO distinct analytical method requirements prevent full study portability from Western laboratories. Maharashtra and Gujarat industrial corridors concentrate new capacity for export-bound production verification.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks forces parallel accreditation maintenance for cross-channel trade. MHRA pharmaceutical batch release testing and construction product marking rules sustain domestic laboratory demand. Greater Manchester and West Midlands clusters specialize in aerospace component airworthiness documentation.
Testing, Inspection, and Certification Market Key Industry Players
Diversified multi-sector giants and specialized sector anchors split the market into distinct capability tiers. Consolidation pressures narrow independent laboratory networks across Europe and North America. Three archetypes dominate: geographic coverage leaders, sector-specialist anchors, and technology-focused boutiques. M&A activity concentrates among mid-sized operators seeking accreditation portfolio breadth, while strategic partnerships address cross-border recognition gaps.
Within the geographic coverage tier, SGS exemplifies multi-regional accreditation scale, while Bureau Veritas anchors maritime and energy specialization. Intertek Group occupies a position in consumer product safety program intensity. These three represent contrasting strategic postures: breadth-driven network economics, sector-deep technical authority, and high-velocity consumer goods turnaround respectively.
| Leading Market Players |
|---|
| TÜV SÜD |
| Eurofins Scientific |
| SGS |
| DNV GL |
| DEKRA |
| Bureau Veritas |
| TÜV Rheinland |
| UL Solutions |
| Intertek Group |
| Others |
Cost & Logistics Intelligence
Overcapacity in Indian pharmaceutical testing laboratories is compressing contract margins while forcing European providers to emphasize high-complexity analytical services. This utilization asymmetry is reshaping procurement patterns as buyers arbitrage cost-quality trade-offs across accreditation jurisdictions.
Pricing Analysis
The customization-premium spread separates standard ISO 17025 compliance testing from configured-to-order battery safety validation for German automotive OEMs. Subscription-based testing programs dominate recurring manufacturing relationships, while project-based pricing governs one-off safety evaluations. Price differentiation hinges on certification level (EASA Part 145 vs. basic ISO accreditation) and geographic delivery cost (field inspection dispatch premiums). Cost compression in high-volume electronics screening is intensifying because Asian manufacturing expansion concentrates procurement power. Retail chains exhibit highest price sensitivity, while aerospace suppliers accept premium rates for dual FAA-EASA accreditation coverage.
Supply Chain Analysis
Export-control regimes limiting spectroscopy and chromatography instrument flows from German and Japanese manufacturing bases are extending equipment lead times for mid-sized operators. Supply concentrates in Germany, Japan, and the United States for advanced analytical instrumentation. Raw material dependencies encompass helium for chromatography carrier gas, high-purity reference standards, and rare-earth magnets for mass spectrometry components. Single-source vulnerability runs through Japanese precision optics suppliers. Distribution runs through manufacturer-authorized service networks with regional calibration laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as infrastructure aging across North America and automotive electrification in Germany restore utilization rates. Capital expenditure cycles in these end-use sectors are driving the upturn.
For Market Incumbents: Insulate accreditation portfolios against regulatory fragmentation by maintaining parallel FDA and EMA pharmaceutical testing capabilities. Prioritize capacity addition in Maharashtra and Gujarat industrial corridors to capture India's PLI scheme manufacturing expansion. Vertical integration into remote inspection platform development addresses technician scarcity and protects margin structure against drone-based inspection startups.
For New Entrants and Emerging Players: Southeast Asian pharmaceutical manufacturing corridors represent the most penetrable geography for GMP laboratory establishment. Target carbon accounting verification services for CSRD-mandated European corporate clients as a white-space entry point. Pursue partnership-based go-to-market models with established logistics providers to bypass accreditation timeline barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-accredited providers serving German automotive electrification supply chains. Long-term viability favors laboratories with demonstrated ILAC mutual recognition maintenance and specialized battery thermal runaway testing capabilities. Watch for inflection signals in India's CDSCO inspection outsourcing tenders as indicators of regulatory agency privatization acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Portfolio Expansion | Parallel FDA-EMA coverage captures cross-Atlantic pharmaceutical launch volumes. |
| Remote Inspection Platform Deployment | Drone-based protocols reduce PHMSA pipeline inspection dispatch costs. |
| Carbon Accounting Verification Service Launch | CSRD mandates in Europe create recurring emissions assurance revenue streams. |
| Laboratory Capacity Addition in India | PLI scheme electronics and pharmaceutical production incentives sustain export-bound testing demand. |
| Blockchain-Based Audit Trail Integration | Immutable record systems satisfy FDA and EFSA traceability requirements for pharmaceutical clients. |
Research Approach
Desk research of regulatory filing databases, accreditation body directories, and customs trade statistics preceded structured interviews with laboratory operations directors, regulatory affairs managers at pharmaceutical OEMs, third-party inspection procurement leads, and certification body technical assessors. Primary fieldwork combined telephone interviews and facility observation visits with secondary validation against ISO 17025 audit documentation and ILAC mutual recognition agreements. Bottom-up testing volume estimates triangulated against top-down market sizing from accreditation body membership data.
The analytical framework held regulatory implementation timelines and accreditation cost structures fixed across the modeling period while varying manufacturing output assumptions by end-use sector. Segmentation dimensions modeled include service type, testing technology, industry application, and regional regulatory cluster. CAGRs were derived from regression analysis of historical testing volume against manufacturing output indices and regulatory mandate expansion schedules. Battery testing demand curves and infrastructure age distributions served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-subsidized Chinese laboratories would shift outcomes. Material shifts in EU AI Act enforcement intensity or REACH substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Food and Beverage Air Filtration Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Food Certification Market