
 Bar Inspection System Market | 2026-2036
Bar Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
Bar Inspection System Market Outlook
Software-defined analytics subscription tiers is broadening what inspection vendors monetize beyond hardware placement. Baker Hughes Company leverages its digital industrial platform to bundle predictive maintenance algorithms with ultrasonic bar inspection hardware. Innerspec Technologies anchors its competitive stance in electromagnetic acoustic transducer specialization for high-temperature bar lines. Mettler-Toledo dominates precision weighing and dimensional verification niches where pharmaceutical and food-grade bar cleanliness intersect with metrology requirements.
A bar inspection system comprises sensor arrays, mechanical handling equipment, and analysis software engineered to detect surface cracks, dimensional deviations, internal voids, and material inconsistencies in metal bars and billets, typically operating at throughput speeds of meters per second in hot-rolling environments. Its primary industrial purpose is to prevent downstream machining failures, liability claims, and structural collapses by intercepting defective material before further value is added. Inline inspection systems command the largest installed base because continuous production economics favor real-time rejection over batch sampling delays. Ultrasonic testing captures the fastest expansion trajectory as phased-array techniques replace conventional piezoelectric methods for internal defect resolution.
The US FDA and FAA enforce material traceability and defect-documentation standards that propagate upstream to bar suppliers serving medical implant and airframe fastener applications. Germany's KBA and the EU's CE marking framework under the Machinery Directive mandate functional safety certifications for automated inspection equipment deployed in automotive supply chains. Stakeholders must monitor how AI-driven defect classification standards from ISO and IEC evolve, because algorithmic auditability will soon determine market access as decisively as physical measurement accuracy.
Market Dynamics
The transition from manual gauging to automated inline inspection is compressing acceptance cycles for steel and aluminum bars destined for safety-critical automotive and aerospace components.
Growth Catalysts
- ISO 9001 defect-liability tightening:Certification bodies in Germany and the United States now mandate documented traceability for every bar lot, forcing foundries to install sensor arrays that log dimensional and surface data automatically.
- Automotive OEM zero-defect mandates:Crankshaft and camshaft producers in Stuttgart and Wolfsburg reject entire shipments unless suppliers provide real-time inspection certificates generated during hot-rolling operations.
- Phased-array ultrasonic testing:This technique replaces conventional piezoelectric methods, delivering internal void resolution at throughput speeds exceeding three meters per second on continuous casting lines.
Market Restraints
- High-purity piezoelectric crystal supply:Sourcing constraints for lead zirconate titanate elements concentrate among Japanese and Chinese specialty ceramic producers, creating input cost volatility for transducer manufacturers.
- Electromagnetic acoustic transducer temperature limits:Current EMAT designs degrade above six hundred degrees Celsius, excluding their deployment from the hottest zones of bar finishing mills where defect formation rates peak.
- CE marking functional safety compliance:The EU Machinery Directive's third-party certification requirements add fourteen to eighteen months to equipment validation timelines for vendors targeting automotive supply chains.
Strategic Opportunities
- Indian specialty steel expansion:The country's PLI scheme for high-grade automotive steel creates virgin demand for inspection systems among domestic mills previously serving construction-grade markets exclusively.
- Medical implant bar traceability:FDA material documentation standards for orthopedic fasteners and spinal rods propagate upstream to bar suppliers, opening premium pricing tiers for certified-clean production lines.
- AI-driven defect classification convergence:Machine vision algorithms fused with ultrasonic signal processing enable predictive rejection before physical handling, reducing scrap rates in continuous casting operations.
Industry Challenges
- Phased-array calibration technician scarcity:The specialized skill set combining ultrasonics physics with software-defined instrumentation outpaces vocational training output in Midwestern US manufacturing corridors.
- Legacy mill mechanical integration:Retrofitting sensor gantries onto fifty-year-old rolling lines requires custom mechanical handling designs that extend commissioning timelines and inflate project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bar Inspection System Market |
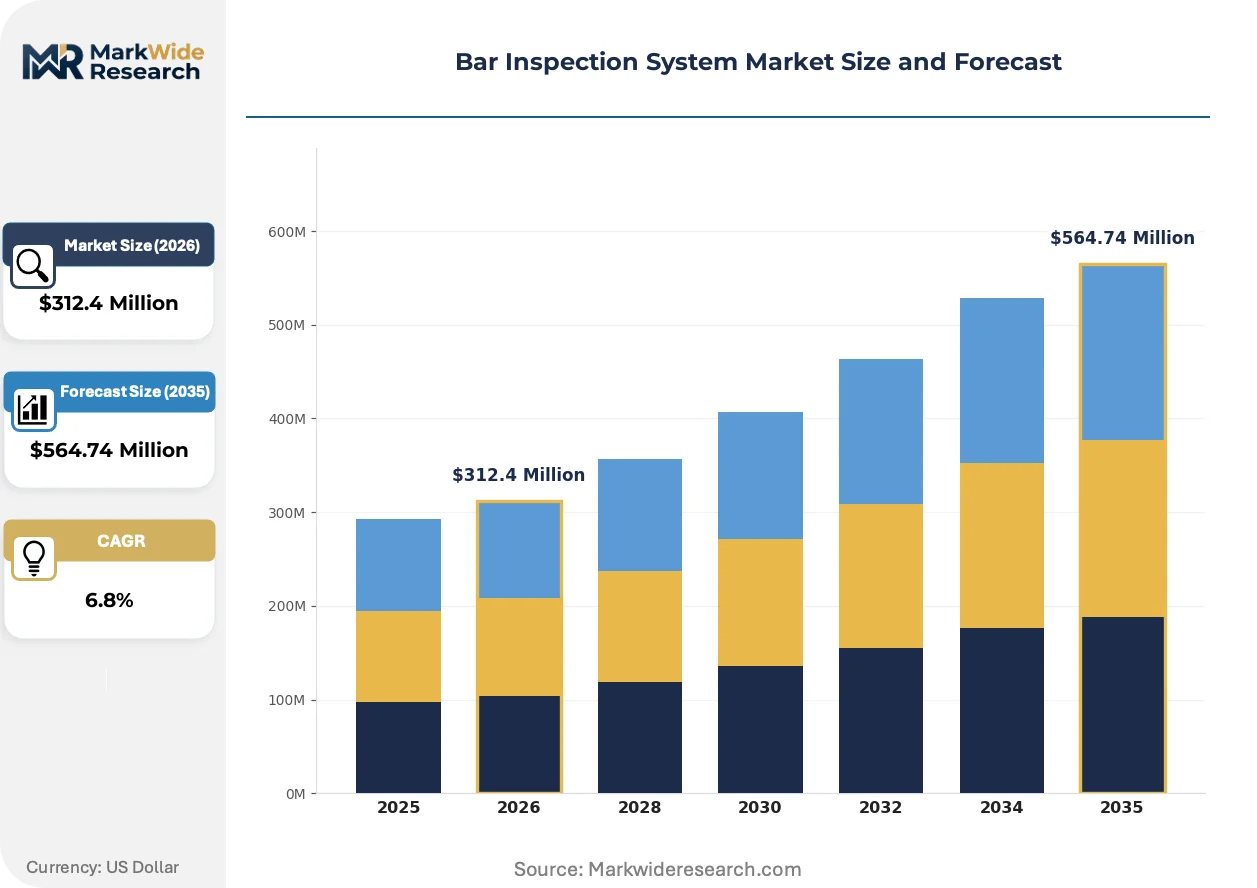
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
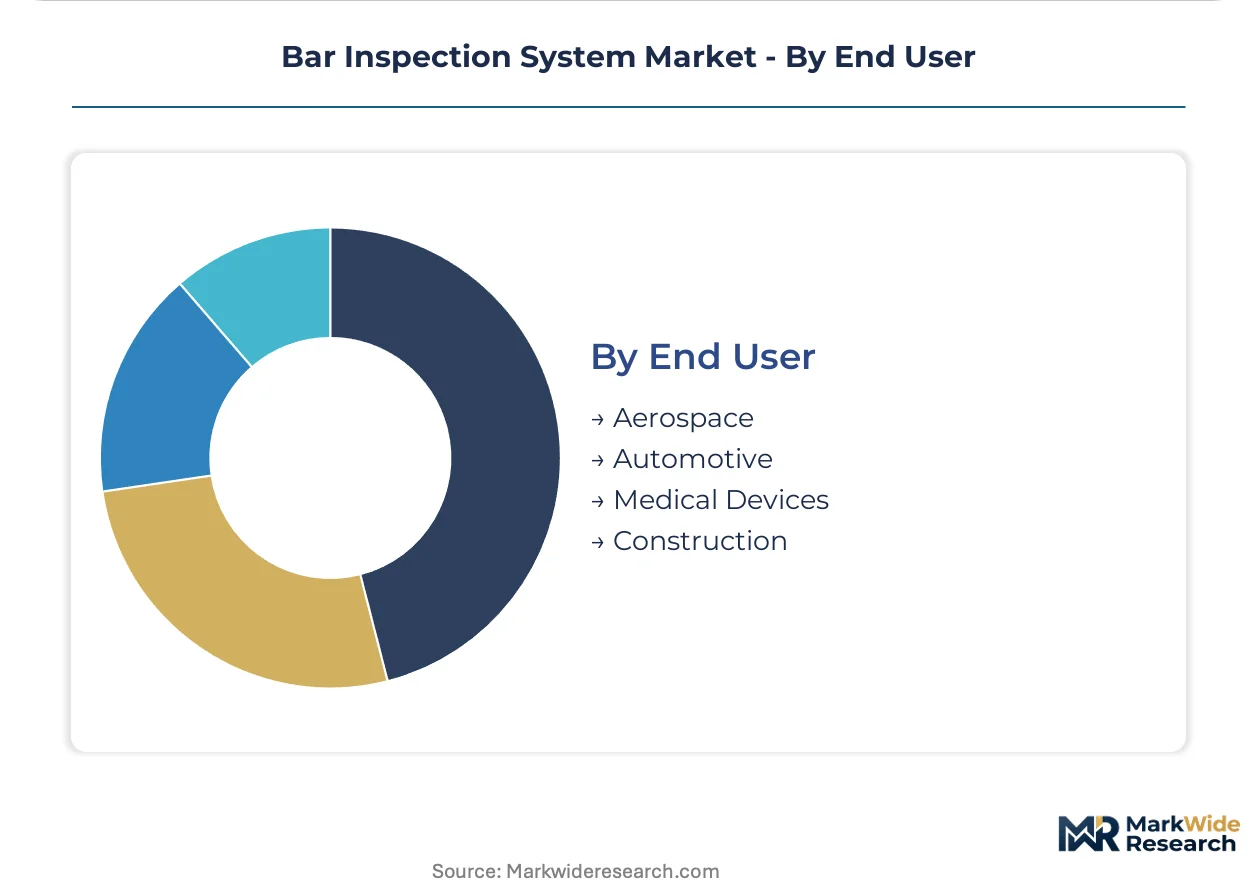
| Segmentation | Product Type: Fixed Inspection Systems, Portable Inspection Systems, Inline Inspection Systems, Manual Inspection Tools Technology: Laser Measurement, Optical Inspection, X-Ray Inspection, Ultrasonic Testing Application: Manufacturing Quality Control, Research & Development, Product Testing, Maintenance Operations End User: Aerospace, Automotive, Medical Devices, Construction |
| Companies Covered | Olympus Corporation, Baker Hughes Company, Blue Star Limited, Namicon Testing, Salem Design & Manufacturing, Structural Diagnostics Inc., Innerspec Technologies, Epsilon NDT, Mettler-Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bar Inspection System Market Strategic Shifts
Software-defined analytics platforms are transforming how inspection vendors monetize hardware deployments, shifting revenue toward recurring algorithm subscriptions and predictive maintenance bundles.
Phased-array ultrasonic testing is electrifying competitive positioning in high-throughput bar inspection. This technology steers multiple ultrasonic beams electronically without mechanical scanning, enabling complete volumetric coverage at speeds manual methods cannot match. European automotive tier-one suppliers now specify phased-array certification as a qualification gate for crankshaft material contracts. The technology is electrifying vendor differentiation by collapsing the trade-off between inspection depth and line speed that constrained prior generations.
REACH substance restrictions on lead-containing piezoelectric materials are forcing transducer redesigns across the European supply base. The regulation's candidate list expansion threatens exemptions previously enjoyed by industrial NDT equipment, compelling manufacturers to accelerate lead-free ceramic formulations. German inspection system integrators report twelve to eighteen month qualification delays as they validate alternative sensing materials against established performance baselines.
Buyer consolidation among North American steel distributors is compressing equipment procurement cycles and elevating total-cost-of-ownership criteria over upfront capital expenditure. Large distributors now demand cloud-connected inspection systems that aggregate performance data across multiple mill sources, replacing siloed quality departments. This pattern concentrates most visibly in the Great Lakes region, where integrated distributors serve Detroit-area automotive stamping plants with unified material certification portals.
Bar Inspection System Market Segmentation

Bar inspection system procurement decisions pivot on throughput requirements, defect detection depth, and regulatory documentation burdens. Each segment carries distinct certification obligations and integration complexities that shape vendor selection and total cost of ownership.
Product Type:
ISO 9001 and CE marking under the EU Machinery Directive impose divergent validation timelines across installation configurations, with inline systems facing the most stringent functional safety audits.
- Inline Inspection Systems:Permanently integrated sensor arrays operate at hot-rolling line speeds exceeding three meters per second. German automotive crankshaft suppliers in Stuttgart and Wolfsburg mandate these systems for zero-defect material certificates generated during continuous casting.
- Fixed Inspection Systems:Stationary gantry installations at bar finishing mill exits perform dimensional verification and surface crack detection on cooled material. North American steel distributors in the Great Lakes region specify cloud-connected variants that aggregate quality data across multiple mill sources.
- Portable Inspection Systems:Battery-powered ultrasonic and electromagnetic units enable spot-checking at remote forging operations or customer receiving docks.
- Manual Inspection Tools:Handheld calipers, bore gauges, and visual inspection kits persist in low-volume specialty alloy production where automation economics fail.
Leading the category by volume: Inline Inspection Systems. Growing fastest: Fixed Inspection Systems.
Technology:
Cost tier stratification separates premium volumetric methods from economy surface techniques, with phased-array ultrasonic systems commanding three to five times the hardware investment of laser profiling.
- Ultrasonic Testing:Phased-array techniques electronically steer multiple beams without mechanical scanning, delivering complete internal void resolution. European automotive tier-one suppliers now specify this certification as a qualification gate for crankshaft material contracts.
- Laser Measurement:Triangulation and time-of-flight systems capture sub-micron dimensional deviations on cold bars at throughput speeds matching rolling mill outputs. Mettler-Toledo dominates pharmaceutical and food-grade applications where cleanliness intersects with precision metrology.
- X-Ray Inspection:Computed tomography systems penetrate high-density superalloy bars for aerospace fastener applications requiring full volumetric documentation.
- Optical Inspection:Machine vision arrays detect surface cracks, scale patterns, and cosmetic defects through high-speed line-scan cameras.
Dominating revenue share: Ultrasonic Testing. Expanding most quickly: Laser Measurement.
Application:
Customer maturity separates preventive quality investment from reactive troubleshooting, with integrated mills funding real-time systems while service centers defer to periodic testing.
- Manufacturing Quality Control:Inline sensor networks intercept defective bars before downstream machining adds value. FDA material traceability standards for medical implants propagate upstream to require automated documentation at this stage.
- Product Testing:Destructive and non-destructive validation of sample lots for customer certification packages. Baker Hughes bundles predictive maintenance algorithms with testing hardware through digital industrial platform subscriptions.
- Research & Development:Laboratory-grade phased-array and X-ray systems support new alloy formulation and process parameter optimization.
- Maintenance Operations:Periodic inspection of in-service structural bars in bridges, cranes, and heavy equipment using portable electromagnetic and ultrasonic methods.
Capturing largest installed base: Manufacturing Quality Control. Gaining share fastest: Product Testing.
End User:
Margin structure across end-use sectors correlates with liability exposure and defect consequence severity, driving premium pricing for aerospace and medical certification tiers.
- Automotive:Crankshaft and camshaft producers enforce zero-defect bar supply through real-time inspection certificate requirements during hot-rolling operations. KBA functional safety certifications govern equipment deployed in German automotive supply chains.
- Aerospace:Airframe fastener and landing gear applications demand full material traceability under FAA documentation standards. X-ray and phased-array ultrasonic systems dominate this segment for internal defect resolution in titanium and nickel superalloys.
- Medical Devices:Orthopedic fasteners, spinal rods, and surgical instruments require FDA-mandated material cleanliness documentation. Mettler-Toledo precision weighing systems intersect with pharmaceutical-grade bar production requirements.
- Construction:Structural rebar and beam applications utilize lower-cost laser and optical systems for dimensional compliance with building codes.
Commanding highest average selling prices: Aerospace. Expanding most quickly: Medical Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global demand for zero-defect bar inspection systems, where automotive OEMs enforce real-time certification requirements during hot-rolling operations for crankshaft and camshaft production.
Germany
KBA functional safety certifications govern equipment validation timelines for automotive supply chains, while Stuttgart and Wolfsburg enforce zero-defect mandates through real-time inspection certificates. The EU Machinery Directive's CE marking requirements add fourteen to eighteen months to equipment deployment schedules.
United States
FAA material traceability standards propagate upstream to bar suppliers serving airframe fastener applications, and FDA documentation requirements govern orthopedic implant bar production. Great Lakes steel distributors demand cloud-connected systems aggregating quality data across multiple mill sources for Detroit-area automotive stamping plants.
India
The PLI scheme for high-grade automotive steel creates virgin demand among domestic mills previously serving construction-grade markets exclusively. BIS standards for specialty steel grades accelerate inspection system procurement in Maharashtra and Gujarat manufacturing corridors.
China
MIIT industrial upgrading programs prioritize automated quality control in steel production, while GB standards for structural materials tighten defect documentation requirements. Yangtze River Delta steel mills deploy phased-array ultrasonic systems for high-throughput continuous casting lines.
Japan
METI manufacturing competitiveness initiatives subsidize smart factory investments including inline inspection automation. JIS standards for automotive steel grades drive adoption in Nagoya and Osaka industrial clusters serving precision component manufacturers.
Bar Inspection System Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the bar inspection system market. The vendor base separates into integrated industrial conglomerates with digital platforms, specialized NDT technology developers, and precision metrology equipment manufacturers. Strategic archetypes include platform bundlers combining hardware with predictive analytics subscriptions, transducer specialists advancing electromagnetic acoustic and phased-array ultrasonic methods, and precision weighing leaders intersecting pharmaceutical-grade cleanliness requirements. Dominant competitive moves encompass software-defined analytics tier expansion and strategic partnerships bundling maintenance algorithms with hardware deployment.
Within the integrated industrial tier, Baker Hughes Company and Olympus Corporation exemplify platform-scale positioning through digital industrial ecosystems. Among specialized NDT developers, Innerspec Technologies occupies a position anchored in electromagnetic acoustic transducer specialization for high-temperature applications. On the precision metrology vector, Mettler-Toledo represents the intersection of pharmaceutical-grade cleanliness standards with dimensional verification requirements. These three archetypes illustrate how competitive differentiation separates platform bundlers, sensing specialists, and precision equipment leaders across distinct certification and application tiers.
| Leading Market Players |
|---|
| Olympus Corporation |
| Baker Hughes Company |
| Blue Star Limited |
| Namicon Testing |
| Salem Design & Manufacturing |
| Structural Diagnostics Inc. |
| Innerspec Technologies |
| Epsilon NDT |
| Mettler-Toledo |
| Others |
Value Chain & Pricing Dynamics
Lead zirconate titanate price volatility cascades through transducer manufacturing into three-tier pricing structures across premium, standard, and economy levels, with Japanese and Chinese specialty ceramic producers concentrating supply leverage over European system integrators facing REACH substance restrictions.
Pricing Analysis
Cost-down pressure on mid-tier hardware accelerates because automotive OEMs bundle predictive analytics subscriptions with equipment procurement, compressing standalone system margins. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Price differentiation hinges on phased-array calibration capability and cloud-connectivity features. Service centers and construction-grade distributors exhibit highest price sensitivity, while aerospace and medical device manufacturers accept premium positioning for FDA and FAA documentation compliance.
Supply Chain Analysis
Refurbishment flows for legacy piezoelectric transducers create secondary component channels that moderate raw material cost spikes for budget-tier system assemblers. Manufacturing concentrates in Germany, Japan, and the United States for precision metrology equipment, while China dominates electromagnetic acoustic transducer component fabrication. The supply chain draws from high-purity piezoelectric crystals, precision optical sensors, and specialized high-temperature alloys. Single-source vulnerability concentrates in Japanese lead zirconate titanate suppliers. Distribution runs through direct OEM relationships for inline systems and regional distributor networks for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into transducer manufacturing and predictive algorithm development is accelerating as vendors seek margin defense against software-defined analytics commoditization.
For Market Incumbents: Extend cloud-platform subscription tiers to capture recurring revenue from installed hardware bases, insulating against phased-array calibration technician scarcity that threatens service delivery quality. Deepen captive supply of lead-free piezoelectric formulations to preempt REACH restriction compliance failures. Prioritize certification investment in KBA functional safety and FDA material traceability tiers to maintain automotive and medical device pricing power. For New Entrants and Emerging Players: Indian specialty steel mills upgrading under PLI scheme incentives represent the most penetrable buyer archetype, with virgin demand for inspection systems among construction-grade producers entering automotive supply chains. Target cloud-connected fixed inspection systems for Great Lakes steel distributors consolidating procurement around unified quality data portals. Pursue partnership-based go-to-market models with established European system integrators to bypass eighteen-month CE marking validation timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor electromagnetic acoustic transducer specialists in Germany and Japan with validated high-temperature designs, as automotive OEM consolidation pressures smaller NDT technology developers. Long-term viability centers on algorithmic auditability capabilities under evolving ISO and IEC AI-driven defect classification standards. Monitor BIS standard enforcement in Maharashtra and Gujarat manufacturing corridors as inflection indicator for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Analytics Platform Launch | Baker Hughes leverages digital industrial ecosystems to bundle predictive maintenance with ultrasonic hardware subscriptions. |
| Lead-Free Transducer Formulation Investment | German inspection system integrators accelerate alternative ceramic validation to preempt REACH candidate list expansion. |
| Cloud-Connected Fixed System Deployment | Great Lakes steel distributors aggregate multi-source quality data for Detroit-area automotive stamping plant certification. |
| Phased-Array Ultrasonic Capability Acquisition | European automotive tier-one suppliers specify this certification as qualification gate for crankshaft material contracts. |
| Indian PLI Scheme Market Entry | Domestic mills in Maharashtra and Gujarat corridors upgrade from construction-grade to high-grade automotive steel production. |
Study Parameters
Multi-period observation of ISO 9001 certification timelines, REACH regulatory amendment trajectories, and automotive OEM supplier mandate evolutions anchored the trend analysis, supplemented by interviews with maintenance directors at North American steel mills, procurement leads at German automotive tier-one suppliers, NDT calibration technicians in Midwestern US manufacturing corridors, and regulatory affairs specialists at FDA-registered medical device bar suppliers. Secondary validation drew from SEC 10-K filings of listed industrial equipment manufacturers, BIS standard publication records, KBA functional safety certification databases, and customs trade data for piezoelectric ceramic imports. Bottom-up equipment deployment counts triangulated against top-down market sizing from vendor revenue disclosures.
Input-output matrices modeled sensor array shipments, software subscription attach rates, and service revenue streams across product type, technology, application, and end user dimensions throughout the forecast period. CAGRs derived from regression analysis of historical installation growth against automotive production forecasts and steel capacity expansion announcements. Industry-specific inputs included phased-array ultrasonic adoption curves, cloud-connectivity penetration in distributor procurement specifications, and AI-driven defect classification standard development timelines from ISO and IEC working groups.
Revisions become necessary when REACH substance restriction timelines accelerate, FAA material traceability standards expand to additional fastener categories, or Indian PLI scheme incentive disbursement delays materialize. Practitioners should monitor KBA functional safety certification queue lengths, lead zirconate titanate spot price movements, and automotive OEM zero-defect mandate geographic expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Food Irradiation Market